
 Global Battery Grade Lithium Hydroxide Market | 2026-2036
Global Battery Grade Lithium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battery Grade Lithium Hydroxide Market Analysis
Australia is reconfiguring its lithium hydroxide conversion capacity through spodumene concentrate upgrades at Kwinana and Kemerton. Albemarle Corporation leverages vertical integration from Nevada brine to Asian cathode customers. Ganfeng Lithium Group anchors its position through captive spodumene offtake from Mount Marion and Pilgangoora. SQM competes with Atacama-derived carbonate feedstock routed through Chilean conversion assets.
Battery grade lithium hydroxide denotes material exceeding 56.5% lithium content with strict impurity ceilings on sodium, potassium, calcium, and iron, produced via caustic soda conversion of spodumene or electrolysis of lithium chloride brines for high-nickel NCM and NCA cathode synthesis. The Electric Vehicles application dominates volume offtake as automakers specify hydroxide-compatible cathodes for extended-range battery packs. Energy Storage Systems represents the fastest-expanding demand pool as grid-scale deployments shift toward higher-energy-density chemistries requiring hydroxide-derived precursors.
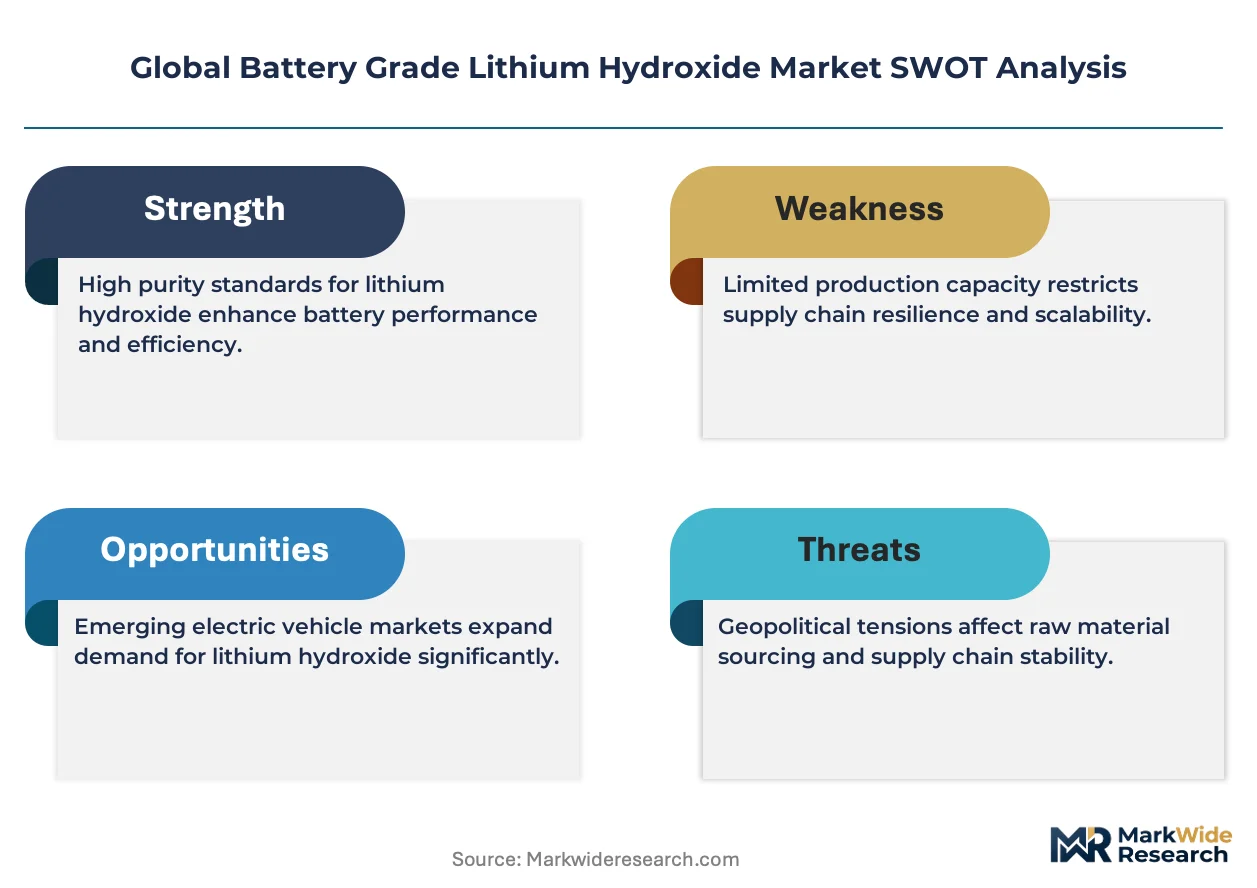
The EU Battery Regulation mandates recycled content disclosures and carbon footprint declarations that reshape qualification criteria for European automotive supply chains. China's MIIT enforces GB standards on battery material purity that filter export eligibility from domestic refiners. The US IRA domestic content thresholds redirect procurement toward North American conversion capacity. Stakeholders must monitor cathode chemistry roadmaps and offtake contract structures as high-nickel formulations face cobalt substitution pressures and solid-state timelines.
Market Dynamics
High-nickel cathode chemistry roadmaps are compressing qualification timelines for battery-grade lithium hydroxide as automakers accelerate 800-volt platform deployments. This specification tightening is forcing spodumene-to-hydroxide conversion assets to demonstrate impurity control at pilot scale before offtake execution.
Growth Catalysts
- EU Battery Regulation carbon footprint mandates:European automakers now require supply-chain disclosure for imported cathode materials, creating procurement preference for hydroxide with documented Scope 3 emissions.
- South Korea's cathode manufacturing corridor:Hyundai and Samsung SDI are expanding NCM811 and NCA precursor capacity, concentrating demand for battery-grade material in Gwangyang and Ochang industrial zones.
- Direct shipping ore-to-hydroxide pathways:Australian spodumene producers are commissioning integrated conversion plants at port locations, compressing logistics costs for Asian cathode makers.
Market Restraints
- Caustic soda input cost volatility:Conversion economics depend on chlor-alkali byproduct pricing, which fluctuates with European energy costs and Chinese export quotas.
- Atacama brine concentration:SQM and Albemarle control carbonate-derived hydroxide feedstock from Chile, creating supply-side dependency for non-integrated cathode producers.
- Technical limitation in impurity removal:Calcium and magnesium separation during spodumene acid roasting requires proprietary solvent extraction circuits that few refiners have perfected.
Strategic Opportunities
- US IRA domestic content thresholds:North American conversion capacity qualifies for electric vehicle tax credit passthrough, incentivizing greenfield hydroxide plants in Nevada and North Carolina.
- Energy Storage Systems density requirements:Grid-scale battery deployments are specifying NCM622 and higher-nickel chemistries for containerized systems, opening a parallel demand channel beyond automotive.
- Solid-state electrolyte compatibility:Sulfide-based solid-state prototypes require ultra-low moisture hydroxide specifications that incumbent carbonate routes struggle to meet.
Industry Challenges
- Process engineer scarcity:Hydrometallurgical expertise for lithium purification is concentrated among a small cohort of specialists with brine or nickel-cobalt experience.
- Qualification timeline compression:Cathode makers now demand 18-month sample-to-contract cycles versus historical 36-month windows, straining pilot plant throughput.
- Feedstock quality variance:Spodumene concentrate grades from African and Australian hard-rock mines fluctuate in iron and tantalum content, disrupting continuous conversion operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battery Grade Lithium Hydroxide Market |
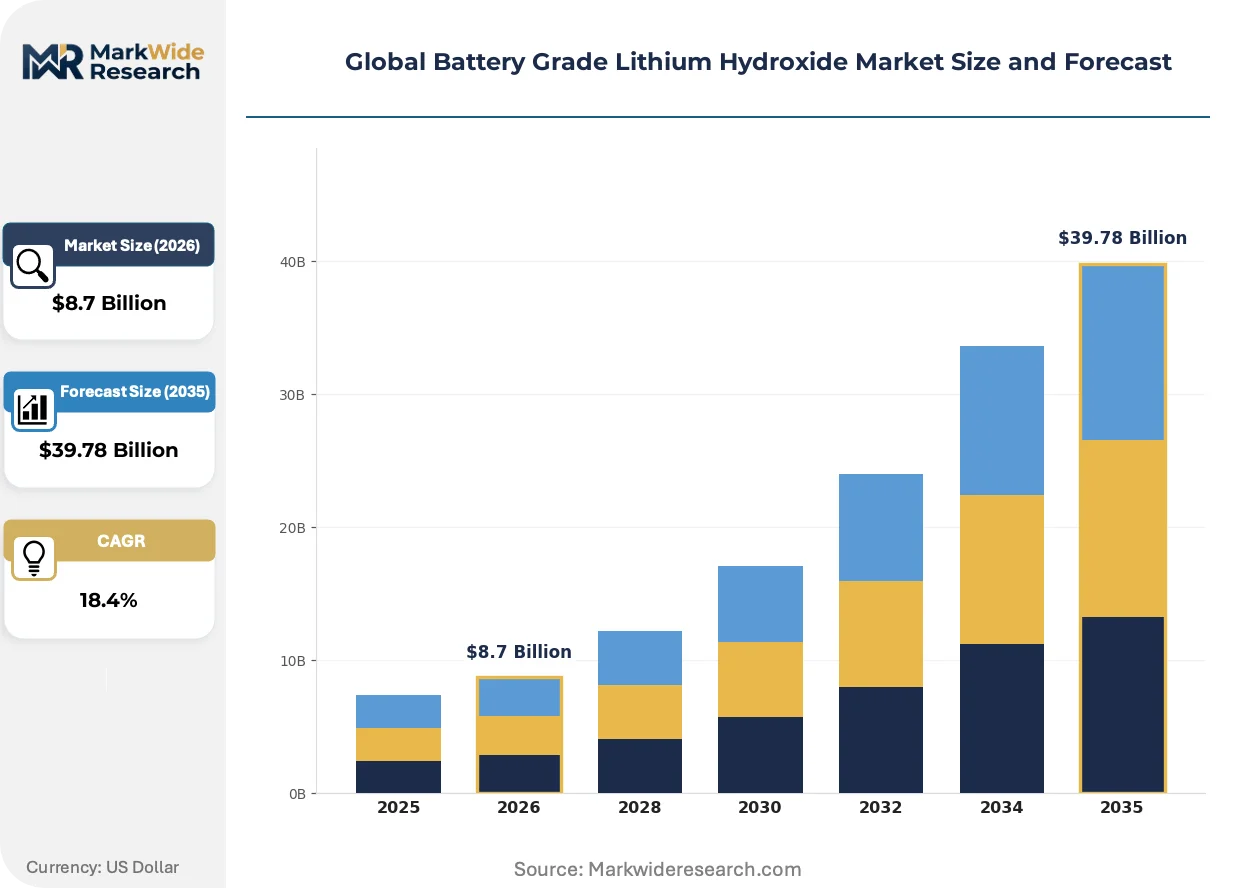
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Battery Grade, Technical Grade, Pharmaceutical Grade Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Aerospace End User: Automotive Manufacturers, Electronics Producers, Renewable Energy Firms, Chemical Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Albemarle Corporation, Ganfeng Lithium Group, Sociedad Química y Minera de Chile (SQM), Tianqi Lithium Corporation, Arcadium Lithium, Mineral Resources Limited, Nemaska Lithium, AMG Critical Materials, Pilbara Minerals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battery Grade Lithium Hydroxide Market Emerging Trajectories
Conversion technology and cathode specification standards are converging faster than asset deployment cycles, creating capability gaps between announced capacity and operational qualification. Refiners must now engineer for chemistry roadmaps that remain unsettled.
Direct acid leach of spodumene without sulfuric acid roasting is hybridizing the traditional conversion flowsheet, eliminating calcination energy intensity. Korean cathode makers are piloting this route for hydroxide destined for NCM9½½ cells. The process is compressing capital intensity for new entrants while forcing incumbent roasters to defend their cost positions through scale.
China's MIIT is enforcing revised GB/T 26008 purity standards that tighten sodium and potassium ceilings below 50 ppm for battery-grade material. Domestic refiners are retrofitting crystallization circuits to meet export eligibility. European automotive supply chains are responding by dual-sourcing from Chinese and Australian conversion assets to manage qualification risk.
Automakers are consolidating cathode procurement through direct offtake contracts with hydroxide refiners, bypassing traditional trading house intermediaries. This disintermediation is most visible in German OEM supply chains, where Volkswagen and BMW have established direct supply relationships with Australian conversion projects. The model is compressing margin capture for traders while transferring price volatility risk to vehicle manufacturers.
Global Battery Grade Lithium Hydroxide Market Segmentation
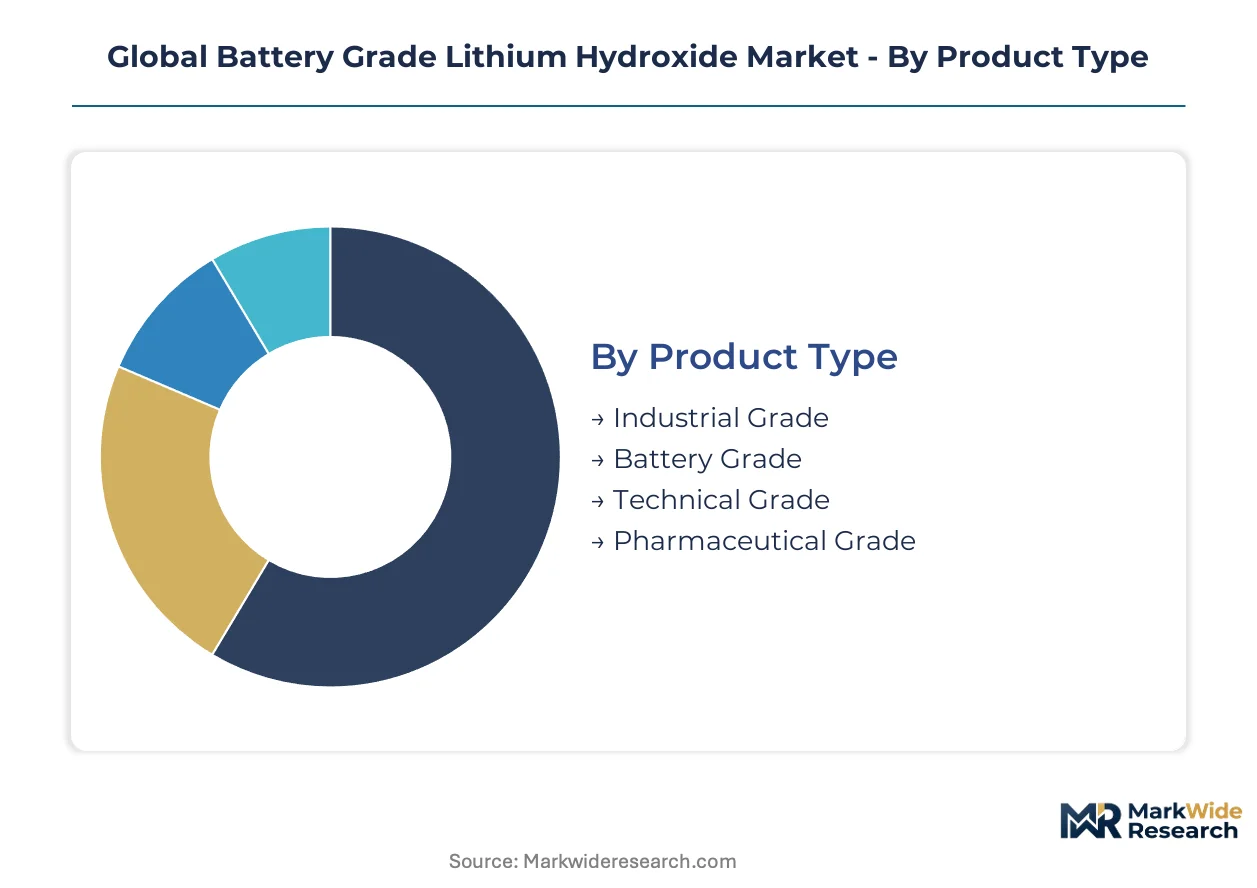
Segmentation in battery-grade lithium hydroxide tracks specification tiers, cathode chemistry compatibility, and procurement channel structures. Each dimension reveals distinct margin profiles and qualification barriers that shape competitive positioning across the value chain.
Product Type:
Cost tier differentiation separates commodity material from premium-grade supply contracted under automotive qualification protocols.
- Battery Grade:Material exceeding 56.5% lithium content with sodium and potassium impurities capped below 50 ppm per China's MIIT GB/T 26008 standards. South Korean cathode makers at Gwangyang and Ochang industrial zones concentrate procurement for NCM811 and NCA precursor synthesis. The segment commands price premiums tied to 18-month qualification timelines and carbon footprint documentation required under EU Battery Regulation mandates.
- Industrial Grade:Lower-purity material serving lubricating greases, air conditioning systems, and ceramic glazing applications. Demand concentrates in China's domestic chemical manufacturing belt where specification tolerances remain less stringent than automotive thresholds.
- Technical Grade:Intermediate purity band for specialized catalyst production and polymer manufacturing. German chemical processors represent the primary offtake channel for this specification tier.
- Pharmaceutical Grade:Ultra-high purity material for psychiatric medication synthesis and medical device components. Swiss and Japanese pharmaceutical regulators enforce the strictest impurity ceilings for this niche application.
Battery grade commands the established base. The steepest expansion runs through technical grade as catalyst applications diversify.
Application:
End-use volume distribution reflects cathode chemistry roadmaps and energy density requirements across mobility and stationary power systems.
- Electric Vehicles:High-nickel NCM and NCA cathodes for 800-volt battery platforms specify hydroxide-derived precursors exclusively. Hyundai and Samsung SDI procurement in South Korea anchors volume concentration. Automaker direct offtake contracts are displacing traditional trading house intermediaries in German OEM supply chains.
- Energy Storage Systems:Grid-scale deployments specifying NCM622 and higher-nickel chemistries for containerized systems. This application channel is expanding most quickly as utility procurement shifts toward higher-energy-density configurations.
- Consumer Electronics:Lithium-ion cells for smartphones, laptops, and portable power tools. Japanese electronics manufacturers at the Kansai industrial corridor maintain steady offtake for mid-nickel cathode formulations.
- Aerospace:Specialized battery systems for satellite power and electric aircraft propulsion prototypes. NASA and ESA procurement programs drive ultra-low moisture specification requirements.
Electric vehicles anchor current volume. Energy Storage Systems deliver the steepest expansion trajectory.
End User:
Customer type segmentation tracks procurement sophistication, qualification timelines, and integration depth across the value chain.
- Automotive Manufacturers:Volkswagen and BMW direct supply relationships with Australian conversion projects exemplify disintermediation trends. These buyers demand documented Scope 3 emissions and recycled content disclosures per EU Battery Regulation frameworks.
- Electronics Producers:Samsung SDI and LG Energy Solution cathode divisions concentrate demand in South Korea's manufacturing corridor. Their procurement integrates tightly with precursor synthesis operations.
- Renewable Energy Firms:Utility-scale battery developers specifying containerized storage systems. These customers prioritize volume scalability over automotive-grade qualification stringency.
- Chemical Companies:Diversified processors serving industrial and pharmaceutical applications. Their procurement tolerates broader specification bands than battery-grade channels.
Automotive manufacturers dominate premium-tier offtake. Renewable energy firms are climbing the fastest as grid storage deployment accelerates.
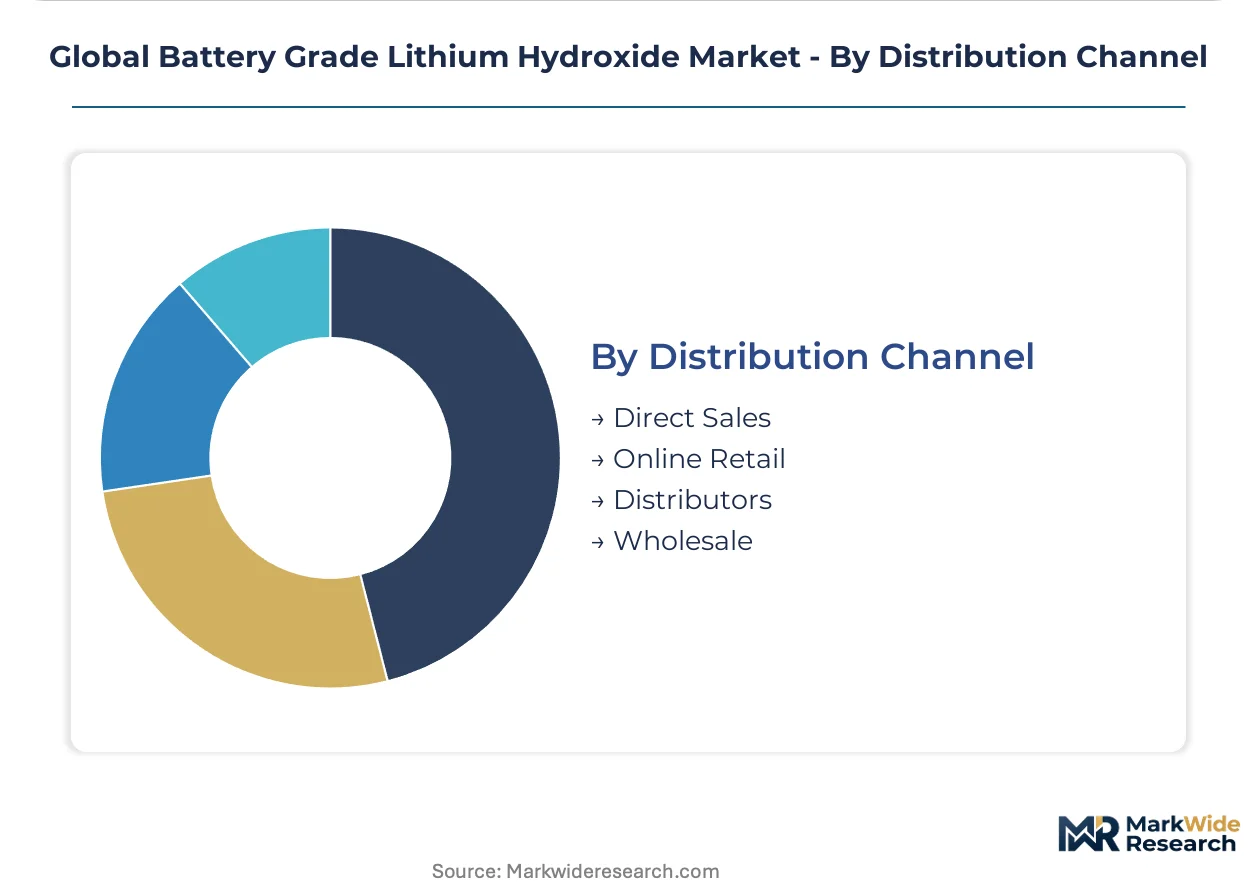
Distribution Channel:
Channel structure reflects disintermediation pressures and the migration from commodity trading toward qualified direct supply relationships.
- Direct Sales:Automaker-to-refiner contracts bypassing traditional traders. This channel captures margin compression from price volatility risk transfer to vehicle manufacturers.
- Distributors:Regional specialists managing qualification documentation and logistics for mid-tier cathode producers. Australian port-based conversion assets leverage distributor networks for Asian market access.
- Wholesale:Bulk material aggregation for industrial and technical grade applications. Chinese domestic refiners utilize wholesale channels for non-export-eligible production.
- Online Retail:Emerging platform for small-volume laboratory and research procurement. This channel remains marginal for battery-grade specifications requiring qualification protocols.
Direct sales commands the established base. Distributor relationships are gaining share fastest as new conversion assets seek market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforces GB/T 26008 purity standards that filter export eligibility for battery-grade material, establishing regulatory gravity across the supply chain. Conversion capacity clusters in Australia, Chile, South Korea, and the United States respond to this specification anchor.
Australia
Spodumene concentrate upgrades at Kwinana and Kemerton anchor hard-rock hydroxide conversion. The country's Critical Minerals Facility directs capital toward integrated port-based plants. Pilbara-to-Perth logistics corridors now host direct shipping ore-to-hydroxide pathways serving Asian cathode makers.
Chile
Atacama brine concentration supports carbonate-derived hydroxide feedstock for non-integrated cathode producers. SQM controls evaporation ponds and conversion assets under CORFO lease agreements. Antofagasta-to-port infrastructure channels material toward contract manufacturers in Asia.
South Korea
Hyundai and Samsung SDI procurement concentrates demand in Gwangyang and Ochang industrial zones. The country's cathode manufacturing corridor specifies hydroxide for NCM811 and NCA precursor synthesis. Korean cathode makers pilot direct acid leach routes for NCM9½½ cells.
United States
IRA domestic content thresholds redirect procurement toward North American conversion capacity in Nevada and North Carolina. Albemarle leverages brine extraction from Silver Peak to cathode customers. The Department of Energy Loan Programs Office underwrites greenfield hydroxide plant development.
Germany
Volkswagen and BMW direct supply relationships with Australian conversion projects bypass traditional trading intermediaries. EU Battery Regulation carbon footprint mandates reshape qualification criteria for European automotive supply chains. BASF cathode precursor operations in Schwarzheide demand documented Scope 3 emissions.
Global Battery Grade Lithium Hydroxide Market Vendor Landscape
Vertically integrated brine operators and hard-rock conversion specialists split the market between feedstock-controlled and asset-light positioning. The structure concentrates around three archetypes: Atacama-based carbonate converters, Australian spodumene integrators, and Chinese state-linked refiners. Competitive moves center on captive offtake contracting and pilot-scale qualification acceleration.
Among brine-based operators, Sociedad Química y Minera de Chile exemplifies the feedstock-controlled archetype through CORFO-leased Atacama assets. Tianqi Lithium Corporation and Ganfeng Lithium Group occupy positions within the state-linked refiner tier, leveraging domestic GB standard compliance for export eligibility. These three anchors represent distinct geographic and regulatory positioning strategies.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Ganfeng Lithium Group |
| Sociedad Química y Minera de Chile (SQM) |
| Tianqi Lithium Corporation |
| Arcadium Lithium |
| Mineral Resources Limited |
| Nemaska Lithium |
| AMG Critical Materials |
| Pilbara Minerals Limited |
| Others |
Supply Flow & Price Mechanics
Kwinana and Kemerton conversion clusters in Western Australia concentrate hard-rock hydroxide capacity, transferring upstream scarcity leverage to contract negotiations with South Korean cathode makers. Automaker direct offtake agreements now compress trading margins while shifting price volatility risk downstream.
Pricing Analysis
Geographic price spreads between Australian conversion assets and Chilean brine-derived supply reflect energy intensity differentials in spodumene acid roasting versus carbonate electrolysis. Contract-based long-term offtake dominates, with premiums attaching to automotive qualification protocols and carbon footprint documentation under EU Battery Regulation mandates. Cost compression in industrial-grade channels stems from Chinese domestic refinery oversupply. Renewable energy firms exhibit highest price sensitivity; German OEM direct contracts show lowest sensitivity due to qualification lock-in requirements.
Supply Chain Analysis
Spodumene concentrate feedstock from Australian hard-rock mines and Atacama brine extraction in Chile anchor upstream supply, with South Korean cathode manufacturing completing the tripartite concentration. Caustic soda, sulfuric acid, and chlor-alkali byproducts constitute critical chemical inputs. Single-source vulnerability runs through Atacama brine operators controlling carbonate-derived hydroxide feedstock. Distribution feeds from integrated port-based conversion plants directly into precursor synthesis operations at Gwangyang and Ochang industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon footprint auditing and Scope 3 emissions verification services attach to every qualified hydroxide contract, with recurring certification revenue expanding faster than commodity conversion margins. This service layer now determines supplier stickiness in European automotive supply chains.
For Market Incumbents: Build qualification protocol moats by accelerating pilot-scale sample throughput to match compressed 18-month cathode maker timelines. Defensive moves center on captive spodumene offtake from Mount Marion and Pilgangoora, plus crystallization circuit retrofits for China's MIIT GB/T 26008 compliance. Sodium and potassium impurity control below 50 ppm constitutes the critical lever against emerging direct acid leach competitors. For New Entrants and Emerging Players: US IRA domestic content thresholds in Nevada and North Carolina represent the most penetrable entry point, with greenfield hydroxide plants qualifying for electric vehicle tax credit passthrough. Grid-scale energy storage system procurement offers parallel volume without automotive qualification barriers. Go-to-market positioning should emphasize NCM622 precursor compatibility for utility battery developers prioritizing scalability over certification stringency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hydrometallurgical specialists with proprietary solvent extraction circuits for calcium and magnesium separation. Long-term viability across the next decade hinges on solid-state electrolyte compatibility and ultra-low moisture specification capability. Watch cathode chemistry roadmaps for cobalt substitution pressures and NCM9½½ adoption rates as inflection signals for hydroxide demand mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spodumene Mining | Ganfeng Lithium Group's captive Mount Marion offtake secures feedstock independence from Pilbara spot volatility. |
| Direct Acid Leach Process Deployment | Korean cathode makers piloting this route at Ochang compress energy intensity for NCM9½½ cell qualification. |
| Carbon Footprint Certification Program | EU Battery Regulation mandates reshape procurement criteria toward documented Scope 3 emissions disclosure. |
| Port-Based Integrated Conversion Capacity | Australian Critical Minerals Facility capital directs greenfield plants at Kwinana to serve Asian precursor makers. |
| Long-Term Supply Agreement with Automotive OEMs | Volkswagen and BMW direct contracts with Australian projects displace traditional trading house intermediaries. |
Methodological Framework
Cross-validation between primary interviews with lithium refinery operations managers, cathode precursor procurement leads, and EU regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from MIIT GB standard filings, SEC 10-K supply chain disclosures, customs trade data for spodumene concentrate flows, and CORFO lease agreement documentation. Bottom-up capacity modeling and top-down demand projection from electric vehicle platform roadmaps complete the triangulation.
Calibration against historical capacity utilization rates and cathode chemistry adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions include product grade tier, cathode chemistry compatibility, end-use application, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand modeling incorporating IRA domestic content thresholds and EU Battery Regulation compliance timelines. Feedstock quality variance and process engineer scarcity constitute industry-specific forecast sensitivity inputs.
Stress conditions across caustic soda input cost volatility, Atacama brine concentration constraints, and qualification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding high-nickel cathode roadmap stability and solid-state electrolyte commercialization pace. Cross-checking against IEA critical minerals supply chain benchmarks and OEM platform production announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Aminic Antioxidants Market