
 Powder Coating Guns Market | 2026-2036
Powder Coating Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Coating Guns Market Analytics
ISO 9001 quality management certification is reorganizing supplier eligibility for tier-one coating system integrators. Nordson Corporation leverages its corona-charge patent portfolio to sustain premium positioning in automatic gun architectures. Gema Switzerland GmbH anchors European demand through precision-engineered tribo-charge systems for automotive OEM lines. Wagner competes aggressively on aftermarket service density across North American industrial corridors.
Powder coating guns are electrostatic spray devices that propel thermoset or thermoplastic powder particles through a charged field onto grounded substrates, typically operating at 60-100 kV corona or triboelectric charge with transfer efficiencies exceeding 95%. Corona-charge technology dominates volume shipments due to lower capital thresholds and broader substrate compatibility, while tribo-charge configurations command margin pools in automotive clear-coat and aerospace primer applications where Faraday-cage penetration proves critical. Manual guns retain installed-base dominance in job-shop environments, though automatic gun demand accelerates as appliance manufacturers in South Korea and Mexico integrate continuous conveyor systems.
EPA NESHAP standards for hazardous air pollutants and REACH restrictions on hexavalent chromium pretreatments are elevating powder-system specifications across regulated jurisdictions. China's MEE enforces progressively stricter VOC emission ceilings that favor electrostatic powder over solvent-borne liquid alternatives in Yangtze River Delta manufacturing zones. Stakeholders must monitor divergence between regional compliance timelines when allocating R&D budgets and qualifying new gun-platform architectures.
Market Dynamics
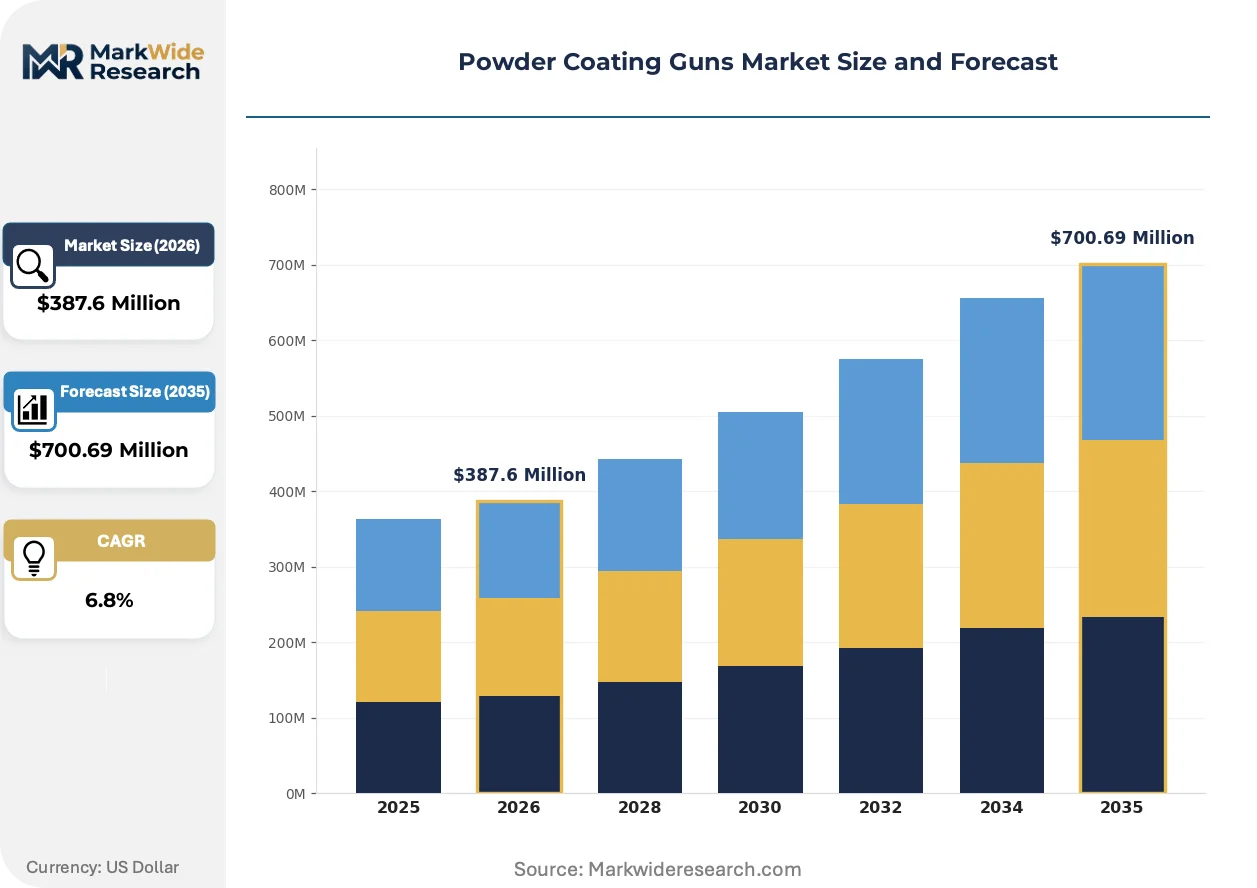
Electrostatic powder coating technology is consolidating around automated conveyor-integrated architectures as appliance and automotive manufacturers eliminate solvent-borne liquid lines to satisfy tightening VOC emission ceilings across multiple regulatory jurisdictions.
Growth Catalysts
- EPA NESHAP hazardous air pollutant standards:US-based metal fabricators and finishing shops accelerate powder system retrofits to avoid compliance penalties and permit restrictions on hexavalent chromium pretreatments.
- Appliance manufacturing scale-up:South Korean and Mexican production clusters for refrigerators, washing machines, and HVAC equipment integrate continuous automatic gun lines to achieve throughput targets and color consistency.
- Triboelectric charging advances:Faraday-cage penetration improvements enable complex automotive clear-coat and aerospace primer applications previously reserved for liquid spray systems.
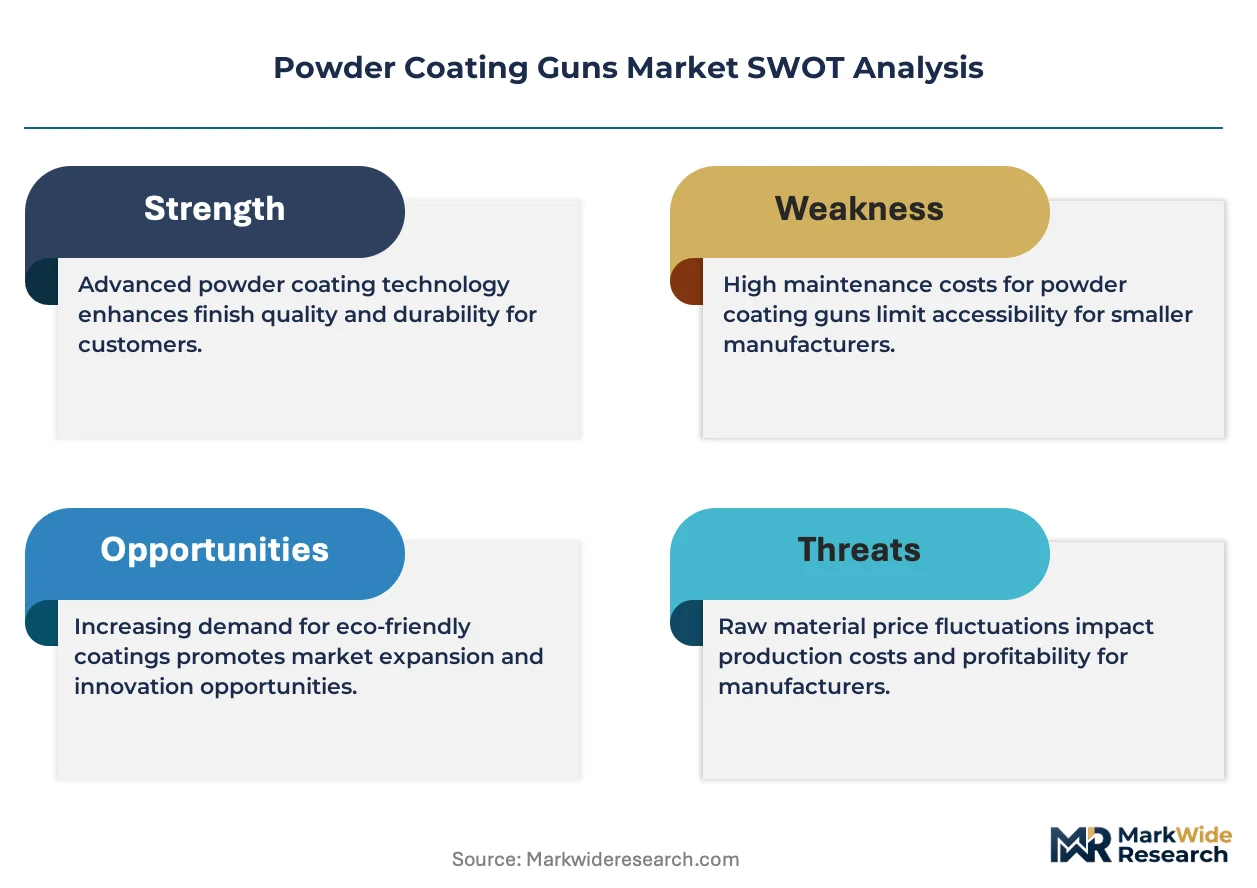
Market Restraints
- Specialized polymer powder supply concentration:Epoxy and polyester resin feedstock production clusters in eastern China and the US Gulf Coast create input cost volatility and logistics vulnerability for gun system operators.
- High-voltage corona equipment capital intensity:60-100 kV power supply modules and precision fluidized-bed hoppers require substantial upfront investment that constrains job-shop adoption in emerging manufacturing economies.
- Substrate pretreatment complexity:Conversion coating chemistries face REACH authorization pressures in Europe, forcing parallel qualification of alternative surface preparation protocols that extend system integration timelines.
Strategic Opportunities
- India automotive component finishing:Tier-one and tier-two suppliers to domestic and export OEMs represent underpenetrated demand for tribo-charge automatic systems as domestic production scales.
- Wind turbine tower coating:Onshore and offshore tower manufacturers seek field-portable manual gun configurations for touch-up and repair applications in remote installation locations.
- China MEE dual carbon alignment:Provincial emission trading schemes and carbon intensity benchmarks create regulatory tailwinds for powder system displacements of solvent-borne lines in Yangtze and Pearl River Delta manufacturing zones.
Industry Challenges
- Electrostatic application technician certification:Shortage of qualified personnel capable of optimizing gun-to-substrate distance, voltage modulation, and powder flow rates constrains line startup and troubleshooting capacity.
- Legacy liquid line decommissioning:Existing spray booth infrastructure, drying ovens, and waste handling systems require coordinated shutdown and environmental remediation that complicates powder system integration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Coating Guns Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Guns, Manual Guns, Automatic Guns, Hybrid Guns Technology: Corona Charge, Tribo Charge, Fluidized Bed, Spray Booth End User: Aerospace, Automotive, Furniture, Electronics Application: Industrial Coating, Decorative Coating, Protective Coating, Appliance Coating |
| Companies Covered | Nordson Corporation, Gema Switzerland GmbH, Wagner, Graco Inc., SAMES KREMLIN, Carlisle Fluid Technologies, Binks, Powder Coating Systems, KCI Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Coating Guns Market Evolving Landscape
Pulse-width modulated voltage control and real-time powder flow monitoring are compressing transfer efficiency variance and enabling predictive maintenance architectures that reduce unplanned line stoppages in continuous manufacturing environments.
Smart gun controllers with embedded current-sensing feedback loops are displacing fixed-voltage analog architectures in high-volume automotive and appliance finishing lines. BMW, Whirlpool, and Haier manufacturing engineers specify these systems to maintain consistent film build across complex part geometries. The displacement is compressing margin pools for legacy gun suppliers lacking digital control IP.
REACH restrictions on chromium trioxide in conversion coatings are forcing parallel qualification of zirconium-based and silane pretreatment chemistries across European automotive OEM supply chains. Tier-one coating system integrators must validate gun spray patterns and curing profiles against these alternative substrates. German and Czech manufacturing clusters are absorbing the largest compliance transition costs.
Buyer consolidation among appliance OEMs is compressing vendor qualification cycles and favoring coating system suppliers offering integrated powder-to-oven turnkey solutions. Procurement teams at Electrolux, Midea, and LG Electronics now specify single-source accountability for film thickness uniformity and color match. This concentration is most visible in Monterrey, Mexico and Changzhou, China industrial corridors.
Powder Coating Guns Market Segmentation
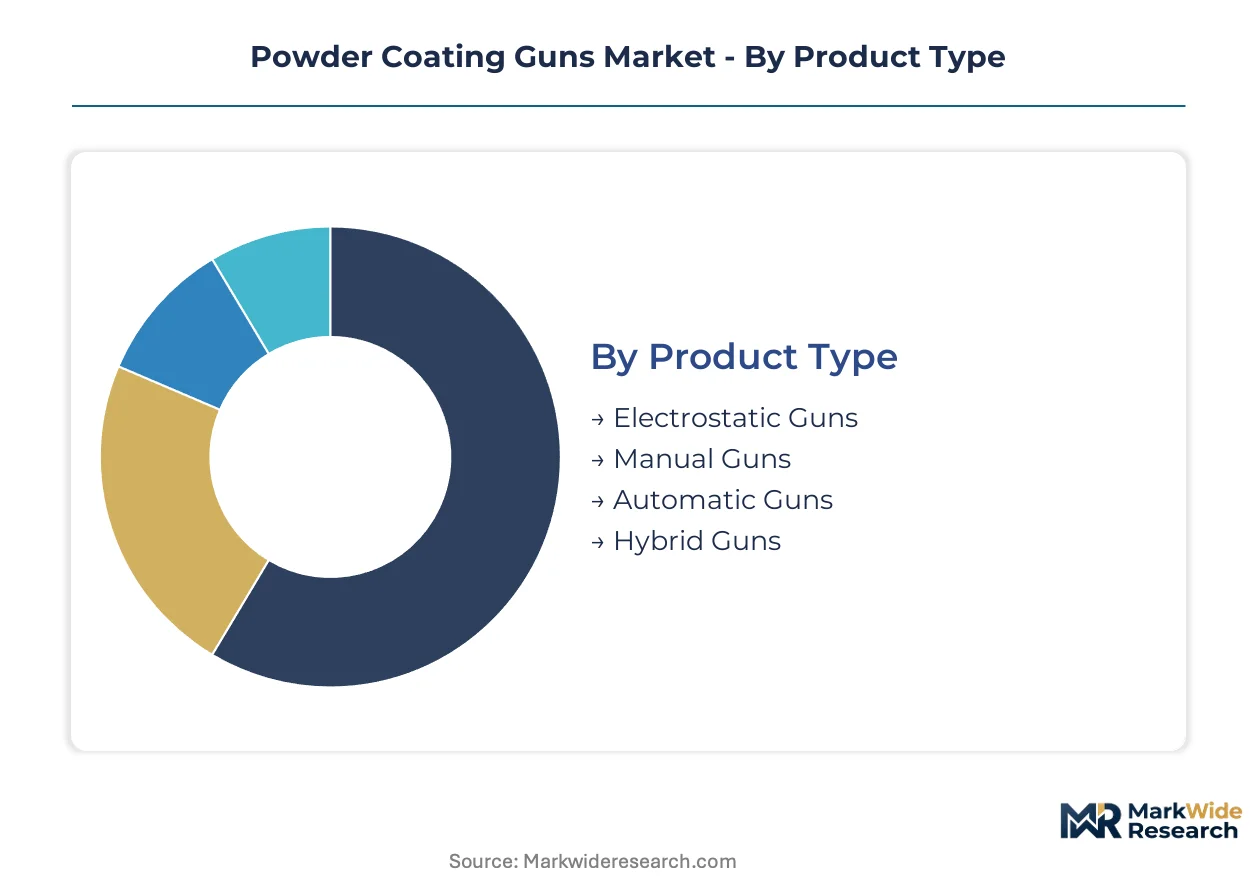
Powder coating gun procurement patterns diverge sharply across product architectures and charging technologies, with automation intensity and regulatory compliance requirements reshaping vendor selection criteria. Understanding segment-level substitution pressures enables stakeholders to anticipate where liquid spray systems retain residual threat and where electrostatic powder achieves irreversible displacement.
Product Type:
Substitution pressure from robotic liquid spray systems weighs most heavily on manual gun configurations, while automatic architectures face competitive threat primarily from alternative finishing technologies rather than direct product substitution.
- Electrostatic Guns:These systems apply 60-100 kV corona or triboelectric charge to propel thermoset or thermoplastic powders, achieving transfer efficiencies above 95% through grounded substrate attraction. Demand concentrates in German and Chinese automotive OEM lines where EPA and REACH VOC limits have eliminated solvent-borne alternatives for chassis and wheel components.
- Automatic Guns:Conveyor-integrated architectures with programmable reciprocators and synchronized powder delivery systems enable continuous throughput for appliance manufacturers. South Korean and Mexican production clusters for refrigerators and HVAC equipment specify these configurations to achieve color consistency across high-volume runs.
- Manual Guns:Handheld units with trigger-controlled powder flow and adjustable voltage modulation serve job-shop environments and field repair applications. These retain installed-base dominance among metal fabricators with batch production requirements.
- Hybrid Guns:Configurable architectures supporting both manual operation and automated mounting adapt to mixed-mode production environments. These address mid-tier manufacturers transitioning from batch to continuous processing.
Manual guns anchor the volume base across job-shop installations while automatic guns gain share at the steepest rate as appliance OEMs eliminate liquid lines.
Technology:
Margin stratification across charging architectures reflects the divergence between capital-threshold accessibility and precision-application premium capture.
- Corona Charge:High-voltage ionization at the gun electrode creates electrostatic fields that propel charged particles toward grounded substrates, operating reliably across diverse powder chemistries and substrate geometries. This technology dominates shipment volumes due to lower equipment costs and broader material compatibility, with particular concentration in North American general industrial applications.
- Tribo Charge:Friction-based charging through proprietary polymer gun barrels generates uniform particle distribution without external high-voltage power supplies, enabling superior Faraday-cage penetration for complex automotive clear-coat and aerospace primer applications where recessed geometries challenge corona systems.
- Fluidized Bed:Submersion-based coating for preheated parts achieves thick film builds in single dips, serving specialized pipeline and rebar applications outside mainstream spray gun demand.
- Spray Booth:Enclosed containment systems with integrated recovery and filtration modules address environmental compliance and powder recycling requirements, typically specified as integrated components rather than standalone gun technologies.
Corona charge technology commands the broadest installed base while tribo charge configurations capture expanding share in automotive and aerospace specification tiers.
End User:
Customer concentration patterns reveal which verticals drive replacement cycles versus greenfield specification, with regulatory pressure intensity varying substantially across sector procurement teams.
- Automotive:OEM finishing lines and tier-one component suppliers specify automatic tribo-charge systems for exterior body panels, wheels, and chassis components where film uniformity and durability standards are most stringent. German and Chinese manufacturers lead system integration as domestic emission regulations tighten.
- Aerospace:Primer and topcoat applications for airframe structures and engine components demand precision film control and traceable process documentation, with triboelectric configurations preferred for complex geometries.
- Electronics:Enclosure finishing for servers, telecommunications equipment, and consumer devices emphasizes thin-film consistency and rapid color change capability.
- Furniture:Metal office and outdoor furniture manufacturers balance decorative appearance requirements with cost constraints, often retaining manual gun configurations in batch production modes.
Automotive end users anchor replacement demand volume while aerospace specifications drive premium technology adoption.
Application:
Functional requirement differentiation separates commodity coating volumes from specification-driven premium segments, with protective and industrial applications facing distinct competitive dynamics.
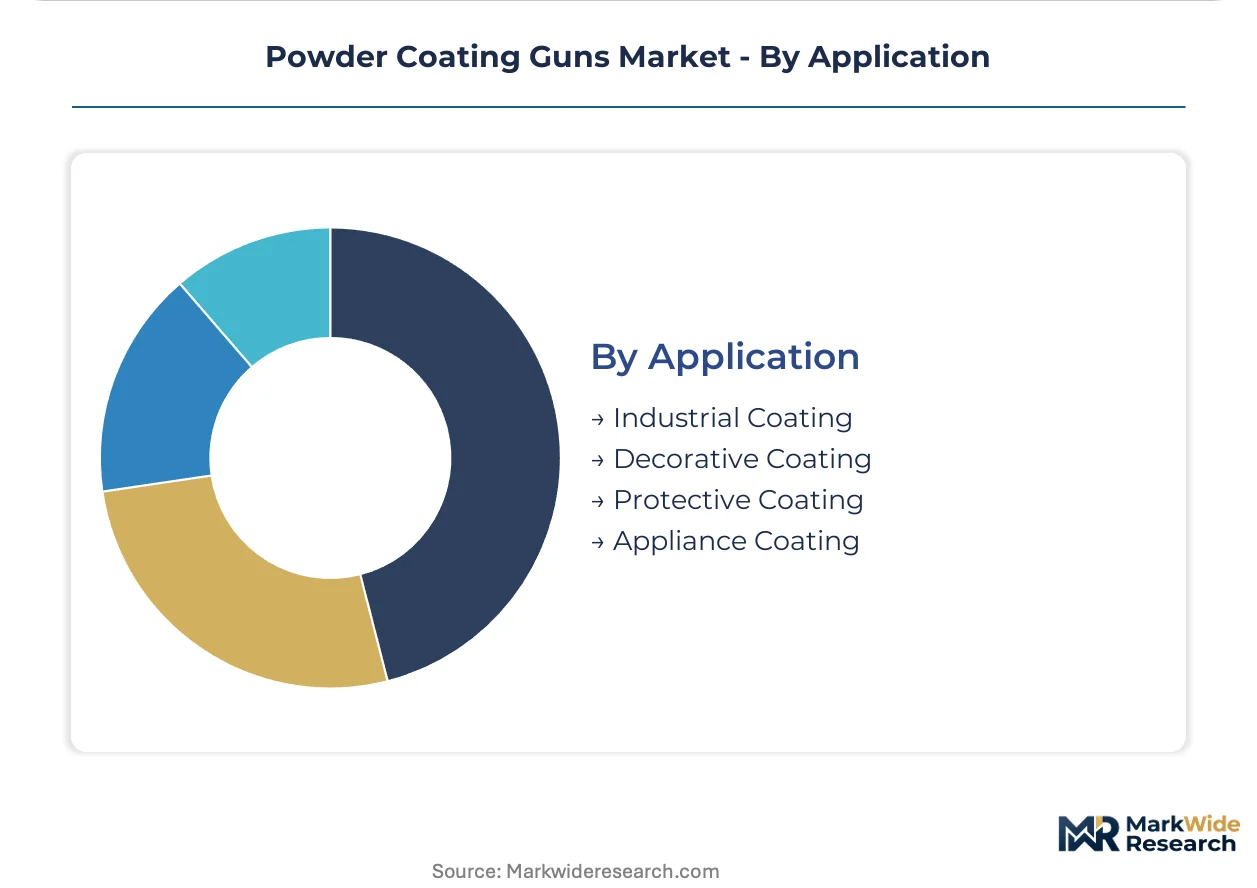
- Industrial Coating:Heavy-duty finishes for agricultural equipment, construction machinery, and material handling systems prioritize corrosion resistance and mechanical durability over aesthetic precision, with corona-charge automatic guns dominating high-throughput lines.
- Protective Coating:Infrastructure and pipeline applications demand specialized epoxy and fusion-bonded powder chemistries applied through field-portable manual configurations or specialized fluidized-bed architectures for in-plant pipe coating.
- Appliance Coating:Refrigerator, washing machine, and HVAC exterior panels require consistent color match and detergent resistance, with South Korean and Mexican manufacturing corridors driving automatic gun specification for continuous conveyor integration.
- Decorative Coating:Architectural aluminum, lighting fixtures, and consumer products emphasize metallic and special-effect finishes with frequent color change requirements, favoring manual gun flexibility in smaller batch environments.
Industrial coating anchors current volume concentration while appliance coating applications expand most quickly as OEMs consolidate supplier relationships around integrated system specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA NESHAP hazardous air pollutant standards and REACH VOC restrictions are accelerating powder coating gun deployment across automotive and appliance manufacturing corridors worldwide. Manufacturers in Germany and China are expanding electrostatic coating lines as regulatory compliance tightens. Demand concentrates in East Asian industrial clusters where appliance and electronics production scales rapidly.
United States
Metal fabricators and finishing shops accelerate powder system retrofits to avoid EPA NESHAP compliance penalties on hexavalent chromium pretreatments. The EPA enforces progressively stricter hazardous air pollutant standards across Midwest and Southeast industrial zones. Automotive OEM lines in Detroit and appliance manufacturers in the Ohio River Valley specify automatic gun configurations for continuous conveyor integration.
Germany
REACH restrictions on chromium trioxide in conversion coatings force automotive OEM supply chains to validate alternative pretreatment chemistries. German manufacturers absorb the largest compliance transition costs across European coating system integrators. Bavarian and Baden-Württemberg automotive clusters specify tribo-charge automatic systems for exterior body panel and wheel component finishing.
China
MEE enforces progressively stricter VOC emission ceilings that favor electrostatic powder over solvent-borne alternatives in Yangtze River Delta manufacturing zones. Provincial emission trading schemes and carbon intensity benchmarks create regulatory tailwinds for powder system displacements. Appliance OEMs in Changzhou and automotive suppliers in Shanghai integrate continuous automatic gun lines for throughput targets.
South Korea
Appliance manufacturers expand refrigerator, washing machine, and HVAC production capacity with integrated continuous conveyor systems. The country's national environmental regulator tightens industrial emission standards favoring powder coating over liquid spray alternatives. Seoul Capital Area and Busan-Ulsan industrial corridors specify automatic gun configurations to achieve color consistency across high-volume runs.
Mexico
Appliance OEMs consolidate supplier relationships around integrated powder-to-oven turnkey solutions in Monterrey manufacturing corridors. Nearshoring trends accelerate metal fabrication capacity expansion for North American export markets. Nuevo León industrial zones absorb specification demand from Electrolux, Midea, and LG Electronics procurement teams seeking single-source accountability for film thickness uniformity.
Powder Coating Guns Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and regional service density dimensions. The vendor base organizes around three strategic tiers: integrated system architects with corona-charge patent portfolios, precision tribo-charge specialists anchored in European automotive supply chains, and aftermarket service providers competing on North American industrial corridor coverage. Competitive moves concentrate on M&A for digital control IP and geographic expansion through distributor network consolidation.
Among Switzerland-based precision engineers, Gema Switzerland GmbH exemplifies the tribo-charge specialist archetype serving automotive OEM qualification requirements. Nordson Corporation represents the integrated system architect tier with established positions in automatic gun architectures. Wagner occupies a position within the aftermarket service density vector across North American industrial markets. These three anchors illustrate the competitive structure without exhaustively mapping the field.
| Leading Market Players |
|---|
| Nordson Corporation |
| Gema Switzerland GmbH |
| Wagner |
| Graco Inc. |
| SAMES KREMLIN |
| Carlisle Fluid Technologies |
| Binks |
| Powder Coating Systems |
| KCI Industrial Co., Ltd. |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification gates supplier eligibility for tier-one coating system integrators while simultaneously stratifying price bands across corona-charge and tribo-charge gun architectures. Buyers in German automotive OEM lines demand certified equipment for REACH-compliant finishing operations, forcing uncertified competitors into steep discounting to retain job-shop segments.
Pricing Analysis
Certification level (ISO 9001/CE marking) creates the primary spread between premium tribo-charge systems and economy corona-charge configurations. Three-tier pricing structure across premium, standard, and economy levels reflects automation intensity, after-sales service bundling, and regional delivery cost differentials. Price erosion runs through manual gun tiers as Chinese manufacturers expand export capacity. Appliance OEM procurement teams in Mexico and South Korea exhibit lowest price sensitivity due to single-source accountability requirements for integrated powder-to-oven systems.
Supply Chain Analysis
Strategic stockpiling of high-voltage power supply modules and precision fluidized-bed hoppers dominates inventory strategy among North American distributors facing extended qualification timelines for new gun-platform architectures. Component sourcing draws from Germany for tribo-charge polymer barrels, Switzerland for precision-engineered nozzles, and China for corona-charge electrode assemblies. Single-source vulnerability concentrates in epoxy and polyester resin feedstock production clusters along the US Gulf Coast and eastern China. Distribution runs through authorized system integrators with regional service density commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among appliance OEMs shifts procurement leverage toward Electrolux, Midea, and LG Electronics procurement teams demanding integrated turnkey accountability. Tier-one supplier qualification cycles compress as these buyers eliminate multi-vendor coating line architectures.
For Market Incumbents: Secure digital control IP through targeted acquisition of smart gun controller specialists to defend against margin compression from analog legacy suppliers. Backward integration into high-voltage power supply production reduces exposure to semiconductor component volatility. Capacity expansion in Monterrey and Changzhou industrial corridors captures specification demand from consolidating appliance OEMs. For New Entrants and Emerging Players: Lead with field-portable manual gun configurations for wind turbine tower touch-up applications in remote installation locations. India's tier-two automotive component finishing segment offers the most penetrable white space for tribo-charge automatic systems as domestic production scales. Channel partnership with established powder coating system integrators accelerates OEM qualification timelines. For Investors and Strategic Acquirers: REACH authorization pressures on chromium trioxide pretreatments reshape the acquisition landscape toward coating system integrators with validated alternative surface preparation protocols. Long-term viability favors precision tribo-charge specialists with automotive OEM qualification track records over commodity corona-charge assemblers. Monitor divergence between EPA NESHAP and China MEE compliance timelines as inflection signal for regional R&D allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Control IP Acquisition | Smart gun controllers with embedded current-sensing feedback loops displace fixed-voltage analog architectures at BMW and Whirlpool lines. |
| Backward Integration into Power Supplies | In-house production of 60-100 kV modules reduces semiconductor component volatility exposure for automatic gun manufacturers. |
| Regional Service Density Expansion | Authorized distributor consolidation in Midwest and Southeast industrial zones captures EPA NESHAP-driven retrofit demand. |
| Alternative Pretreatment Qualification | Zirconium-based and silane chemistry validation opens German automotive OEM supply chains to new system integrators. |
| Field-Portable Manual Gun Development | Touch-up configurations for offshore wind tower repair address logistics constraints in remote North Sea and Great Lakes installations. |
Research Methodology
Cross-validation between primary interviews with coating line engineers and secondary validation through EPA enforcement databases anchors the qualitative findings. Plant managers at automotive OEM finishing lines, procurement leads at appliance manufacturers, aftermarket service heads at industrial distributors, and technical R&D directors at powder coating system integrators provided operational data. Secondary sources include SEC 10-K filings of listed coating equipment suppliers, customs and trade data for powder coating gun imports, REACH authorization status registers, and China MEE emission compliance disclosures. Bottom-up shipment data triangulates against top-down market sizing across the projection horizon.
Sensitivity analysis around regulatory compliance timelines and raw material cost volatility informs the analytical framework. Segmentation dimensions modeled include charging technology architecture, automation intensity level, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and greenfield specification trends. Industry-specific forecast inputs incorporate EPA NESHAP enforcement intensity indices and China provincial emission trading scheme participation rates.
Underlying assumptions cover sustained REACH authorization pressure on hexavalent chromium pretreatments and progressive China MEE VOC ceiling reductions, with deviation risk concentrated in legacy liquid line decommissioning delays and electrostatic technician certification bottlenecks. Revision becomes warranted when regulatory compliance timeline divergence between jurisdictions crosses thresholds that fragment R&D allocation efficiency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Oilfield Biocides and Bio-Solvents Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Soil Treatment Chemicals Market