
 Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market | 2026-2036
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market Foresight
Brazilian pharmaceutical manufacturing capacity is decoupling from historical import dependence as regional fill-finish operations expand. AstraZeneca leverages its cardiovascular outcomes data to anchor hospital formulary positioning across major Latin American markets. Boehringer Ingelheim sustains differentiated access through integrated diabetes-cardiovascular protocols with public health systems. Janssen Pharmaceuticals competes on renal protection labeling, occupying a distinct therapeutic niche in nephrology-driven prescribing.
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitors comprise oral antihyperglycemic agents that block sodium-glucose cotransporter-2 proteins in renal proximal tubules, producing glucosuric effects at plasma concentrations typically below 10 mg daily. These molecules function primarily to lower HbA1c while conferring cardiorenal protection independent of glycemic control. Dapagliflozin dominates hospital procurement through established heart failure admission protocols, while empagliflozin captures expanding outpatient chronic kidney disease segments where renal endpoints drive payer preference. Canagliflozin maintains mature diabetes positioning despite safety labeling constraints that shifted prescriber attention toward newer entrants.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia each enforce bioequivalence standards and pharmacovigilance reporting that shape product registration timelines and post-market surveillance obligations for SGLT-2 inhibitors. These frameworks elevate documentation requirements for cardiorenal outcome claims, filtering which manufacturers secure premium reimbursement tiers versus commodity positioning. Stakeholders must monitor evolving pharmacoeconomic assessments across national health technology evaluation bodies as cardiovascular prevention indications expand beyond diabetes-centric funding pools.
Market Dynamics
Hospital-based prescribing protocols for cardiovascular risk reduction are displacing diabetes-centric reimbursement pathways across Latin America, forcing manufacturers to restructure their regulatory submissions and medical affairs deployment toward cardiology and nephrology specialists rather than endocrinology networks.
Growth Catalysts
- ANVISA streamlined approval:Brazil's regulator has compressed review timelines for cardiorenal outcome claims, accelerating hospital formulary access for agents with proven heart failure admission reduction data.
- Integrated care systems:São Paulo's dense specialist networks are embedding SGLT-2 inhibitors into chronic kidney disease management protocols, creating pull-through from nephrology-driven prescribing.
- Renal endpoint prioritization:Payers across Colombia and Mexico are weighting kidney protection metrics in pharmacoeconomic assessments, favoring agents with documented glomerular filtration rate preservation.
Market Restraints
- Import dependence:Active pharmaceutical ingredient supply concentrates in Indian and Chinese manufacturing clusters, exposing Latin American fill-finish operations to API cost volatility and shipping disruptions.
- COFEPRIS bioequivalence documentation:Mexico's regulator demands extensive bridging studies for cardiorenal indication extensions, extending registration timelines and deferring premium reimbursement tier access.
- Generics substitution pressure:Commodity dapagliflozin copies are eroding pricing power in outpatient diabetes segments where glycemic control alone drives prescribing.
Strategic Opportunities
- Northeast Brazil penetration:Underpenetrated states beyond São Paulo and Rio de Janeiro present whitespace for hospital protocol expansion as regional cardiology residency programs mature.
- INVIMA fast-track pathways:Colombia's regulator offers priority review for agents addressing dual diabetes-heart failure populations, compressing time-to-reimbursement for differentiated entrants.
- Telemedicine integration:Remote patient monitoring platforms are converging with chronic disease management, enabling direct-to-patient adherence programs that bypass traditional pharmacy distribution.
Industry Challenges
- Cardiorenal specialist shortage:Brazil's Northeast and North regions lack sufficient nephrology-trained prescribers to execute hospital protocol expansion, constraining geographic rollout velocity.
- Legacy diabetes detailing infrastructure:Established sales forces optimized for endocrinology relationships require costly retraining and territory restructuring to access cardiology decision-makers.
- Pharmacovigilance reporting harmonization:Divergent post-market surveillance requirements across ANVISA, COFEPRIS, and INVIMA fragment safety database management and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market |
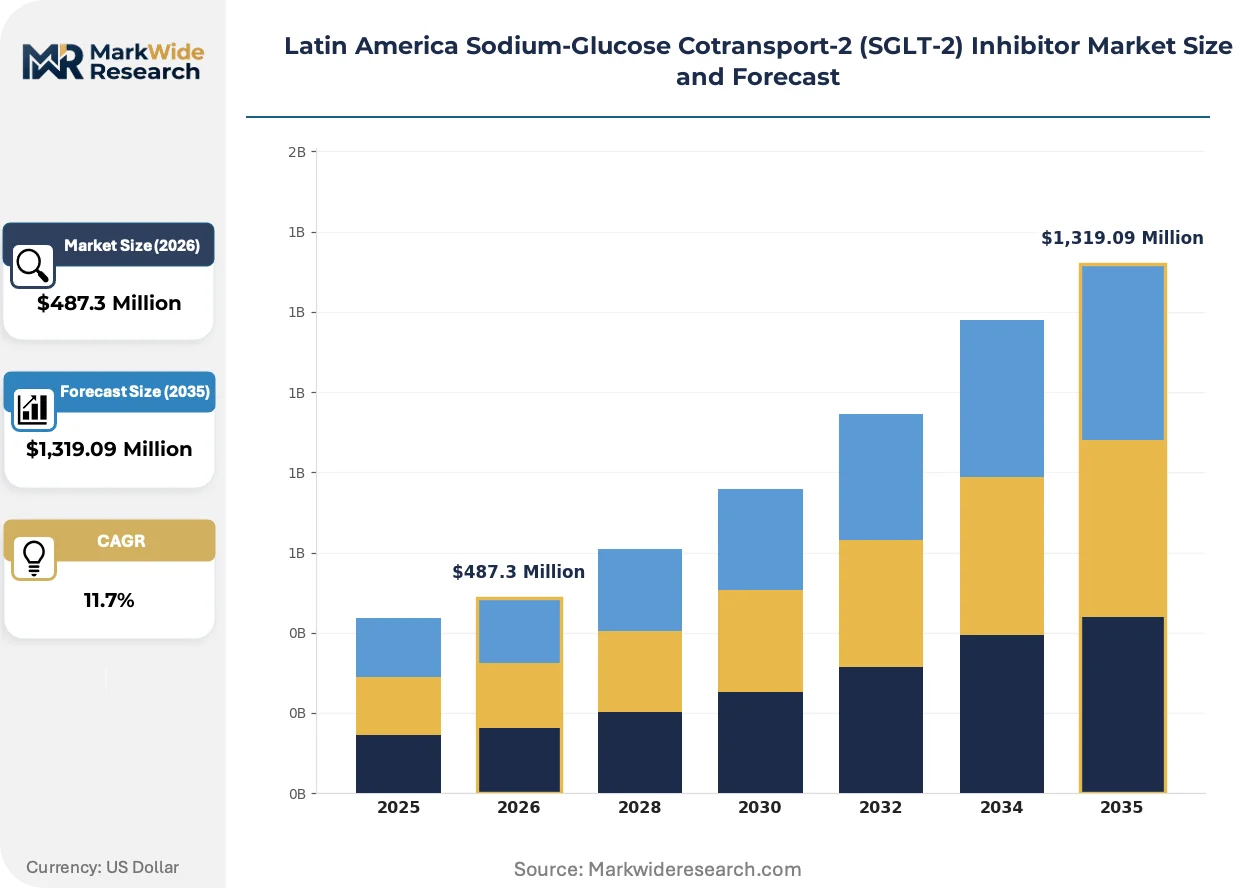
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dapagliflozin, Empagliflozin, Canagliflozin, Ertugliflozin End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Retail, Online, Wholesale, Direct Sale Therapy Area: Diabetes, Cardiovascular, Obesity, Renal |
| Companies Covered | AstraZeneca, Eli Lilly and Company, Janssen Pharmaceuticals, Bristol-Myers Squibb, Astellas Pharma, Boehringer Ingelheim, Johnson & Johnson Services, Inc., Merck & Co., Inc., Lexicon Pharmaceuticals, Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market Shifts & Advancements
Fixed-dose combination therapies are compressing the therapeutic algorithm for cardiometabolic patients, forcing standalone SGLT-2 inhibitors to demonstrate incremental value beyond convenience to maintain formulary positioning.
Triple-combination tablets pairing SGLT-2 inhibition with GLP-1 receptor agonism and metformin are expanding into Brazilian hospital discharge protocols, where pharmacy committees favor simplified regimens to reduce readmission risk. Cardiology departments in São Paulo's integrated networks are adopting these formulations at accelerating pace, compressing demand for single-agent prescribing in high-acuity settings.
ANVISA's 2023 guidance on real-world evidence submissions for cardiovascular outcome claims is redirecting manufacturer investment toward Latin American-specific registry construction rather than reliance on US and EU trial data alone. This regulatory shift elevates documentation burdens for foreign entrants lacking regional clinical infrastructure, while rewarding sponsors with established investigator networks across Brazilian teaching hospitals.
Specialty pharmacy channels are displacing traditional retail distribution for high-complexity cardiorenal patients, with São Paulo and Mexico City seeing concentrated hub-and-spoke models emerge. These platforms bundle adherence monitoring with prior authorization management, capturing margin from payers seeking to reduce emergency department utilization. Colombia's private insurer segment shows the fastest channel migration, where integrated delivery networks contract directly with specialty pharmacies for population management.
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market Segmentation
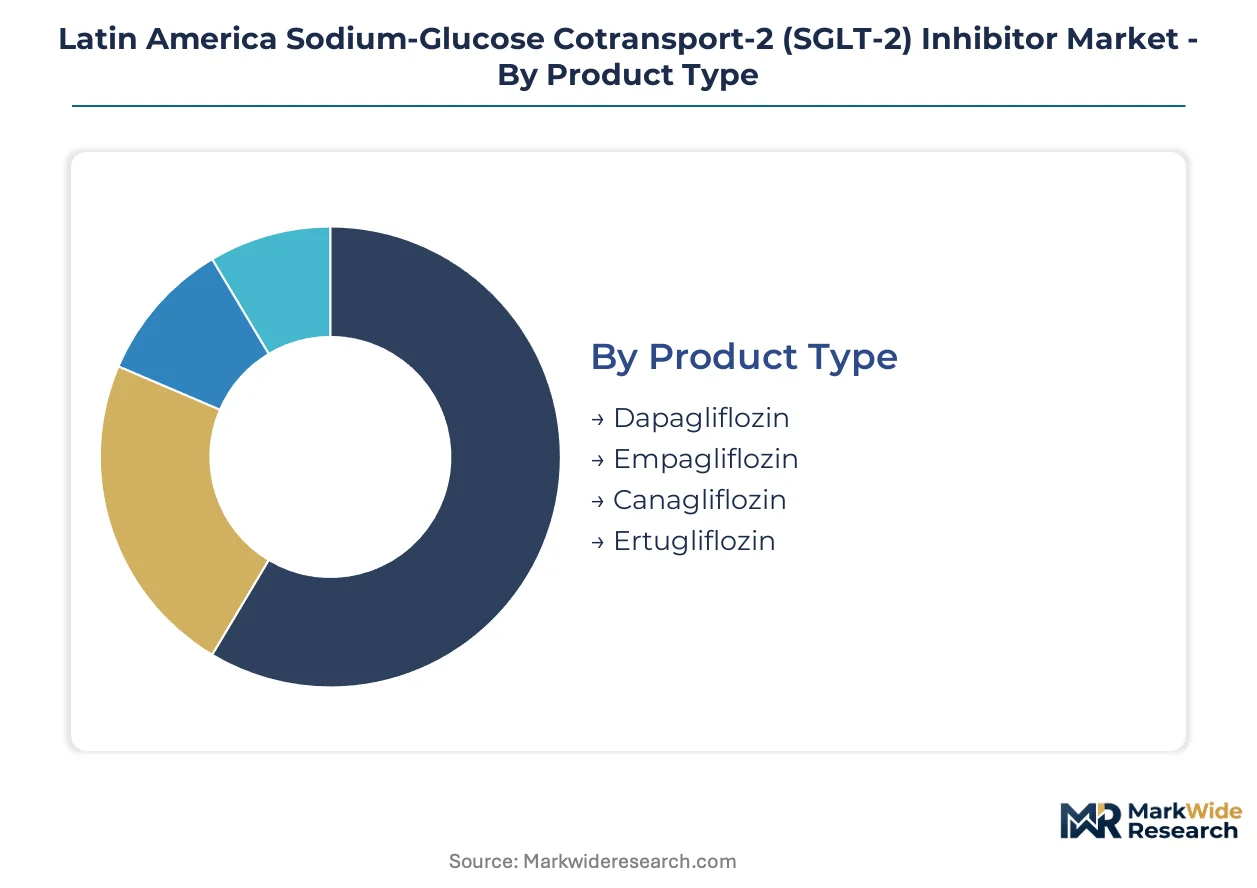
Prescribing protocols across Latin America fragment demand by clinical setting and reimbursement pathway, forcing manufacturers to align product positioning with distinct access requirements. Segmentation reveals where cardiorenal indications command premium positioning versus commodity competition in diabetes-only segments.
Product Type:
Hospital formulary committees differentiate agents by cardiovascular outcome trial design and renal endpoint documentation.
- Dapagliflozin:Oral SGLT-2 inhibitor with established heart failure admission reduction data anchors São Paulo hospital procurement protocols. Southeast Brazil's integrated care systems embed this agent into discharge algorithms for reduced ejection fraction patients, creating pull-through from cardiology-driven prescribing.
- Empagliflozin:Selective renal proximal tubule blocker with documented glomerular filtration rate preservation captures outpatient chronic kidney disease segments across Colombia and Mexico. Payer pharmacoeconomic assessments weight kidney protection metrics, favoring this agent where renal endpoints drive reimbursement tier access.
- Canagliflozin:First-generation SGLT-2 inhibitor maintains mature diabetes positioning despite safety labeling constraints from amputation risk signals.
- Ertugliflozin:Newer entrant competing on glycemic control efficacy in price-sensitive outpatient segments where generic substitution pressure intensifies.
Dapagliflozin leads volumes today; empagliflozin is gaining share fastest.
End User:
Access dynamics split between institutional procurement with protocol-driven prescribing and retail channels where patient cost-sharing determines adherence.
- Hospitals:Cardiology and nephrology departments in Brazilian teaching hospitals drive SGLT-2 inhibitor initiation through admission-to-discharge protocols. ANVISA streamlined approval pathways accelerate formulary access for agents with proven cardiorenal outcomes.
- Clinics:Specialist outpatient settings in São Paulo and Mexico City manage complex cardiometabolic patients requiring integrated diabetes-cardiovascular protocols.
- Pharmacies:Retail dispensing concentrates in Brazil's Southeast region where pharmacy benefit managers negotiate tiered reimbursement for maintenance therapy.
- Homecare:Remote patient monitoring platforms in Colombia's private insurer segment enable direct-to-patient adherence programs bypassing traditional distribution.
Hospitals dominate value capture; homecare is climbing the fastest.
Distribution Channel:
Channel selection determines margin structure and patient access speed, with specialty platforms displacing traditional retail for high-complexity cases.
- Retail:Traditional pharmacy networks handle volume diabetes prescriptions where generic dapagliflozin copies erode branded pricing power.
- Online:Telemedicine-integrated platforms expand in Mexico City and Bogotá, bundling adherence monitoring with prior authorization management.
- Wholesale:Hospital procurement consortia across Brazil's Southeast negotiate tender pricing for cardiovascular indication protocols.
- Direct Sale:Specialty pharmacy hub-and-spoke models in São Paulo capture margin from payers seeking reduced emergency department utilization.
Wholesale channels anchor institutional volumes; online distribution shows steepest expansion trajectory.
Therapy Area:
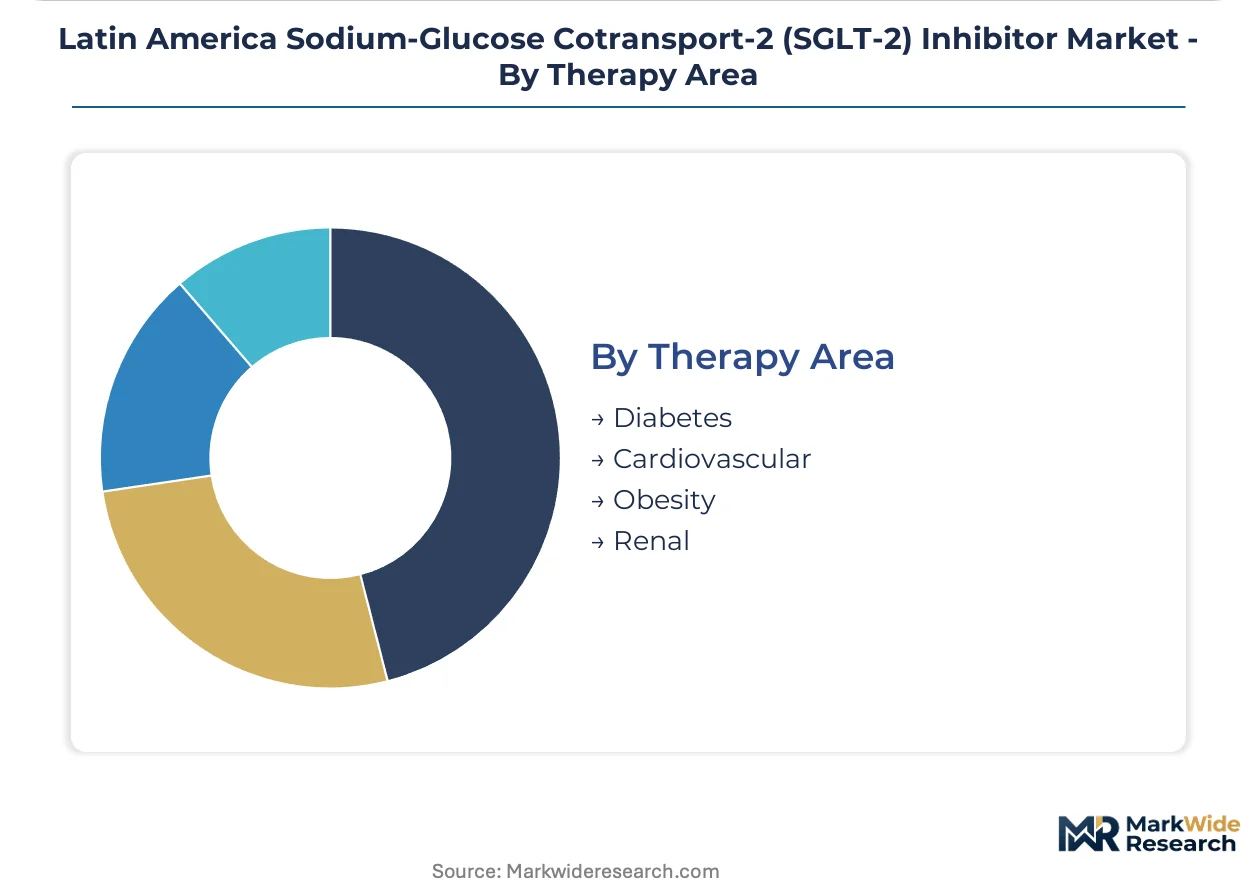
Indication breadth determines reimbursement tier and prescriber specialty target, with cardiovascular and renal applications commanding premium positioning over diabetes-only labeling.
- Diabetes:Glycemic control indication faces commodity pricing pressure from generic entrants in outpatient segments across Latin America.
- Cardiovascular:Heart failure admission reduction claims secure hospital formulary positioning through ANVISA fast-track pathways in Brazil.
- Obesity:Emerging indication with limited current reimbursement coverage, requiring real-world evidence construction for payer acceptance.
- Renal:Chronic kidney disease protection drives nephrology prescribing in Colombia's integrated delivery networks and Mexican public health systems.
Cardiovascular applications lead value generation; renal indications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping pharmaceutical manufacturing footprints across Latin America as Brazil's ANVISA streamlines cardiorenal approval pathways faster than Mexican or Colombian counterparts. Manufacturers are redirecting regional headquarters and medical affairs infrastructure toward São Paulo to exploit this compliance-cost differential.
Brazil
Hospital procurement protocols in Southeast Brazil concentrate SGLT-2 inhibitor demand through São Paulo's integrated care networks. ANVISA's 2023 real-world evidence guidance accelerates formulary access for agents with heart failure admission reduction data. The São Paulo-Rio de Janeiro corridor anchors regional medical science liaison deployment.
Mexico
COFEPRIS bioequivalence requirements extend registration timelines for cardiorenal indication extensions beyond diabetes-only labeling. Mexico City's specialist outpatient clinics manage complex cardiometabolic patients requiring integrated protocols. The capital's pharmacy benefit managers negotiate tiered reimbursement for maintenance therapy.
Colombia
INVIMA fast-track pathways compress time-to-reimbursement for agents addressing dual diabetes-heart failure populations. Bogotá's private insurer segment shows the fastest specialty pharmacy channel migration. Integrated delivery networks contract directly with hub-and-spoke platforms for population management.
Argentina
Macroeconomic volatility constrains hospital procurement budgets despite growing cardiorenal patient burden. The national pharmaceutical regulator maintains stringent import documentation requirements for active pharmaceutical ingredients. Buenos Aires anchors specialist prescribing concentration while interior provinces face access gaps.
Chile
ISP pharmacovigilance standards elevate post-market surveillance obligations for SGLT-2 inhibitors with renal protection claims. Santiago's cardiology residency programs are maturing to support hospital protocol expansion. The metropolitan region concentrates reimbursement decision-making authority.
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated cardiorenal labeling to escape commodity pricing. The market structure consolidates around multinational pharmaceutical conglomerates with cardiovascular outcomes trial infrastructure. Three archetypes dominate: cardiovascular data leaders, renal protection specialists, and integrated diabetes-cardiovascular protocol partners. Competitive moves center on real-world evidence registry construction and specialty pharmacy channel partnerships.
Within the cardiovascular data tier, AstraZeneca and Boehringer Ingelheim anchor hospital formulary positioning through established heart failure protocols. Janssen Pharmaceuticals occupies the renal protection niche, exemplifying specialist positioning where chronic kidney disease endpoints drive nephrology prescribing. These three entities represent distinct strategic vectors—cardiovascular admission reduction, renal function preservation, and integrated care system penetration.
| Leading Market Players |
|---|
| AstraZeneca |
| Eli Lilly and Company |
| Janssen Pharmaceuticals |
| Bristol-Myers Squibb |
| Astellas Pharma |
| Boehringer Ingelheim |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| Lexicon Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
Hospital procurement consortia across Brazil's Southeast region anchor pricing power through volume-based tender negotiations, compressing margins for manufacturers while rewarding agents with differentiated cardiorenal labeling. This buyer concentration forces a contract-based pricing structure where formulary tier placement determines net realized price.
Pricing Analysis
Distributor margins for specialty pharmacy channels absorb 15-25% of ex-manufacturer price in São Paulo's hub-and-spoke models, while retail pharmacy markups run thinner at 8-12% for commodity diabetes prescriptions. Price differentiation hinges on cardiovascular outcome trial documentation and ANVISA fast-track certification tier. Cost compression in outpatient diabetes segments intensifies as generic dapagliflozin copies erode branded pricing power. Retail pharmacy patients in Brazil's Northeast show highest price sensitivity; hospital formulary committees in São Paulo show lowest.
Supply Chain Analysis
Brazil's ANVISA local-content requirements for finished pharmaceutical products are reshaping sourcing patterns, pressuring manufacturers to expand regional fill-finish capacity. Active pharmaceutical ingredient supply draws from Indian and Chinese manufacturing clusters, with key inputs including dapagliflozin API, empagliflozin intermediates, and canagliflozin starting materials. Single-source vulnerability concentrates in API supply from specific Indian manufacturing sites. Distribution runs through wholesale hospital procurement consortia for institutional volumes and specialty pharmacy platforms for high-complexity cardiorenal patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Latin American SGLT-2 inhibitors rests on shifting patient volume toward cardiorenal indications where premium formulary tiers offset diabetes-segment compression. This premium-tier shift is enabled by ANVISA's streamlined cardiovascular outcome approval pathways.
For Market Incumbents: Acquire regional real-world evidence registry infrastructure to defend hospital formulary positioning against emerging entrants lacking Latin American-specific cardiovascular outcome data. Consolidate medical science liaison networks in São Paulo's teaching hospitals to deepen cardiology specialist relationships. Threat: Boehringer Ingelheim's integrated diabetes-cardiovascular protocols with public health systems. Lever: backward integration into regional API sourcing to reduce import dependence exposure. For New Entrants and Emerging Players: The mid-tier pricing gap between premium cardiovascular-labeled agents and economy diabetes generics presents whitespace for differentiated renal protection positioning. Target Colombia's INVIMA fast-track pathway for dual diabetes-heart failure populations where reimbursement timelines compress. Penetrate Northeast Brazil's underdeveloped cardiology residency markets before specialist networks mature. Go-to-market angle: nephrology-driven prescribing protocols in integrated delivery networks. For Investors and Strategic Acquirers: Cardiovascular-focused pharmaceutical conglomerates are the most active acquirer in this space, seeking Latin American-specific outcome trial infrastructure. Long-term viability favors sponsors with established investigator networks across Brazilian teaching hospitals and ANVISA regulatory relationships. Acquisition target archetype: regional specialty pharmacy platforms with hub-and-spoke distribution in São Paulo and Bogotá. Signal to watch: INVIMA and COFEPRIS adoption of ANVISA-style real-world evidence guidance for cardiovascular claims.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Registry Construction | ANVISA's 2023 guidance elevates regional trial data above US and EU submissions alone. |
| Specialty Pharmacy Channel Partnership | São Paulo's hub-and-spoke models capture margin from payers seeking reduced emergency department utilization. |
| Cardiorenal Indication Extension | COFEPRIS bridging study requirements in Mexico extend timelines but secure premium reimbursement tiers. |
| Regional Fill-Finish Capacity Expansion | Brazil's local-content rules decouple manufacturing from historical API import dependence. |
| Telemedicine Adherence Platform Integration | Colombia's private insurer segment enables direct-to-patient programs bypassing traditional distribution. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API import tracking forms the analytical core of this study. Primary interviews with formulary directors, cardiology department heads, regulatory affairs leads at ANVISA, and payer access specialists informed demand-side assumptions. Secondary validation drew from ANVISA registration databases, COFEPRIS approval records, INVIMA fast-track pathway documentation, and hospital procurement tender archives. This dual approach triangulates volume estimates against supply-side manufacturing capacity.
Historical trendline analysis of SGLT-2 inhibitor adoption across cardiovascular and renal indications established baseline penetration curves. The analytical framework projects volumes across product type, end user, distribution channel, and therapy area segmentation, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from fitted growth curves adjusted for indication-specific reimbursement velocity. Forecast inputs include ANVISA approval timeline compression, cardiorenal specialist supply expansion rates, and generic substitution elasticity in diabetes-only segments.
Caveats apply where ANVISA regulatory delays, API supply disruptions from Indian manufacturing clusters, or COFEPRIS bioequivalence documentation requirements could materially shift the outlook. Forecasts reflect documented assumptions about cardiorenal indication expansion velocity and hospital protocol adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
Thin Film Drug Manufacturing Market