
 Pharmaceutical Elixir Market | 2026-2036
Pharmaceutical Elixir Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Elixir Market Analysis
The gap between premium branded elixirs and commodity-grade alternatives is realigning procurement patterns across hospital networks and retail pharmacies. Novartis leverages its biologics expertise to command premium positioning in specialized therapeutic elixirs. Sun Pharmaceutical Industries anchors volume production through backward integration into active pharmaceutical ingredient supply. Gencyst Biotech differentiates via concentrated R&D in novel solvent systems for enhanced bioavailability.
Pharmaceutical elixirs are hydroalcoholic liquid preparations containing dissolved or suspended medicinal agents, typically formulated with ethanol concentrations between 5% and 40% to optimize solubility and preservation. These formulations serve as critical delivery vehicles for populations with swallowing difficulties, including pediatric and geriatric patients. Syrup formulations occupy the largest volume share due to their palatability and stability profiles, while tincture segments retain niche dominance in herbal and complementary medicine channels. The antihistamine active ingredient category leads prescription volumes, though herbal compositions represent the fastest-growing margin pool as natural product regulations evolve. Oral administration routes command structural priority across all therapeutic areas, with pediatric applications driving formulation innovation in taste-masking technologies.
FDA Current Good Manufacturing Practice standards, EMA quality guidelines for liquid dosage forms, and India's CDSCO manufacturing license requirements collectively shape product standards and market access barriers for elixir manufacturers. Compliance costs favor scaled producers with dedicated quality infrastructure, compressing margins for smaller regional operators. Stakeholders must monitor regulatory divergence between stringent Western markets and emerging economy frameworks to optimize portfolio allocation and facility certification investments.
Market Dynamics
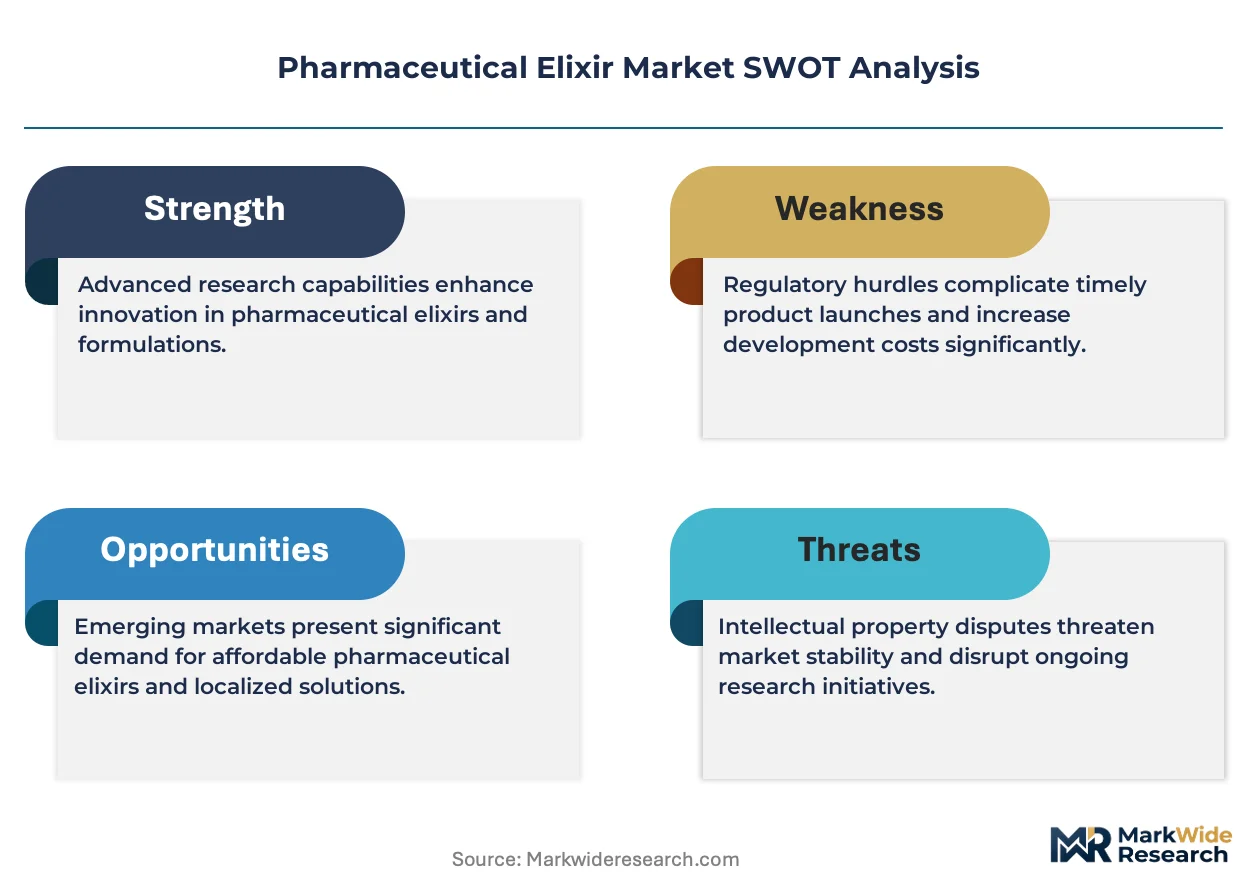
FDA Current Good Manufacturing Practice enforcement is compressing margins for regional elixir manufacturers while favoring scaled producers with dedicated quality infrastructure. This regulatory pressure is accelerating consolidation across liquid pharmaceutical supply chains.
Growth Catalysts
- CDSCO manufacturing license expansion:India's streamlined export certification pathways enable domestic manufacturers to access regulated Western markets with reduced technical barriers.
- Pediatric formulation demand:Caregivers increasingly specify palatable liquid alternatives for young patients with swallowing difficulties, pulling volume from solid dosage forms.
- Herbal composition regulatory evolution:Natural product frameworks in multiple jurisdictions are creating compliant pathways for traditional medicine elixirs previously restricted to informal channels.
Market Restraints
- Ethanol supply volatility:Hydroalcoholic formulation costs fluctuate with biofuel policy shifts and grain commodity cycles in major producing regions.
- Quality infrastructure concentration:Validated aseptic filling capacity clusters with contract manufacturing organizations in India and selected European hubs.
- Solid dosage substitution:Orally disintegrating tablets and mini-tablets capture pediatric and geriatric indications previously reserved for liquid forms.
Strategic Opportunities
- CDSCO-EMA mutual recognition pathway:India's bilateral regulatory cooperation creates accelerated market access for compliant domestic manufacturers.
- Taste-masking technology convergence:Combination of polymer microencapsulation and flavor engineering enables bitter active ingredient formulation.
- Direct-to-pharmacy distribution:Hospital network consolidation in the United States and Germany enables bypass of traditional wholesale tiers.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in hydroalcoholic stability and preservative efficacy remains concentrated with legacy manufacturers.
- Aseptic line qualification timelines:FDA and EMA facility inspections create 18-24 month certification delays for new production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Elixir Market |
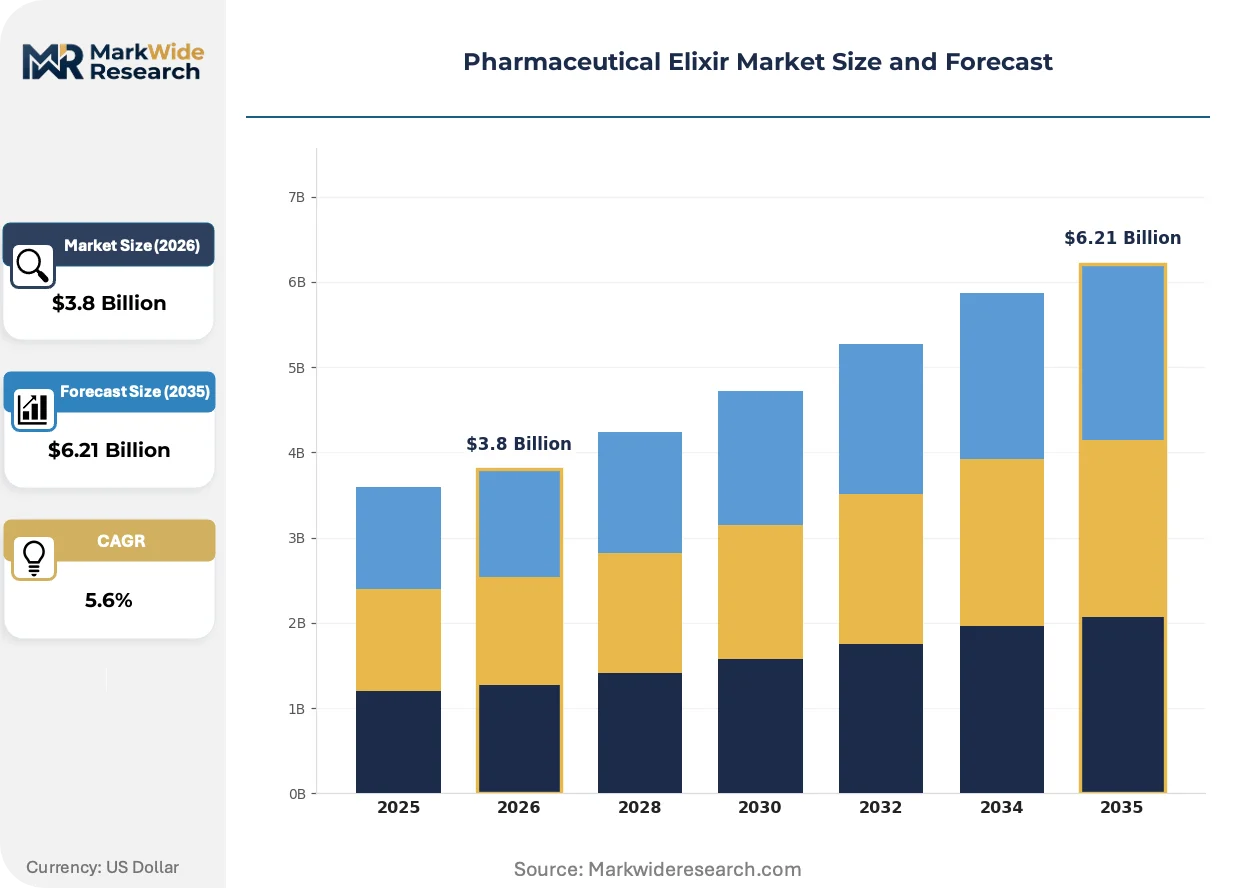
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syrup, Tincture, Solution, Suspension Active Ingredient: Herbal, Antihistamine, Antipyretic, Antiseptic Therapeutic Area: Pediatrics, Geriatrics, Pain Management, Infectious Disease Administration Route: Oral, Topical, Intravenous, Inhalation |
| Companies Covered | Cipla, Sun Pharmaceutical Industries, Novartis, Gencyst Biotech, Purna Pharmaceutical, Johnson & Johnson, Zydus Group, Life Flower Care, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Elixir Market Emerging Trajectories
Continuous manufacturing and advanced process analytical technology are displacing batch production in liquid pharmaceutical facilities. These shifts promise reduced waste and real-time quality assurance.
Hot-melt extrusion combined with solvent-free processing is modularizing taste-masking and bioavailability enhancement workflows. Pediatric-focused manufacturers adopt these platforms to compress development cycles from 24 months to under 12. The technology is enabling smaller batch sizes for orphan indications without sacrificing unit economics.
EMA's revised quality guidelines for liquid dosage forms mandate enhanced extractables and leachables testing for primary packaging. Manufacturers serving European markets must validate container closure systems against tightened thresholds. High-barrier plastic and glass alternatives are displacing conventional packaging in premium therapeutic categories.
Hospital procurement consolidation is compressing supplier panels and unbundling technical services from product supply. Integrated delivery networks in the United States now specify outcome guarantees for pediatric adherence programs. This shift pressures traditional distributors to demonstrate patient compliance metrics alongside unit pricing.
Pharmaceutical Elixir Market Segmentation
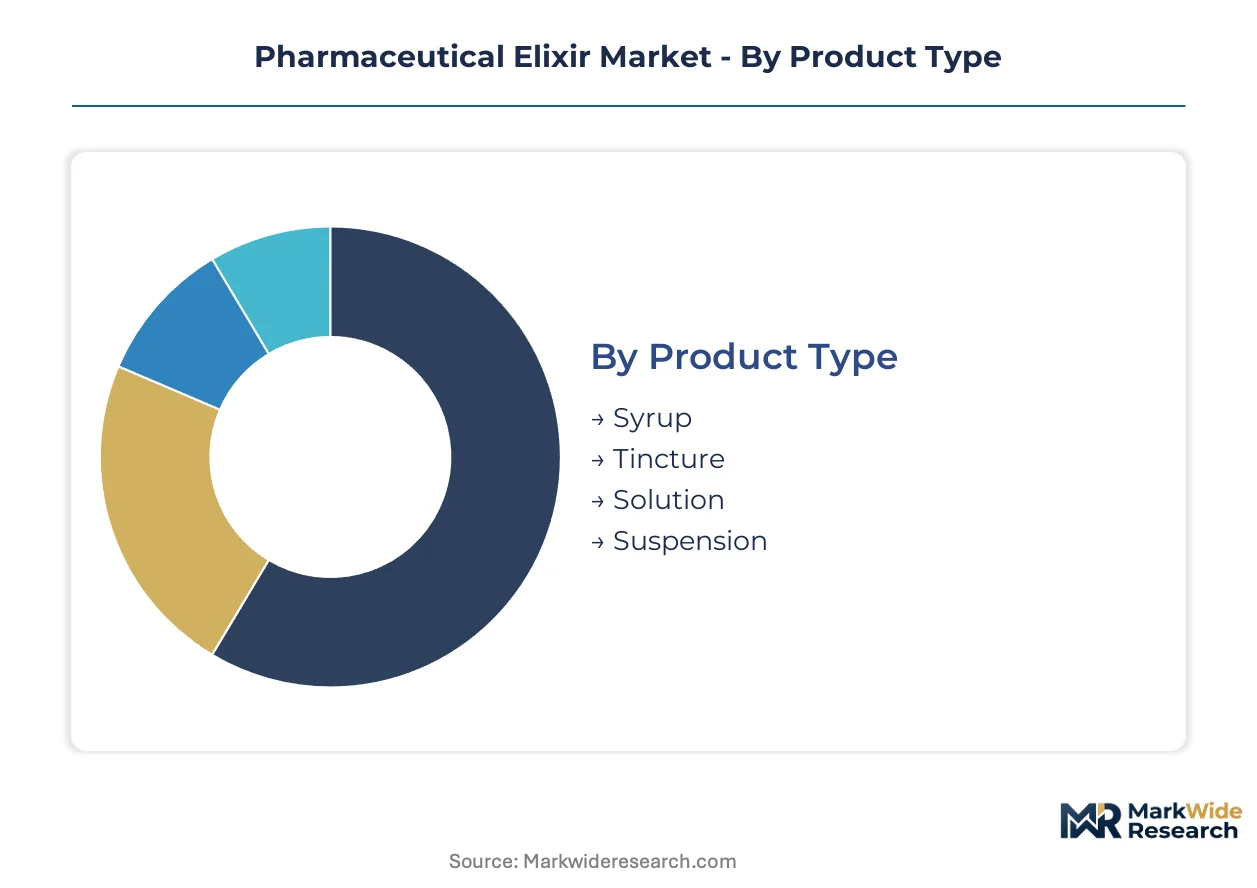
Pharmaceutical elixir segmentation reflects divergent technical requirements across patient populations and therapeutic contexts. Formulation choices directly determine manufacturing infrastructure investments, regulatory pathways, and distribution economics. Understanding these segment boundaries enables targeted portfolio positioning against specific unmet medical needs.
Product Type:
Upgrade cycles in liquid pharmaceutical manufacturing favor facilities capable of flexible multi-format production, with legacy single-format lines facing accelerated obsolescence.
- Syrup:Viscous aqueous solutions incorporating high concentrations of sucrose or alternative sweeteners for stability and palatability. Pediatric formulations in India and the United States concentrate demand here, with CDSCO and FDA bioequivalence requirements driving formulation standardization investments.
- Tincture:Hydroalcoholic extracts with ethanol content typically exceeding 25 percent, historically dominant in herbal and complementary medicine channels. European natural product regulatory evolution is pulling tincture volumes into compliant pharmacy distribution from informal markets.
- Solution:Homogeneous molecular dispersions of active ingredients in aqueous or hydroalcoholic vehicles, offering precise dosing control. Hospital procurement consolidation in Germany favors unit-dose solution packaging for formulary compliance tracking.
- Suspension:Heterogeneous dispersions of insoluble particulate matter requiring robust shaking protocols and sedimentation-resistant formulation engineering. Geriatric applications in Japan leverage suspension formats for patients with dysphagia, with PMDA stability guidelines mandating extended shelf-life validation.
Syrup sits at the top of the volume ranking, with Tincture climbing the fastest.
Active Ingredient:
Cost tier differentiation separates premium synthetic actives from commodity botanical extracts, with margin structures inverting as regulatory compliance costs escalate.
- Herbal:Plant-derived constituents including alkaloids, glycosides, and essential oils extracted through maceration or percolation. India's export-oriented manufacturers scale herbal elixir production under CDSCO GMP certification for access to EMA-regulated European markets.
- Antihistamine:Synthetic H1-receptor antagonists formulated for allergy and cold symptom management. Pediatric liquid antihistamines dominate prescription volumes in the United States, with FDA concentration restrictions on diphenhydramine products reshaping formulation strategies.
- Antipyretic:Fever-reducing agents including acetaminophen and ibuprofen suspensions. Retail pharmacy chains in Brazil specify antipyretic elixirs with ANVISA-compliant child-resistant packaging and dosing devices.
- Antiseptic:Microbial growth-inhibiting compounds for topical and oral mucosal application. Wound care protocols in Australian hospitals specify chlorhexidine-based antiseptic solutions with TGA-validated sterility assurance.
Antihistamine commands the largest prescription base, with Herbal gaining share fastest.
Therapeutic Area:
Application-specific formulation requirements create divergent technical barriers, with pediatric and geriatric segments demanding specialized taste-masking and dosing precision capabilities.
- Pediatrics:Age-appropriate liquid formulations addressing swallowing difficulties in patients under 12 years. Palatability engineering and precise mg/kg dosing dominate development priorities, with integrated delivery networks in the United States now requiring adherence outcome guarantees.
- Geriatrics:Formulations optimized for polypharmacy management and reduced gastric motility in aging populations. Japanese PMDA guidelines for geriatric dosing precision drive analytical method investments among contract manufacturers.
- Pain Management:Opioid and non-opioid analgesic liquids with abuse-deterrent packaging specifications. DEA scheduling requirements in the United States constrain distribution channel options for controlled-substance elixirs.
- Infectious Disease:Antimicrobial and antiviral liquids requiring stringent stability profiles across tropical storage conditions. CDSCO export certification for infectious disease elixirs enables Indian manufacturers to supply WHO prequalified procurement programs.
Pediatrics sits at the top of the volume ranking, with Geriatrics climbing the fastest.
Administration Route:
Supply concentration in validated aseptic filling capacity favors oral and parenteral formats, with topical and inhalation routes requiring specialized manufacturing site qualifications.
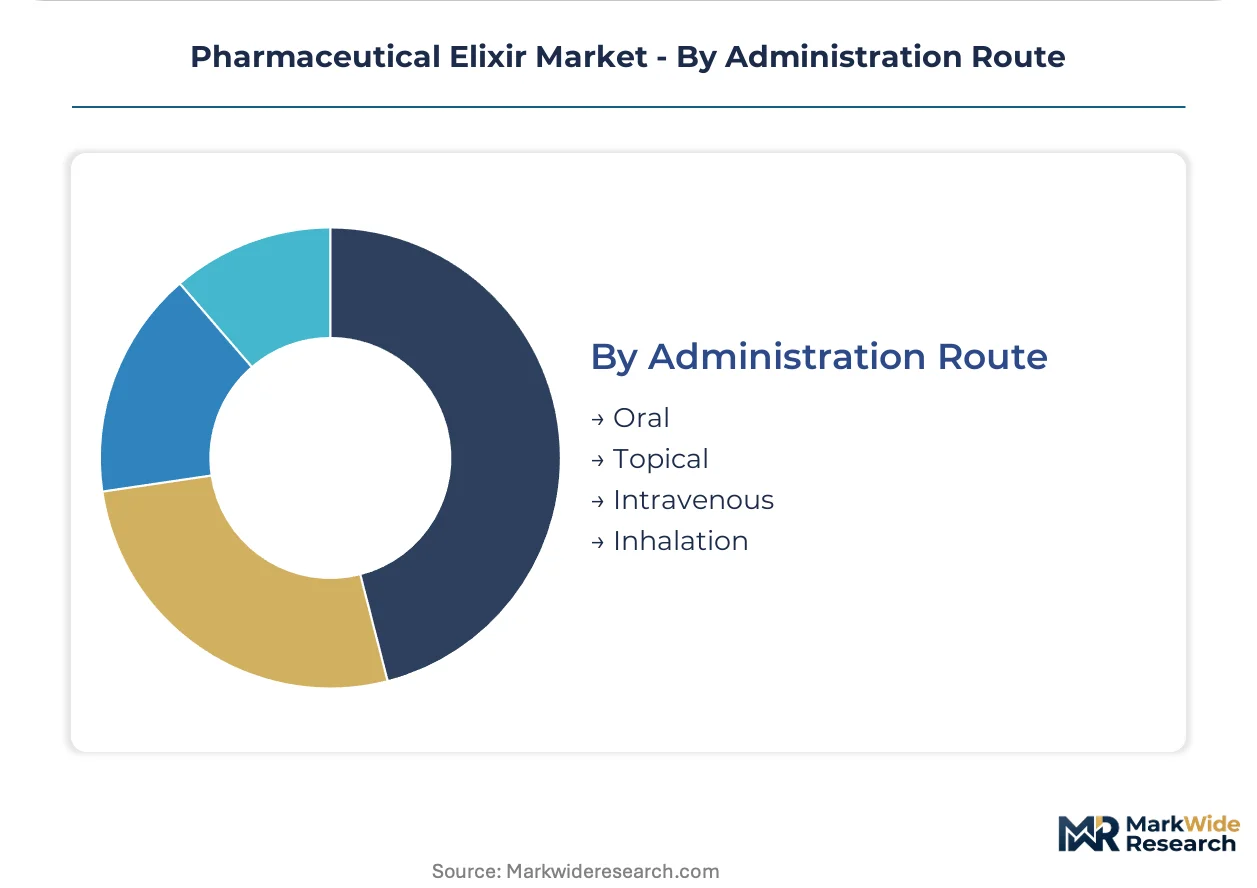
- Oral:Systemic delivery through gastrointestinal absorption, commanding structural priority across all therapeutic categories. EMA revised quality guidelines for liquid dosage forms mandate enhanced extractables and leachables testing for oral elixir primary packaging systems.
- Topical:Cutaneous or mucosal application for localized therapeutic effect. Dermatology-focused manufacturers in Switzerland leverage Swissmedic certification for premium topical elixir positioning in European pharmacy channels.
- Intravenous:Direct vascular administration requiring absolute sterility and pyrogen-free validation. Aseptic line qualification timelines of 18-24 months for FDA and EMA facility inspections concentrate IV elixir production with established contract manufacturing organizations.
- Inhalation:Pulmonary delivery through nebulization or metered-dose systems, niche in elixir formats but expanding for respiratory therapeutics. Health Canada PMRA guidelines for inhalation product particle size distribution constrain formulation options.
Oral sits at the top of the volume ranking, with Topical climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation scientists and quality assurance specialists concentrate in regulatory-heavy jurisdictions, anchoring production clusters where FDA, EMA, and CDSCO standards intersect with contract manufacturing scale.
United States
Pediatric antihistamine prescriptions and hospital procurement consolidation drive formulation demand. FDA Current Good Manufacturing Practice enforcement tightens quality benchmarks for liquid pharmaceuticals. New Jersey and Massachusetts clusters host specialized aseptic filling capacity serving integrated delivery networks.
Germany
Hospital formulary compliance tracking and unit-dose packaging specifications shape procurement patterns. EMA revised quality guidelines for liquid dosage forms mandate enhanced extractables and leachables testing. Bavaria and North Rhine-Westphalia concentrate validated manufacturing infrastructure for European distribution.
India
Export-oriented herbal elixir production and contract research organization scaling pull investment into liquid pharmaceutical capacity. CDSCO manufacturing license expansion streamlines export certification pathways for Western markets. Gujarat and Maharashtra anchor backward-integrated active pharmaceutical ingredient supply chains.
Japan
Geriatric dysphagia formulations and polypharmacy management requirements sustain suspension and solution demand. PMDA stability guidelines mandate extended shelf-life validation for aging-population therapeutics. Kansai and Kanto regions concentrate analytical method investments among contract manufacturers.
Switzerland
Premium topical elixir positioning and dermatology-focused manufacturing attract specialized quality infrastructure. Swissmedic certification enables pharmacy channel access across European markets. Basel and Zurich clusters leverage legacy pharmaceutical expertise for niche therapeutic categories.
Pharmaceutical Elixir Market Vendor Landscape
Top-tier vendors anchor premium therapeutic positioning, while mid-scale producers compete on volume and regulatory compliance speed. The vendor base stratifies across three tiers: multinational biologics specialists, Indian integrated manufacturers, and regional contract research organizations. Two dominant competitive moves are reshaping structure: backward integration into active pharmaceutical ingredient supply and taste-masking technology licensing partnerships.
Within the multinational biologics tier, Novartis and GlaxoSmithKline occupy positions leveraging specialized therapeutic expertise. Sun Pharmaceutical Industries exemplifies the Indian integrated manufacturer archetype with captive supply chain control. Gencyst Biotech represents the concentrated R&D specialist model, anchoring novel formulation development capabilities.
| Leading Market Players |
|---|
| Cipla |
| Sun Pharmaceutical Industries |
| Novartis |
| Gencyst Biotech |
| Purna Pharmaceutical |
| Johnson & Johnson |
| Zydus Group |
| Life Flower Care |
| GlaxoSmithKline |
| Others |
Supply Flow & Price Mechanics
Continuous manufacturing adoption and advanced process analytical technology deployment are compressing unit production costs while concentrating validated capacity among scaled producers with dedicated quality infrastructure. This simultaneous cost-down and supply-concentration dynamic is reshaping procurement economics for hospital networks and retail pharmacy chains.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes procurement arrangements across buyer tiers. Hospital procurement consolidation in the United States and Germany favors three-tier pricing structure across premium, standard, and economy levels, with premium tiers commanding outcome guarantees for pediatric adherence programs. Price differentiation centers on FDA and EMA certification grade plus after-sales technical support depth. Cost compression in standard tiers is intensifying because contract manufacturing organizations in India absorb quality infrastructure investments across volume production. Integrated delivery networks exhibit lowest price sensitivity; independent retail pharmacies in emerging markets exhibit highest.
Supply Chain Analysis
Formulation scientist scarcity in India, Germany, and the United States is tethering specialized expertise to legacy manufacturers with established training pipelines. Active pharmaceutical ingredient supply concentrates in Gujarat and Maharashtra, India, with backward-integrated domestic manufacturers commanding procurement leverage. Ethanol feedstocks, high-barrier packaging substrates, and aseptic filling equipment constitute critical input dependencies. Single-source vulnerability in validated aseptic line qualification creates 18-24 month capacity expansion timelines. Distribution runs through consolidated wholesale tiers in Western markets and direct-to-pharmacy channels in hospital network consolidation zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pharmaceutical elixirs rests on continuous manufacturing cost-down trajectories and premium-tier shift toward outcome-guaranteed pediatric formulations. The cost-down driver is displacing batch production waste with real-time quality assurance.
For Market Incumbents: To counter solid dosage substitution threats from orally disintegrating tablets, anchor pediatric volume through taste-masking technology licensing partnerships and compress development cycles with hot-melt extrusion platforms. Deepen backward integration into active pharmaceutical ingredient supply to defend margin position against Indian contract manufacturing organization pricing. FDA Current Good Manufacturing Practice enforcement favors scaled producers with dedicated quality infrastructure; accelerate facility certification investments to capture regional operator compression. For New Entrants and Emerging Players: Geriatric dysphagia formulations in Japan represent an underserved buyer archetype with PMDA stability guidelines mandating extended shelf-life validation that legacy manufacturers under-resource. White-space targets include orphan indication elixirs enabled by modular continuous manufacturing for smaller batch sizes, and herbal composition regulatory evolution in European natural product channels. The most penetrable segment is compliant tincture distribution migrating from informal markets. A go-to-market angle of Swissmedic certification for premium topical positioning unlocks European pharmacy channel access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian manufacturers with CDSCO export certification but underdeveloped EMA regulatory pathways. Long-term viability framing centers on 5-10 year regulatory divergence between stringent Western markets and emerging economy frameworks, with compliant facility certification as the scarcest capability. Acquisition target archetype: contract research organizations with validated aseptic filling capacity and existing FDA or EMA inspection history. The signal to watch is CDSCO-EMA mutual recognition pathway implementation accelerating market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Taste-Masking Technology Licensing | Partnerships with polymer microencapsulation specialists enable bitter active ingredient formulation for pediatric segments. |
| CDSCO-EMA Mutual Recognition Pathway | Bilateral regulatory cooperation creates accelerated market access for compliant Indian domestic manufacturers. |
| Continuous Manufacturing Scale-Up | Advanced process analytical technology deployment reduces waste and real-time quality assurance costs. |
| Backward Integration into API Supply | Captive active pharmaceutical ingredient production defends margin position against ethanol supply volatility. |
| Direct-to-Pharmacy Distribution | Hospital network consolidation in the United States and Germany enables bypass of traditional wholesale tiers. |
Methodological Framework
Multiple input streams — regulatory filing analysis, trade flow databases, and stakeholder interviews — were reconciled through bottom-up and top-down triangulation. Primary interviews engaged drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across FDA, EMA, and CDSCO jurisdictions. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO manufacturing license databases. Cross-referencing of volume estimates against customs data and GPO contract disclosures anchored precision.
Historical volume trajectories were cross-referenced against expert panel input to construct analytical framework projections across the analysis window. Segmentation dimensions modeled include product type, active ingredient category, therapeutic area, administration route, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth rates applied to base-year estimates. Industry-specific forecast inputs incorporated ethanol commodity cycle patterns and aseptic line qualification timeline data.
Underlying measurement precision varies by segment; syrup and antihistamine categories carry tighter precision than tincture and herbal compositions due to trade data granularity differences. Forecasts reflect documented assumptions regarding regulatory pathway stability and commodity input cost baselines. Material deviation in CDSCO-EMA mutual recognition implementation or biofuel policy shifts affecting ethanol supply warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market