
 Sildenafil Drug Market | 2026-2036
Sildenafil Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Sildenafil Drug Market Analytics
Generic substitution revenue is rewriting margin distribution across the sildenafil value chain. Teva Pharmaceutical Industries leverages vertical integration from active pharmaceutical ingredient synthesis through finished dosage to sustain cost leadership in commoditized tablet markets. Viatris anchors North American distribution through pharmacy benefit manager relationships and controls wholesale channel access. Cipla competes in emerging markets with localized manufacturing and extends its reach through direct-to-pharmacy logistics networks.
Sildenafil citrate, a phosphodiesterase type 5 inhibitor with the molecular formula C22H30N6O4S, functions by enhancing nitric oxide-mediated vasodilation in corpus cavernosum smooth muscle and pulmonary vascular beds. The compound requires stereoselective synthesis followed by salt formation and micronization to achieve pharmacopeial dissolution specifications for oral bioavailability. Tablet formulations dominate commercial volume due to manufacturing scalability and patient familiarity, while pulmonary hypertension applications represent the fastest-expanding clinical segment driven by orphan drug pricing flexibility and pulmonologist prescriber adoption. Retail pharmacy channels capture the largest margin pool through insurance reimbursement mechanics, though online pharmacy distribution is gaining script volume from privacy-sensitive patient cohorts.
FDA bioequivalence protocols under 21 CFR 320 govern abbreviated new drug application approvals and shape product development timelines for generic entrants. EMA centralized procedures and WHO prequalification standards create parallel regulatory pathways that determine market access sequencing across developed and developing economies. India's CDSCO manufacturing facility inspections and BIS quality benchmarks influence export eligibility for domestic API producers. Stakeholders must monitor ANDA approval backlogs, patent litigation settlement terms, and prescriber comfort with generic substitution as determinants of competitive positioning.
Market Dynamics
Generic substitution momentum is compressing originator margins while expanding prescriber access across price-sensitive patient cohorts. FDA bioequivalence standards and EMA centralized review procedures are accelerating approval velocity for abbreviated new drug applications.
Growth Catalysts
- EMA Centralized Procedures:Streamlined marketing authorization across member states reduces regulatory duplication and compresses time-to-revenue for generic entrants targeting European pharmacy networks.
- Pulmonary Hypertension Indication Expansion:Orphan drug pricing flexibility in this clinical segment attracts pulmonologist prescribing volume and diversifies revenue beyond erectile dysfunction applications.
- India API Manufacturing Clusters:Concentrated active pharmaceutical ingredient synthesis capabilities in Hyderabad and Ahmedabad lower input costs and enable backward integration for finished dosage producers.
Market Restraints
- ANDA Approval Backlogs:FDA resource constraints extend abbreviated new drug application review timelines, delaying market entry and compressing effective patent cliff windows for challengers.
- Raw Material Concentration Risk:Sildenafil citrate precursor chemicals depend on concentrated Chinese intermediate suppliers, exposing formulation manufacturers to geopolitical supply disruptions.
- Prescriber Substitution Hesitancy:Physician comfort gaps with generic bioequivalence claims limit automatic substitution rates in cash-pay and high-deductible insurance segments.
Strategic Opportunities
- Direct-to-Pharmacy Logistics Networks:Bypassing wholesale distribution layers captures margin pool compression and enables real-time inventory management for retail pharmacy chains.
- WHO Prequalification Standards:Meeting international procurement eligibility opens institutional purchasing channels in low-income country health systems previously served by originator brands.
- Online Pharmacy Channel Expansion:Privacy-sensitive patient cohorts prefer discrete digital fulfillment, creating script volume migration from brick-and-mortar retail locations.
Industry Challenges
- Stereoselective Synthesis Expertise Gap:Chiral chemistry capability scarcity constrains API quality consistency and batch failure rates for manufacturers lacking specialized workforce.
- Micronization Equipment Capex Intensity:Achieving pharmacopeial dissolution specifications requires capital-intensive particle size reduction infrastructure that fragments manufacturing scale economics.
- Patent Litigation Settlement Complexity:Paragraph IV certification disputes with originator holders create legal cost burdens and unpredictable launch timing for generic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sildenafil Drug Market |
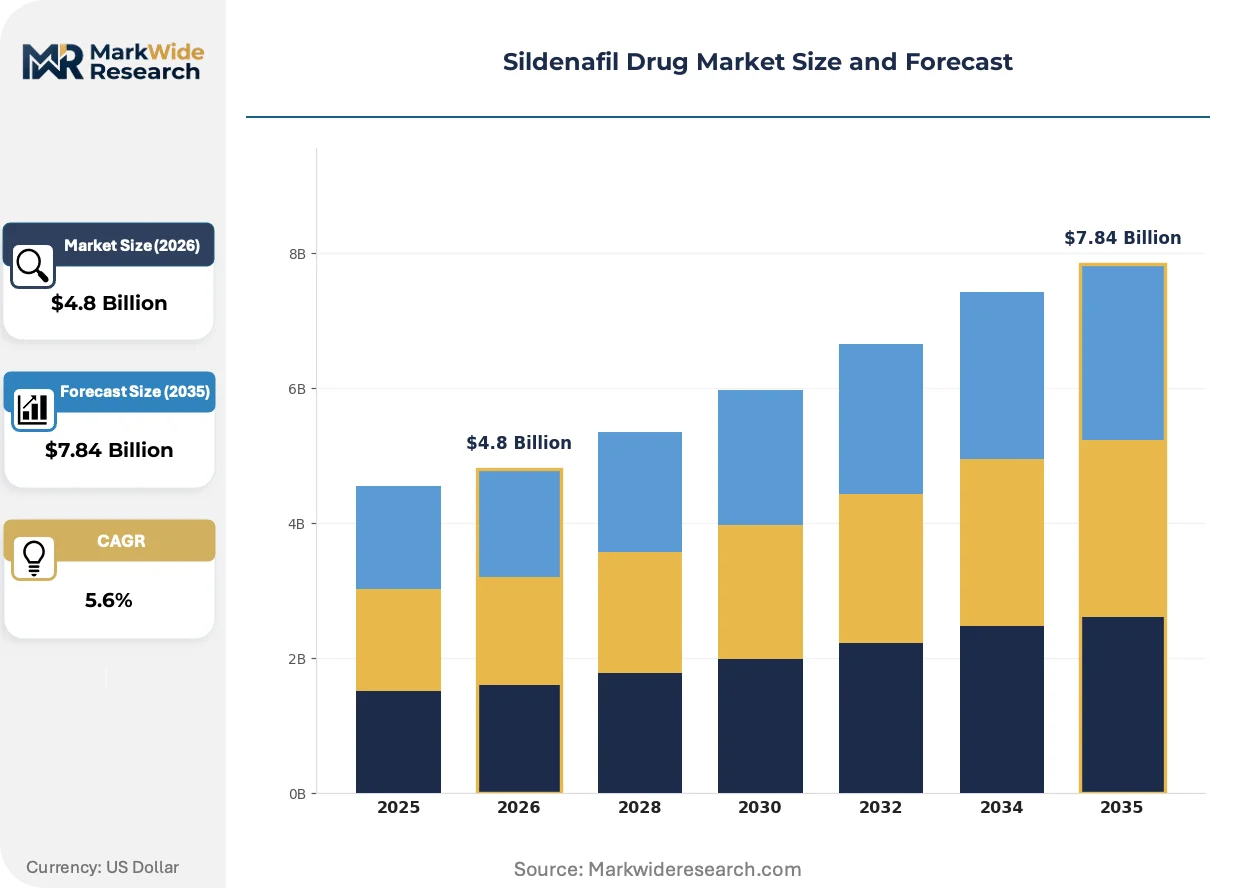
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Oral Suspension, Injection, Topical Application End User: Hospitals, Clinics, Homecare, Retail Pharmacies Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales Application: Erectile Dysfunction, Pulmonary Hypertension, Cardiovascular Disorders, Others |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Viatris Inc., Sun Pharmaceutical Industries Ltd., Cipla Ltd., Lupin Ltd., Dr. Reddy's Laboratories Ltd., Torrent Pharmaceuticals Ltd., Aurobindo Pharma Ltd., Glenmark Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sildenafil Drug Market Evolving Landscape
Continuous manufacturing platforms and real-time release testing are compressing production cycle times while reshaping quality assurance economics. These shifts intersect with regulatory modernization efforts and evolving patient access preferences.
Process analytical technology (PAT) is digitizing sildenafil tablet manufacturing through inline spectroscopic monitoring of blend uniformity and dissolution profiles. Generic manufacturers in India and North America are deploying these systems to reduce offline testing burden and accelerate batch release decisions. This technology compression is enabling smaller-footprint production facilities that challenge traditional scale economies.
FDA's Quality Management Maturity program is elevating cGMP inspection intensity for foreign API facilities supplying the US market. Manufacturers face heightened documentation requirements and supply chain traceability mandates that increase compliance overhead. Indian CDSCO-registered facilities are responding with dedicated quality unit expansion and automated deviation tracking systems.
Subscription-based pharmacy fulfillment models are displacing per-script retail transactions among chronic pulmonary hypertension patients requiring monthly sildenafil refills. Telehealth platforms are capturing initial prescribing encounters and directing volume toward affiliated mail-order pharmacies. This channel pivot is most visible in US markets with high deductible health plan penetration and limited brick-and-mortar pharmacy density.
Sildenafil Drug Market Segmentation
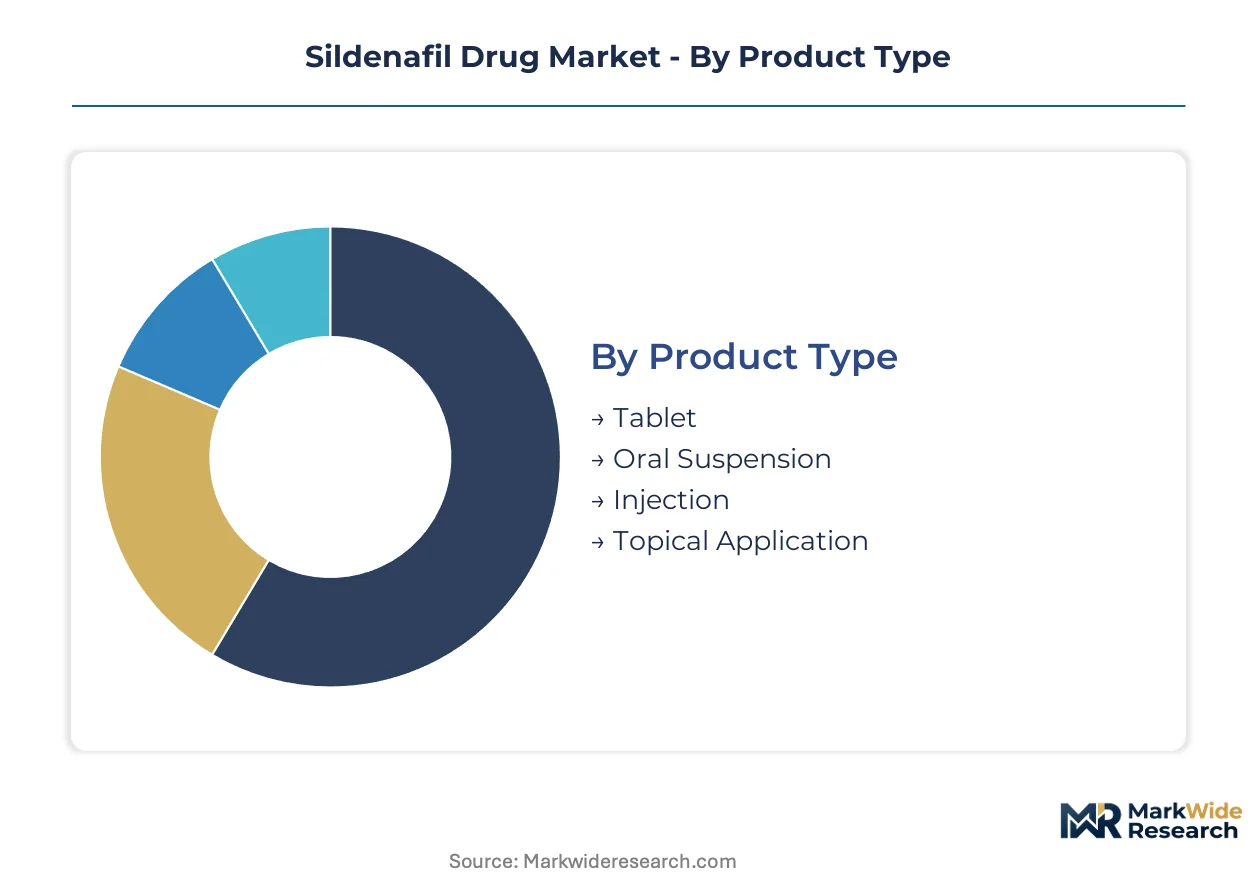
Sildenafil formulation diversity reflects divergent patient compliance profiles and administration settings. Route-specific bioavailability requirements and reimbursement channel access shape manufacturer portfolio decisions across dosage forms.
Product Type:
Cost tier differentiation separates commodity tablet production from specialized delivery systems requiring advanced manufacturing infrastructure.
- Tablet:Compressed sildenafil citrate with standard excipients achieves pharmacopeial dissolution specifications through conventional wet granulation. Retail pharmacy channels in the United States and India concentrate demand for this familiar oral format, though prescriber substitution hesitancy in cash-pay segments constrains automatic dispensing rates.
- Oral Suspension:Micronized API dispersed in aqueous vehicle enables dose titration for pediatric pulmonary hypertension patients and dysphagic adults. Hospital pharmacy procurement in Germany and France drives volume for this flexible administration format, supported by EMA centralized marketing authorizations that streamline multi-national tender eligibility.
- Injection:Parenteral sildenafil for intensive care settings requiring rapid hemodynamic control.
- Topical Application:Transdermal development-stage formats targeting localized vasodilation with reduced systemic exposure.
Tablet commands the established base. The steepest expansion runs through oral suspension as pediatric labeling expands.
End User:
Customer type fragmentation across institutional and ambulatory settings determines pricing flexibility and contract structure.
- Retail Pharmacies:Brick-and-mortar and mail-order dispensaries capture the largest script volume through insurance reimbursement mechanics and patient familiarity. Third-party payer formulary placement in the United States and pharmacy benefit manager rebate structures shape margin distribution, while India's direct-to-pharmacy logistics networks bypass wholesale markups.
- Hospitals:Acute care facilities administer intravenous and high-dose oral formulations for pulmonary hypertension crises. Institutional purchasing consortiums in the United Kingdom and Japan aggregate demand and extract volume-based pricing concessions from manufacturers seeking formulary inclusion.
- Clinics:Outpatient urology and cardiology practices initiate therapy and monitor therapeutic response.
- Homecare:Long-term oxygen therapy providers coordinate chronic pulmonary hypertension medication delivery.
Retail pharmacies anchor volume concentration. The most rapid share gain is occurring in homecare as subscription fulfillment models displace per-script transactions.
Distribution Channel:
Channel selection reflects privacy sensitivity, urgency requirements, and insurance network constraints.
- Online Pharmacy:Digital platforms with discrete packaging and direct-to-patient shipping capture privacy-sensitive erectile dysfunction patients. Telehealth-integrated fulfillment in the United States and United Kingdom accelerates script migration from physical locations, though FDA and MHRA verification requirements for internet pharmacy practice sites filter rogue operators.
- Retail Pharmacy:Community and chain dispensaries maintain dominant position for acute needs and insurance adjudication.
- Hospital Pharmacy:Captive dispensaries serving inpatient and discharge medication needs.
- Direct Sales:Manufacturer-to-institution contracting for large-volume pulmonary hypertension tenders.
Retail pharmacy retains the incumbent position. The sharpest trajectory shift is moving through online pharmacy as digital health integration deepens.
Application:
Clinical indication maturity separates established urology prescribing from expanding pulmonologist adoption.
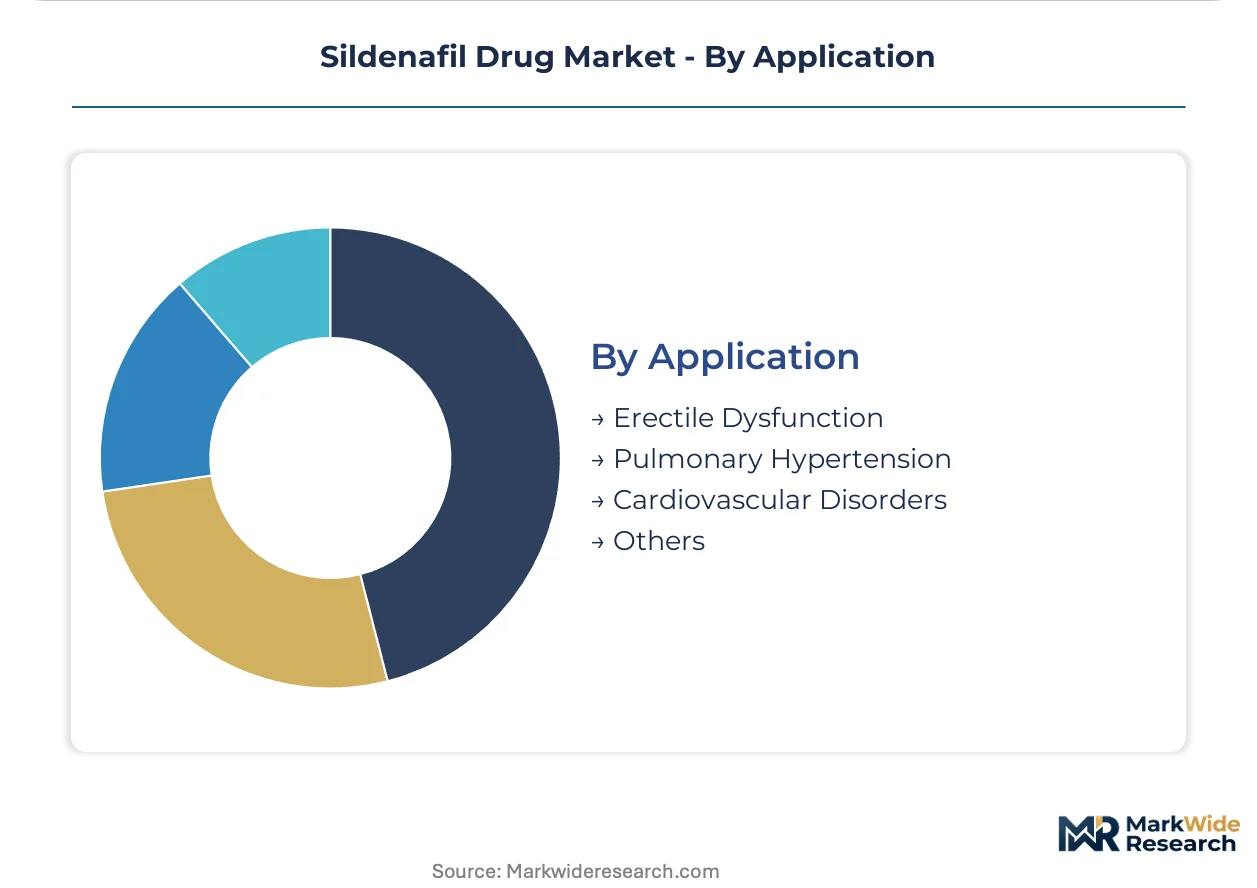
- Erectile Dysfunction:Original approved indication with saturated prescriber awareness and generic commoditization. Primary care and urology practices in the United States, Brazil, and Australia generate stable refill volume, though originator brand loyalty has eroded to single-digit percentages in most developed markets.
- Pulmonary Hypertension:WHO Group 1 arterial and Group 3 pulmonary hypertension represent the fastest-climbing application as orphan drug pricing flexibility attracts manufacturer investment. Pediatric exclusivity extensions and combination therapy protocols with endothelin receptor antagonists expand addressable patient populations in tertiary care centers.
- Cardiovascular Disorders:Investigational and off-label use in heart failure with preserved ejection fraction.
- Others:Raynaud's phenomenon and altitude sickness prophylaxis in niche populations.
Erectile dysfunction holds the volume foundation. Pulmonary hypertension is climbing the fastest as specialty prescriber adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients consume sildenafil primarily through insurance-adjudicated retail channels, while Indian demand concentrates in cash-pay direct-to-pharmacy networks with pronounced generic substitution rates. This divergence in payment mechanics creates fundamentally different margin structures and prescriber access patterns across mature and emerging markets.
United States
Pharmacy benefit manager formulary placement and rebate mechanics dominate US commercial dynamics, with Medicare Part D coverage expanding prescriber access among elderly pulmonary hypertension patients. FDA abbreviated new drug application backlogs periodically delay generic entry timing. New Jersey and North Carolina manufacturing corridors host major finished dosage facilities serving domestic distribution.
India
Hyderabad and Ahmedabad API synthesis clusters supply global generic formulation demand while domestic consumption runs through direct-to-pharmacy logistics bypassing wholesale markups. CDSCO manufacturing facility inspections and BIS quality benchmarks shape export eligibility for domestic producers. Localized production enables price points inaccessible to import-dependent markets.
Germany
Hospital pharmacy procurement consortiums extract volume-based pricing concessions for intravenous and high-dose oral pulmonary hypertension formulations. EMA centralized marketing authorizations streamline multi-national tender eligibility across member states. Bavaria and Baden-Württemberg host specialized hospital networks driving orphan drug prescribing volume.
United Kingdom
NHS England commissioning frameworks and NICE technology appraisals determine formulary inclusion for pulmonary hypertension indications, with generic substitution protocols accelerating once bioequivalence demonstrates. MHRA verification requirements for internet pharmacy practice sites filter rogue online operators. London and Southeast England concentrate specialist pulmonologist prescribing.
Brazil
ANVISA regulatory pathways govern generic entry sequencing while SUS public procurement channels expand access among price-sensitive patient cohorts. São Paulo and Rio de Janeiro anchor private insurance reimbursement mechanics for erectile dysfunction applications. Local manufacturing partnerships with Indian API suppliers reduce import dependency.
Sildenafil Drug Market Competitive Landscape
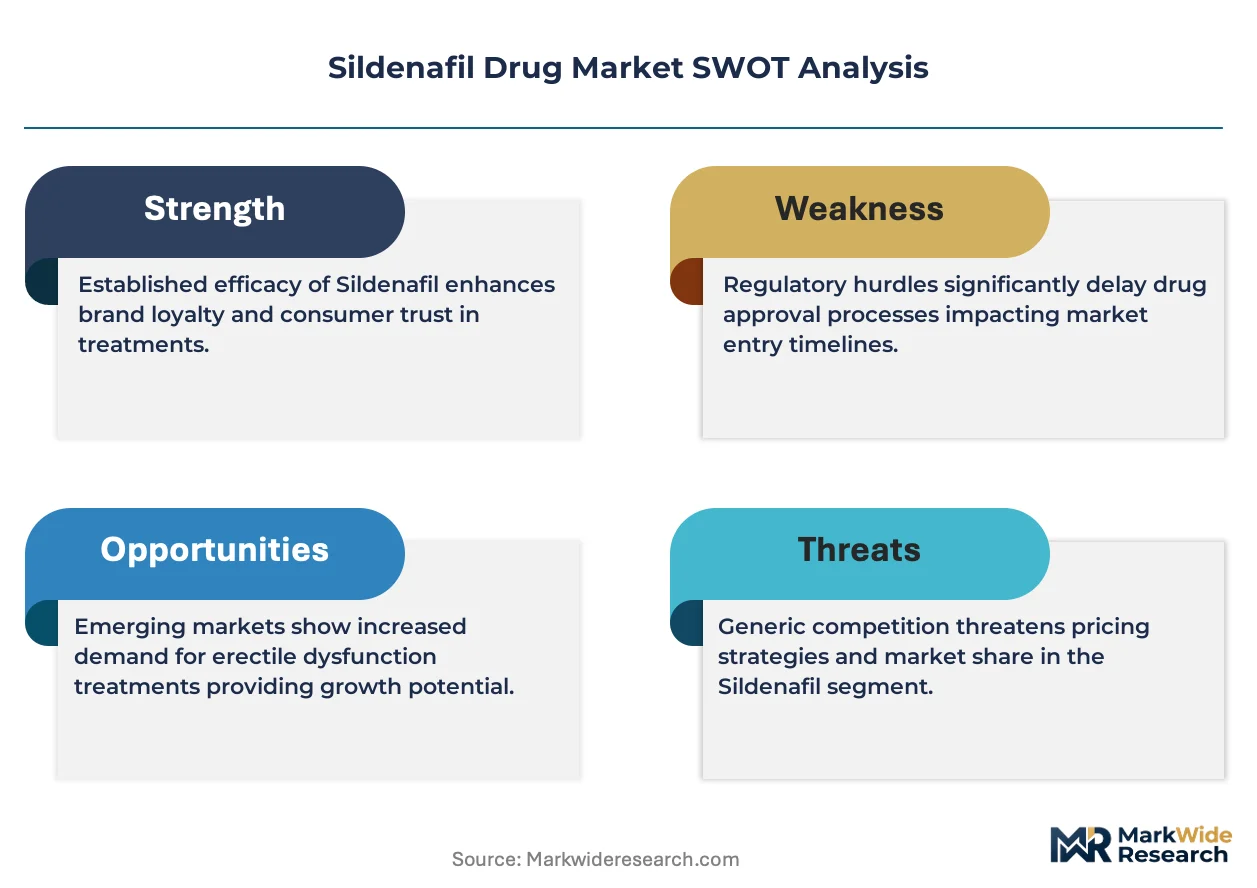
Capability concentration sits with API synthesis specialists commanding stereoselective chemistry expertise; scale advantage sits with finished dosage producers leveraging distribution infrastructure. The market structures around three tiers: vertically integrated pharmaceutical conglomerates, API-forward specialists with backward integration, and formulation-focused generic houses dependent on external active pharmaceutical ingredient supply. Consolidation pressure runs through ANDA approval backlogs compressing effective patent cliff windows, while partnership strategies target direct-to-pharmacy logistics bypassing wholesale layers.
Among Israel-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. exemplifies vertical integration from active pharmaceutical ingredient synthesis through finished dosage production. Viatris Inc. and Cipla Ltd. occupy distinct positions on the geography-specialization matrix, with the former anchoring North American distribution relationships and the latter representing emerging market manufacturing and logistics capabilities. These three entities collectively illustrate the competitive archetypes shaping margin distribution across the value chain.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Ltd. |
| Lupin Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Torrent Pharmaceuticals Ltd. |
| Aurobindo Pharma Ltd. |
| Glenmark Pharmaceuticals Ltd. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Chinese intermediate suppliers for sildenafil citrate precursor chemicals determines both the spread between premium and economy pricing tiers and the geographic shape of active pharmaceutical ingredient sourcing networks. This concentration risk compresses margins for formulation manufacturers while creating arbitrage opportunities for vertically integrated producers with captive synthesis capabilities.
Pricing Analysis
Long-term offtake agreements with pharmacy benefit managers anchor pricing for generic tablet volumes in North American markets, while spot purchasing in Indian cash-pay channels enables sharper price competition. Price differentiation rests on FDA bioequivalence certification tier and geographic delivery cost to retail pharmacy networks. Cost compression in economy-tier tablets is intensifying because of ANDA approval backlogs extending competitive entry timelines. Cash-pay patient segments in emerging markets exhibit highest price sensitivity, whereas insured pulmonary hypertension patients in tertiary care settings show lowest sensitivity due to orphan drug reimbursement mechanics.
Supply Chain Analysis
Upstream feedstock pyrazolopyrimidine intermediates draw from concentrated manufacturing bases in China's Zhejiang and Jiangsu provinces, with final active pharmaceutical ingredient synthesis clustering in Hyderabad and Ahmedabad, India. Key inputs include stereoselective chiral catalysts, micronization-grade excipients, and specialized dissolution testing reagents. Single-source vulnerability in Chinese intermediate supply creates tariff exposure and geopolitical disruption risk for formulation manufacturers lacking backward integration. Distribution runs through direct-to-pharmacy logistics networks in India and wholesale pharmacy channels in the United States, with online pharmacy fulfillment gaining share among privacy-sensitive patient cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic substitution momentum across erectile dysfunction and pulmonary hypertension indications forces incumbents to defend against commoditization while new entrants exploit white-space opportunities in specialized delivery formats and emerging market access.
For Market Incumbents: Pre-empt margin erosion by deepening backward integration into stereoselective API synthesis in Hyderabad manufacturing clusters, and secure pharmacy benefit manager formulary placement through rebate structures that lock out challenger ANDA holders. The priority lever sits with pulmonary hypertension orphan drug pricing flexibility, which sustains premium positioning against erectile dysfunction commoditization. For New Entrants and Emerging Players: Pediatric oral suspension formulations for pulmonary hypertension patients in European hospital pharmacy networks represent the most penetrable entry point, bypassing saturated tablet commoditization. WHO prequalification eligibility for low-income country institutional procurement offers a second white-space channel. Telehealth-integrated online pharmacy fulfillment provides the most efficient go-to-market angle for privacy-sensitive patient acquisition. For Investors and Strategic Acquirers: The market sits at a patent cliff maturation phase that favors API-forward specialists with backward integration capabilities over pure-play formulation houses. Long-term viability over the next decade hinges on regulatory compliance infrastructure and chiral chemistry workforce depth. The signal to watch is FDA Quality Management Maturity program enforcement intensity against Indian CDSCO-registered facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive supply of sildenafil citrate from stereoselective chemistry operations insulates margin compression from Chinese intermediate price volatility. |
| EMA Centralized Marketing Authorization | Streamlined multi-national tender eligibility across European hospital pharmacy procurement consortiums accelerates revenue recognition. |
| Direct-to-Pharmacy Logistics Deployment | Bypassing wholesale distribution layers in Indian retail networks captures margin pool compression and enables real-time inventory management. |
| Pulmonary Hypertension Label Expansion | Orphan drug pricing flexibility in WHO Group 1 arterial indications diversifies revenue beyond erectile dysfunction commoditization. |
| Continuous Manufacturing Platform Investment | Process analytical technology deployment reduces offline testing burden and accelerates batch release decisions for generic tablet production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA ANDA filings, EMA centralized procedure submissions, CDSCO manufacturing facility inspection records, and WHO prequalification status reports. Primary interviews engaged regulatory affairs leads at generic pharmaceutical manufacturers, formulary directors at pharmacy benefit managers, hospital procurement managers in tertiary care pulmonology centers, and API synthesis technical directors in Indian manufacturing clusters. Bottom-up patient volume modeling and top-down value chain margin analysis were cross-validated to establish market size estimates.
Forecast inputs include treatment line positioning across erectile dysfunction and pulmonary hypertension indications, dosage form preference shifts between tablets and oral suspensions, administration route evolution from inpatient injection to ambulatory oral therapy, and regional regulatory cluster dynamics across FDA, EMA, and CDSCO jurisdictions. CAGRs were derived from segment-level volume projections and price trajectory assumptions across the analysis window. Industry-specific inputs incorporate ANDA approval velocity trends and patent litigation settlement pattern analysis.
Practitioners should monitor FDA resource allocation to abbreviated new drug application review timelines, EMA inspection intensity for Indian API facilities, and pulmonologist prescribing adoption curves for pediatric pulmonary hypertension labeling for early signals of forecast revision. Cross-checking against CMS Medicare Part D utilization data and NHS England prescribing analytics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Topical Acne Medication Market