
 Compound Glycyrrhizin Injection Market | 2026-2036
Compound Glycyrrhizin Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Glycyrrhizin Injection Market Insights
Hepatology is repositioning Compound Glycyrrhizin Injection from secondary adjuvant use toward frontline chronic liver disease protocols in China's tier-1 hospitals. Jilin Century Hanke Pharmaceutical leverages deep vertical integration in licorice root extraction to secure raw material cost advantages. Shanxi PUDE Pharmaceutical anchors its position through concentrated hepatology channel relationships in northern provincial hospital networks. Dalian Tianyu Pharmaceutical differentiates via specialized cold-chain distribution capabilities for temperature-sensitive biologic injectables.
Compound Glycyrrhizin Injection comprises a sterile aqueous formulation of glycyrrhizin ammonium salt, typically standardized at 40 mg per 20 mL ampoule, manufactured through alkalinization and lyophilization processes for intravenous administration in hepatic inflammatory conditions. The intravenous delivery mode dominates current volume flows through hospital central pharmacy procurement, while pre-filled cartridge formats are gaining fastest traction in specialized infusion centers seeking reduced compounding error rates. Hepatology therapy area segments capture the deepest margin pools due to longer treatment durations and higher reimbursement tiers, whereas dermatology applications remain comparatively nascent with concentrated trial activity in Guangdong and Shandong provinces.
China's NMPA enforces stringent GMP Annex 1 sterile manufacturing requirements for parenteral products, while the national pharmacopoeia commission periodically revises glycyrrhizin purity thresholds that directly filter qualified suppliers. Provincial centralized procurement consortiums in Shandong and Jiangsu layer additional tender specifications on production batch documentation and stability testing protocols. Stakeholders must monitor NMPA's evolving biologics classification deliberations for plant-derived injectables, as reclassification would trigger substantially different clinical trial and registration cost structures.
Market Dynamics
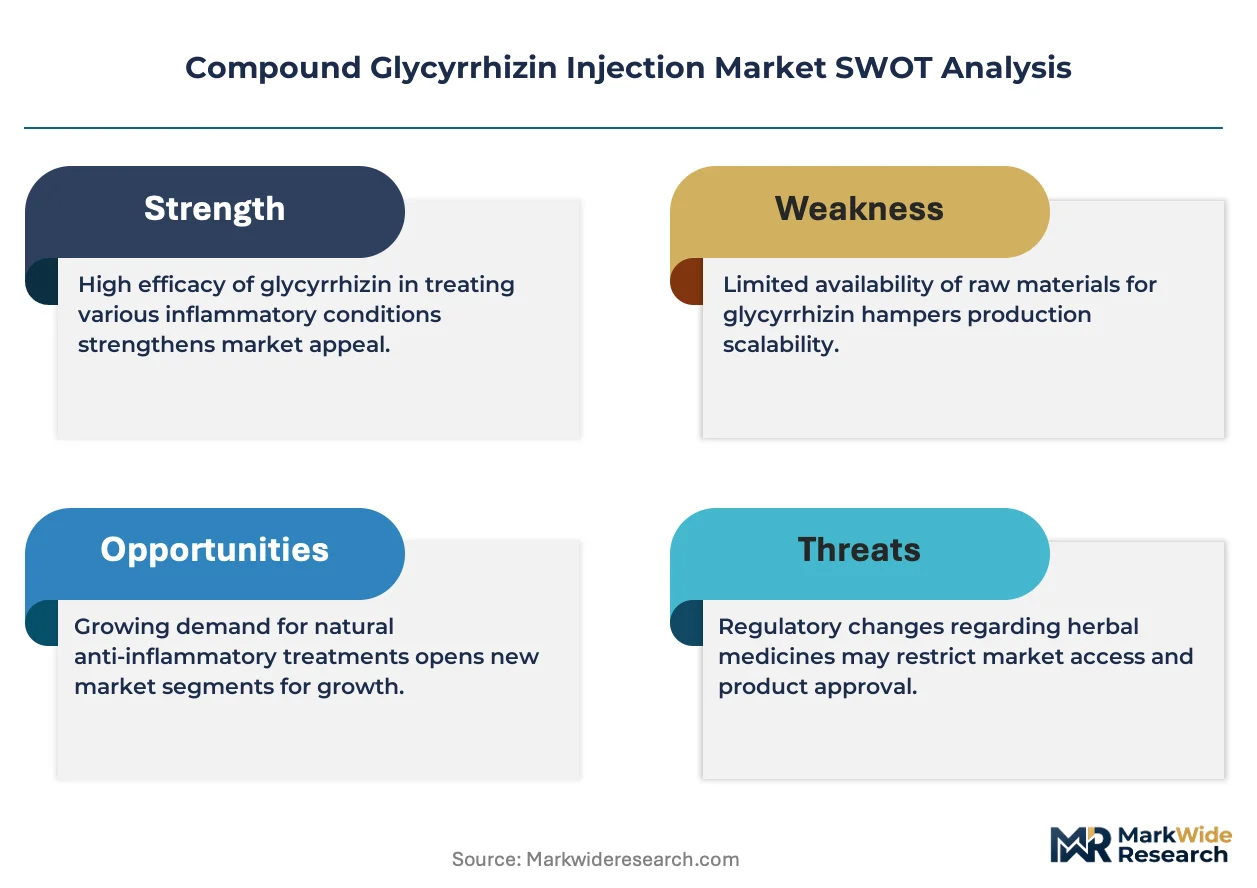
China's NMPA enforcement of revised GMP Annex 1 sterile manufacturing standards is compressing the supplier base for parenteral glycyrrhizin formulations, forcing hepatology procurement officers to recertify vendor qualifications and consolidate purchase orders toward vertically integrated domestic manufacturers.
Growth Catalysts
- Chronic Hepatitis B Prevalence:China's high disease burden sustains inpatient demand for anti-inflammatory liver therapies in tertiary hospital hepatology wards, with treatment protocols extending average therapy durations.
- NMPA GMP Annex 1 Compliance:Stricter sterile manufacturing audits accelerate manufacturer consolidation, filtering qualified suppliers and reducing price competition among remaining certified producers.
- Lyophilization Process Advances:Improved freeze-drying technologies enhance glycyrrhizin stability profiles, enabling extended shelf lives that reduce hospital pharmacy wastage rates.
Market Restraints
- Licorice Root Supply Concentration:Raw material sourcing clusters in Inner Mongolia and Xinjiang create geographic concentration risk for extractors dependent on regional agricultural yields.
- Intravenous Administration Limitations:Hospital-based infusion requirements restrict patient access compared to oral hepatoprotective alternatives, capping outpatient market expansion.
- Reimbursement Tier Compression:Provincial centralized procurement consortiums in Jiangsu and Shandong impose price ceilings that squeeze margin pools for non-integrated manufacturers.
Strategic Opportunities
- Pre-filled Cartridge Formats:Specialized infusion centers in Guangdong province are adopting ready-to-administer delivery systems to reduce compounding errors and nursing labor costs.
- Dermatology Adjunct Applications:Trial activity for licorice-derived anti-inflammatory therapy in Guangdong and Shandong creates potential indication expansion beyond hepatology.
- Dual Carbon Policy Alignment:China's national decarbonization mandates incentivize green chemistry investments in plant extraction processes, favoring domestic suppliers with certified sustainable sourcing.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:NMPA's elevated audit standards create acute shortages of qualified aseptic process engineers and quality assurance specialists.
- Cold-Chain Infrastructure Capex:Temperature-sensitive biologic injectables require specialized logistics networks that demand substantial capital deployment for regional distribution coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Glycyrrhizin Injection Market |
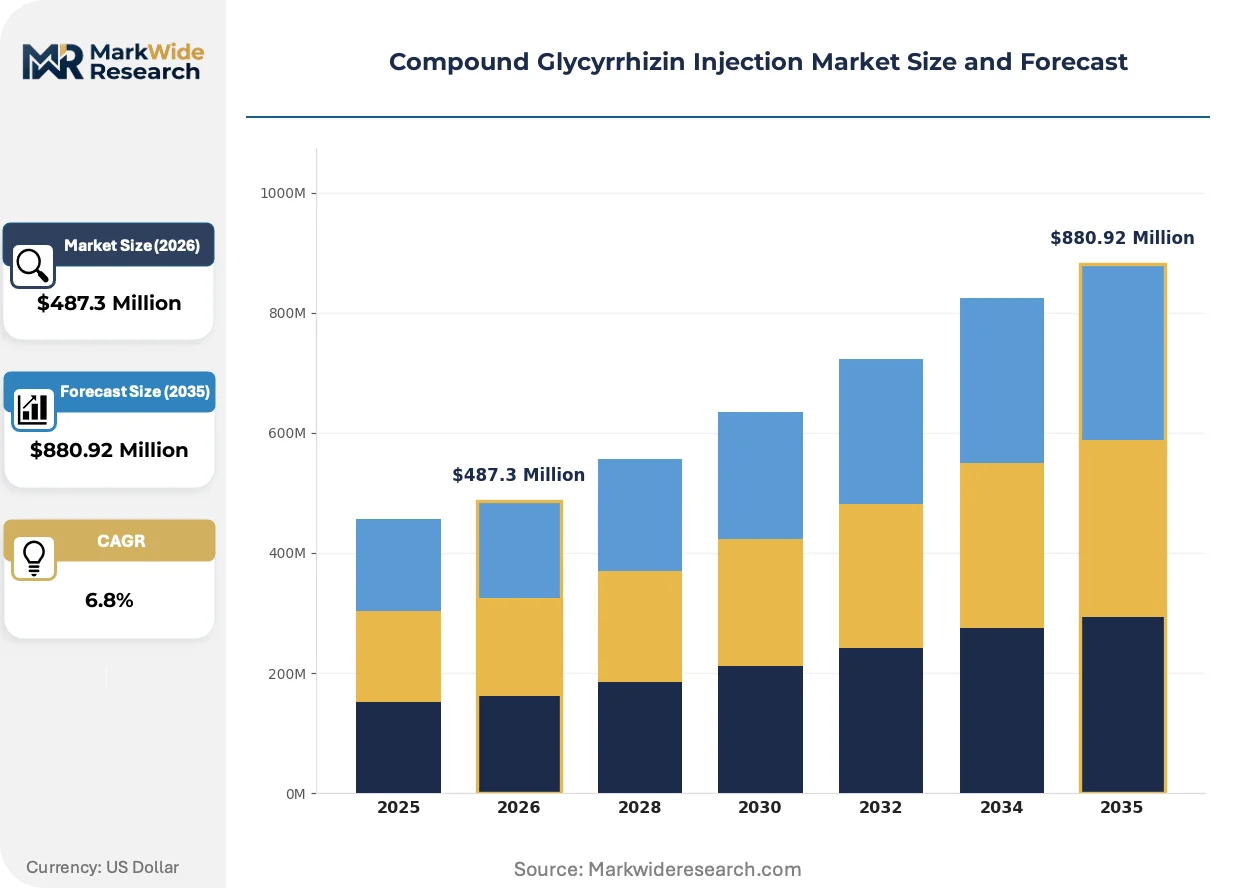
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Subcutaneous, Intramuscular, Oral Therapy Area: Hepatology, Dermatology, Immunology, Oncology End User: Hospitals, Clinics, Home Care, Specialized Centers Delivery Mode: Syringe, Vial, Ampoule, Pre-filled Cartridge |
| Companies Covered | Jilin Century Hanke Pharmaceutical, Jilin Connell Pharmaceutical, Shanxi PUDE Pharmaceutical, Hainan Weikang Pharmaceutical, Dalian Tianyu Pharmaceutical, Dezhou Deyao Pharmaceutical, Qingdao Jinfeng Pharmaceutical, Shaanxi Jingxi Pharmaceutical, Shandong Wego Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Glycyrrhizin Injection Market Trends and Innovations
Formulation science and regulatory technology are converging to reshape how hepatology departments source and administer parenteral glycyrrhizin therapies, with automation and quality verification systems commanding fresh investment priority.
Pre-filled syringe and cartridge delivery systems are electrifying hospital pharmacy workflows by eliminating manual compounding steps. Tertiary hepatology departments in Shanghai and Jiangsu are adopting these formats fastest, with procurement officers citing reduced medication error rates and nursing time savings. The technology is compressing traditional ampoule-based supply contracts and forcing manufacturers to retool filling lines.
NMPA's phased implementation of electronic batch record systems and real-time release testing protocols is tightening documentation requirements for sterile injectables. Domestic manufacturers must now deploy process analytical technology to demonstrate continuous quality verification. Medium-scale producers in northern provincial clusters are responding by partnering with automation vendors or exiting the category entirely.
Centralized procurement consortiums are consolidating purchasing power across hospital networks, displacing fragmented hospital-by-hospital tender processes. Shandong and Jiangsu provincial health commissions now negotiate annual volume contracts that bundle glycyrrhizin injection with complementary hepatology therapies. This concentration is most visible in East China, where tier-1 hospital clusters coordinate procurement timing to maximize volume leverage.
Compound Glycyrrhizin Injection Market Segmentation
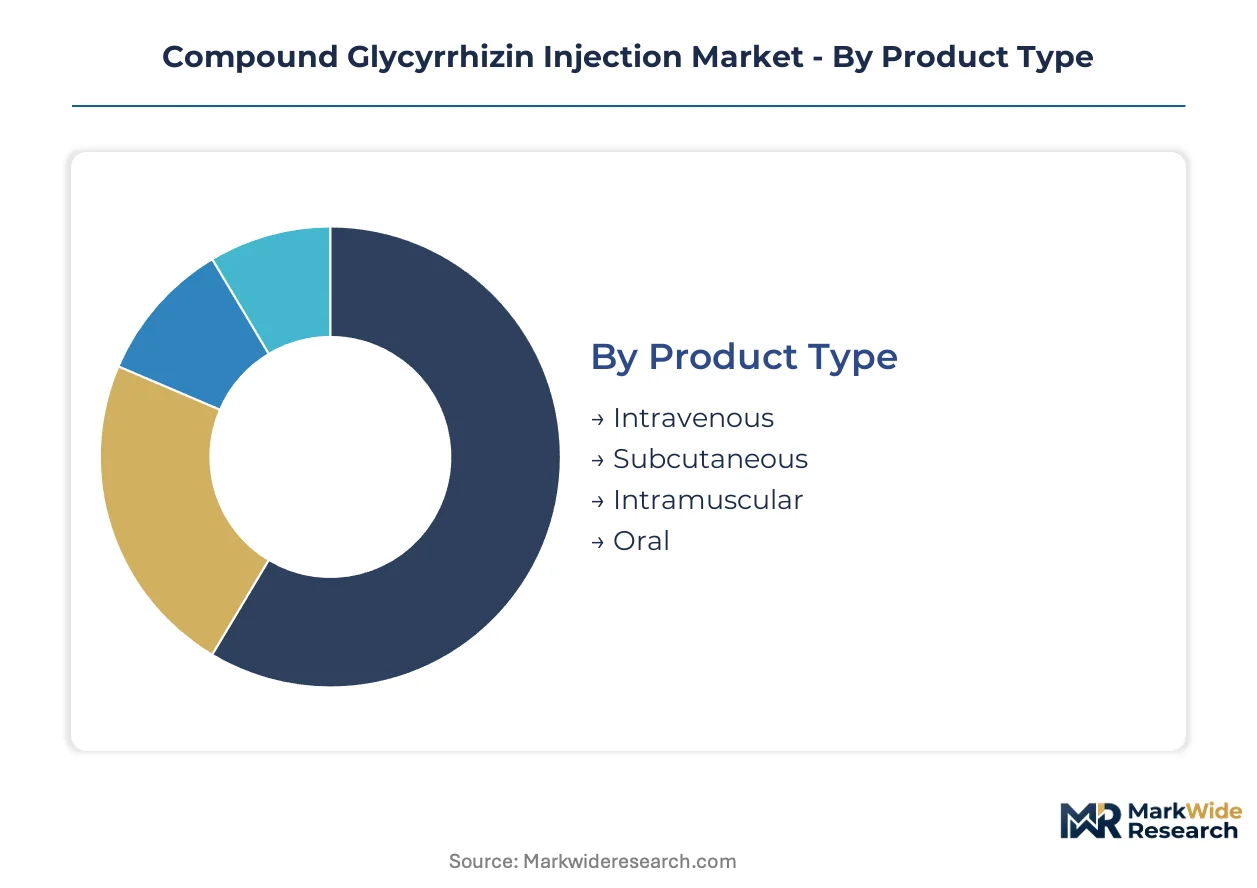
Compound Glycyrrhizin Injection procurement patterns diverge sharply across administration routes, therapeutic applications, and institutional settings. Hospital pharmacy committees evaluate segments through distinct lenses of reimbursement eligibility, compounding complexity, and patient throughput economics.
Product Type:
Route selection determines reimbursement tier, nursing labor allocation, and patient eligibility criteria across China's hospital networks.
- Intravenous:Sterile aqueous glycyrrhizin ammonium salt delivered through central venous access or peripheral infusion dominates tertiary hospital hepatology wards. Shanghai and Jiangsu provincial procurement consortiums channel the majority of volume through this route due to established reimbursement codes for chronic hepatitis B inpatient protocols.
- Subcutaneous:Emerging delivery route for outpatient hepatology programs seeking to reduce central pharmacy bottlenecks. Guangdong specialty clinics are piloting subcutaneous protocols to extend therapy beyond traditional infusion center footprints.
- Intramuscular:Restricted to dermatology applications and short-course immunomodulatory protocols where rapid systemic absorption is less critical.
- Oral:Non-injectable glycyrrhizin formulations compete at the margin of this market category, capturing patients who fail intravenous access criteria or refuse parenteral therapy.
Intravenous leads volumes today; subcutaneous is gaining share fastest.
Therapy Area:
Margin pools and treatment duration economics separate therapeutic applications.
- Hepatology:Chronic hepatitis B and drug-induced liver injury protocols generate extended treatment courses with the deepest reimbursement tiers. East China's tier-1 hospital clusters anchor demand concentration here.
- Dermatology:Licorice-derived anti-inflammatory therapy for eczema and psoriasis is expanding through trial activity concentrated in Guangdong and Shandong provinces.
- Immunology:Adjunct applications in autoimmune modulation remain exploratory with limited protocol adoption outside academic medical centers.
- Oncology:Hepatoprotective co-administration during chemotherapy cycles captures niche volume in comprehensive cancer centers.
Hepatology commands revenue concentration; dermatology climbs the fastest.
End User:
Institutional scale and procurement authority reshape competitive access.
- Hospitals:Tertiary hepatology departments in Shanghai, Jiangsu, and Zhejiang drive procurement volume through centralized pharmacy tender processes.
- Clinics:Secondary urban clinics in provincial capitals are adopting pre-filled formats to bypass compounding infrastructure requirements.
- Home Care:Limited penetration due to cold-chain logistics constraints and infusion supervision requirements.
- Specialized Centers:Guangdong infusion centers are standardizing pre-filled cartridge workflows to minimize medication errors.
Hospitals dominate procurement value; specialized centers are expanding most quickly.
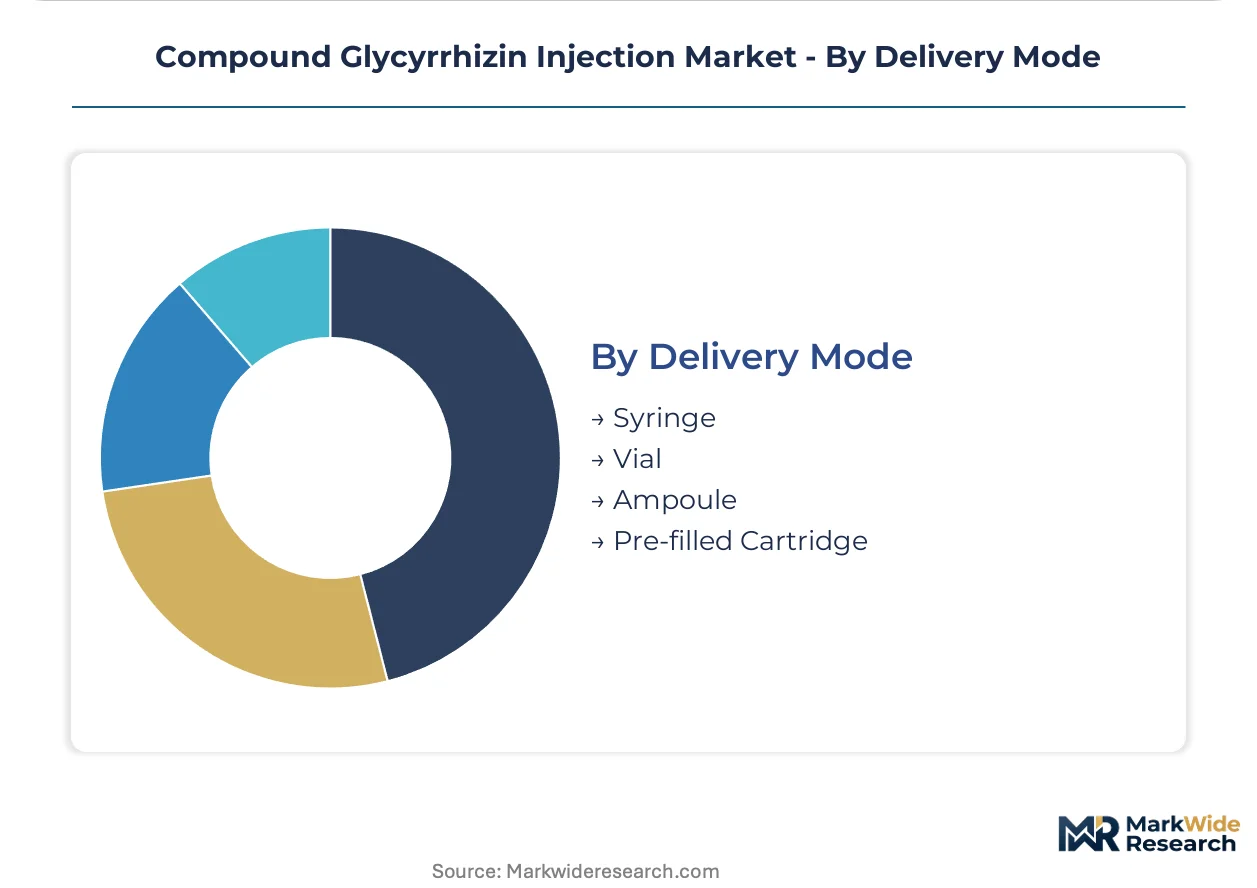
Delivery Mode:
Packaging format selection reflects automation priorities and error reduction mandates.
- Syringe:Conventional disposable syringes remain prevalent in cost-sensitive procurement tiers.
- Vial:Multi-dose glass vials serve high-throughput hepatology wards with dedicated compounding pharmacy support.
- Ampoule:Single-dose glass ampoules at 40 mg per 20 mL represent the legacy standard now facing displacement.
- Pre-filled Cartridge:Ready-to-administer systems eliminate manual compounding steps. Shanghai and Jiangsu tertiary hospitals are adopting these formats fastest to reduce nursing labor and error rates.
Ampoule formats lead installed base; pre-filled cartridge shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redistributing Compound Glycyrrhizin Injection production capacity across East Asia, with manufacturers migrating toward jurisdictions offering streamlined sterile manufacturing certification pathways.
China
Chronic hepatitis B prevalence drives inpatient demand through Shanghai and Jiangsu hospital clusters. NMPA's revised GMP Annex 1 standards filter qualified suppliers and compress the vendor base. The Yangtze River Delta anchors production concentration, with tertiary hepatology wards in Zhejiang standardizing pre-filled cartridge procurement.
Japan
PMDA's stringent biologics classification deliberations for plant-derived injectables create regulatory uncertainty for market entrants. METI's pharmaceutical manufacturing incentives support domestic lyophilization capacity investments. The Kansai region's Osaka-based formulation specialists supply academic medical centers with high-purity hepatoprotective therapies.
South Korea
MFDS enforcement of sterile manufacturing documentation requirements shapes import approval timelines for Chinese-origin glycyrrhizin formulations. Seoul Capital Area hospital networks source through centralized procurement consortiums. Busan-Ulsan's cold-chain logistics hubs facilitate temperature-sensitive biologic distribution throughout the peninsula.
India
CDSCO's injectable quality standards for imported parenteral products create compliance barriers for non-integrated manufacturers. Maharashtra's Mumbai-Pune pharmaceutical corridor hosts formulation development activity for hepatoprotective adjuvants. Gujarat's Ahmedabad cluster specializes in plant extraction processes for licorice-derived active pharmaceutical ingredients.
Compound Glycyrrhizin Injection Market Competitive Landscape
Capacity expansion dominates the current landscape as NMPA compliance costs force manufacturer consolidation. The vendor base compresses toward vertically integrated domestic producers with captive licorice root supply chains. Three archetypes define competitive positioning: state-affiliated pharmaceutical groups with preferential hospital access, privately held extraction-to-injection specialists, and regional distributors building cold-chain capabilities. Strategic partnerships and backward integration into raw material sourcing represent the dominant competitive moves.
Among Chinese pharmaceutical manufacturers, Jilin Century Hanke Pharmaceutical, Shanxi PUDE Pharmaceutical, and Dalian Tianyu Pharmaceutical occupy distinct positioning within the consolidated supplier tier. Jilin Century Hanke exemplifies the vertically integrated archetype through upstream control over licorice root extraction. Shanxi PUDE anchors northern provincial hospital network relationships. Dalian Tianyu represents specialized cold-chain distribution capabilities for temperature-sensitive biologic injectables.
| Leading Market Players |
|---|
| Jilin Century Hanke Pharmaceutical |
| Jilin Connell Pharmaceutical |
| Shanxi PUDE Pharmaceutical |
| Hainan Weikang Pharmaceutical |
| Dalian Tianyu Pharmaceutical |
| Dezhou Deyao Pharmaceutical |
| Qingdao Jinfeng Pharmaceutical |
| Shaanxi Jingxi Pharmaceutical |
| Shandong Wego Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Lyophilization process standardization across NMPA-certified facilities is compressing unit economics while simultaneously filtering production capacity toward vertically integrated domestic manufacturers with captive licorice root processing capabilities. This technological convergence creates asymmetric pricing power between extraction-to-injection specialists and formulation-dependent competitors.
Pricing Analysis
Provincial tender margins absorb the primary compression from centralized procurement consortiums in Jiangsu and Shandong. Three-tier pricing structure across premium, standard, and economy levels separates NMPA Annex 1-certified producers from regional formulators and import-reliant distributors. Pricing pressure stems from volume-based tender aggregation that rewards scale over brand premium. Standard-tier procurement officers exhibit highest price sensitivity; tertiary hepatology departments with established GMP relationships show lowest.
Supply Chain Analysis
Aseptic process engineer scarcity in northern provincial manufacturing clusters constrains capacity expansion timelines for sterile injectable producers. Raw material sourcing draws from Inner Mongolia and Xinjiang licorice cultivation zones, with alkalinization reagents and lyophilization equipment anchored in Yangtze River Delta industrial corridors. Single-source vulnerability concentrates in regional agricultural yield fluctuations. Distribution runs through hospital central pharmacy procurement networks with cold-chain logistics partnerships for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound Glycyrrhizin Injection represents a late-cycle quality story as hepatology departments shift procurement toward pre-filled cartridge formats with documented error-reduction profiles and extended stability specifications.
For Market Incumbents: Hedge against NMPA biologics reclassification risk by accelerating electronic batch record system deployment and securing dual-source lyophilization capacity. Prioritize backward integration into licorice root cultivation in Inner Mongolia to insulate margin structures from agricultural commodity volatility. Reinforce hospital pharmacy committee relationships through real-time release testing documentation. For New Entrants and Emerging Players: The premium-economy price-point gap in dermatology applications offers white-space access with lower certification barriers than hepatology's entrenched reimbursement codes. Target Guangdong and Shandong specialty infusion centers with pre-filled cartridge formulations. Pursue partnership routes with established cold-chain distributors rather than infrastructure buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators lacking captive extraction capacity but holding valid NMPA Annex 1 certifications. Long-term viability favors acquisition targets with demonstrated sterile manufacturing talent retention and provincial tender track records. Monitor PMDA biologics classification deliberations as inflection signal for plant-derived injectable regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | NMPA Annex 1 compliance filters qualified suppliers toward freeze-drying specialists with validated stability protocols. |
| Backward Integration into Licorice Cultivation | Inner Mongolia agricultural partnerships secure raw material cost advantages against volatile regional yields. |
| Pre-filled Cartridge Format Development | Shanghai and Jiangsu tertiary hospitals prioritize ready-to-administer systems for nursing labor reduction. |
| Electronic Batch Record Implementation | Real-time release testing documentation satisfies provincial tender specifications for continuous quality verification. |
| Dermatology Indication Expansion | Guangdong and Shandong trial activity creates pipeline diversification beyond hepatology reimbursement dependence. |
Research Methodology
Direct dialogue with hepatology department procurement officers, NMPA regulatory affairs specialists, sterile manufacturing quality directors, and hospital pharmacy committee members grounded qualitative insights. Secondary validation drew from NMPA GMP inspection databases, provincial centralized procurement tender announcements, pharmacopoeia commission purity standard revisions, and customs import records for lyophilization equipment. Bottom-up volume estimates triangulated against top-down therapeutic area expenditure models.
Bottom-up modeling segmented demand across administration routes, therapy areas, and institutional settings, then aggregated through hospital procurement database analysis. Top-down approaches calibrated against national hepatitis B prevalence statistics and hepatology ward capacity expansion plans across the analysis window. CAGRs derived from volume trajectory convergence between patient flow projections and manufacturing capacity expansion timelines, with lyophilization batch yield improvements and cold-chain infrastructure deployment as key forecast inputs.
Caveats apply where NMPA biologics reclassification, provincial tender price ceiling adjustments, or licorice root agricultural yield shocks could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Oral Vaccines Market