
 India Medical Devices Market | 2026-2036
India Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Medical Devices Market Insights
Asset-light leasing and rental models for high-end diagnostic equipment is narrowing the capital barrier for mid-size hospital chains across India. GE Healthcare leverages its installed base of imaging systems to sustain service revenue streams in tier-II cities. Siemens Healthineers anchors its position through localized manufacturing of CT and MRI components under the PLI scheme. Medtronic competes by specializing in cardiac rhythm and vascular device portfolios tailored to Indian patient demographics.
Medical devices encompass instruments, apparatus, implants, and in vitro reagents that diagnose, prevent, monitor, or treat medical conditions through physical or mechanical action rather than pharmacological means. These products range from simple surgical steel instruments to complex programmable pacemakers, with sterility assurance levels and biocompatibility standards governing material selection and manufacturing processes. Diagnostic Equipment occupies the largest revenue pool as hospitals prioritize imaging modalities for early disease detection, while Wearable Devices represents the fastest-expanding technology segment as remote patient monitoring gains clinical acceptance. Robotics in surgical applications commands premium pricing and attracts targeted R&D investment from domestic and multinational firms alike.
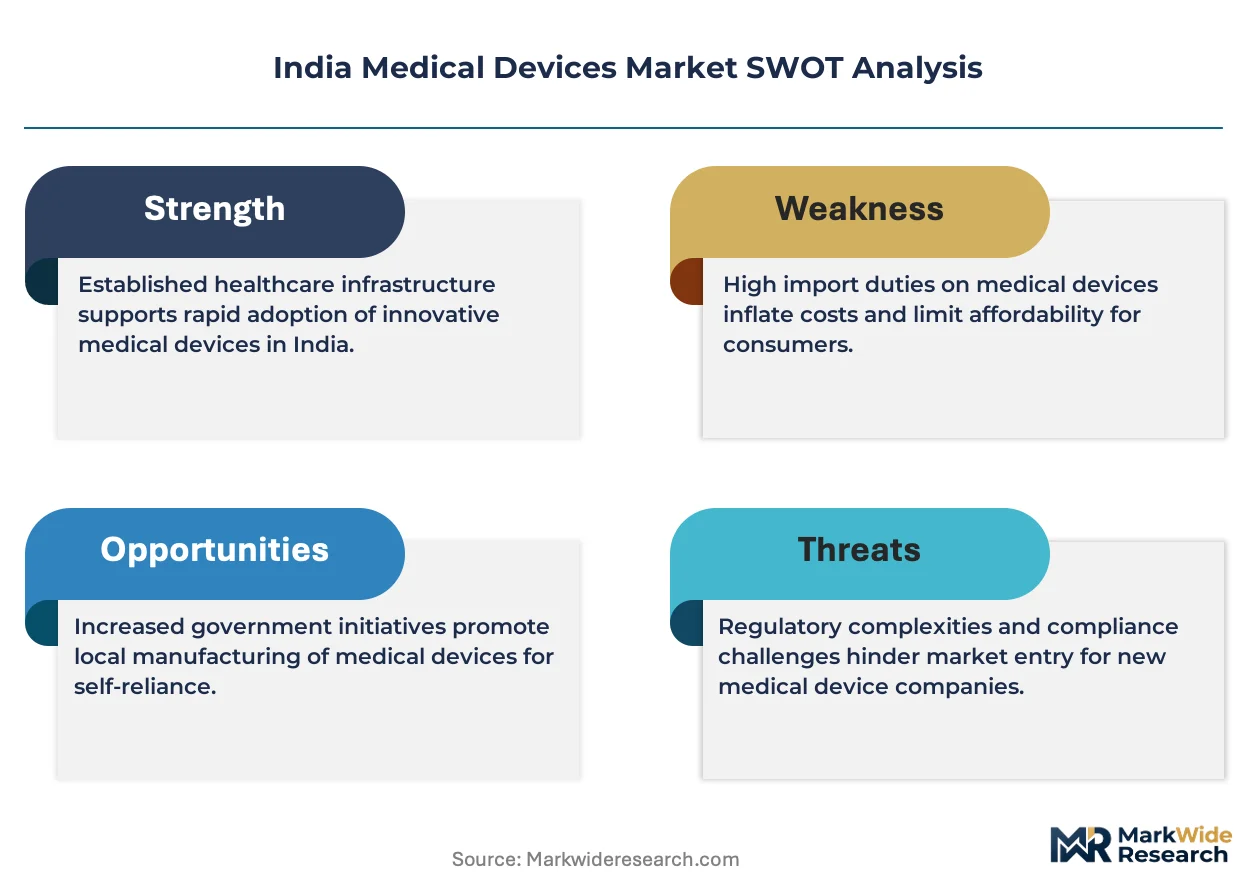
CDSCO mandates registration and quality certification for all imported and domestically manufactured medical devices under the Medical Devices Rules, while BIS standards govern electrical safety and electromagnetic compatibility for active devices. The PLI scheme administered by the Department of Pharmaceuticals redirects procurement incentives toward domestic production, reshaping supply chain decisions for hospital buyers. Stakeholders must monitor how CDSCO's risk-based classification system and forthcoming quality management system requirements alter market access timelines and compliance costs for new entrants.
Market Dynamics
The PLI scheme administered by India's Department of Pharmaceuticals is redirecting procurement incentives toward domestic manufacturing, reshaping supply chain decisions for hospital buyers and accelerating localization of high-value imaging and cardiac device production.
Growth Catalysts
- Domestic Manufacturing Incentives:The PLI scheme offers tiered production-linked incentives that reduce landed cost disadvantages for locally manufactured CT, MRI, and cath-lab equipment. Tier-II hospital chains are expanding procurement from domestic contract manufacturers.
- Diagnostic Imaging Expansion:Maharashtra, Karnataka, and Telangana are witnessing concentrated hospital infrastructure buildouts where specialty chains prioritize imaging modality procurement for early disease detection protocols.
- Remote Patient Monitoring:Wearable biosensors and connected monitoring devices are gaining clinical acceptance in post-operative care and chronic disease management, creating pull-through demand for integrated hospital IT systems.
Market Restraints
- Import Dependency for Core Components:High-field MRI magnets, CT detector arrays, and semiconductor-based sensor modules remain concentrated among suppliers in Germany, Japan, and the United States, exposing domestic assemblers to currency volatility and shipping disruptions.
- CDSCO Registration Timelines:Risk-based classification requirements and quality management system audits extend market access timelines for novel device categories, particularly Class C and D implantables requiring clinical investigation reports.
- Capital Intensity of Imaging Systems:MRI and PET-CT installations require specialized shielding, cryogen infrastructure, and HVAC specifications that inflate total cost of ownership beyond equipment purchase price alone.
Strategic Opportunities
- Tier-III City Penetration:District hospitals and nursing homes in Uttar Pradesh, Bihar, and Madhya Pradesh remain underserved for advanced dialysis, ventilator, and anesthesia machine access, creating whitespace for rental and refurbished equipment channels.
- Regulatory Harmonization:CDSCO's alignment with IMDRF technical documentation standards is streamlining parallel registration pathways for manufacturers holding FDA or CE certificates, compressing time-to-market for multinational portfolios.
- AI-Enabled Diagnostics:Machine learning algorithms for radiology workflow optimization and pathology image analysis are hybridizing with installed imaging bases, creating software-as-a-service revenue streams independent of hardware replacement cycles.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hospital technology management departments face acute shortages of trained professionals capable of preventive maintenance and calibration for multi-vendor imaging fleets, forcing reliance on OEM service contracts.
- Legacy System Integration:New digital health devices must interface with fragmented hospital information systems and non-standardized electronic medical record platforms, complicating deployment and data interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Medical Devices Market |
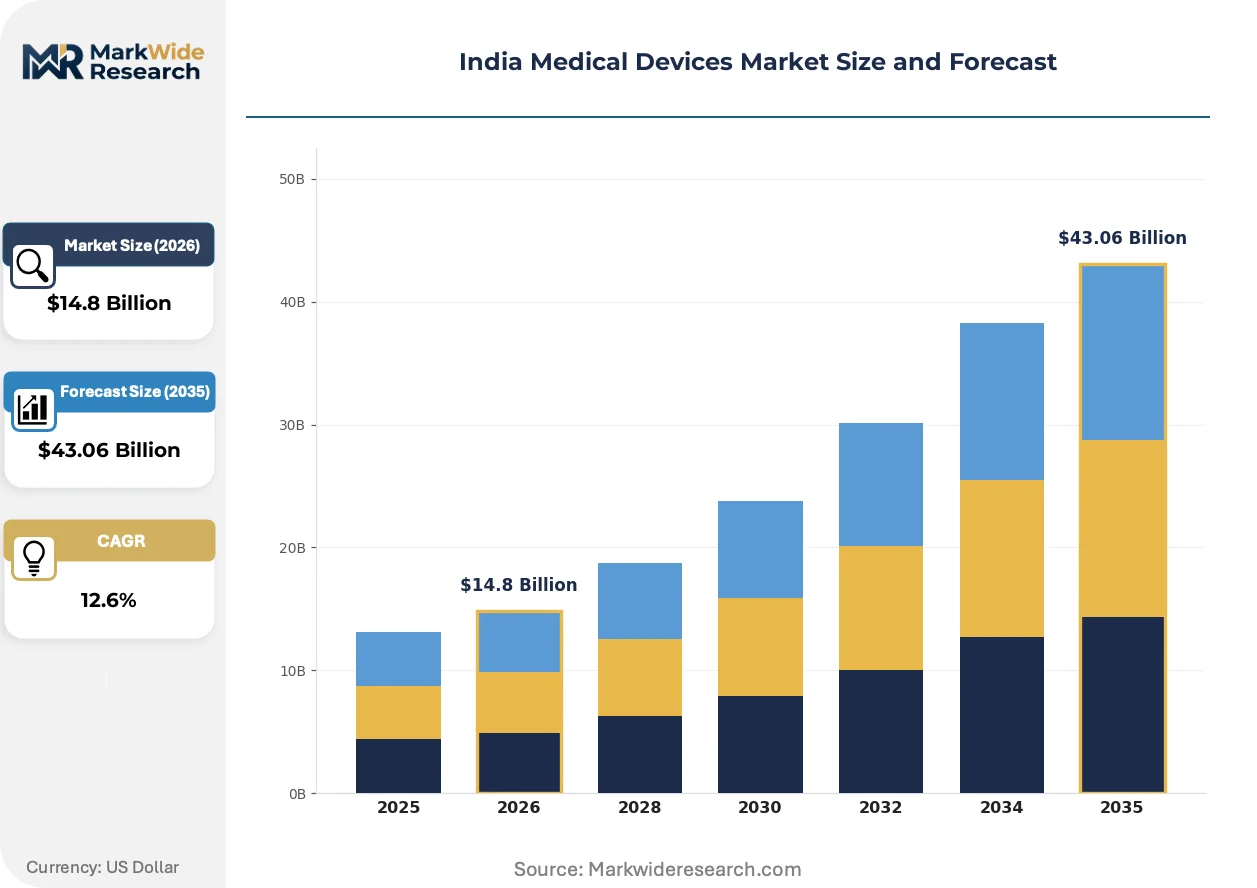
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Patient Monitoring Devices, Implants End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Wearable Devices, Imaging Technology, Robotics, Telemedicine Application: Cardiology, Orthopedics, Neurology, Urology |
| Companies Covered | Abbott Laboratories, GE Healthcare, Koninklijke Philips, Medtronic, Siemens Healthineers, Meril, Trivitron, BPL Medical, Molbio Diagnostics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Medical Devices Market Trends and Innovations
Digital connectivity and artificial intelligence are embedding intelligence into physical devices, transforming standalone instruments into networked care delivery nodes that generate recurring revenue through software and service attachments.
Point-of-care ultrasound systems are hybridizing with tablet-based interfaces and cloud-based image storage, enabling deployment in ambulatory settings and emergency departments where full radiology infrastructure is unavailable. Cardiology and obstetrics departments in corporate hospital chains are adopting these compact systems at twice the pace of conventional cart-based machines. This convergence is compressing the addressable market for basic radiology rooms while expanding diagnostic access to previously unreachable clinical environments.
CDSCO's phased implementation of quality management system requirements under the Medical Devices Rules is mandating ISO 13485 certification for all Class B through D device manufacturers and importers by specified deadlines. Domestic contract manufacturers are upgrading cleanroom facilities and documentation protocols to meet these standards, while multinational firms are accelerating transfer of technical files to Indian regulatory affiliates. The implantable cardiac device segment faces the steepest compliance cost escalation due to mandatory adverse event reporting and post-market surveillance obligations.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchase agreements, negotiating separate multi-vendor maintenance arrangements with third-party biomedical engineering firms. This disintermediation of OEM service revenue is most pronounced among mid-size hospital chains in Gujarat and Tamil Nadu that operate mixed fleets of GE, Siemens, and Philips imaging systems. Equipment financiers are responding with bundled lease offerings that explicitly exclude service components, forcing manufacturers to compete for maintenance contracts on standalone merit.
India Medical Devices Market Segmentation
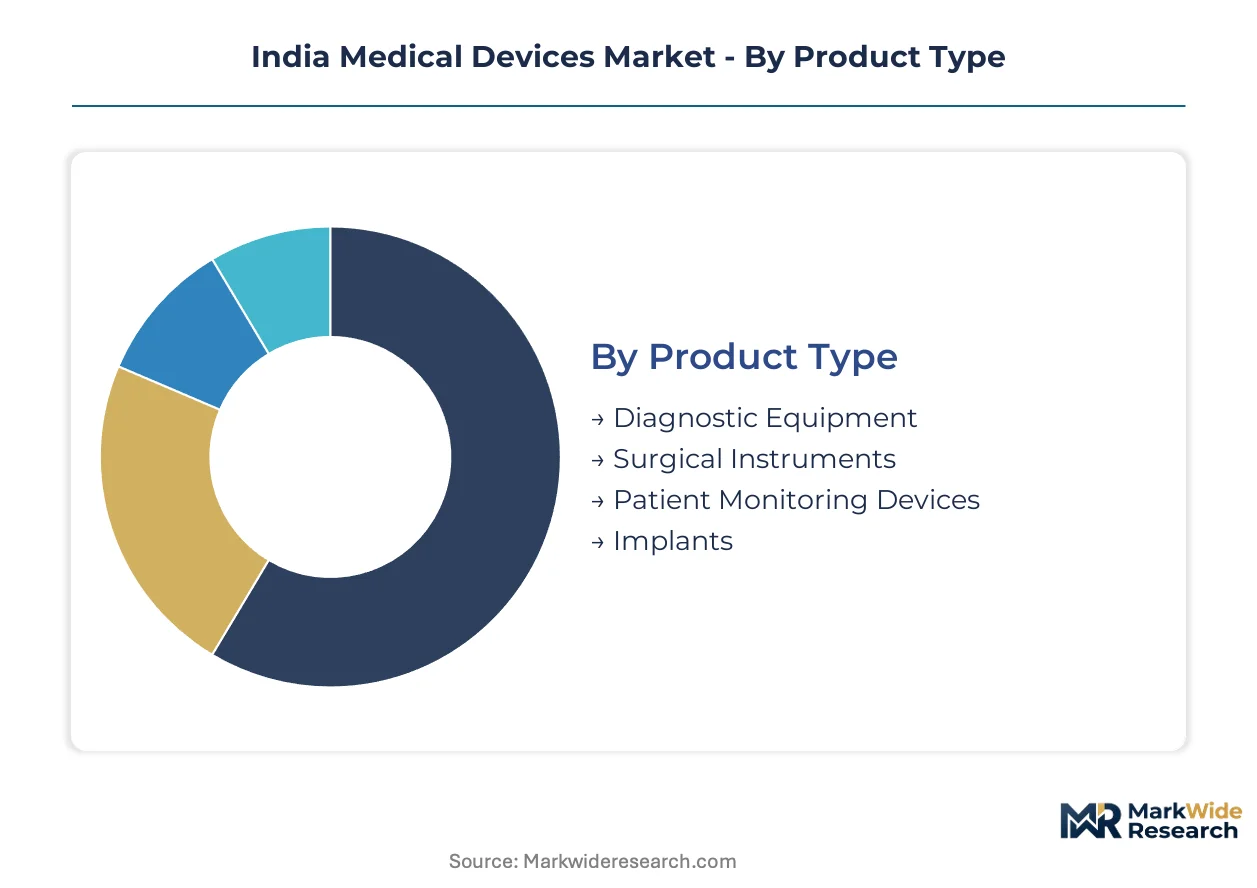
Segmentation reveals how procurement patterns diverge across India's medical device landscape. Service intensity, capital requirements, and regulatory complexity vary sharply by product category and end-use setting.
Product Type:
After-sales-service intensity varies dramatically across device categories, with imaging systems demanding multi-year maintenance contracts and surgical instruments requiring minimal post-purchase support.
- Diagnostic Equipment:Imaging modalities including CT, MRI, and ultrasound systems generate recurring service revenue streams through annual maintenance contracts. Maharashtra and Karnataka hospital chains concentrate procurement of these capital-intensive systems where early disease detection protocols drive purchasing decisions.
- Surgical Instruments:Stainless steel and polymer-based cutting, grasping, and retracting tools serve operating theaters with lower service attachment rates. Tier-II hospitals in Gujarat and Tamil Nadu source these through third-party biomedical distributors seeking price advantages over OEM channels.
- Patient Monitoring Devices:Multi-parameter bedside monitors and portable vital signs equipment integrate with hospital IT networks for centralized alarm management.
- Implants:Cardiac stents, orthopedic prosthetics, and dental fixtures face CDSCO's strictest quality management system requirements under risk-based classification rules.
Diagnostic Equipment holds the largest share; momentum sits with Patient Monitoring Devices as connected care protocols expand beyond tertiary centers.
End User:
Capital deployment thresholds and procurement sophistication separate institutional buyers, with facility scale determining contract negotiation leverage and vendor selection criteria.
- Hospitals:Multi-specialty and corporate chains command volume-based pricing for imaging fleets and negotiate unbundled service agreements. Telangana's expanding hospital infrastructure exemplifies concentrated demand for integrated diagnostic and therapeutic device procurement.
- Clinics:Single-specialty and diagnostic centers prioritize point-of-care ultrasound and basic monitoring equipment with lower footprint requirements. These settings in Uttar Pradesh and Bihar remain underserved for advanced modality access.
- Home Care:Portable oxygen concentrators, continuous glucose monitors, and sleep apnea devices serve post-acute and chronic disease management outside institutional settings.
- Rehabilitation Centers:Physical therapy equipment and assistive mobility devices address stroke recovery and orthopedic post-surgical care protocols.
Hospitals dominate procurement volume; Home Care is expanding most quickly as remote patient monitoring gains clinical reimbursement acceptance.
Technology:
Software integration intensity and data connectivity requirements differentiate technology platforms, with cloud-native architectures commanding premium positioning.
- Wearable Devices:Biosensors for cardiac rhythm, blood glucose, and activity tracking transmit continuous data streams to clinician dashboards. Post-operative care departments in Karnataka corporate hospitals are adopting these for remote surveillance protocols.
- Imaging Technology:Digital radiography, CT reconstruction algorithms, and MRI pulse sequences embed proprietary software that locks hospitals into vendor ecosystems.
- Robotics:Surgical navigation and minimally invasive procedure systems require specialized training infrastructure and dedicated operative suites.
- Telemedicine:Integrated diagnostic peripherals and video consultation platforms extend specialist reach into district hospital networks.
Imaging Technology retains the largest installed base; Wearable Devices show the steepest expansion trajectory as chronic disease management shifts toward continuous monitoring models.
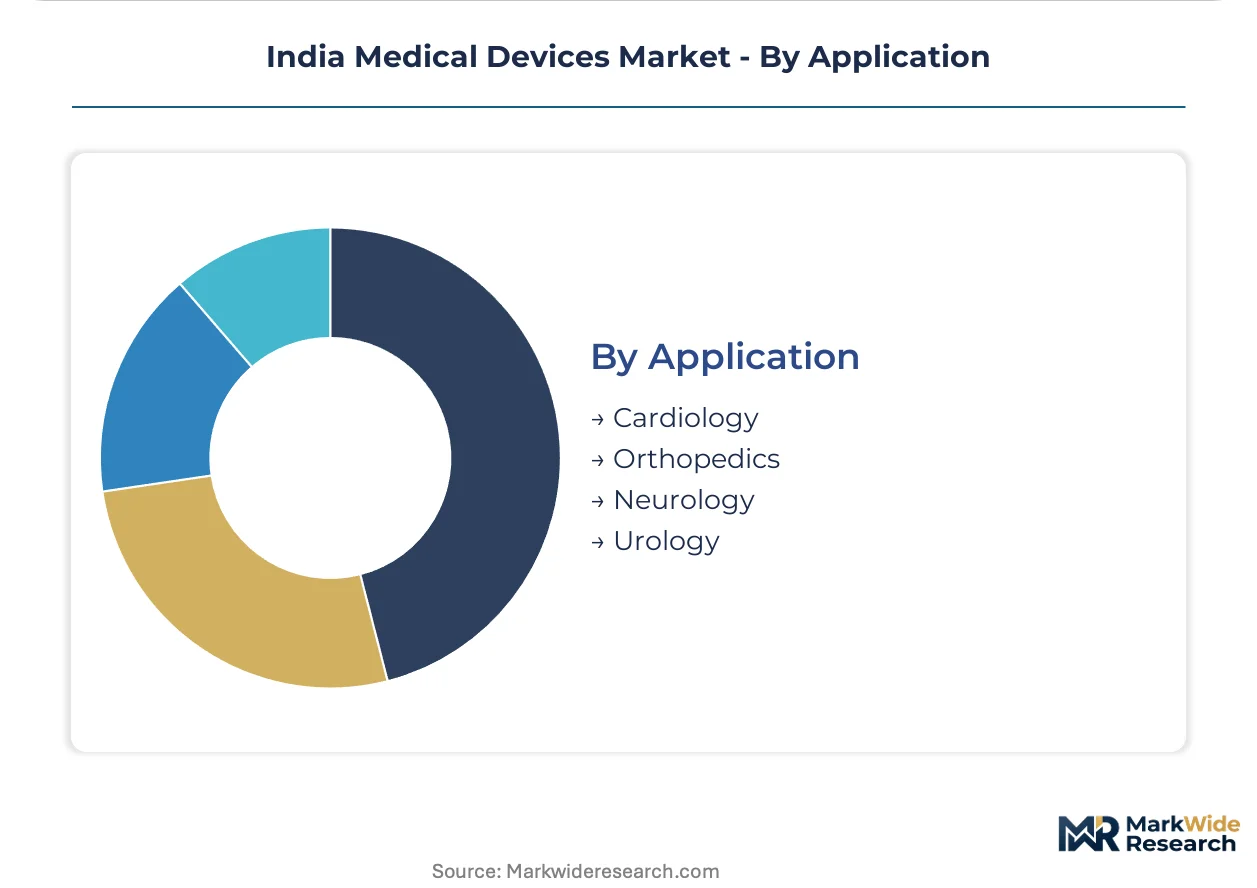
Application:
Procedure volume and reimbursement rates determine device utilization intensity, with high-acuity specialties justifying more frequent technology refresh cycles.
- Cardiology:Interventional catheters, electrophysiology mapping systems, and implantable rhythm devices address India's rising cardiovascular disease burden. CDSCO's adverse event reporting mandates impose the steepest compliance costs on this segment.
- Orthopedics:Joint replacement implants, arthroscopy systems, and trauma fixation devices serve aging demographics and accident trauma volumes.
- Neurology:Deep brain stimulation systems and neuro-navigation platforms require highly specialized surgical training infrastructure.
- Urology:Endoscopic lithotripsy systems and urinary incontinence devices address stone disease and benign prostatic hyperplasia prevalence.
Cardiology commands the highest device revenue concentration; Orthopedics is gaining share fastest as joint replacement surgery penetrates tier-II city hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Maharashtra, Karnataka, and Telangana concentrate demand for high-value imaging systems, while tier-II city expansion in Gujarat and Tamil Nadu reshapes distribution economics for mid-range equipment.
Maharashtra
Mumbai-Pune corridor hospitals drive CT and MRI procurement volumes as corporate chains expand specialty cardiac and oncology centers. CDSCO's risk-based classification rules extend registration timelines for Class C implantables entering this market. The Mumbai medical device cluster anchors domestic assembly operations for dialysis equipment and patient monitoring systems.
Karnataka
Bengaluru's hospital infrastructure prioritizes wearable biosensors and connected monitoring devices for post-operative care protocols. The state's PLI scheme beneficiaries localize manufacturing of ultrasound probes and diagnostic peripherals. Medical technology parks in Bengaluru attract contract manufacturers serving both domestic and export markets.
Telangana
Hyderabad's expanding hospital chains concentrate procurement of cath-lab equipment and interventional cardiology devices. BIS electrical safety standards govern active device approvals for equipment entering this market. The Genome Valley life sciences corridor hosts diagnostic reagent manufacturing and medical device R&D facilities.
Gujarat
Ahmedabad-Surat hospital networks source surgical instruments and basic monitoring equipment through third-party biomedical distributors. The PLI scheme redirects procurement incentives toward domestic manufacturers of standard consumables. Medical device parks in Vadodara specialize in polymer-based disposables and sterilization equipment.
Tamil Nadu
Chennai's mixed-fleet hospital chains negotiate unbundled service contracts across GE, Siemens, and Philips imaging systems. CDSCO quality management system requirements mandate ISO 13485 certification for device importers serving this market. The Sriperumbudur electronics manufacturing corridor supports component sourcing for patient monitoring device assembly.
India Medical Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across India's medical device market, creating a tiered structure where imaging OEMs anchor premium positions and domestic contract manufacturers capture mid-range volumes. The vendor base separates into three strategic archetypes: multinational imaging system integrators, regional surgical instrument fabricators, and emerging domestic diagnostic device specialists. Competitive moves center on PLI-linked manufacturing localization and unbundled service contract negotiations that disintermediate traditional OEM revenue streams.
Among multinational imaging and cardiac device specialists, GE Healthcare, Siemens Healthineers, and Medtronic occupy positions that exemplify contrasting strategic anchors within the market structure. GE Healthcare represents the installed-base leverage archetype, Siemens Healthineers exemplifies PLI-driven manufacturing localization, and Medtronic occupies the therapeutic specialization position focused on cardiac rhythm and vascular portfolios.
| Leading Market Players |
|---|
| Abbott Laboratories |
| GE Healthcare |
| Koninklijke Philips |
| Medtronic |
| Siemens Healthineers |
| Meril |
| Trivitron |
| BPL Medical |
| Molbio Diagnostics |
| Others |
Pricing and Supply Chain Analysis
The JNPT-Mundra freight corridor's container cost dynamics amplify supply concentration effects for imaging equipment landed in Maharashtra, compressing margins for domestic assemblers while enabling tiered price differentiation between port-proximate hospital chains and inland procurement committees facing logistics premiums.
Pricing Analysis
Cost-plus contracts with yen-denominated indexation clauses govern MRI and CT equipment procurement for corporate hospital chains. Three-tier pricing structure across premium, standard, and economy levels separates OEM-direct installations from refurbished systems and third-party refurbished channels. Price differentiation rests on ISO 13485 certification tier and bundled service contract duration. Cost compression in economy-tier surgical instruments is intensifying because Gujarat-based contract manufacturers are absorbing PLI-linked input cost advantages. Tier-III nursing homes in Uttar Pradesh exhibit the highest price sensitivity; tertiary cardiac centers in Hyderabad demonstrate the least.
Supply Chain Analysis
Export-control restrictions on high-field superconducting magnet technology limit flows from Germany and Japan to Indian MRI assemblers. Component sourcing concentrates in China for printed circuit assemblies, Germany for precision sensor modules, and the United States for semiconductor-based imaging processors. Raw material dependencies include rare-earth elements for magnet fabrication, high-purity copper for RF coils, and medical-grade polymers for disposable surgical consumables. Single-source vulnerability for cryogen supply exposes domestic manufacturers to helium market volatility. Distribution runs through biomedical engineering distributors in tier-II cities and direct OEM sales teams for imaging system installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's medical devices sector is positioned for cyclical recovery as hospital capital expenditure resumes following PLI scheme maturation and deferred procurement backlog clearance.
For Market Incumbents: Harden service revenue streams by unbundling maintenance contracts from equipment sales to compete with third-party biomedical engineering firms in Tamil Nadu and Gujarat. Deepen backward integration into domestic manufacturing of CT detector arrays under PLI incentives to offset import dependency on German and Japanese suppliers. Channel control through exclusive spare parts distribution agreements represents the critical defensive lever against emerging domestic contract manufacturers. For New Entrants and Emerging Players: District hospitals and nursing homes in Madhya Pradesh and Bihar represent the most penetrable entry point for rental-model dialysis equipment and refurbished ventilator channels. Point-of-care ultrasound systems for ambulatory cardiology departments in tier-II Karnataka cities offer a second whitespace target with lower regulatory barriers than implantable devices. A go-to-market angle through hospital procurement committee education on total cost of ownership calculations differentiates against incumbent OEM direct sales approaches. For Investors and Strategic Acquirers: Domestic diagnostic device specialists with ISO 13485 certification and established CDSCO registration pathways command premium positioning for portfolio consolidation. Long-term viability over the next decade hinges on regulatory harmonization momentum and PLI scheme extension decisions. The signal to monitor is CDSCO's implementation timeline for mandatory quality management system audits, which would accelerate compliance cost advantages for certified domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | CDSCO's IMDRF alignment compresses parallel registration timelines for European-certified portfolios entering Indian markets. |
| Hospital System Partnership | Corporate chain preferred vendor status locks in imaging fleet refresh cycles and captive service revenue streams. |
| Software Companion Development | AI-enabled radiology workflow tools generate recurring SaaS revenue independent of hardware replacement demand. |
| Reimbursement Strategy | Central Government Health Scheme inclusion for wearable monitoring devices accelerates home care segment penetration. |
| Backward Integration | In-house production of ultrasound probes under PLI scheme reduces landed cost disadvantages against imported finished goods. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and CDSCO regulatory affairs specialists anchored the qualitative base. Secondary validation drew from CDSCO registration databases, hospital procurement tender records, Department of Pharmaceuticals PLI scheme disclosures, and BIS standards documentation. Bottom-up equipment installation tracking across Maharashtra, Karnataka, and Telangana combined with top-down pharmaceutical and medical device trade flow analysis to establish market sizing boundaries.
Scenario-bracketing around PLI scheme extension decisions and CDSCO quality management system implementation pace framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type intensity, end-user facility scale, technology platform connectivity requirements, and application-specific reimbursement pathways. CAGRs were derived from equipment replacement cycle analysis and hospital bed expansion forecasts. Industry-specific inputs incorporated cath-lab procedure volume growth and dialysis center penetration rates in tier-III districts.
Macroeconomic conditions sit as an overlay; deviation in rupee-yen exchange rates and helium commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization momentum and PLI beneficiary manufacturing scale-up. Material shifts in CDSCO risk-based classification enforcement or import duty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Cyberknife Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Bowel Stimulators Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market