
 Asia-Pacific Conjunctivitis Treatment Market | 2026-2036
Asia-Pacific Conjunctivitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Conjunctivitis Treatment Market Insights
Multi-source API procurement is broadening among generic ophthalmic manufacturers across the Asia-Pacific region. Sun Pharmaceutical Industries Ltd. leverages its vertically integrated active pharmaceutical ingredient operations to secure cost advantages in antibiotic drop production. Cipla Limited anchors its position through sustained R&D investment in preservative-free formulation technologies. Santen Pharmaceutical Co., Ltd. dominates Japan's prescription ophthalmic channel through deep ties with university hospitals and specialized eye clinics.
Conjunctivitis treatment encompasses pharmaceutical interventions targeting acute and chronic inflammation of the bulbar and palpebral conjunctiva, typically administered via topical formulations containing antibiotics, antihistamines, corticosteroids, or lubricating agents with osmolality adjusted to 250-350 mOsm/kg for corneal compatibility. These therapies serve to eradicate bacterial or viral pathogens, modulate immune-mediated allergic responses, and restore tear film stability in clinical and homecare settings. Antibiotic drops occupy the largest revenue share due to high prescription volumes for bacterial conjunctivitis across India's government health schemes and China's urban hospital networks. Artificial tears represent the fastest-expanding category, propelled by rising digital screen exposure and dry eye syndrome prevalence among white-collar workers in South Korea and Australia.
Japan's PMDA maintains stringent stability testing requirements for multi-dose ophthalmic containers, while India's CDSCO enforces bioequivalence protocols for generic fluoroquinolone drops under its ophthalmic product guidance. Australia's TGA alignment with EU MDR standards for preservative safety thresholds is reshaping formulation strategies for multinational suppliers seeking regional registration. Stakeholders must monitor China's NMPA accelerated review pathways for innovative anti-allergic compounds and calibrate portfolio investments between mature antibiotic segments and emerging biologic eye drops.
Market Dynamics
India's PLI scheme for active pharmaceutical ingredients is compressing manufacturing costs for ophthalmic antibiotic drops, forcing regional competitors to reconfigure procurement strategies or absorb margin erosion.
Growth Catalysts
- Active pharmaceutical ingredient localization:India's production-linked incentive scheme reduces import dependency for fluoroquinolone precursors, enabling faster batch turnaround for generic eye drop manufacturers.
- Allergic conjunctivitis prevalence:Rising pollen indices across Australia's southeastern corridor expand prescription volumes for dual-action antihistamine-mast cell stabilizer formulations.
- Digital diagnostic penetration:Smartphone-enabled anterior segment imaging accelerates remote triage decisions in China's tier-two city hospital networks.
Market Restraints
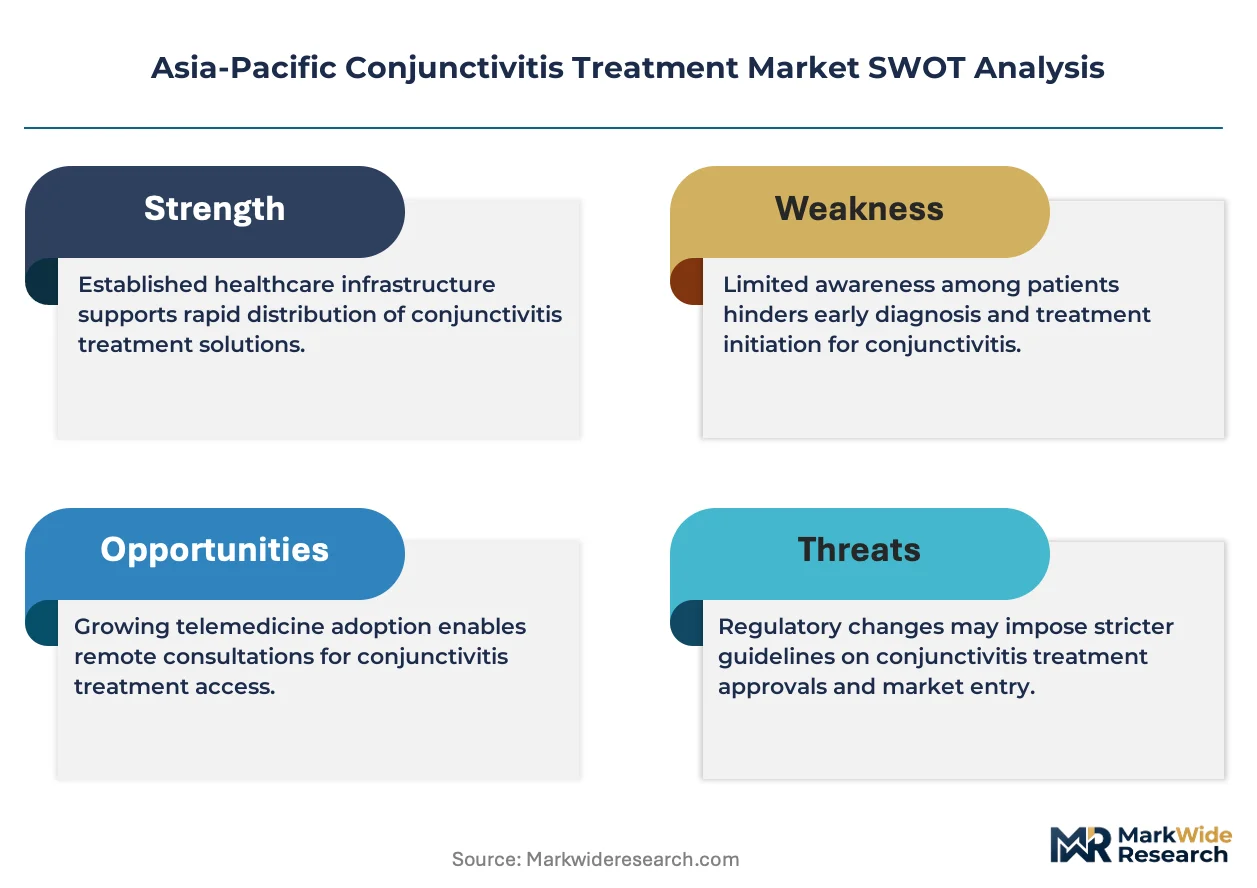
- Preservative safety thresholds:Australia's TGA alignment with EU MDR benzalkonium chloride limits forces reformulation investments that compress generic manufacturer margins.
- API supply concentration:Bulk antibiotic intermediate production clusters in China's Zhejiang province create single-source vulnerability for regional formulators.
- Stability testing duration:Japan's PMDA multi-dose container validation protocols extend registration timelines by 8-14 months versus ASEAN mutual recognition pathways.
Strategic Opportunities
- Biologic eye drop white space:China's NMPA accelerated review pathway for anti-allergic monoclonal antibodies rewards first-movers in severe vernal keratoconjunctivitis.
- Preservative-free segment expansion:Unit-dose vial demand among South Korean contact lens wearers outpaces domestic blow-fill-seal capacity.
- Teleophthalmology integration:Japan's Ministry of Health reimbursement expansion for remote conjunctivitis screening creates channel arbitrage for platform-integrated pharmacies.
Industry Challenges
- Ophthalmic formulation expertise scarcity:Qualified personnel for isotonic buffer optimization and sterility assurance remain concentrated in Mumbai and Shanghai clusters.
- Legacy packaging line retrofit costs:Transition from glass to cyclic olefin polymer containers requires capital outlays that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Conjunctivitis Treatment Market |
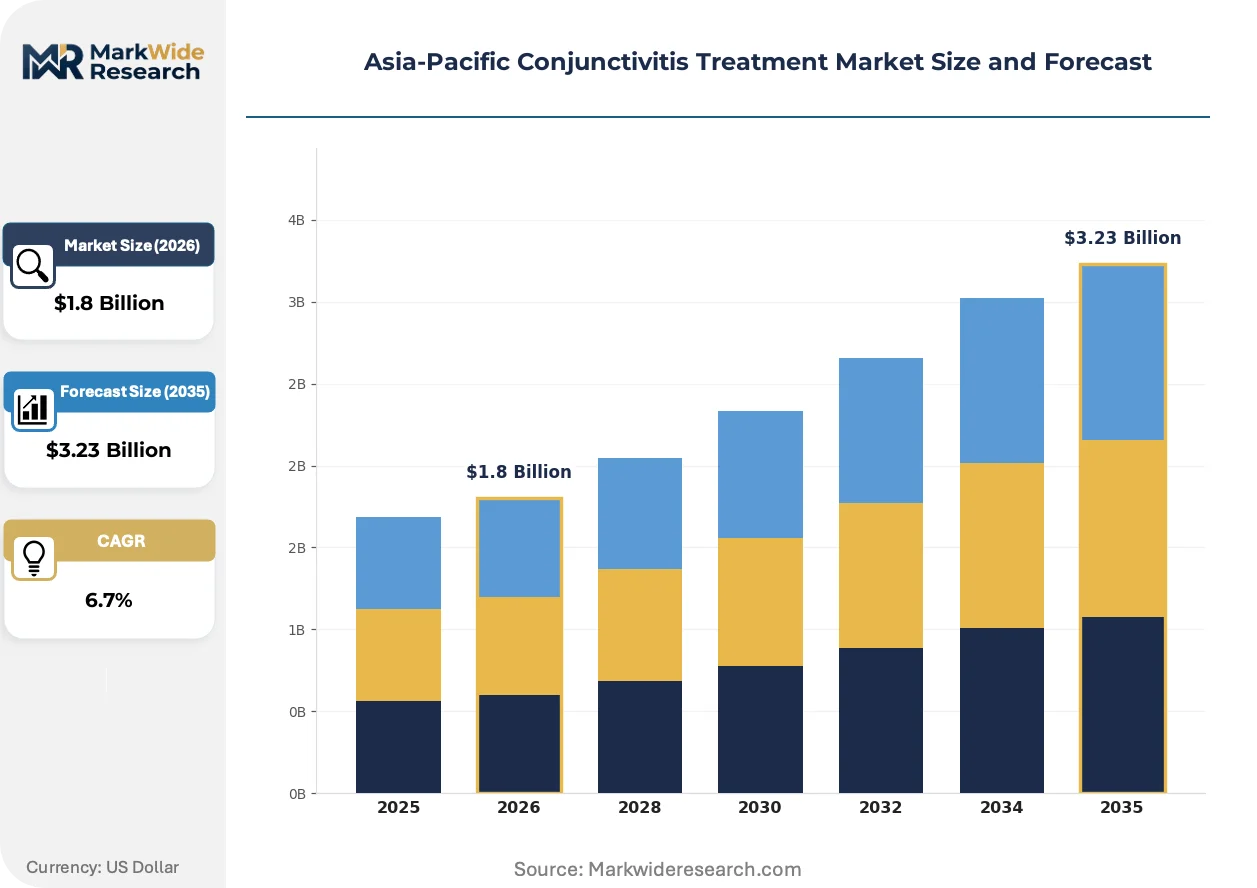
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotic Drops, Antihistamine Drops, Steroid Drops, Artificial Tears Delivery Mode: Topical, Injectable, Oral, Ophthalmic End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Formulation: Solutions, Suspensions, Gels, Ointments |
| Companies Covered | Santen Pharmaceutical Co., Ltd., Sun Pharmaceutical Industries Ltd., Cipla Limited, Novartis AG, AbbVie Inc. (Allergan), Bausch + Lomb, Alcon, Akorn Operating Company LLC, Pfizer Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Conjunctivitis Treatment Market Trends and Innovations
Electrification of diagnostic and therapeutic modalities is collapsing the latency between symptom onset and targeted intervention across Asia-Pacific ophthalmology workflows.
Nanostructured lipid carrier technology is electrifying corticosteroid bioavailability in anterior segment applications. Japanese university hospitals are piloting these vehicles for refractory allergic conjunctivitis cases. The platform is compressing dosing frequency from four times daily to twice daily, reshaping adherence economics for chronic management protocols.
Japan's PMDA revised stability guidance for multi-dose preservative systems now mandates real-time temperature excursion data. Generic manufacturers must deploy continuous monitoring infrastructure across distribution networks. Cold chain validation costs are concentrating procurement decisions among suppliers with captive logistics capabilities.
Hospital pharmacy consortiums in China's Yangtze River Delta are consolidating anti-infective eye drop tenders under volume-based procurement frameworks. Tier-one municipal health bureaus now dictate maximum allowable prices for fluoroquinolone and aminoglycoside categories. Formulators with backward-integrated API operations capture disproportionate share in these centralized awards.
Asia-Pacific Conjunctivitis Treatment Market Segmentation
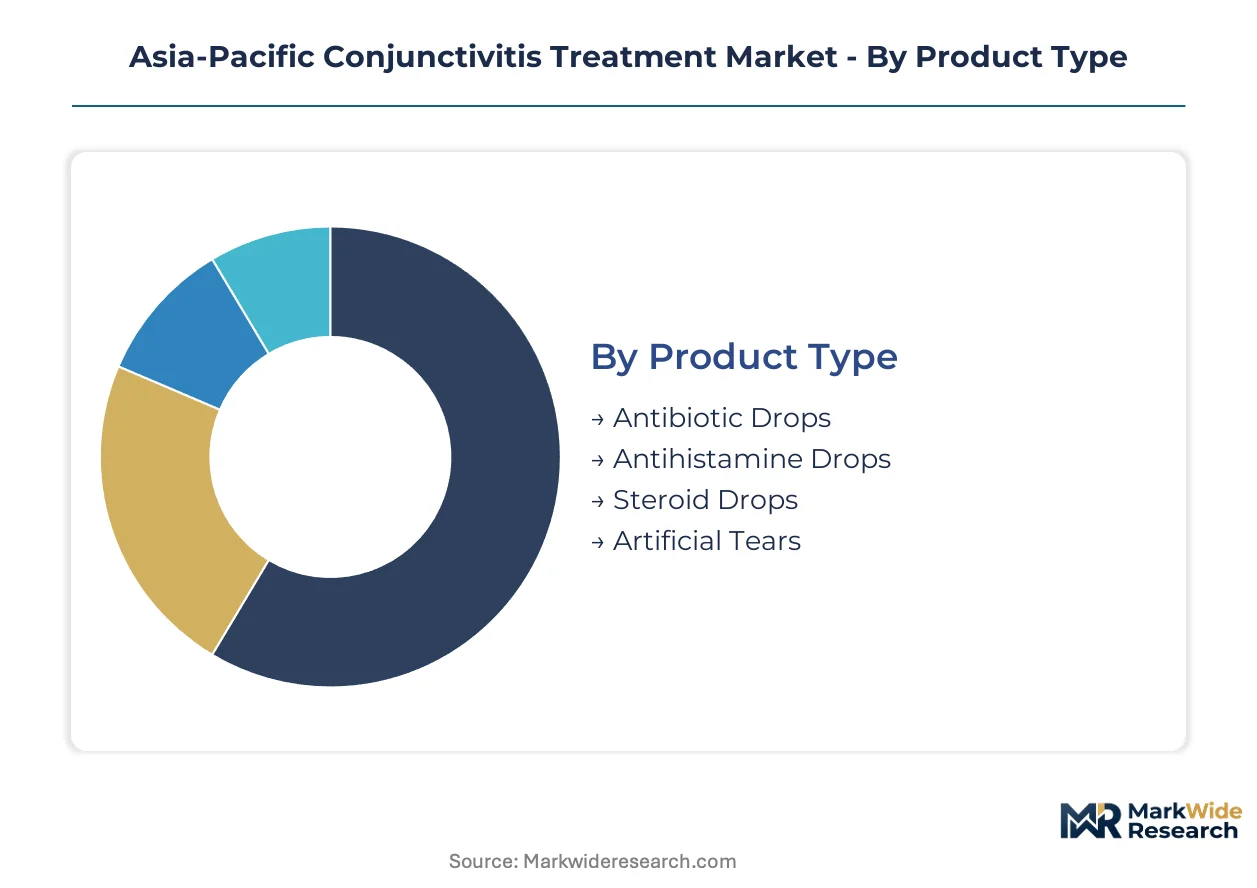
Conjunctivitis treatment modalities span standalone pharmaceutical products for acute episodes and integrated therapeutic systems for chronic management. Segment boundaries blur as preserv-free unit-dose formats migrate from hospital discharge kits into direct-to-consumer channels across Asia-Pacific markets.
Product Type:
Standalone antibiotic and antihistamine formulations dominate acute care prescribing, while embedded lubrication therapies integrate into broader dry eye management protocols.
- Antibiotic Drops:Fluoroquinolone and aminoglycoside solutions with osmolality calibrated to 250-350 mOsm/kg for corneal compatibility. Procurement volumes concentrate in China's tier-one city hospital pharmacy consortiums, driven by volume-based procurement frameworks that favor backward-integrated API manufacturers.
- Artificial Tears:Viscosity-enhanced polymer solutions and lipid-based emulsions restoring tear film stability. Demand clusters among South Korean and Australian white-collar workers facing elevated digital screen exposure, with preservative-free unit-dose formats outpacing multi-dose bottle preferences.
- Antihistamine Drops:Dual-action mast cell stabilizer formulations targeting IgE-mediated allergic responses.
- Steroid Drops:Corticosteroid suspensions for severe inflammatory presentations requiring rapid immune suppression.
Volume placements concentrate in Antibiotic Drops; the faster expansion belongs to Artificial Tears.
Delivery Mode:
Cost-tier stratification separates high-touch institutional administration from self-directed home therapy, with reimbursement thresholds dictating channel allocation.
- Topical:Direct ocular surface application via dropper or spray systems achieving anterior segment bioavailability. India's government health schemes and China's urban hospital networks generate the highest prescription volumes for this accessible, patient-administered format.
- Ophthalmic:Specialized delivery encompassing punctal plugs, drug-eluting contact lenses, and intracanalicular inserts for sustained release. Japanese university hospitals pilot these embedded systems for refractory allergic conjunctivitis, compressing dosing frequency and reshaping chronic management economics.
- Injectable:Periocular or intravitreal depot formulations for posterior segment complications.
- Oral:Systemic antihistamines and antibiotics for concurrent sinus or dermatological involvement.
Standard topical administration captures the volume base; ophthalmic specialty delivery is gaining share fastest among refractory case protocols.
End User:
Customer-type fragmentation reflects divergent procurement authority, with centralized hospital tenders contrasting decentralized retail pharmacy purchasing.
- Hospitals:Inpatient and emergency department dispensing with formulary-controlled antibiotic stewardship. China's Yangtze River Delta municipal health bureaus consolidate anti-infective tenders under price-ceiling frameworks, squeezing margins for non-integrated suppliers.
- Clinics:Outpatient ophthalmology and general practice prescribing with direct patient purchase options. Australia's southeastern corridor pollen indices expand prescription volumes for dual-action antihistamine formulations through these accessible points of care.
- Homecare:Self-directed therapy for recurrent allergic or mild infectious presentations.
- Ambulatory Surgical Centers:Perioperative prophylaxis and post-procedural lubrication protocols.
Hospital procurement anchors volume concentration; clinic channel expansion is climbing the fastest on teleophthalmology integration.
Formulation:
Supply concentration in isotonic buffer optimization expertise shapes competitive access to differentiated viscosity and residence-time profiles.
- Solutions:Homogeneous aqueous formulations with dissolved active pharmaceutical ingredients for immediate bioavailability. Mumbai and Shanghai manufacturing clusters concentrate qualified personnel for sterility assurance in this high-volume segment.
- Suspensions:Micronized particle dispersions requiring resuspension protocols for dose uniformity. Japan's PMDA stability testing mandates for multi-dose containers extend registration timelines, favoring suppliers with captive analytical infrastructure.
- Gels:Mucoadhesive polymers prolonging precorneal residence for overnight lubrication.
- Ointments:Petrolatum-based vehicles for severe exposure keratopathy and pediatric applications.
Aqueous solutions dominate placement volumes; gel formulations are expanding most quickly on contact lens wearer demand for overnight therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in Zhejiang province anchor supply-side economics for regional formulators. Hospital pharmacy procurement reforms in China's tier-one cities are compressing margins for non-integrated suppliers. Japan's PMDA stability mandates and India's PLI scheme are creating divergent regulatory pathways across the region.
China
Volume-based procurement frameworks in the Yangtze River Delta municipal health bureaus dictate price ceilings for fluoroquinolone and aminoglycoside eye drops. NMPA accelerated review pathways reward first-movers in anti-allergic monoclonal antibodies for severe vernal keratoconjunctivitis. Zhejiang province concentrates bulk antibiotic intermediate production, creating single-source vulnerability for regional formulators dependent on external procurement.
India
Government health schemes generate the highest prescription volumes for topical antibiotic drops among outpatient populations. CDSCO enforces bioequivalence protocols for generic fluoroquinolone formulations under ophthalmic product guidance. Mumbai manufacturing clusters concentrate qualified personnel for isotonic buffer optimization and sterility assurance in high-volume aqueous solution production.
Japan
University hospitals pilot nanostructured lipid carrier vehicles for refractory allergic conjunctivitis cases, compressing dosing frequency from four times to twice daily. PMDA revised stability guidance mandates real-time temperature excursion data for multi-dose preservative systems. Kanto region ophthalmology clinics expand outpatient capacity through deep ties with specialized eye hospitals and research institutions.
South Korea
White-collar workers facing elevated digital screen exposure drive demand for preservative-free unit-dose artificial tear formats. MFDS regulatory frameworks align with international standards for ophthalmic container safety and preservative thresholds. Seoul metropolitan area contact lens wearer populations outpace domestic blow-fill-seal manufacturing capacity for single-use vial production.
Australia
Rising pollen indices across the southeastern corridor expand prescription volumes for dual-action antihistamine-mast cell stabilizer formulations. TGA alignment with EU MDR benzalkonium chloride limits forces reformulation investments that compress generic manufacturer margins. Melbourne and Sydney ophthalmology practices integrate smartphone-enabled anterior segment imaging for remote triage decisions.
Asia-Pacific Conjunctivitis Treatment Market Competitive Landscape
Backward integration into active pharmaceutical ingredient production dominates the current landscape among cost-positioned manufacturers. The vendor base fragments across three tiers: multinational pharmaceutical conglomerates with diversified ophthalmic portfolios, regional generic specialists with captive API operations, and mid-tier formulators dependent on external supply chains. Two strategic archetypes define competitive positioning: vertically integrated cost leaders leveraging government incentive schemes, and innovation-focused developers targeting preservative-free and biologic formats. Capacity expansion in unit-dose blow-fill-seal infrastructure and strategic partnerships for distribution logistics represent the dominant competitive moves.
Among Japan-based prescription ophthalmic specialists, Santen Pharmaceutical Co., Ltd. occupies a position exemplifying deep institutional channel penetration. Indian generic manufacturers Sun Pharmaceutical Industries Ltd. and Cipla Limited represent the vertically integrated archetype, with the former anchoring cost advantages through captive API production and the latter exemplifying sustained formulation technology investment. These three companies illustrate the regional competitive tension between innovation-driven premium positioning and scale-driven generic economics.
| Leading Market Players |
|---|
| Santen Pharmaceutical Co., Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Cipla Limited |
| Novartis AG |
| AbbVie Inc. (Allergan) |
| Bausch + Lomb |
| Alcon |
| Akorn Operating Company LLC |
| Pfizer Inc. |
| Others |
Pricing and Supply Chain Analysis
China's tier-one city hospital pharmacy consortiums concentrate procurement authority under volume-based procurement frameworks, compressing margins for fluoroquinolone and aminoglycoside eye drops and forcing formulators toward backward-integrated API operations or exit.
Pricing Analysis
Service bundling remains minimal in ophthalmic generics, with after-sales support and clinical education unbundled from unit pricing. Three-tier pricing structure across premium preservative-free formulations, standard multi-dose antibiotics, and economy-tier government tenders captures the market stratification. Price differentiation hinges on API backward integration status and PMDA/TGA registration tier, with integrated Indian manufacturers commanding flexibility against margin-squeezed external sourcers. Pricing pressure stems from China's municipal price-ceiling mandates, eroding profitability for non-integrated suppliers. Government health scheme procurement exhibits highest price sensitivity; Japanese university hospital channels show lowest sensitivity due to formulary stickiness and clinical preference protocols.
Supply Chain Analysis
India's PLI scheme and China's Zhejiang province API manufacturing mandates are reshaping regional sourcing patterns, pressuring formulators to localize intermediate procurement or absorb tariff and compliance penalties. Active pharmaceutical ingredient production concentrates in China's Zhejiang corridor, India's Mumbai-Pune belt, and select Japanese fermentation facilities. Fluoroquinolone precursors, preservative systems, and cyclic olefin polymer containers constitute critical input dependencies. Single-source vulnerability in Zhejiang antibiotic intermediate clusters threatens batch continuity for regional formulators. Distribution runs through hospital pharmacy consortiums in China, government medical stores in India, and specialized ophthalmic wholesalers in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where Japan's PMDA real-time temperature excursion mandates and stability testing protocols erect formidable registration barriers, advantaging incumbents with captive analytical infrastructure and cold chain logistics.
For Market Incumbents: To counter margin compression from China's volume-based procurement price ceilings, deepen backward integration into fluoroquinolone API production through India's PLI scheme incentives, and expand preservative-free blow-fill-seal capacity in South Korea to capture contact lens wearer demand. For New Entrants and Emerging Players: Refractory allergic conjunctivitis cases in Japanese university hospitals represent an underserved buyer archetype with unmet need for nanostructured lipid carrier formulations; enter through licensing partnerships with established local distributors to navigate PMDA registration complexity. For Investors and Strategic Acquirers: The window for entry favors mid-tier Indian manufacturers with CDSCO-approved bioequivalence portfolios and latent API integration potential; monitor China's NMPA accelerated review pathway approvals for anti-allergic monoclonal antibodies as inflection signal for biologic eye drop segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Scale-Up | Captures South Korean and Australian contact lens wearer demand outpacing domestic unit-dose capacity. |
| API Backward Integration | Secures cost positioning under India's PLI scheme against China's volume-based procurement price compression. |
| NMPA Accelerated Review Pathway Submission | Rewards first-mover status in severe vernal keratoconjunctivitis biologic eye drops for China market access. |
| Cold Chain Logistics Infrastructure Deployment | Satisfies Japan's PMDA real-time temperature monitoring mandates for multi-dose preservative system distribution. |
| Teleophthalmology Platform Integration | Aligns with Japan's Ministry of Health reimbursement expansion for remote conjunctivitis screening services. |
Research Methodology
Independent corroboration across CDSCO regulatory filings, PMDA stability guidance documents, and China's NMPA volume-based procurement tender databases underwrites the qualitative findings. Primary interviews with ophthalmic formulation R&D directors, hospital pharmacy procurement managers, and API manufacturing plant heads in Mumbai and Zhejiang combined with secondary validation from ClinicalTrials.gov entries, customs trade data for ophthalmic active pharmaceutical ingredients, and SEC 10-K ophthalmic segment disclosures. Bottom-up prescription volume modeling and top-down market sizing triangulate across these sources.
Rate-of-change decomposition across the projection horizon segments volume and value trajectories by treatment modality, delivery mode, end-user channel, and regional regulatory cluster. Compound annual growth rates derive from patient population epidemiology, prescription volume trends in government health schemes, and pricing elasticity under volume-based procurement frameworks. Forecast inputs incorporate pollen index projections for Australia's southeastern corridor, digital screen exposure metrics for South Korean white-collar workers, and PLI scheme uptake rates for Indian API manufacturing.
Revisions become necessary when NMPA accelerates or delays biologic eye drop review timelines, when PMDA tightens preservative safety thresholds beyond current EU MDR alignment, or when PLI scheme eligibility criteria shift for ophthalmic API categories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Orthokeratology Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
CNV (Choroidal Neovascularization) Market