
 South Africa Ophthalmic Devices Market | 2026-2036
South Africa Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Ophthalmic Devices Market Analytics
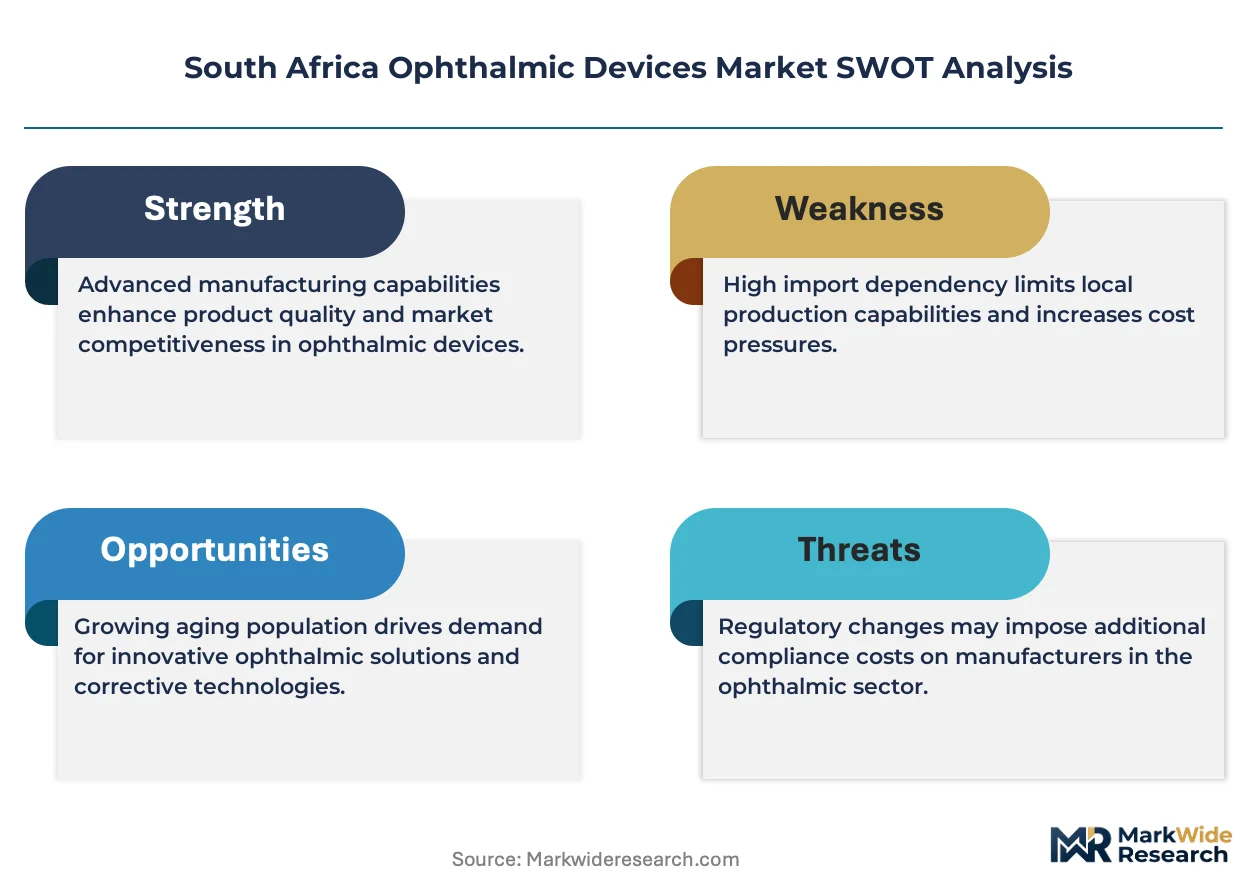
Aftermarket service revenue for diagnostic imaging platforms is tilting toward independent service organizations and away from manufacturer-direct contracts. EssilorLuxottica leverages its vertically integrated lens manufacturing and retail network to dominate premium spectacle lens distribution across urban South Africa. Alcon anchors its position through sustained investment in surgical consumables training programs at public teaching hospitals. Carl Zeiss competes on optical coherence tomography technology leadership, particularly in retinal imaging sub-specialties.
South Africa ophthalmic devices encompass precision-engineered instruments for vision correction, ocular disease diagnosis, and surgical intervention, typically manufactured to ISO 13485 quality standards with biocompatible materials such as hydrophilic acrylics for intraocular lenses. These devices serve the primary commercial purpose of restoring or preserving visual function across clinical settings from tertiary hospitals to community eye care programs. Diagnostic equipment commands the deepest installed base among product types, though surgical instruments generate superior per-procedure margins in private hospital networks. Cataract surgery remains the highest-volume application segment, while retinal procedures represent the fastest-growing application driven by diabetic retinopathy prevalence. Laser-based technology occupies the premium tier of the technology dimension, with imaging systems expanding access in resource-constrained settings.
The South African Health Products Regulatory Authority governs medical device registration and post-market surveillance, while the National Department of Health sets procurement standards that shape public sector demand patterns. BIS alignment for imported devices and WHO prequalification pathways increasingly influence market access for multinational suppliers. Stakeholders must monitor pending revisions to the National Health Insurance benefit package, which will redefine reimbursement levels for cataract and glaucoma interventions across both public and accredited private facilities.
Market Dynamics
The National Health Insurance benefit package revision is compressing procurement timelines for public hospital cataract programs while concentrating demand among accredited suppliers capable of meeting volume-scale compliance requirements.
Growth Catalysts
- Public procurement expansion:The National Department of Health is accelerating phacoemulsification system purchases through centralized tender frameworks that favor multi-unit hospital contracts.
- ISO 13485 certification pathways:Streamlined quality management system recognition is reducing vendor qualification periods for imported surgical consumables entering Gauteng province's academic medical centers.
- Diabetic retinopathy screening protocols:Provincial health departments are mandating optical coherence tomography deployment in diabetes management programs, pulling diagnostic equipment into primary care networks.
Market Restraints
- Import duty structure:BIS alignment requirements and customs processing delays inflate landed costs for premium diagnostic imaging platforms sourced from European manufacturing bases.
- Specialized technician scarcity:Laser system maintenance and phacoemulsification handpiece repair capabilities concentrate in Johannesburg and Pretoria, leaving secondary cities dependent on fly-in service models.
- Reimbursement compression:Pending National Health Insurance fee schedules threaten margin structures for private hospital cataract procedures currently cross-subsidizing technology upgrades.
Strategic Opportunities
- KwaZulu-Natal province penetration:Durban's ophthalmology clinic density lags Gauteng by a factor of four, creating whitespace for diagnostic equipment distributors establishing regional service hubs.
- Tele-ophthalmology integration:Remote retinal image interpretation platforms are converging with cloud-based electronic health record systems, enabling rural clinic screening without on-site specialist presence.
- WHO prequalification leverage:Multinational suppliers securing prequalified status gain accelerated access to provincial tender processes and development finance institution procurement windows.
Industry Challenges
- Biomedical engineering talent pipeline:Universities produce insufficient graduates trained in ophthalmic device calibration and preventive maintenance, forcing manufacturers to internalize training costs.
- Legacy system interoperability:Hospital information systems in public teaching hospitals run on fragmented architectures that resist seamless integration with modern imaging workstation data outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Ophthalmic Devices Market |
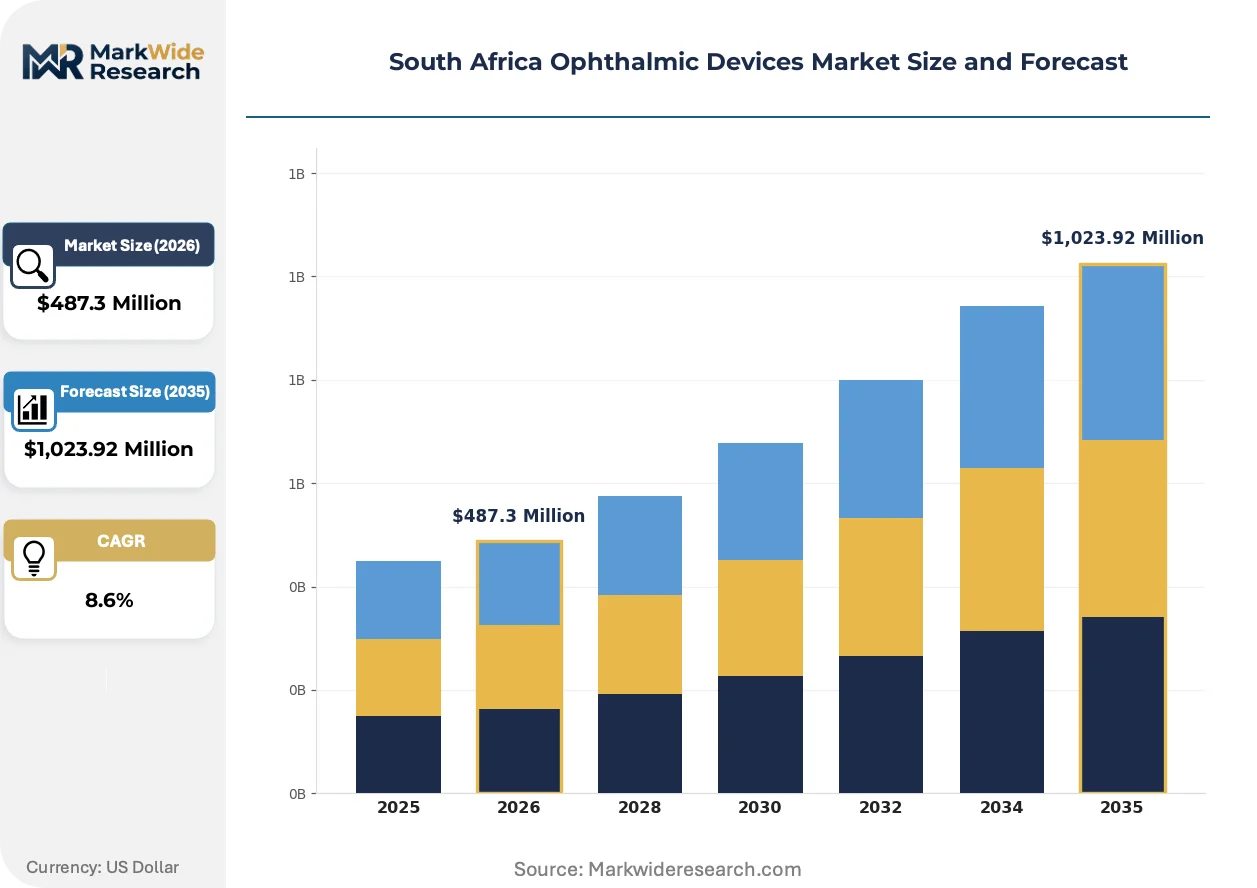
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Lens & Lens Inserts, Vision Aids Application: Cataract Surgery, Glaucoma Treatment, Refractive Surgery, Retinal Procedures End User: Hospitals, Ophthalmology Clinics, Research Institutions, Homecare Technology: Laser-Based, Manual Techniques, Imaging Systems, Diagnostic Software |
| Companies Covered | Bausch + Lomb, EssilorLuxottica, Alcon, Topcon, CooperVision Inc., Johnson & Johnson, HOYA, Nidek, Carl Zeiss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Ophthalmic Devices Market Evolving Landscape
Three intersecting developments are restructuring competitive advantage in South African ophthalmic care: surgical platform miniaturization, regulatory pathway acceleration, and service model unbundling from hardware contracts.
Femtosecond laser-assisted cataract surgery systems are collapsing the traditional boundary between diagnostic planning and surgical execution by integrating optical coherence tomography guidance directly into the treatment console. Private hospital groups in Johannesburg are adopting these platforms at replacement cycle compression rates of eighteen to twenty-four months. The technology is collapsing premium-tier pricing differentiation between academic medical centers and high-volume private chains.
South Africa's Health Products Regulatory Authority has implemented parallel review tracks for medical devices holding CE marking or FDA clearance, compressing registration timelines for imported diagnostic equipment by approximately forty percent. This regulatory acceleration is redirecting multinational market entry strategies toward direct subsidiary establishment rather than distributor-dependent models. Retinal imaging sub-specialties are capturing disproportionate benefit from faster approval pathways as diabetic screening program deadlines tighten.
After-sales service contracts are fragmenting as independent service organizations capture diagnostic imaging platform maintenance revenue previously held by manufacturer-direct agreements. Private hospital procurement departments are unbundling service from capital purchase, forcing original equipment manufacturers to compete on hourly labor rates and spare parts transparency. This shift is most visible in Gauteng province, where hospital group consolidation has created concentrated bargaining power against vendor service pricing.
South Africa Ophthalmic Devices Market Segmentation
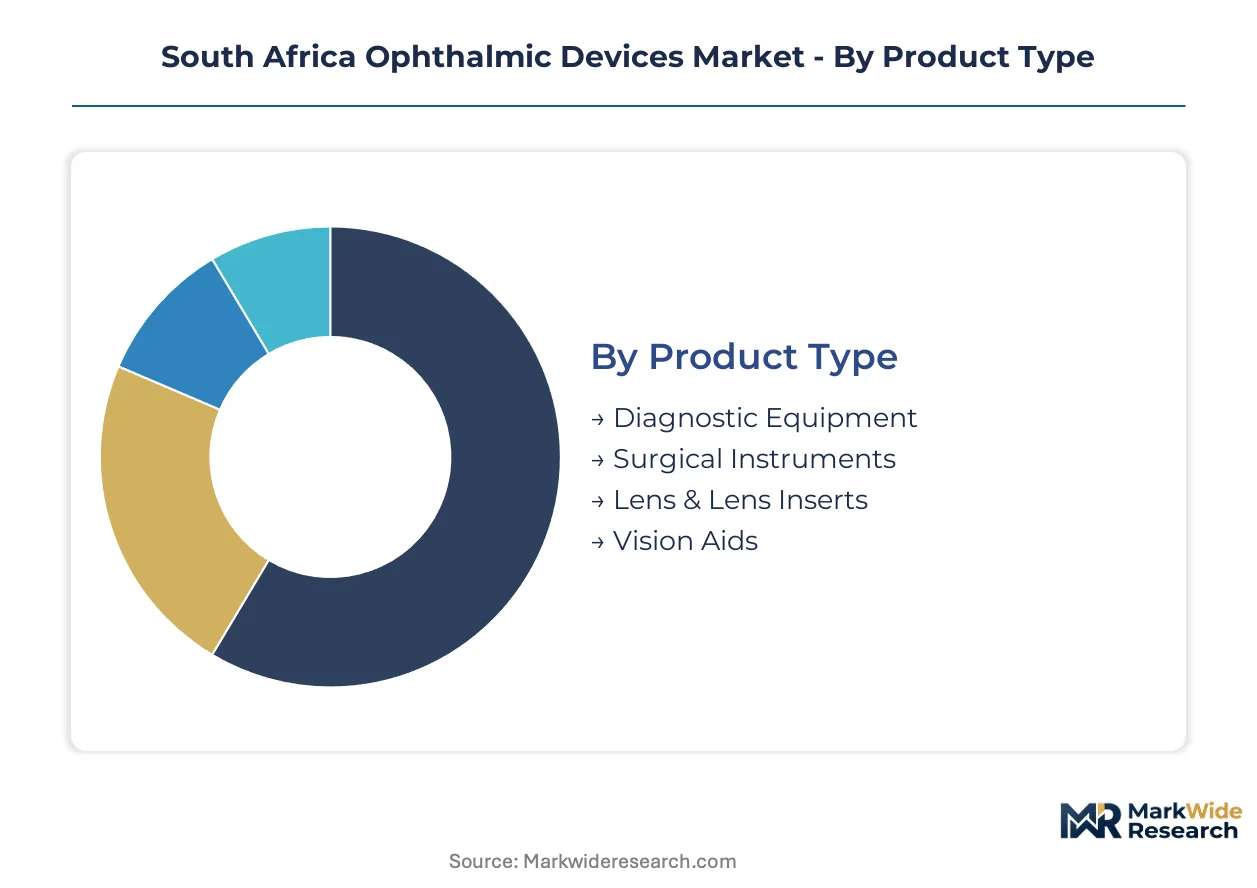
South Africa's ophthalmic device landscape fragments across clinical workflow stages, from diagnostic workup through surgical intervention and post-operative visual rehabilitation. Each segment category reflects distinct procurement channels, margin structures, and regulatory pathways that shape supplier positioning.
Product Type:
Clinical workflows span screening infrastructure, surgical intervention, and optical correction across public and private delivery channels.
- Diagnostic Equipment:Optical coherence tomography systems, fundus cameras, and visual field analyzers manufactured to ISO 13485 standards. Gauteng province's academic medical centers concentrate demand for multi-modal imaging platforms as diabetic retinopathy screening protocols expand into primary care networks.
- Surgical Instruments:Phacoemulsification handpieces, vitrectomy cutters, and microsurgical forceps fabricated from titanium and stainless steel alloys. Private hospital groups in Johannesburg drive replacement cycles for premium consumables through high-volume cataract programs.
- Lens & Lens Inserts:Hydrophilic acrylic intraocular lenses and premium toric designs for astigmatism correction. The National Department of Health's centralized tenders favor cost-optimized monofocal lenses for public sector cataract surgery.
- Vision Aids:Spectacle frames, contact lenses, and low-vision magnifiers distributed through retail optical chains and hospital dispensaries. Urban centers host denser penetration of premium progressive lens fitting services.
The dominant share belongs to Diagnostic Equipment, while Surgical Instruments is closing the gap fastest.
Application:
Volume concentration and margin profiles diverge sharply between high-frequency cataract programs and emerging retinal specialties.
- Cataract Surgery:Phacoemulsification and manual small-incision techniques for age-related lens opacity removal. Public hospital procurement in Gauteng and KwaZulu-Natal accelerates as the National Health Insurance benefit package expands surgical access.
- Retinal Procedures:Vitrectomy, laser photocoagulation, and intravitreal injection therapies for diabetic retinopathy and macular degeneration. Screening protocol mandates are pulling diagnostic equipment into provincial diabetes management programs.
- Glaucoma Treatment:Trabeculectomy, shunt implantation, and minimally invasive glaucoma surgery. Private clinics in Pretoria concentrate demand for advanced drainage device technologies.
- Refractive Surgery:LASIK, PRK, and phakic intraocular lens implantation for elective vision correction. Urban private hospital chains host the limited installed base of excimer laser platforms.
Cataract Surgery retains the deepest procedure volume, though Retinal Procedures is expanding most quickly.
End User:
Procurement authority and reimbursement pathways segment demand across institutional and consumer-directed channels.
- Hospitals:Tertiary academic centers and district hospitals performing surgical interventions under National Department of Health contracts. Public sector tender frameworks favor suppliers with ISO 13485 certification and established Gauteng service infrastructure.
- Ophthalmology Clinics:Private specialist practices and corporate chain clinics delivering diagnostic and refractive services. Johannesburg and Pretoria host the densest concentration of retinal imaging equipment outside hospital settings.
- Research Institutions:University medical schools and clinical trial sites evaluating novel surgical techniques and diagnostic algorithms. Academic medical centers in Gauteng coordinate multicenter studies for multinational device manufacturers.
- Homecare:Direct-to-consumer vision aids including reading spectacles, contact lens supplies, and low-vision devices. Retail optical chains dominate distribution through vertically integrated lens manufacturing partnerships.
Hospitals command the largest capital equipment budgets, while Ophthalmology Clinics is gaining share fastest.
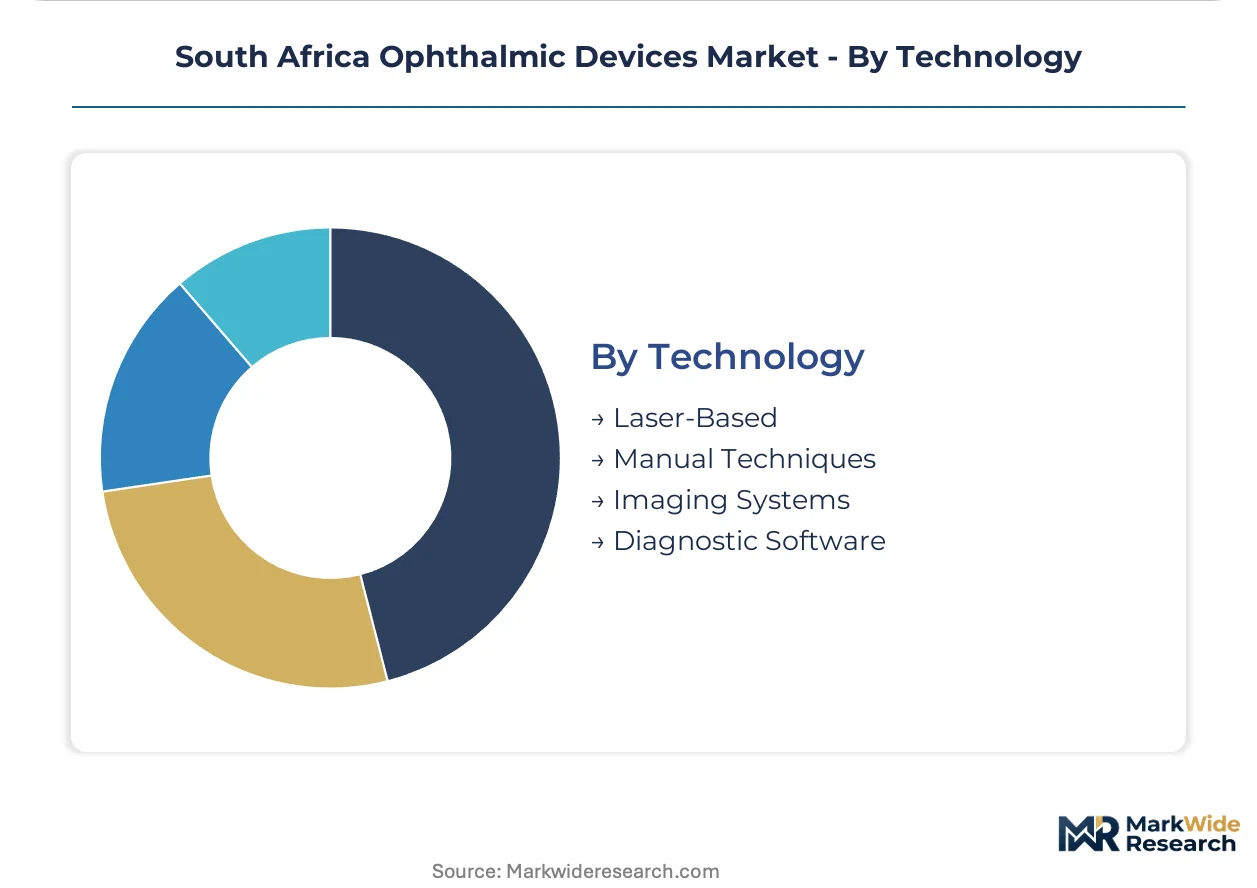
Technology:
Automation intensity and capital requirements stratify competitive positioning across the technology spectrum.
- Imaging Systems:Optical coherence tomography, fundus photography, and anterior segment imaging platforms. Diabetic retinopathy screening deadlines in provincial health departments are compressing deployment timelines for cloud-connected devices.
- Laser-Based:Femtosecond cataract platforms, excimer refractive systems, and retinal photocoagulation lasers. Private hospital groups in Johannesburg adopt replacement cycles of eighteen to twenty-four months for premium surgical consoles.
- Manual Techniques:Conventional extracapsular extraction and small-incision cataract surgery without phacoemulsification. Rural public hospitals retain manual methods where capital constraints limit technology acquisition.
- Diagnostic Software:Image analysis algorithms, electronic health record integration, and tele-ophthalmology platforms. Remote retinal interpretation capabilities are converging with cloud-based systems to enable rural screening without specialist presence.
Imaging Systems holds the dominant installed base, while Laser-Based platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province consumes ophthalmic devices differently than other South African regions, concentrating high-value diagnostic platforms in academic medical centers while KwaZulu-Natal and Western Cape rely more heavily on mobile screening units and tele-ophthalmology linkages for rural coverage.
Gauteng
Johannesburg and Pretoria host the densest clusters of ophthalmology clinics and private hospital chains, driving demand for femtosecond laser platforms and multi-modal imaging systems. The National Department of Health's centralized tender frameworks favor suppliers with ISO 13485 certification and established service infrastructure in this province. Academic medical centers in Johannesburg coordinate multicenter clinical trials for multinational device manufacturers.
KwaZulu-Natal
Durban's ophthalmology clinic density lags Gauteng by a factor of four, creating whitespace for diagnostic equipment distributors establishing regional service hubs. Provincial health departments mandate optical coherence tomography deployment in diabetes management programs, pulling equipment into primary care networks. The eThekwini Metropolitan Municipality anchors private hospital investment in coastal cataract surgery capacity.
Western Cape
Cape Town's university medical school drives research institution procurement for novel surgical technique evaluation and diagnostic algorithm development. The provincial health department's diabetic retinopathy screening protocols compress deployment timelines for cloud-connected imaging devices. Stellenbosch University's biomedical engineering programs partially address technician scarcity for device calibration.
Eastern Cape
Rural public hospitals in this province retain manual cataract extraction techniques where capital constraints limit phacoemulsification acquisition. The National Health Insurance benefit package revision targets this region for expanded surgical access, accelerating procurement timelines for accredited suppliers. Port Elizabeth concentrates limited private ophthalmology capacity.
Limpopo
Fly-in service models dominate laser system maintenance and handpiece repair in this northern province, given technician concentration in Gauteng. Tele-ophthalmology platforms enable rural clinic retinal screening without on-site specialist presence. Provincial tender processes increasingly recognize WHO prequalification status for multinational suppliers.
South Africa Ophthalmic Devices Market Competitive Landscape
Capability concentration sits with European and Japanese precision optics specialists; scale advantage sits with diversified healthcare conglomerates possessing vertically integrated lens manufacturing and retail distribution networks. The market structure tilts toward oligopoly in premium surgical platforms while fragmenting across vision aids and consumables. Three archetypes dominate: integrated lens manufacturers controlling spectacle distribution, surgical consumables specialists anchoring public hospital training programs, and diagnostic imaging technology leaders competing on optical coherence tomography innovation. M&A activity concentrates on retail optical chain consolidation; strategic partnerships focus on tele-ophthalmology platform integration with electronic health record systems.
Among the diversified healthcare conglomerates, Johnson & Johnson and Bausch + Lomb exemplify scale-driven positioning through broad surgical consumables portfolios and established public sector contracting relationships. Carl Zeiss occupies a position within the precision optics specialist tier, representing technology leadership in retinal imaging sub-specialties. These three companies anchor the competitive landscape without exhausting its structural diversity.
| Leading Market Players |
|---|
| Bausch + Lomb |
| EssilorLuxottica |
| Alcon |
| Topcon |
| CooperVision Inc. |
| Johnson & Johnson |
| HOYA |
| Nidek |
| Carl Zeiss |
| Others |
Value Network & Pricing Analysis
German and Japanese precision optics manufacturing concentrates upstream supply for phacoemulsification handpieces and optical coherence tomography components, anchoring margin capture in aftermarket service contracts and ISO 13485-certified consumables rather than capital equipment sales alone.
Pricing Analysis
Long-term service contracts with public teaching hospitals dominate procurement structures for diagnostic imaging platforms, while spot purchasing persists for consumable lens inserts. Three-tier pricing structure across premium femtosecond laser systems, standard phacoemulsification consoles, and economy manual surgical sets separates procurement tiers by certification grade and after-sales bundling intensity. Cost compression in economy-tier consumables is intensifying because the National Department of Health's centralized tenders prioritize volume-scale compliance over brand premium. Private hospital groups in Johannesburg exhibit the least price sensitivity, while rural public hospitals in Eastern Cape and Limpopo face acute budget constraints.
Supply Chain Analysis
Extended payment terms through development finance institution procurement windows are becoming standard for multinational suppliers entering provincial tender processes. Manufacturing concentration in Germany, Japan, and Switzerland feeds South Africa's demand for precision-engineered surgical instruments and diagnostic optics. Supply chains draw from hydrophilic acrylic polymer feedstocks, titanium alloys for microsurgical tools, and CMOS sensors for retinal imaging platforms. Single-source vulnerability concentrates in femtosecond laser component suppliers, where alternative sourcing requires lengthy regulatory requalification. Distribution runs through Johannesburg-based medical device distributors with Gauteng service infrastructure, then radiates to KwaZulu-Natal and Western Cape through regional hub arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among private hospital groups in Gauteng is shifting bargaining power toward concentrated buyers capable of unbundling service contracts from capital purchases, fragmenting traditional manufacturer-direct revenue streams.
For Market Incumbents: Build switching-cost moats through embedded biomedical engineering training programs at public teaching hospitals that create personnel dependency on proprietary calibration protocols. Anchor defensive positioning by securing WHO prequalification status for accelerated provincial tender access, while expanding captive repair capabilities in Durban to offset fly-in service vulnerabilities. The threat of independent service organizations capturing maintenance revenue demands urgent channel control investment in KwaZulu-Natal regional hubs. For New Entrants and Emerging Players: Mid-market ophthalmology clinics in Durban and Port Elizabeth represent the most penetrable entry point, given Gauteng's entrenched supplier relationships and dense service infrastructure. Tele-ophthalmology platform integration with provincial diabetes management programs offers a software-first go-to-market angle that bypasses capital-intensive diagnostic equipment sales. Target cloud-connected retinal screening devices for rural Limpopo clinics, where specialist scarcity creates demand for remote interpretation capabilities without on-site hardware investment. For Investors and Strategic Acquirers: Capital is best deployed toward independent service organizations with established Gauteng technician networks and expanding KwaZulu-Natal footprints, as unbundling trends accelerate across private hospital procurement. Long-term viability hinges on regulatory pathway acceleration capabilities and ISO 13485 certification infrastructure rather than pure manufacturing scale. Watch the National Health Insurance benefit package revision timeline as the critical inflection signal for public sector cataract program procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Compressed vendor qualification periods accelerate market access for imported surgical consumables entering Gauteng academic medical centers. |
| Provincial Hospital System Partnership | Centralized tender frameworks in KwaZulu-Natal favor suppliers with established regional service infrastructure and technician density. |
| Tele-ophthalmology Platform Integration | Cloud-connected retinal screening converges with electronic health record systems to enable rural clinic deployment without specialist presence. |
| WHO Prequalification Pathway | Prequalified status unlocks accelerated provincial tender processes and development finance institution procurement windows for multinational entrants. |
| Biomedical Engineering Training Program | Embedded calibration and preventive maintenance education at public teaching hospitals creates personnel dependency and switching costs. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers, ophthalmology clinic directors, and National Department of Health contracting officers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against SAHPRA registration databases, provincial health department tender records, and ISO certification registries. Bottom-up demand modeling triangulated against top-down expenditure estimates from public sector budget allocations and private hospital capital expenditure disclosures.
Scenario-bracketing around National Health Insurance implementation timelines and diabetic retinopathy screening protocol adoption rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application workflow stage, end-user procurement authority, and technology automation intensity. CAGRs derived from procedure volume trajectories, replacement cycle compression rates for laser platforms, and provincial health expenditure growth assumptions.
Macroeconomic conditions sit as an overlay; deviation in rand exchange rate volatility, import duty structures, or public health budget allocations would shift the trajectory materially. Forecasts reflect assumptions about regulatory pathway acceleration and technician pipeline development that warrant continuous validation against operating reality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market