
 Macular Edema Market | 2026-2036
Macular Edema Market Size, Share, and Industry Trends Forecast 2026-2036
Macular Edema Market Outlook
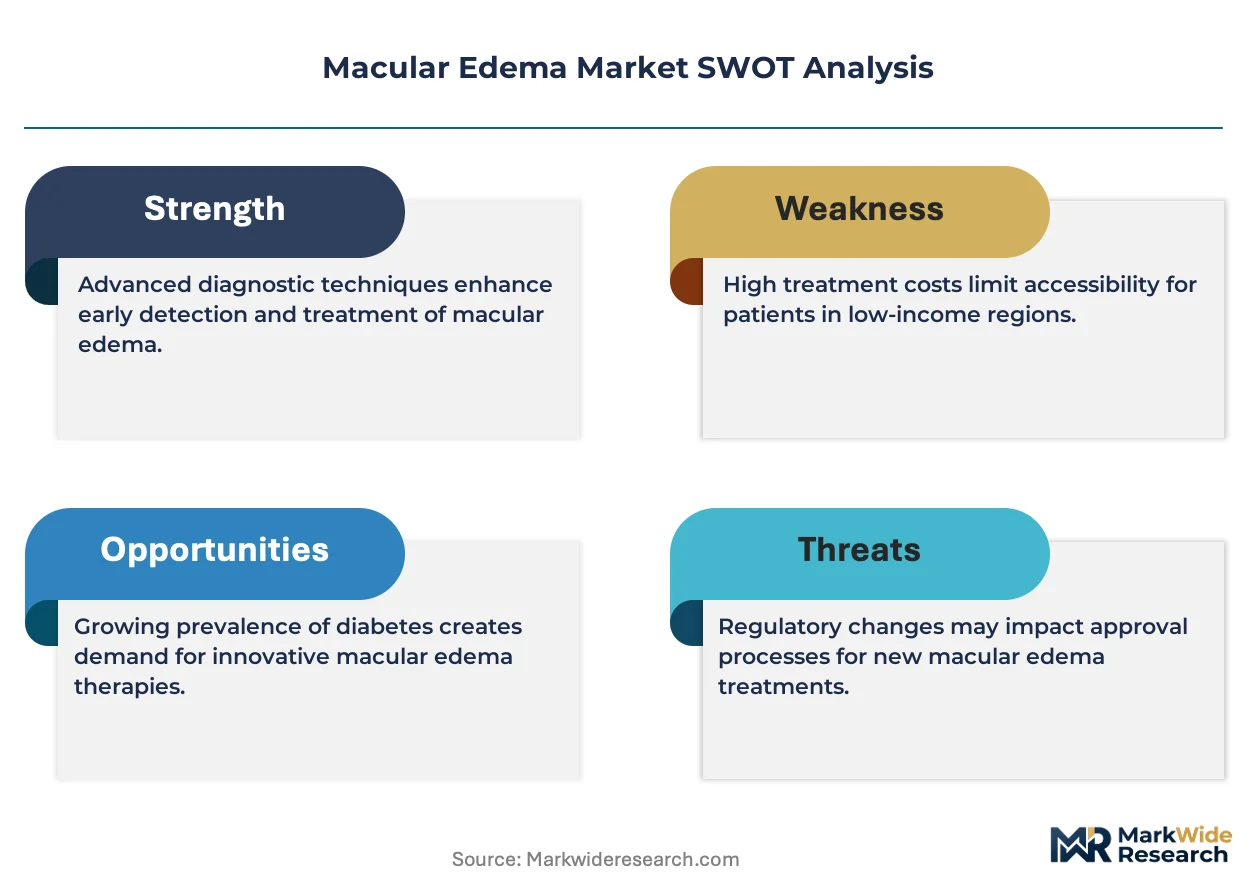
Project finance for specialty ophthalmology clinics is reconfiguring competitive dynamics in macular edema care, lowering capital barriers for independent practices and regional networks. Bayer AG leverages its integrated pharmaceutical-ophthalmology pipeline to sustain manufacturing scale across anti-VEGF and corticosteroid portfolios. Regeneron Pharmaceuticals Inc. anchors its position through technology leadership in intravitreal injection delivery systems. Novartis AG competes via geographic dominance in European and Asia-Pacific ophthalmology markets.
Macular edema denotes retinal thickening from fluid accumulation in the macula, typically measured by optical coherence tomography central subfield thickness exceeding 250-300 micrometers, with primary clinical purpose of preserving or restoring visual acuity in patients with diabetic retinopathy, retinal vein occlusion, or post-surgical inflammation. Anti-VEGF agents occupy the dominant margin pool due to first-line prescribing patterns across diabetic retinopathy and retinal vein occlusion indications, while intravitreal injection as a delivery mode leads volume throughput in hospital and clinic settings. Combination therapy represents the fastest-growing structural segment as physicians seek to reduce injection burden and address anti-VEGF non-responders.
The FDA governs biologic approval pathways and post-market surveillance for intravitreal agents, while the EMA's MDR framework shapes CE marking requirements for ophthalmic diagnostic and delivery devices in Europe. Reimbursement decisions by the Centers for Medicare & Medicaid Services directly determine site-of-care economics and physician prescribing incentives in the United States. Stakeholders must monitor evolving biosimilar entry timelines and real-world evidence requirements that will reshape competitive positioning and access dynamics.
Market Dynamics
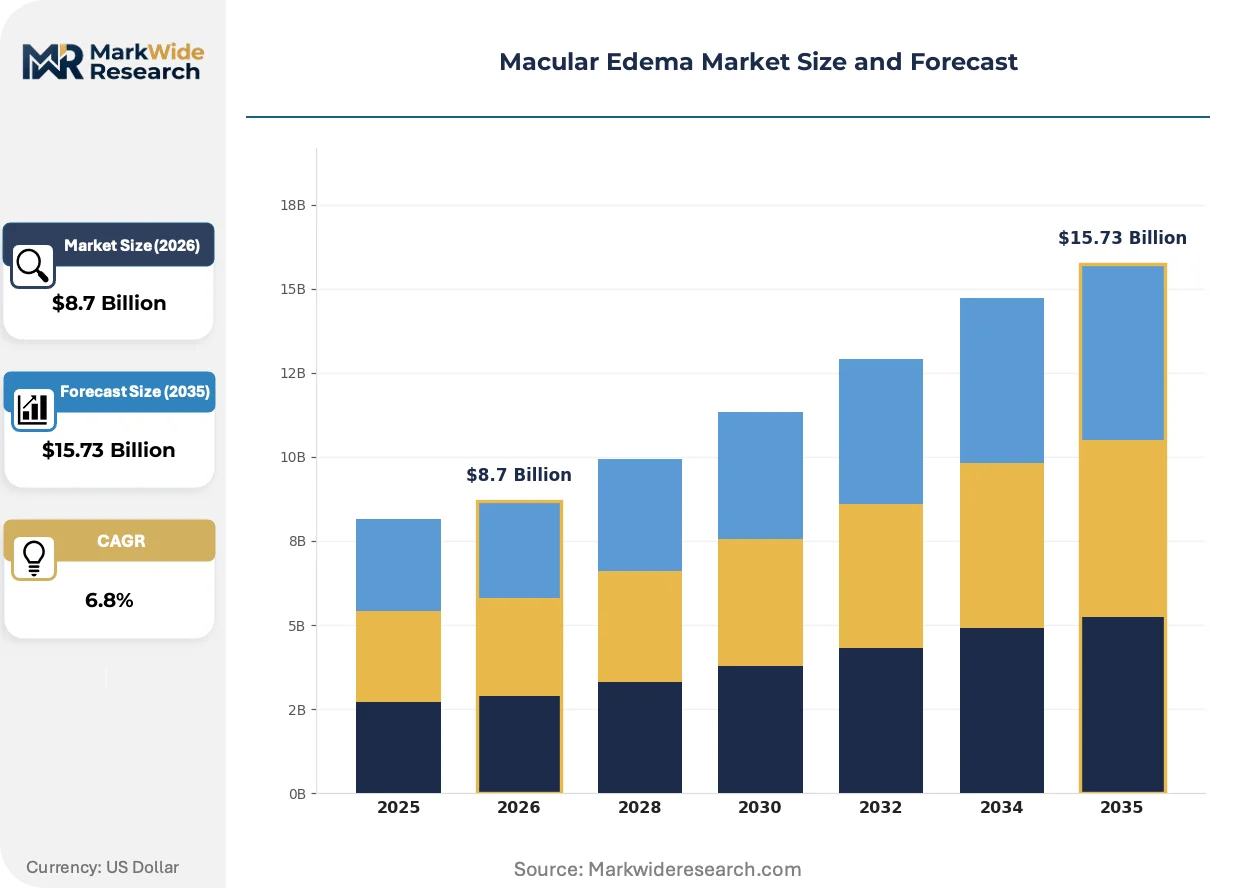
The macular edema treatment landscape is undergoing structural reconfiguration as Medicare reimbursement policies compress site-of-care economics and force independent ophthalmology practices toward alternative capital structures.
Growth Catalysts
- Anti-VEGF biosimilar pathways:The FDA's abbreviated biologics license application framework accelerates competitor entry into first-line diabetic retinopathy therapy, expanding physician formulary flexibility and patient access across Medicare Part B reimbursement structures.
- Optical coherence tomography angiography:This non-invasive imaging modality enables earlier detection of subclinical macular thickening, driving diagnostic volume expansion in retina specialist practices and community ophthalmology clinics.
- Intravitreal injection protocols:Treat-and-extend regimens reduce patient visit burden while preserving visual outcomes, concentrating procedure volume in high-throughput ambulatory surgical centers with dedicated retina nursing staff.
Market Restraints
- Biologic cold chain requirements:Anti-VEGF agents require continuous 2-8°C storage from manufacturing through intravitreal administration, elevating infrastructure costs for smaller ophthalmology practices without hospital pharmacy partnerships.
- Retina specialist supply concentration:Fellowship-trained medical retina physicians cluster in metropolitan academic medical centers, creating access deserts in rural counties across the United States.
- Medicare sequestration mechanics:Automatic payment reductions under the Budget Control Act compress physician practice margins on intravitreal injection services, disincentivizing capacity expansion.
Strategic Opportunities
- Sustained-release corticosteroid implants:Dexamethasone and fluocinolone acetonide intravitreal inserts address anti-VEGF non-responders and reduce injection frequency burden in diabetic macular edema patients with significant cardiovascular comorbidity.
- Teleophthalmology screening networks:Remote diabetic retinopathy evaluation programs in Federally Qualified Health Centers identify treatment-naive macular edema cases earlier, creating referral pipeline opportunities for affiliated retina specialists.
- 340B Drug Pricing Program participation:Hospital-owned ophthalmology clinics leverage federal ceiling pricing on anti-VEGF biologics to subsidize uncompensated care and fund satellite clinic expansion into underserved counties.
Industry Challenges
- Intravitreal injection certification timelines:State medical board scope-of-practice variations create regulatory friction for optometrist-administered anti-VEGF therapy, limiting workforce expansion options.
- Real-world evidence collection infrastructure:Payer mandates for outcomes data submission require electronic health record integration investments that strain independent practice capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macular Edema Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, Laser Therapy, Combination Therapy Therapy Area: Diabetic Retinopathy, Retinal Vein Occlusion, Uveitis, Age-Related Macular Degeneration End User: Hospitals, Ophthalmology Clinics, Research Institutions, Home Care Settings Delivery Mode: Intravitreal Injection, Topical Application, Systemic Administration, Others |
| Companies Covered | Bayer AG, AbbVie Inc, Novartis AG, Bausch Health Companies Inc., Genentech, Regeneron Pharmaceuticals Inc., Alimera Sciences Inc., GlaxoSmithKline Plc, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macular Edema Market Strategic Shifts
Retina therapeutics is experiencing modality diversification as sustained-release formulations and gene therapy candidates challenge the injection-frequency paradigm established by monthly biologic administration.
Port delivery systems for ranibizumab are migrating from clinical trial settings into commercial practice, enabling six-month refill intervals through permanent intravitreal implants. Retina specialists in high-volume academic centers are adopting these devices for chronic diabetic macular edema patients with poor injection adherence. The technology is compressing visit frequency requirements and shifting practice revenue models toward device implantation procedures rather than recurring injection visits.
The FDA's Real-World Evidence program is accelerating post-market surveillance requirements for ophthalmic biologics, mandating systematic collection of visual acuity and anatomical outcomes data. Manufacturers must now fund registry infrastructure or partner with electronic health record vendors to satisfy pharmacovigilance obligations. Anti-VEGF agents with longer market tenure face heightened scrutiny as biosimilar competitors enter with real-world evidence generation capabilities built into launch protocols.
Patient self-referral patterns are fragmenting traditional retina specialist gatekeeping, with direct-to-consumer advertising driving demand for anti-VEGF therapy among diabetic patients without established ophthalmology relationships. Optometry practices in California and Texas are responding by hiring retina-trained staff or forming management services organizations with affiliated ophthalmologists. This channel evolution is most visible in Sun Belt states with high diabetic prevalence and limited historical retina specialist density.
Macular Edema Market Segmentation
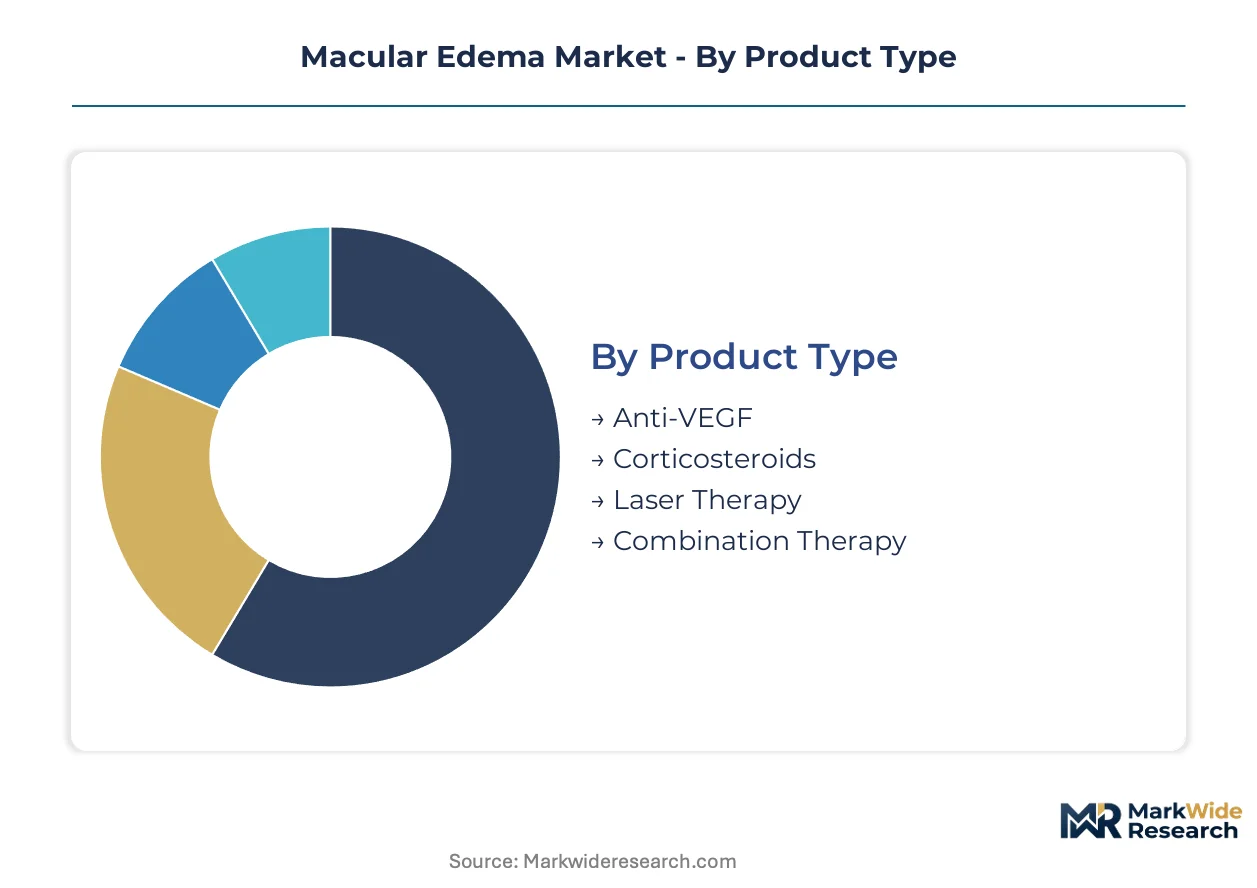
Treatment modality selection in macular edema care hinges on reimbursement pathways, injection infrastructure, and patient comorbidity profiles. Segmentation reveals how site-of-care economics and therapeutic response patterns concentrate demand across distinct product and delivery categories.
Product Type:
After-sales service intensity varies sharply across product categories, with intravitreal biologics demanding cold chain maintenance, compounding pharmacy partnerships, and adverse event reporting infrastructure that corticosteroid implants and laser systems do not replicate.
- Anti-VEGF:Biologic agents targeting vascular endothelial growth factor require continuous refrigeration from manufacturing through administration. United States retina specialists concentrate prescription volume here due to Medicare Part B reimbursement mechanics that reward frequent injection visits.
- Corticosteroids:Dexamethasone and fluocinolone acetonide intravitreal implants address anti-VEGF non-responders with sustained-release pharmacokinetics reducing visit burden. Demand concentrates in diabetic macular edema patients with cardiovascular contraindications to repeated anesthesia exposure.
- Laser Therapy:Focal/grid photocoagulation serves cost-sensitive markets and patients with poor injection adherence.
- Combination Therapy:Simultaneous anti-VEGF and corticosteroid administration targets refractory cases.
By volume, Anti-VEGF leads. By growth pace, Combination Therapy is ahead.
Therapy Area:
Cost tier stratification across indications reflects disease prevalence, treatment duration, and competitive intensity in each therapeutic domain.
- Diabetic Retinopathy:The largest addressable population among therapy areas, diabetic macular edema drives sustained anti-VEGF demand through chronic treatment models. United States Federally Qualified Health Centers generate referral volume through teleophthalmology screening programs.
- Retinal Vein Occlusion:Acute vision-threatening presentation mandates rapid anti-VEGF initiation with shorter overall treatment duration than diabetic indications. Branch and central subtypes differ in anatomical response patterns.
- Uveitis:Inflammatory macular edema responds preferentially to corticosteroid therapy over anti-VEGF agents.
- Age-Related Macular Degeneration:Neovascular AMD with concomitant edema represents crossover prescribing from retina specialists' wet AMD practices.
By patient volume, Diabetic Retinopathy dominates. By unmet need intensity, Uveitis shows the steepest expansion trajectory.
End User:
Customer type determines capital deployment patterns, with hospital systems leveraging 340B pricing advantages against independent clinic efficiency models.
- Hospitals:Academic medical centers concentrate fellowship-trained retina specialists and clinical trial access. 340B Drug Pricing Program participation subsidizes anti-VEGF acquisition costs for hospital-owned ophthalmology departments.
- Ophthalmology Clinics:Independent and network-affiliated practices drive procedure volume through dedicated ambulatory surgical centers. United States Medicare sequestration mechanics compress margins on injection services here.
- Research Institutions:Phase III trial sites generate early exposure to port delivery systems and gene therapy candidates.
- Home Care Settings:Limited current penetration; topical NSAID therapy for post-surgical edema represents the primary application.
By procedure throughput, Ophthalmology Clinics lead. By pricing power, Hospitals are expanding most quickly.
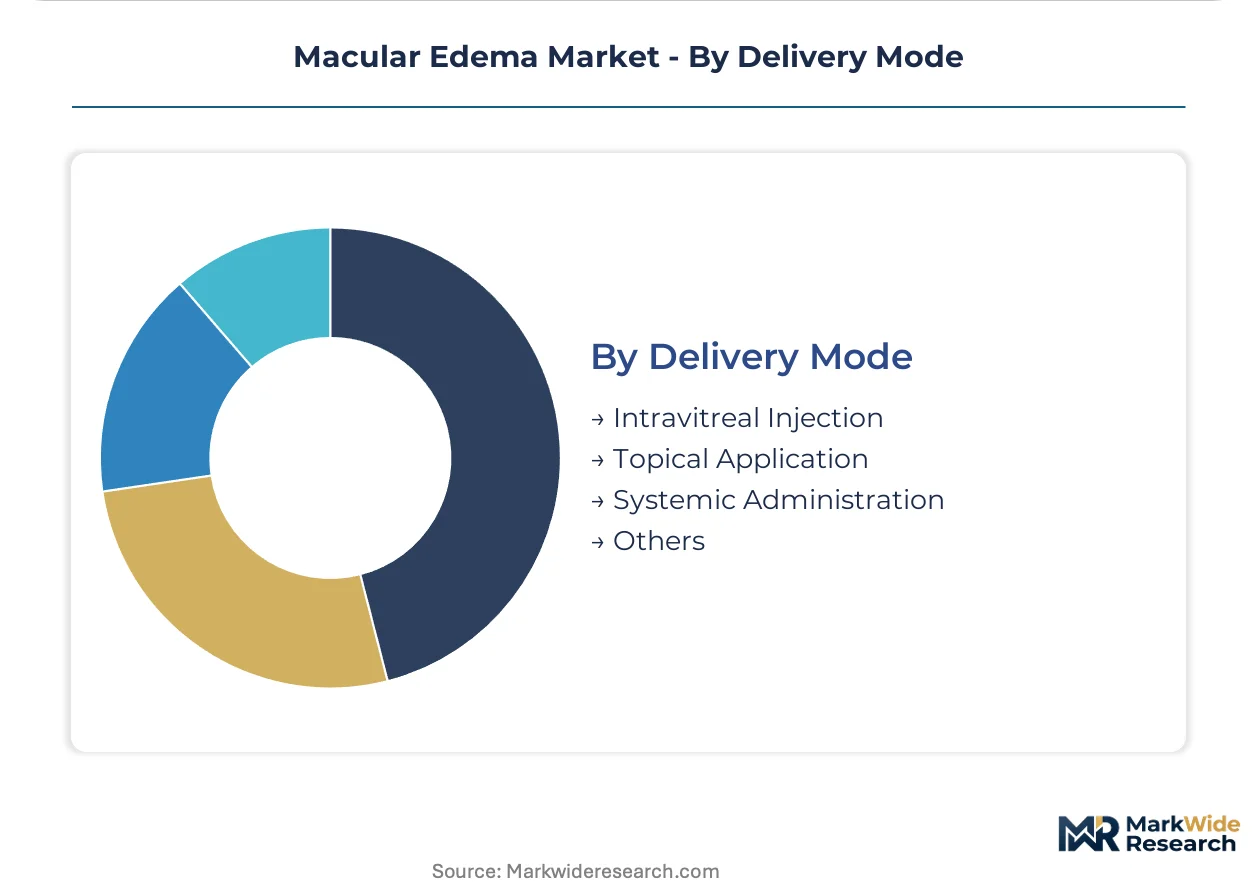
Delivery Mode:
Supply concentration in intravitreal administration reflects regulatory barriers to alternative routes and anatomical constraints of posterior segment drug delivery.
- Intravitreal Injection:Direct vitreous cavity administration achieves therapeutic drug levels unattainable by systemic or topical routes. Treat-and-extend protocols concentrate volume in high-throughput United States ambulatory surgical centers with dedicated retina nursing staff.
- Topical Application:NSAID drops address mild post-cataract macular edema with minimal infrastructure requirements. Community ophthalmology practices in India and Brazil favor this route for cost-sensitive patients.
- Systemic Administration:Oral or intravenous corticosteroids serve uveitis-associated edema when ocular delivery is contraindicated.
- Others:Periocular injection and sustained-release implants represent evolving delivery technologies.
By current utilization, Intravitreal Injection leads. By innovation investment, Others are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement mechanics in the United States compress site-of-care economics and reshape capital deployment patterns for ophthalmology practices. European EMA frameworks accelerate biosimilar entry timelines. Asian markets grapple with retina specialist density constraints against surging diabetic prevalence.
United States
Diabetic macular edema drives sustained anti-VEGF demand through chronic treatment models requiring frequent intravitreal administration. The Centers for Medicare & Medicaid Services directly determines physician prescribing incentives through Part B reimbursement structures. Retina specialists cluster in metropolitan academic medical centers across Massachusetts, Pennsylvania, and California, creating access deserts in rural counties throughout the Southeast and Mountain West.
Germany
EMA's MDR framework shapes CE marking requirements for ophthalmic diagnostic and delivery devices entering European commercialization pathways. The national reimbursement system maintains favorable positioning for sustained-release corticosteroid implants in anti-VEGF non-responder populations. Industrial concentration in Baden-Württemberg and Bavaria hosts manufacturing scale for intravitreal delivery systems and optical coherence tomography platforms.
Japan
PMDA regulatory pathways govern biologic approval timelines for ranibizumab biosimilars seeking market entry against established anti-VEGF franchises. METI industrial policy supports domestic ophthalmic device manufacturing through targeted R&D subsidies. The Kanto region surrounding Tokyo concentrates fellowship-trained retina specialists and high-throughput ambulatory surgical centers serving aging diabetic populations.
India
CDSCO accelerated approval pathways for biosimilar anti-VEGF agents expand physician formulary flexibility in cost-sensitive diabetic retinopathy markets. The country's national pharmaceutical regulator maintains pharmacovigilance requirements for intravitreal biologics administered in tertiary care settings. Maharashtra and Karnataka host expanding ophthalmology clinic networks leveraging teleophthalmology screening programs to identify treatment-naive macular edema cases in Federally Qualified Health Center equivalents.
Brazil
ANVISA regulatory frameworks govern importation and distribution of temperature-sensitive anti-VEGF biologics requiring continuous cold chain maintenance. The national health system reimbursement policies concentrate intravitreal injection capacity in São Paulo and Rio de Janeiro metropolitan corridors. Regional disparities in retina specialist density drive patient migration patterns from Northeastern states toward Southeastern treatment hubs.
Macular Edema Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market structures defined by manufacturing scale and therapeutic modality breadth. The vendor base organizes around three strategic archetypes: integrated pharmaceutical-ophthalmology conglomerates, biologics-focused innovators, and regional generic-biosimilar manufacturers. Dominant competitive moves include backward integration into sustained-release formulation technology and geographic expansion through management services organization partnerships with independent retina practices.
Within the integrated pharmaceutical tier, Bayer AG and Novartis AG occupy positions defined by cross-portfolio manufacturing scale spanning anti-VEGF and corticosteroid therapeutic categories. Regeneron Pharmaceuticals Inc. exemplifies the biologics-specialist archetype through concentration on intravitreal delivery system innovation. These three entities anchor competitive dynamics as biosimilar entry timelines compress margin structures for first-line diabetic retinopathy therapies.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie Inc |
| Novartis AG |
| Bausch Health Companies Inc. |
| Genentech |
| Regeneron Pharmaceuticals Inc. |
| Alimera Sciences Inc. |
| GlaxoSmithKline Plc |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on temperature-controlled biologic manufacturing in Switzerland and Ireland determines both pricing tier spreads and supply chain shape for anti-VEGF therapies. Cold chain infrastructure requirements compress margins for independent ophthalmology practices while hospital systems leverage 340B ceiling pricing to capture volume.
Pricing Analysis
Certification level creates the primary spread across FDA-approved originator biologics, EMA-authorized biosimilars, and CDSCO-accelerated generic alternatives. Pricing stratifies across premium branded anti-VEGF agents, standard biosimilar equivalents, and economy-tier compounded bevacizumab, with Medicare Part B reimbursement mechanics anchoring physician prescribing incentives. Cost compression in the standard tier intensifies as ranibizumab biosimilars enter United States formularies. Federally Qualified Health Centers exhibit highest price sensitivity due to uncompensated care burdens, while academic medical centers command premium positioning through clinical trial access.
Supply Chain Analysis
Contract manufacturing concentration at Lonza, Boehringer Ingelheim, and Samsung Biologics anchors global anti-VEGF production capacity. Active pharmaceutical ingredient synthesis concentrates in Switzerland, fill-finish operations cluster in Ireland and Singapore, and final packaging distributes through regional hubs in the United States and Germany. Supply chain risk rests on single-source fill-finish lines for high-potency biologics requiring aseptic processing. Distribution runs through specialty pharmacy networks with validated cold chain documentation, bypassing traditional wholesale channels for temperature-sensitive intravitreal agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital systems consolidating ophthalmology service lines through management services organization structures, fragmenting independent practice negotiating leverage against manufacturers.
For Market Incumbents: Pre-empt biosimilar erosion by backward integration into sustained-release implant manufacturing and captive supply of corticosteroid active pharmaceutical ingredients. Anchor formulary position through real-world evidence generation partnerships with electronic health record vendors, defending against emerging entrants with built-in pharmacovigilance infrastructure. For New Entrants and Emerging Players: Pursue white-space opportunity in teleophthalmology-enabled diagnostic networks serving rural counties with retina specialist access deserts. Target Federally Qualified Health Center partnerships as the most penetrable channel, deploying optometrist-administered screening protocols with remote ophthalmologist oversight as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA Real-World Evidence program mandates reshape the acquisition landscape by elevating registry infrastructure to strategic asset status. Five-to-ten year viability favors targets with integrated data collection capabilities and hospital system anchor contracts. Monitor CMS Medicare sequestration mechanics as the signal to detect site-of-care economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Port Delivery System Commercialization | Six-month refill intervals shift revenue models toward device implantation procedures in academic centers. |
| Biosimilar Real-World Evidence Generation | Registry infrastructure partnerships satisfy FDA pharmacovigilance obligations ahead of originator agents. |
| 340B Program Participation Expansion | Hospital-owned clinics subsidize anti-VEGF acquisition costs to fund satellite expansion into underserved counties. |
| Teleophthalmology Network Integration | Remote diabetic retinopathy screening creates referral pipelines for affiliated retina specialists. |
| Sustained-Release Formulation Development | Dexamethasone and fluocinolone acetonide implants address anti-VEGF non-responders with reduced visit burden. |
Study Parameters
Desk research of FDA approval documents, EMA MDR submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases preceded structured interviews with retina specialists, hospital formulary directors, ophthalmology clinic operations managers, and 340B program administrators. Secondary validation drew from SEC 10-K pharmaceutical filings, GPO contract databases, and ophthalmic device import records. Bottom-up patient volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Assumptions held fixed include current FDA biosimilar approval timelines, Medicare Part B reimbursement mechanics, and retina specialist fellowship graduation rates; variables tested include EMA MDR enforcement intensity, state-level optometrist scope-of-practice expansion, and 340B program legislative modification. Segmentation dimensions modeled encompass treatment modality, therapy area, end-user site-of-care, and delivery mode. CAGRs derived from logistic diffusion curves for sustained-release technologies and linear extrapolation for mature anti-VEGF markets. Forecast inputs incorporated diabetic prevalence projections and intravitreal injection protocol adoption rates.
Macroeconomic conditions sit as an overlay; deviation in Medicare sequestration mechanics, biologic cold chain logistics costs, or retina specialist geographic distribution would shift the trajectory. Forecasts reflect documented assumptions regarding biosimilar entry sequencing and reimbursement policy continuity. Quarterly review of CMS physician fee schedule updates, FDA biosimilar approval decisions, and state medical board scope-of-practice rulings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Vitreous Detachment Treatment Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Aphakia Market
Ophthalmology
North America Vision Care Market
Ophthalmology
Artificial Iris Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Retina Health Market