
 Synoptophore Market | 2026-2036
Synoptophore Market Size, Share, and Industry Trends Forecast 2026-2036
Synoptophore Market Intelligence
EU MDR is consolidating the cost-of-entry calculus for ophthalmic diagnostic manufacturers seeking CE-marked distribution. Haag-Streit leverages its Swiss-German manufacturing base to sustain premium positioning across European hospital procurement channels. Gem Optical Instruments Industries anchors its competitiveness in South Asian private clinic segments through localized mechanical unit production. Takagi Seiko differentiates via sensor-based integration in digital synoptophore platforms for Japanese domestic demand.
A synoptophore is a binocular instrument employing angled optical pathways and adjustable mirrors to present dissociated images to each eye, enabling measurement and treatment of ocular alignment disorders such as strabismus and amblyopia. The device operates through calibrated haploscopic projection, with typical convergence-divergence ranges of 20 prism diopters and illumination controls for afterimage generation and fusional training. Portable and digital product types now lead segment momentum as ambulatory vision therapy shifts beyond hospital settings, while mechanical units retain dominance in price-sensitive emerging markets where power reliability constrains electronic dependency. Among end users, ophthalmologists and private clinics represent the fastest-growing demand pool as direct-to-specialist distribution shortens replacement cycles.
FDA 510(k) clearance pathways and EU MDR Class IIa designation shape product development timelines and clinical evidence requirements for synoptophore manufacturers targeting transatlantic markets. ISO 13485 quality management certification operates as a baseline procurement filter across institutional buyers in North America and Europe. Stakeholders must monitor how virtual reality-based vision therapy applications alter reimbursement categorization and capital equipment prioritization in eye care budgets.
Market Dynamics
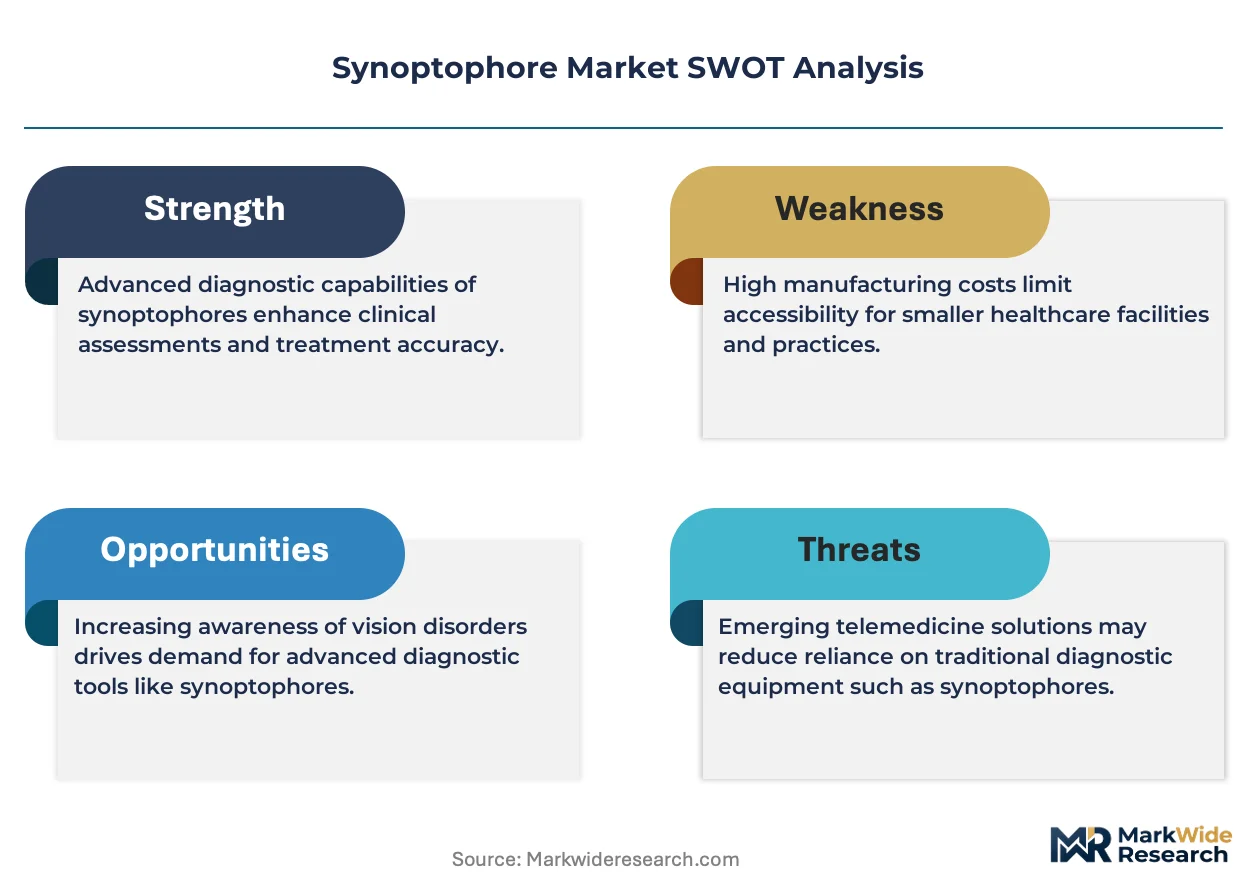
Digital sensor integration is compressing replacement cycles across ambulatory vision therapy settings, forcing mechanical unit manufacturers to defend installed base through service contracting rather than hardware refresh.
Growth Catalysts
- Pediatric strabismus screening mandates:National health systems in Germany and Japan now require early childhood binocular vision assessment, expanding clinic procurement quotas for diagnostic-grade synoptophores.
- EU MDR Class IIa pathway:The regulation's tightened clinical evidence requirements for ophthalmic diagnostics are filtering out marginal competitors and concentrating demand among ISO 13485-certified suppliers.
- Ambulatory vision therapy expansion:Private ophthalmology clinics in South Asia are installing portable units to capture walk-in patients outside hospital referral networks.
Market Restraints
- Optical-grade sensor cost volatility:CMOS image sensor pricing fluctuates with semiconductor foundry allocation, squeezing margins on digital synoptophore assemblies.
- Supply concentration in precision optics:German and Swiss lens grinding houses control critical haploscopic mirror supply, creating single-source vulnerability for mid-tier manufacturers.
- Power infrastructure dependency:Electronic unit penetration remains capped in South Asian and African markets where grid reliability forces continued reliance on mechanical alternatives.
Strategic Opportunities
- Tele-ophthalmology integration:Remote diagnostic platforms in Australian and Canadian rural health networks create demand for synoptophores with cloud-connected measurement logging.
- Virtual reality convergence:VR headset manufacturers are licensing haploscopic IP to develop consumer-grade amblyopia training modules, opening royalty revenue streams for device patent holders.
- India's PLI scheme for medical devices:Domestic production incentives are lowering landed costs for South Asian private clinic segments previously served by imports.
Industry Challenges
- ISO 13485 audit backlog:Certification body capacity constraints in Europe are extending quality management system approval timelines by eight to fourteen months for new market entrants.
- Legacy mechanical unit serviceability:Declining availability of analog mirror adjustment components forces manufacturers to maintain obsolete parts inventories or abandon installed base support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synoptophore Market |
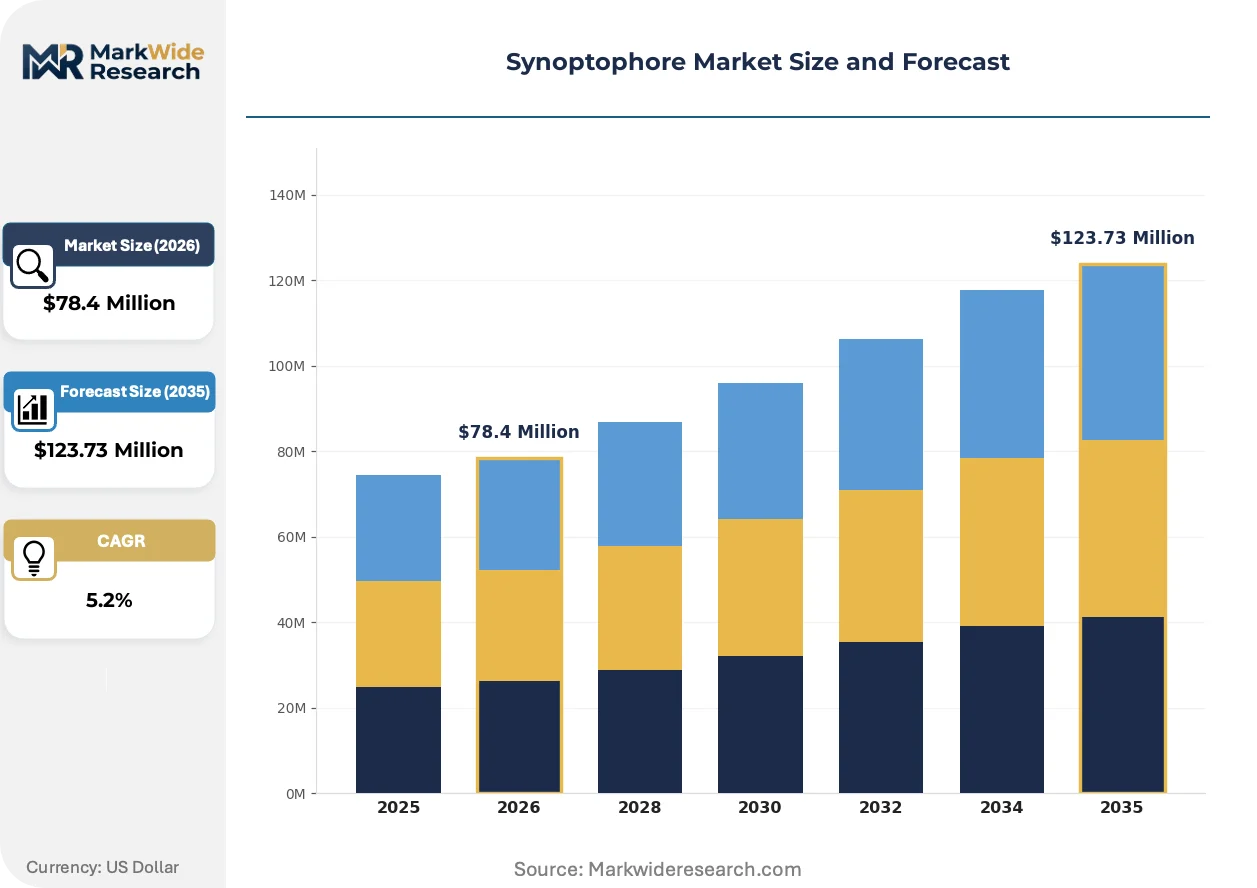
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Digital, Mechanical, Multisensory End User: Ophthalmologists, Rehabilitation Centers, Hospitals, Private Clinics Technology: Optical Alignment, Sensor-Based, Computer-Aided, Virtual Reality Application: Strabismus Treatment, Vision Therapy, Diagnostic Testing, Educational Use |
| Companies Covered | 66 Vision Tech, Gem Optical Instruments Industries, Haag-Streit, Rumax International, Takagi Seiko, Appasamy Associates, Prkamya Visions, Oculus, Nanjing Redsun Optical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synoptophore Market Strategic Shifts & Innovations
Sensor-based digital architectures are displacing purely mechanical haploscopic systems across premium clinic segments, while regulatory harmonization pressures reshape product development roadmaps for transatlantic suppliers.
CMOS-based digital image projection is consolidating control over convergence-divergence measurement precision that mechanical mirror systems previously dominated. Japanese and German ophthalmology clinics are adopting these platforms for pediatric strabismus protocols where repeatability standards exceed mechanical tolerance limits. The technology is consolidating supplier margins around software-enabled service subscriptions rather than discrete hardware sales.
EU MDR's post-market surveillance requirements now mandate systematic clinical follow-up data for Class IIa ophthalmic diagnostics, extending product development timelines by twelve to eighteen months. Manufacturers must maintain notified body relationships across multiple EU member states to sustain CE-marked distribution. Digital synoptophore platforms face heightened scrutiny for software validation under the regulation's Annex I general safety and performance requirements.
Direct-to-specialist distribution is shortening replacement cycles as ophthalmology clinics bypass hospital procurement committees for capital equipment decisions. Independent private practices in Germany and Switzerland now source portable units through manufacturer field representatives rather than group purchasing organizations. This channel compression is most visible in metropolitan clusters where clinic density supports dedicated sales territories.
Synoptophore Market Segmentation
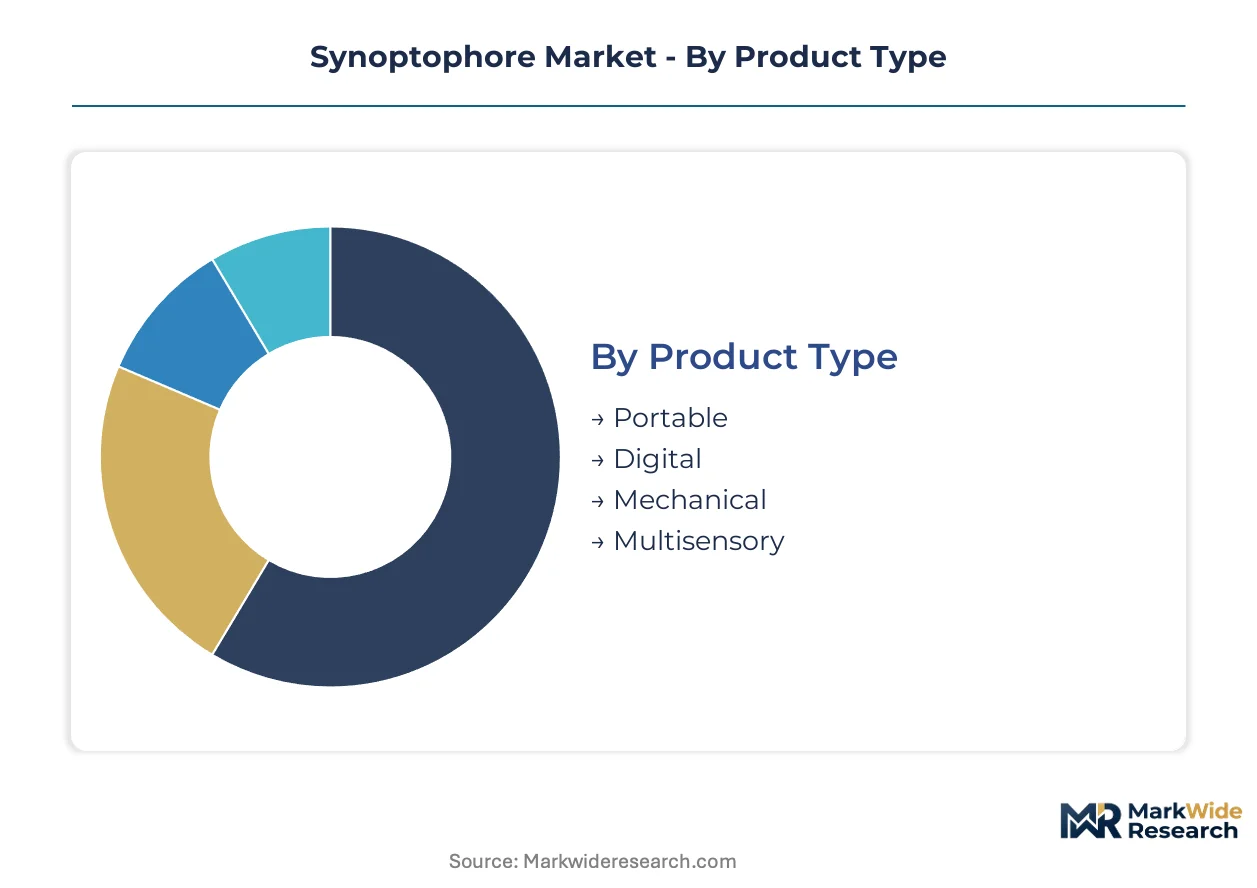
Synoptophore procurement patterns diverge sharply between institutional buyers seeking diagnostic precision and ambulatory operators prioritizing mobility. Segmentation reveals how technology integration depth and end-user economics reshape competitive positioning across hardware tiers.
Product Type:
Standalone mechanical units serve price-constrained clinics without reliable power infrastructure, while embedded digital architectures dominate premium vision therapy protocols requiring measurement repeatability.
- Portable:Battery-operated compact housings with collapsible optical arms enable field deployment in rural screening programs. Demand concentrates in Indian private clinics capturing walk-in patients outside hospital networks, constrained by CMOS sensor import duties under the country's PLI scheme for medical devices.
- Digital:CMOS-based projection systems with software-controlled convergence-divergence calibration displace mechanical mirrors in Japanese pediatric ophthalmology protocols. Clinics in Tokyo and Osaka adopt these platforms where repeatability standards exceed analog tolerance limits, consolidating supplier margins around subscription-enabled service models.
- Mechanical:Purely optical haploscopic systems with manual mirror adjustment retain installed base in South Asian markets with grid reliability concerns.
- Multisensory:Integrated auditory and tactile feedback modules for pediatric patient engagement in German rehabilitation centers.
Volume placements concentrate in mechanical units across emerging markets; the faster expansion belongs to digital platforms in premium clinic segments.
End User:
Procurement authority decentralization is shortening replacement cycles as specialist practices bypass hospital committees for capital equipment decisions.
- Ophthalmologists:Independent practitioners in German metropolitan clusters source portable units through manufacturer field representatives rather than group purchasing organizations. Direct-to-specialist distribution compresses decision timelines from twelve months to six weeks in Berlin and Munich clinic densities.
- Private Clinics:Ambulatory vision therapy operators in South Asia install entry-level mechanical units to capture referral-independent patient flows. Power infrastructure volatility caps electronic penetration, forcing continued reliance on mirror-based systems in Bangalore and Hyderabad private practices.
- Hospitals:Integrated health systems in Japan and Germany maintain centralized procurement for diagnostic-grade equipment with ISO 13485 certification requirements.
- Rehabilitation Centers:Post-surgical vision therapy facilities requiring extended fusional training protocols.
Revenue concentration tilts toward ophthalmologist practices; private clinics are climbing the fastest as ambulatory care decentralization accelerates.
Technology:
Sensor integration depth determines pricing tier and regulatory pathway complexity across transatlantic markets.
- Sensor-Based:CMOS image sensors with real-time convergence angle logging enable cloud-connected measurement archives for Australian tele-ophthalmology networks. Semiconductor foundry allocation volatility squeezes margins on these assemblies, creating procurement urgency during supply windows.
- Optical Alignment:Traditional angled mirror systems with calibrated prism diopter scales dominate mechanical product lines. German and Swiss lens grinding houses control critical haploscopic mirror supply, creating single-source vulnerability for mid-tier manufacturers sourcing components from Stuttgart and Zurich suppliers.
- Computer-Aided:Software-driven projection with automated fusional range calculation.
- Virtual Reality:Headset-based dissociated image presentation for consumer-accessible amblyopia training modules.
Installed base remains heaviest in optical alignment; sensor-based architectures are gaining share fastest as digital refresh cycles compress.
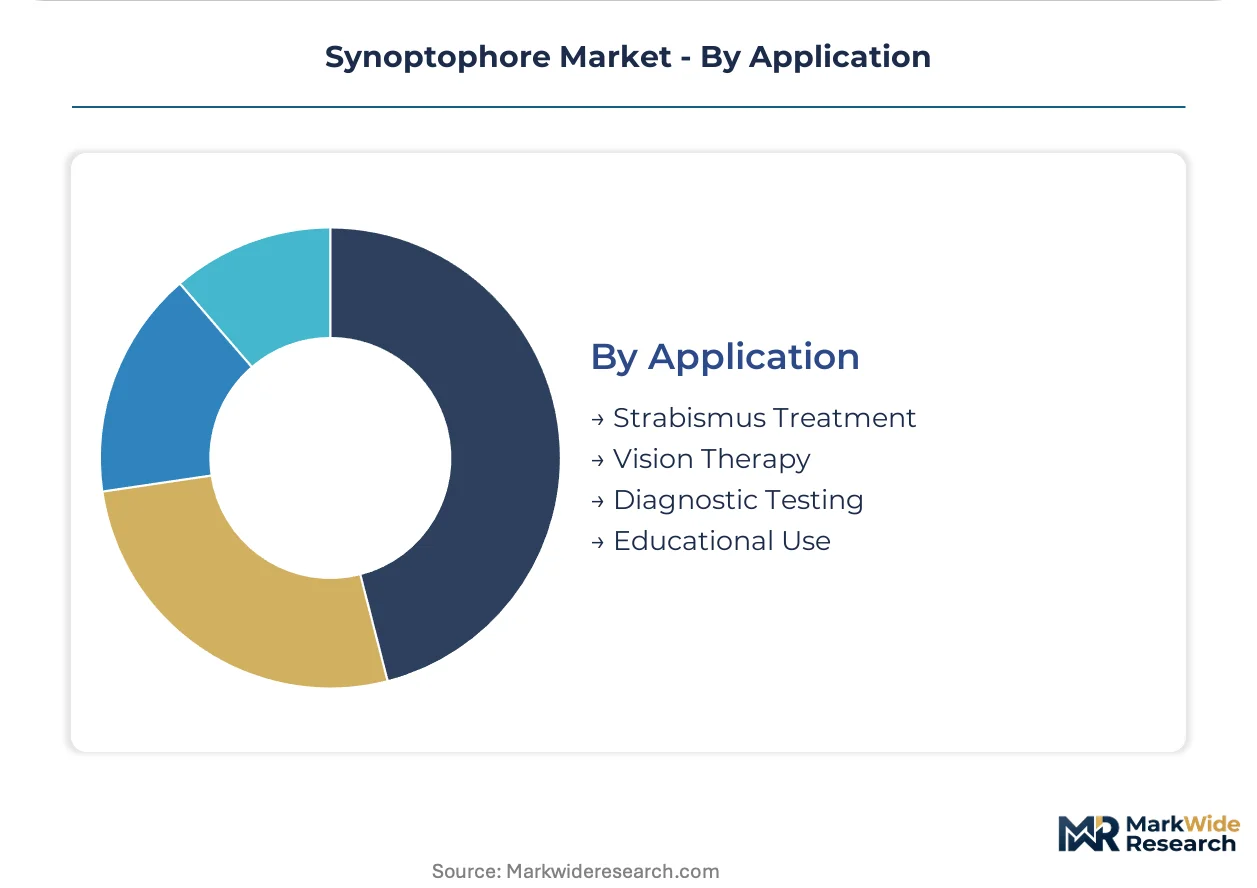
Application:
Reimbursement categorization shifts are elevating diagnostic testing relative to therapeutic protocols in capital equipment prioritization.
- Diagnostic Testing:Quantitative strabismus angle measurement with documented repeatability for pediatric screening mandates. German and Japanese national health systems now require early childhood binocular vision assessment, expanding clinic procurement quotas for diagnostic-grade synoptophores in Hamburg and Osaka.
- Strabismus Treatment:Therapeutic fusional training with adjustable prism diopter progression. Rehabilitation centers in Switzerland combine these protocols with orthoptic follow-up, though reimbursement compression is lengthening equipment depreciation schedules in Geneva and Zurich practices.
- Vision Therapy:Amblyopia suppression treatment with afterimage generation.
- Educational Use:Training instruments for orthoptic certification programs in university hospitals.
Procurement volume clusters in diagnostic testing; vision therapy applications are expanding most quickly as private clinics diversify revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's medical device parks in Andhra Pradesh and Telangana concentrate assembly capacity for export-oriented ophthalmic equipment, drawing component suppliers from Stuttgart and Zurich into local joint ventures with domestic fabricators.
Germany
Specialized eye care infrastructure in Hamburg and Munich sustains faster upgrade cycles for diagnostic-grade equipment. EU MDR Class IIa designation tightens clinical evidence requirements, filtering procurement toward ISO 13485-certified suppliers. The Stuttgart precision optics cluster controls critical haploscopic mirror supply for mid-tier manufacturers across Europe.
Japan
Pediatric strabismus screening mandates in Osaka and Tokyo expand clinic procurement quotas for sensor-based digital platforms. METI standards for medical device software validation shape product development timelines for domestic manufacturers. Kansai region rehabilitation centers combine fusional training protocols with orthoptic follow-up services.
India
Private clinics in Bangalore and Hyderabad install portable mechanical units to capture walk-in patients outside hospital referral networks. PLI scheme incentives lower landed costs for South Asian segments previously served by imports. Power infrastructure volatility caps electronic penetration, forcing continued reliance on mirror-based systems in metropolitan private practices.
Australia
Tele-ophthalmology networks in rural Queensland and Western Australia create demand for cloud-connected measurement logging capabilities. TGA conformity assessment pathways align with ISO 13485 quality management requirements for institutional procurement. Sydney and Melbourne metropolitan clusters support dedicated manufacturer field representative territories for direct-to-specialist distribution.
Switzerland
Swissmedic certification requirements reinforce premium positioning for precision diagnostic equipment across European hospital procurement channels. Geneva and Zurich rehabilitation centers face reimbursement compression lengthening equipment depreciation schedules for therapeutic protocols. The Basel region anchors manufacturing integration with German lens grinding supply chains.
Synoptophore Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base organizes around three strategic archetypes: precision optics conglomerates with Swiss-German manufacturing heritage, South Asian mechanical unit fabricators serving price-sensitive emerging markets, and Japanese sensor-integrators targeting digital platform segments. Consolidation pressures concentrate among ISO 13485-certified suppliers as EU MDR clinical evidence requirements extend development timelines. Competitive moves center on notified body relationship maintenance across multiple EU member states and backward integration into precision mirror component supply.
Within the precision optics tier, Haag-Streit exemplifies Swiss-German manufacturing consolidation for premium hospital procurement channels. Takagi Seiko occupies a position among Japanese specialists leveraging sensor-based integration for domestic digital platform demand. Gem Optical Instruments Industries represents South Asian mechanical fabrication archetypes anchoring competitiveness in private clinic segments through localized production. Appasamy Associates and 66 Vision Tech sit within the emerging market tier serving price-constrained installations where power reliability constrains electronic dependency.
| Leading Market Players |
|---|
| 66 Vision Tech |
| Gem Optical Instruments Industries |
| Haag-Streit |
| Rumax International |
| Takagi Seiko |
| Appasamy Associates |
| Prkamya Visions |
| Oculus |
| Nanjing Redsun Optical |
| Others |
Cost & Logistics Intelligence
CMOS image sensor pricing volatility cascades through synoptophore manufacturing tiers, compressing margins on digital assemblies while mechanical unit producers exploit stable optical glass costs to defend position in price-sensitive procurement channels across South Asian and African markets.
Pricing Analysis
Lead-time premiums command substantial markups in EU hospital procurement channels, while spot inventory of mechanical units trades at discounts in Indian private clinic segments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified diagnostic platforms from CE-marked clinical units and non-certified training instruments. Pricing pressure stems from semiconductor foundry allocation constraints squeezing digital assembly margins. Private clinics in Bangalore and Hyderabad exhibit highest price sensitivity; German metropolitan ophthalmology practices show lowest.
Supply Chain Analysis
Reverse-logistics flows for legacy mechanical units create secondary parts markets, as declining analog mirror component availability forces manufacturers to maintain obsolete inventory or abandon installed base support. Precision haploscopic mirror supply concentrates in Germany, Switzerland, and Japan. CMOS sensors, optical-grade glass, and calibrated prism assemblies constitute critical input dependencies. Single-source vulnerability in Stuttgart and Zurich lens grinding houses exposes mid-tier manufacturers to supply interruption. Distribution runs through manufacturer field representatives for direct-to-specialist channels alongside hospital procurement committees for institutional sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synoptophore market occupies a technology-transition phase where sensor-based digital architectures displace mechanical haploscopic systems, with CMOS projection platforms consolidating control over convergence-divergence measurement precision previously dominated by analog mirror adjustments.
For Market Incumbents: Cement notified body relationships across multiple EU member states to sustain CE-marked distribution under MDR Class IIa pathways. Backward integration into precision mirror component supply defends against single-source vulnerability in German and Swiss lens grinding houses. ISO 13485 certification investment filters procurement toward qualified suppliers as clinical evidence requirements extend development timelines. For New Entrants and Emerging Players: Launch via direct-to-specialist distribution in Australian and Canadian tele-ophthalmology networks, where cloud-connected measurement logging creates white-space demand outside established hospital procurement channels. Target portable mechanical unit segments in South Asian private clinics where power infrastructure volatility caps electronic penetration. Reimbursement strategy development for pediatric strabismus screening mandates unlocks fastest-growth application vertical. For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-integrators with software-enabled service subscription models in Japanese and German premium clinic segments, where repeatability standards exceed mechanical tolerance limits. Long-term viability hinges on patent positions in haploscopic IP licensing to VR headset manufacturers for consumer-grade amblyopia training modules. Monitor virtual reality convergence announcements for inflection signals altering reimbursement categorization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Filters procurement toward ISO 13485 suppliers across German and Swiss hospital networks. |
| Sensor-Based Digital Platform Development | Enables subscription service models in Tokyo and Osaka pediatric ophthalmology protocols. |
| Precision Optics Backward Integration | Reduces single-source vulnerability to Stuttgart and Zurich lens grinding houses. |
| Tele-Ophthalmology Cloud Integration | Captures rural screening demand in Queensland and Western Australian health networks. |
| VR Haploscopic IP Licensing Program | Opens royalty revenue streams from consumer headset manufacturers entering amblyopia therapy. |
Research Approach
Independent corroboration across ophthalmology equipment procurement managers, biomedical engineers at German and Japanese hospital systems, GPO contracts administrators, and regulatory affairs specialists underwrites the qualitative findings. Primary interview data triangulates against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up unit placement estimates and top-down equipment spending allocations converge on segment-level outputs.
Rate-of-change decomposition separates volume effects from mix-shift and pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology integration depth, and application purpose. CAGRs derive from installed base refresh cycle analysis and replacement elasticity estimates. Pediatric screening mandate implementation timelines and semiconductor foundry capacity allocation constitute industry-specific forecast inputs.
Regulatory enforcement intensity, CMOS sensor supply disruption, and virtual therapy reimbursement reclassification are the dominant revision risks to the outlook. Forecasts reflect documented assumptions regarding MDR transition completion and power infrastructure development trajectories. Practitioners should monitor EU notified body audit backlogs and VR headset manufacturer partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Retina Health Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
United States Dry Eye Syndrome Market