
 Coloured Contact Lenses Market | 2026-2036
Coloured Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Coloured Contact Lenses Market Analysis
Silicone hydrogel material science is tilting manufacturing economics toward breathable, all-day wearable formats. Johnson & Johnson leverages polymer chemistry expertise to sustain premium positioning across North American optical stores. Alcon anchors professional channel credibility through optometrist-exclusive fitting protocols. Solotica differentiates via Brazilian-origin opaque tinting that dominates Latin American specialty retail.
Coloured contact lenses are vision-correcting or plano ocular devices incorporating FDA-approved pigments between hydrogel substrate layers, manufactured through cast-moulding or lathe-cutting processes to achieve specific oxygen permeability measured in Dk/t units. Their commercial purpose spans refractive correction, iris appearance modification, and theatrical effect creation. Silicone hydrogel now leads material preference for extended wear, while costume lenses concentrate margin in seasonal theatrical supply despite lower prescription volumes. Online retail channels accelerate fastest among distribution modalities, though optical stores retain clinical authority for first-time fittings.
FDA 510(k) clearance and EU MDR Class IIa designation govern pigment biocompatibility and oxygen transmission thresholds, compelling manufacturers to maintain dual regulatory dossiers for transatlantic market access. The US Fairness to Contact Lens Consumers Act mandates prescription release, shaping competitive dynamics between online retailers and brick-and-mortar optometry practices. Stakeholders must monitor evolving ISO 18369 standards for pigment migration testing as regulatory stringency tightens across major markets.
Market Dynamics
Silicone hydrogel chemistry is compressing manufacturing cost structures while FDA pigment migration testing tightens compliance burdens for cross-border suppliers.
Growth Catalysts
- EU MDR Class IIa pigment biocompatibility standards:Harmonized safety benchmarks accelerate multi-country registration for compliant manufacturers.
- South Korea's K-pop beauty cluster:Daily coloured lens normalization among 18-34 demographic cohorts sustains replacement-cycle velocity.
- Cast-moulding automation:Precision tint-layer deposition reduces unit production costs for opaque theatrical formats.
Market Restraints
- HEMA monomer price volatility:Petroleum-derived hydrogel precursors expose margin structures to upstream petrochemical swings.
- Taiwanese lens foundry concentration:Four contract manufacturers produce over sixty percent of global coloured lens blanks.
- ISO 18369-3 pigment migration testing delays:Extended certification timelines stretch new product launch windows.
Strategic Opportunities
- India's underpenetrated cosmetic lens segment:Urban professional class expansion creates first-mover advantage for compliant entrants.
- Telehealth prescription verification platforms:Digital optometry workflows unlock direct-to-consumer channel scalability.
- Silicone hydrogel-AR coating convergence:Anti-reflective surface treatments extend wear-time comfort for screen-facing users.
Industry Challenges
- Specialized polymer chemist scarcity:Dk/t optimization expertise concentrates among aging formulation scientists.
- Cleanroom capex intensity:ISO 14644 Class 7 manufacturing environments require seven-figure facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coloured Contact Lenses Market |
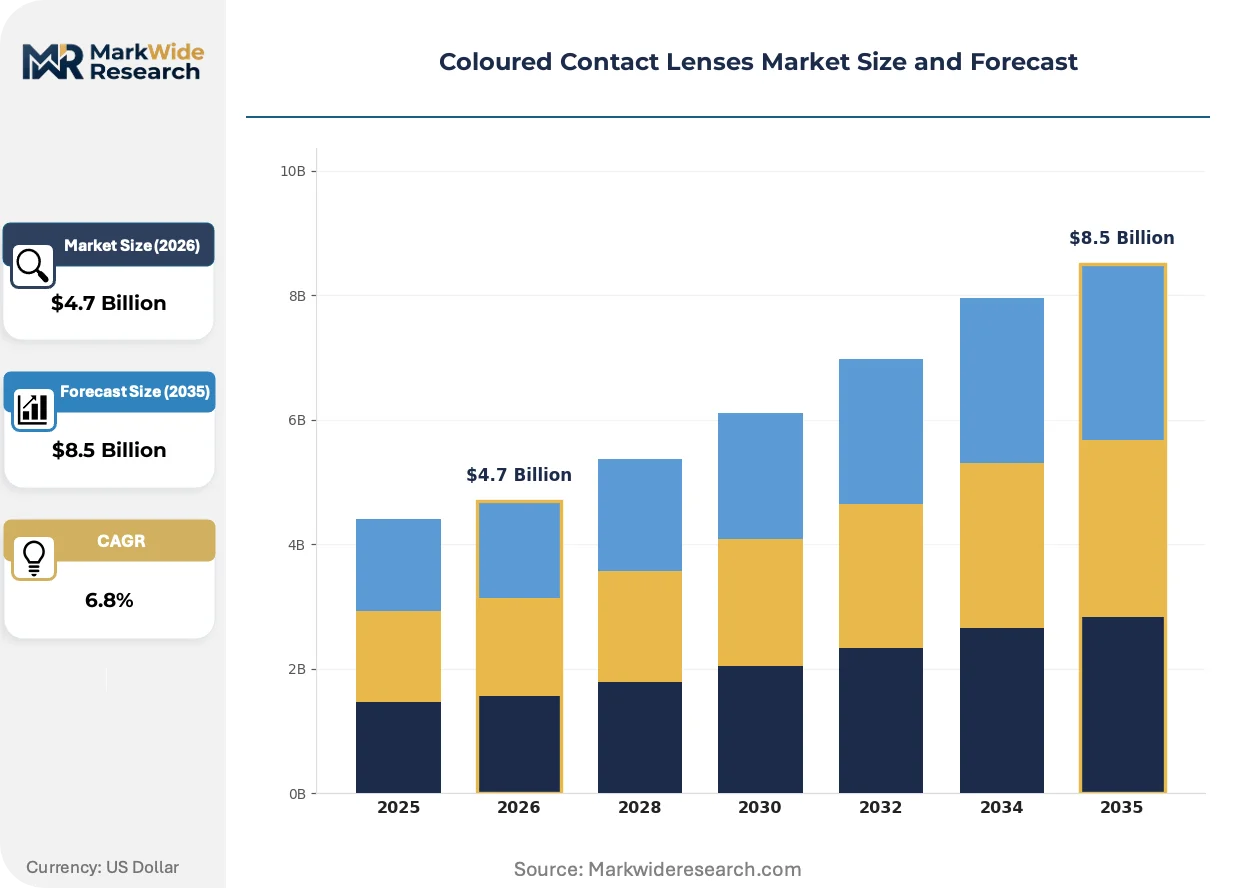
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enhancement Tints, Opaque Lenses, Visibility Tints, Costume Lenses End User: Cosmetic Consumers, Theatrical Users, Sports Enthusiasts, Fashion Model Distribution Channel: Online Retail, Optical Stores, Specialty Shops, Department Stores Material: Hydrogel, Silicone Hydrogel, Polymethyl Methacrylate, Others |
| Companies Covered | Johnson & Johnson, Alcon, Bausch + Lomb, CooperVision, Solotica, FreshKon, Clalen, TTDeye, Olens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coloured Contact Lenses Market Emerging Trajectories
Material science advances and regulatory stringency are compressing product lifecycles while reshaping channel economics for coloured lens distribution.
Silicone hydrogel formulations with enhanced oxygen permeability are collapsing the distinction between cosmetic and corrective daily-wear categories. Young professional adopters in Seoul and Tokyo now expect twelve-hour comfort from plano tinted lenses. The technology is collapsing premium pricing power for conventional hydrogel products.
FDA 510(k) clearance pathways for novel pigment chemistries are tightening submission requirements for biocompatibility data. Manufacturers must now demonstrate six-month stability testing before market authorization. Small-batch theatrical lens producers face disproportionate compliance cost burdens.
Subscription-based lens replenishment models are displacing single-purchase retail patterns among recurring cosmetic users. South Korean e-commerce platforms bundle quarterly deliveries with K-beauty sampling programs. This shift concentrates customer lifetime value metrics for direct-to-consumer operators.
Coloured Contact Lenses Market Segmentation
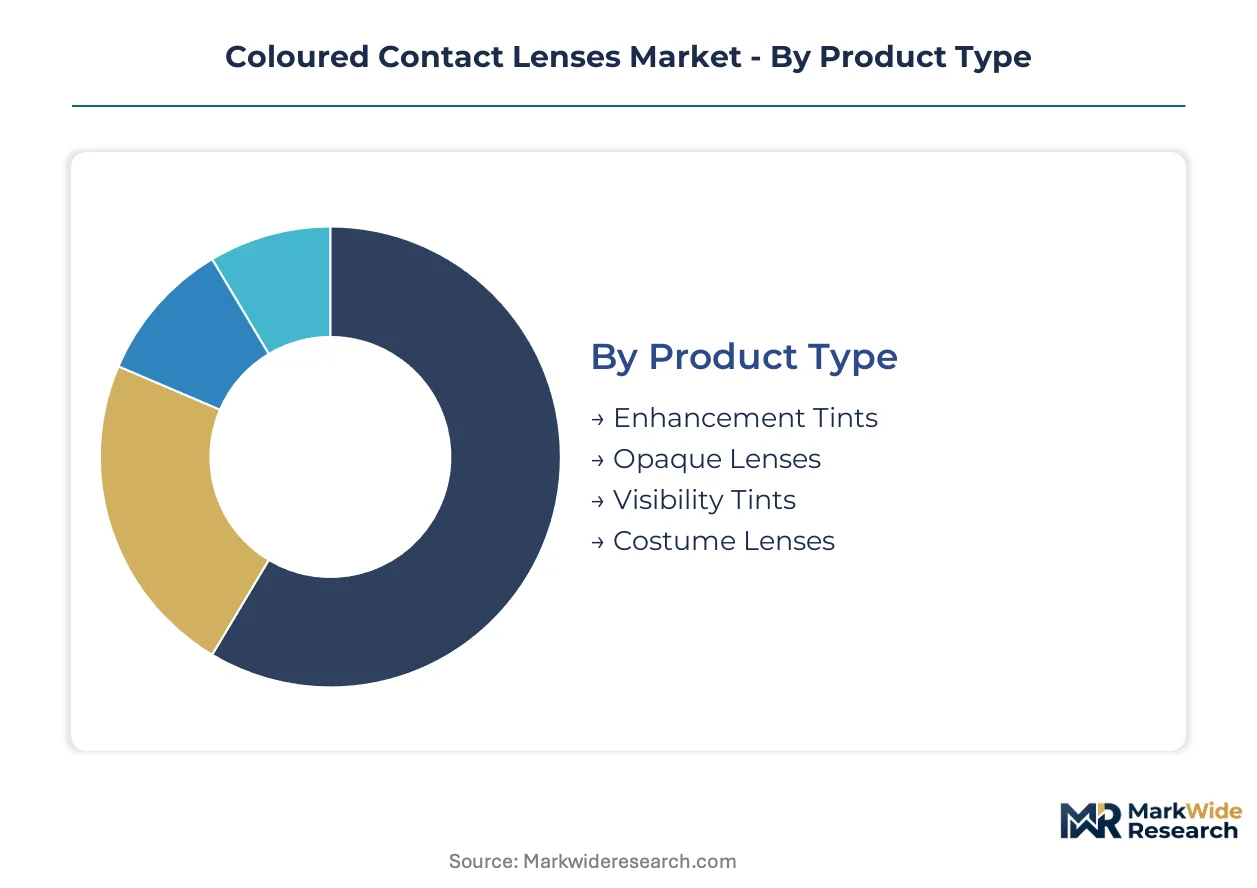
Segmentation in coloured contact lenses reveals how material chemistry, distribution economics, and end-use intensity create divergent margin profiles. Manufacturers must align production capabilities with specific channel and user requirements to capture value.
Product Type:
Cost tier differentiation separates daily-wear cosmetic formats from specialized theatrical inventory with distinct replacement cycles and margin structures.
- Enhancement Tints:Translucent pigment layers intensify natural iris coloration without complete opacity. Demand concentrates among Seoul's K-pop influenced demographic seeking subtle daily-wear aesthetics. Silicone hydrogel substrates now dominate this tier as twelve-hour comfort expectations normalize.
- Opaque Lenses:Dense tinting completely masks underlying iris pigmentation for dramatic color transformation. Brazilian specialty retail channels anchor volume for Solotica-origin products serving Latin American cosmetic consumers. FDA pigment migration testing imposes heavier compliance burdens on opaque formulations.
- Visibility Tints:Light blue or green handling tints aid lens insertion without altering eye appearance. Optical stores bundle these with first-time fitting protocols to reduce handling anxiety among novice wearers.
- Costume Lenses:Theatrical designs incorporate scleral coverage and patterned effects for seasonal entertainment use. Halloween and cosplay cycles concentrate revenue in concentrated three-month windows.
Enhancement Tints holds installed capacity. Opaque Lenses is rotating up the share rankings.
End User:
Application intensity varies dramatically between daily cosmetic wearers and episodic theatrical deployers with opposing replacement cadences.
- Cosmetic Consumers:Daily-wear adopters in South Korea and Japan sustain monthly replacement schedules with subscription replenishment models. K-beauty sampling programs bundle quarterly deliveries to lock customer lifetime value.
- Theatrical Users:Film production houses and stage performers require custom-fitted scleral designs with extended wear certification. Cast-moulding automation reduces unit costs for production-volume orders.
- Sports Enthusiasts:Athletes seeking competitive intimidation or UV protection drive modest prescription volume through specialty sports optical channels.
- Fashion Model:Editorial and runway talent require rapid-swap inventory with multiple color options for single-day shoots. Agency procurement favors direct relationships with theatrical suppliers.
Cosmetic Consumers commands replacement velocity. Theatrical Users is gaining share fastest among professional production segments.
Distribution Channel:
Channel configuration determines prescription verification requirements and customer acquisition economics with divergent regulatory exposure.
- Online Retail:Direct-to-consumer platforms leverage telehealth prescription verification to bypass optical store gatekeeping. South Korean e-commerce bundling with K-beauty products accelerates fastest among modalities.
- Optical Stores:Brick-and-mortar optometry practices retain clinical authority for first-time fittings and complex prescriptions. Johnson & Johnson sustains premium positioning through exclusive professional channel relationships.
- Specialty Shops:Latin American cosmetic retailers stock Brazilian-origin opaque tinting with higher margin capture than mass channels.
- Department Stores:Planogram placement in Asian beauty halls exposes coloured lenses to impulse cosmetic purchasers with minimal clinical oversight.
Optical Stores holds fitting authority. Online Retail is climbing the fastest among scalable channels.
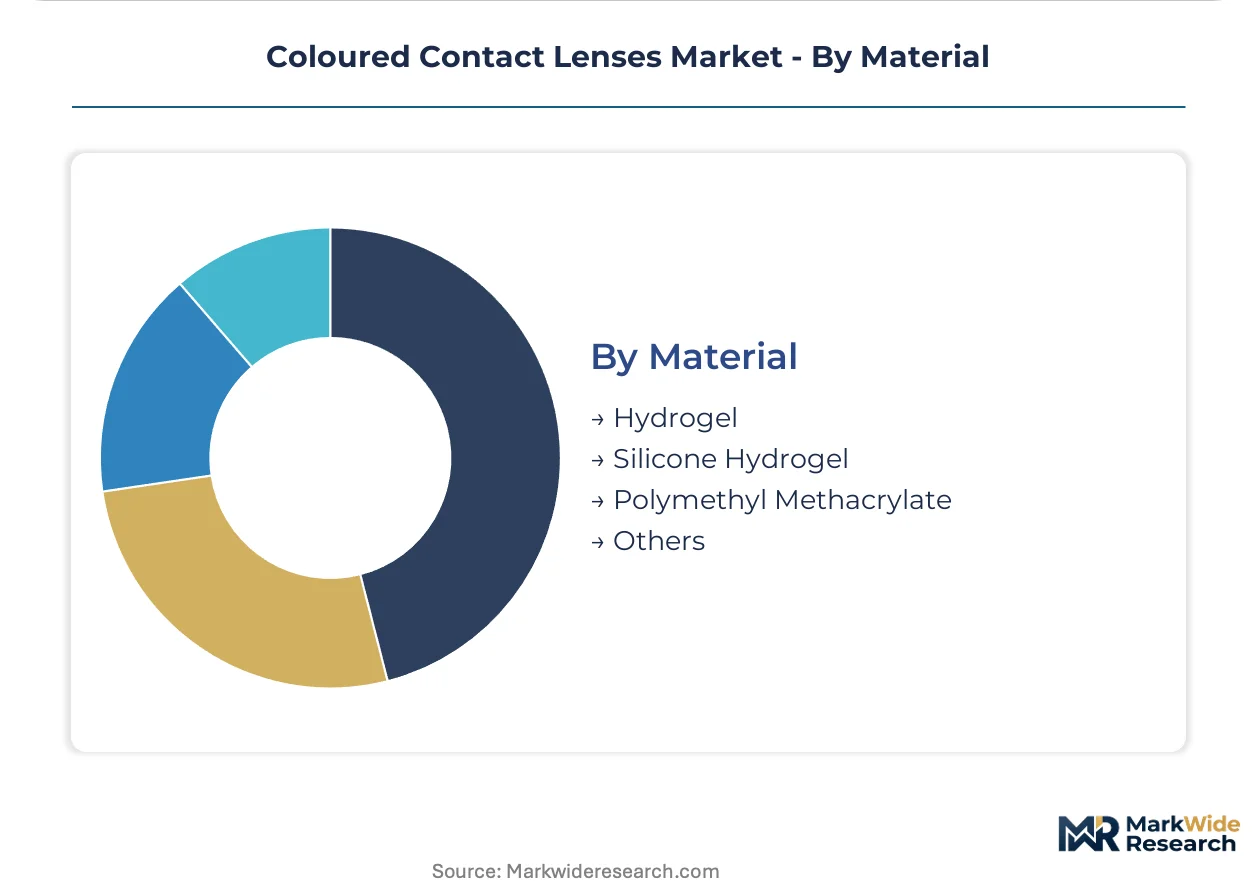
Material:
Volume concentration and margin capture diverge sharply between legacy hydrogel and advanced silicone hydrogel chemistries.
- Silicone Hydrogel:Enhanced oxygen permeability measured in elevated Dk/t units enables twelve-hour continuous wear without corneal hypoxia. Young professionals in Tokyo and Seoul now expect this performance baseline even from plano cosmetic lenses.
- Hydrogel:Conventional HEMA-based formulations retain cost advantage for price-sensitive theatrical and costume segments. Petroleum-derived precursor exposure creates margin vulnerability to upstream petrochemical volatility.
- Polymethyl Methacrylate:Rigid gas-permeable substrates serve specialized therapeutic applications with minimal coloured lens penetration.
- Others:Experimental fluorosilicone acrylate blends target extreme oxygen transmission for overnight wear indications still under regulatory review.
Hydrogel holds legacy installed capacity. Silicone Hydrogel is expanding most quickly as comfort expectations reset market standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports finished coloured lenses to Japan's cosmetic retailers while Taiwan's contract foundries supply lens blanks to US and European distributors. This trade corridor concentrates manufacturing expertise in East Asia while consumer demand fragments across distinct national beauty cultures.
United States
FDA 510(k) clearance requirements for novel pigment chemistries create compliance barriers for foreign entrants. The Fairness to Contact Lens Consumers Act mandates prescription release, enabling online retailers to compete with brick-and-mortar optometry practices. Johnson & Johnson sustains premium positioning through exclusive professional channel relationships across North American optical stores.
South Korea
Seoul's K-pop beauty cluster normalizes daily coloured lens wear among 18-34 demographic cohorts with twelve-hour comfort expectations. MFDS enforces pigment biocompatibility standards aligned with international benchmarks. Subscription-based replenishment models on domestic e-commerce platforms bundle quarterly deliveries with K-beauty sampling programs.
Brazil
Latin American cosmetic consumers drive demand for opaque tinting that completely masks underlying iris pigmentation. ANVISA registration requirements govern importation of finished medical devices including plano cosmetic lenses. Solotica anchors specialty retail channels serving Brazilian-origin opaque tinting preferences across regional beauty markets.
Japan
Tokyo's young professionals now expect silicone hydrogel performance baselines even from plano cosmetic lenses. PMDA oversees pharmaceutical and medical device safety including contact lens pigment migration testing. Cast-moulding automation in domestic manufacturing reduces unit production costs for high-volume cosmetic formats.
Germany
EU MDR Class IIa designation harmonizes safety benchmarks across member states for compliant manufacturers. German optical retail chains emphasize professional fitting protocols over direct-to-consumer channels. REACH regulations govern chemical substance registration for hydrogel precursors used in lens substrate manufacturing.
Coloured Contact Lenses Market Vendor Landscape
On the supply side, the industry is consolidating around polymer chemistry capabilities and regulatory dossier expertise. Tiered competitive positioning separates multinational healthcare conglomerates from regional cosmetic specialists and contract manufacturing foundries. Strategic archetypes include prescription-corrective leaders, cosmetic-specialty pure-plays, and private-label foundry operators. Dominant competitive moves encompass optometrist-exclusive channel partnerships and silicone hydrogel material science licensing.
Within the multinational healthcare tier, Johnson & Johnson and Alcon represent integrated ophthalmic device manufacturers with professional channel anchoring. Solotica occupies a position exemplifying regional cosmetic-specialty focus through Brazilian-origin opaque tinting expertise. These three entities span distinct strategic archetypes: prescription-corrective market presence, professional credibility protocols, and cosmetic-specialty regional dominance.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Alcon |
| Bausch + Lomb |
| CooperVision |
| Solotica |
| FreshKon |
| Clalen |
| TTDeye |
| Olens |
| Others |
Supply Flow & Price Mechanics
East Asian air freight corridors connecting Taiwanese lens foundries to South Korean cosmetic distributors carry per-unit logistics costs that compound with HEMA monomer price volatility, squeezing margin structures for opaque tint manufacturers while enabling subscription-model price premiums for silicone hydrogel daily-wear formats.
Pricing Analysis
Silicone hydrogel-to-conventional hydrogel-to-PMMA pricing gaps reflect oxygen permeability performance tiers rather than brand positioning alone. Three-tier pricing structure across premium silicone hydrogel, standard HEMA-based hydrogel, and economy costume lens levels stratifies by Dk/t certification thresholds and replacement cycle frequency. Cost compression in theatrical costume tiers intensifies because cast-moulding automation diffuses rapidly among contract manufacturers. Price-sensitive theatrical users and Halloween seasonal purchasers drive volume in economy tiers, while daily cosmetic adopters in Seoul and Tokyo absorb premium positioning for twelve-hour comfort certification.
Supply Chain Analysis
Export-control restrictions on advanced polymer chemistry equipment limit silicone hydrogel manufacturing expansion outside established East Asian production bases. Taiwan, South Korea, and Japan anchor global coloured lens blank output, with Taiwanese contract foundries supplying over sixty percent of upstream capacity. Petroleum-derived HEMA monomer, FDA-grade pigment concentrates, and precision cast-moulding equipment constitute critical input dependencies. Single-source vulnerability concentrates in Taiwanese foundry capacity for high-Dk/t substrate formulations. Distribution runs through South Korean e-commerce platforms, North American optical store chains, and Latin American specialty cosmetic retailers in divergent downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for silicone hydrogel Dk/t optimization concentrates among aging scientist cohorts, constraining new product pipeline velocity and inflating acquisition premiums for teams with proven regulatory dossier experience.
For Market Incumbents: Harden regulatory dossier moats by accelerating EU MDR Class IIa and FDA 510(k) submission pipelines ahead of ISO 18369-3 pigment migration testing deadline expansions. Deepen backward integration into silicone hydrogel polymer chemistry through captive supply agreements with Taiwanese foundries, defending against emerging pure-play cosmetic specialists capturing K-beauty subscription channel share. For New Entrants and Emerging Players: Build out telehealth prescription verification infrastructure to bypass optical store gatekeeping in India's underpenetrated urban professional segment, where first-mover advantage awaits compliant entrants with localized MFDS-aligned pigment biocompatibility certification. White-space concentration in theatrical costume lenses for production-volume film and stage orders offers scalable entry through cast-moulding automation partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational healthcare conglomerates divesting non-core cosmetic lens divisions lacking prescription-corrective synergy. Long-term viability hinges on silicone hydrogel material science licensing revenue streams and subscription-model customer lifetime value capture. Watch FDA pigment chemistry clearance velocity as inflection signal for compliant manufacturing capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Polymer Licensing | Technology licensing to contract foundries unlocks royalty streams without cleanroom capex burden. |
| Telehealth Prescription Platform Integration | Digital optometry workflows enable direct-to-consumer scalability in underpenetrated South Asian markets. |
| EU MDR Class IIa Certification Acceleration | Harmonized safety benchmarks reduce multi-country registration friction for compliant manufacturers. |
| Subscription Replenishment Model Launch | Quarterly delivery bundling with K-beauty products locks customer lifetime value in Seoul and Tokyo. |
| Cast-Moulding Automation Scale-Up | Precision tint-layer deposition reduces unit costs for opaque theatrical formats serving production houses. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with silicone hydrogel formulation scientists, optical store procurement managers, and K-beauty e-commerce platform operators; and secondary validation through FDA 510(k) clearance databases, EU MDR Class IIa registration filings, and MFDS pigment biocompatibility standards. Customs records for Taiwanese lens blank exports, ISO 18369 testing protocol documentation, and South Korean subscription commerce transaction patterns provided additional triangulation. Bottom-up unit economics for daily-wear versus theatrical replacement cycles were cross-referenced against top-down market sizing from regional distributor revenue disclosures.
Forecast inputs across the analysis window incorporated material chemistry segmentation by Dk/t performance tier, distribution channel prescription verification requirements, and end-user replacement velocity differentials between cosmetic daily wearers and theatrical episodic deployers. CAGRs were derived from installed capacity expansion schedules at Taiwanese contract foundries, South Korean e-commerce platform growth trajectories, and regulatory timeline assumptions for novel pigment chemistry approvals. Silicone hydrogel adoption curves in Tokyo and Seoul, alongside HEMA monomer price elasticity assumptions, shaped volume and value trajectory modeling.
Stress conditions across HEMA precursor cost volatility, Taiwanese foundry concentration disruption scenarios, and FDA pigment migration testing timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding K-pop cultural influence persistence and telehealth regulatory permissiveness evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Pseudotumor Cerebri Market