
 Global Fundus Cameras Market | 2026-2036
Global Fundus Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fundus Cameras Market Foresight
EU MDR is expanding documentation and post-market surveillance obligations for fundus camera manufacturers seeking CE marking in Europe. Canon leverages its imaging sensor supply chain to control component costs across tabletop and portable product lines. Carl Zeiss Meditec anchors its position through optical coherence tomography integration that deepens clinical workflow attachment. Topcon Corporation specializes in hybrid platforms combining scanning laser ophthalmoscopy with traditional color fundus photography.
Fundus cameras are diagnostic imaging instruments that capture high-resolution photographs of the retina, optic disc, and macula through a specialized optical system with adjustable illumination angles and filter configurations, primarily serving ophthalmologists in disease detection and longitudinal monitoring of retinal pathology. Tabletop fundus cameras dominate installed base revenue in tertiary eye care centers where throughput and image fidelity requirements are highest, while handheld and smartphone-based variants represent the fastest-growing segment as point-of-care screening extends into primary care settings and rural outreach programs. Optical coherence tomography-enabled fundus systems command premium positioning due to their ability to deliver cross-sectional retinal data alongside en face images, creating distinct margin pools distinct from standard digital imaging platforms.
FDA 510(k) clearance processes and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers distributing in the United States and European Economic Area. Japan's PMDA enforces stringent quality management system audits that filter out lower-capability entrants from the Japanese market. China's NMPA has accelerated review pathways for AI-assisted diagnostic features, redirecting R&D investment toward software-integrated hardware platforms. Stakeholders must monitor regulatory divergence across these jurisdictions as algorithm-enabled fundus cameras trigger separate classification debates that could fragment approval strategies.
Market Dynamics
EU MDR documentation burdens and AI-enabled diagnostic integration are compressing product development timelines while fragmenting approval strategies across jurisdictions. Manufacturers now face parallel technical file requirements that favor established players with regulatory infrastructure.
Growth Catalysts
- Diabetic retinopathy screening mandates:Hospital networks in the United States and Germany are expanding procurement of tabletop and portable systems for population-scale early detection programs.
- AI-assisted diagnostic pathways:China's NMPA has accelerated review timelines for software-integrated hardware platforms, redirecting R&D investment toward algorithm-enabled imaging.
- Aging demographic concentration:Japan's elderly population sustains replacement cycles for high-fidelity fundus systems in tertiary eye care centers.
Market Restraints
- Optical component supply concentration:Precision imaging sensors and specialized lenses concentrate among Japanese and German suppliers, creating input cost volatility.
- EU MDR technical documentation:Post-market surveillance obligations and clinical evidence requirements elevate compliance costs for CE marking access.
- Smartphone-based substitution:Low-cost handheld alternatives threaten standard digital imaging platforms in primary care screening applications.
Strategic Opportunities
- Rural outreach penetration:India's underserved districts present white space for portable fundus cameras in government health camps and mobile clinics.
- OCT-fundus convergence:Cross-sectional retinal imaging combined with en face photography commands premium positioning in academic medical centers.
- Telemedicine channel expansion:Remote diagnostic platforms in Australia and Brazil enable direct-to-clinic distribution models bypassing traditional device distributors.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel FDA 510(k), EU MDR, and PMDA quality system audits extend time-to-revenue for new product launches.
- Legacy system integration friction:Hospital IT departments face workflow disruption when connecting AI-enabled cameras to existing PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fundus Cameras Market |
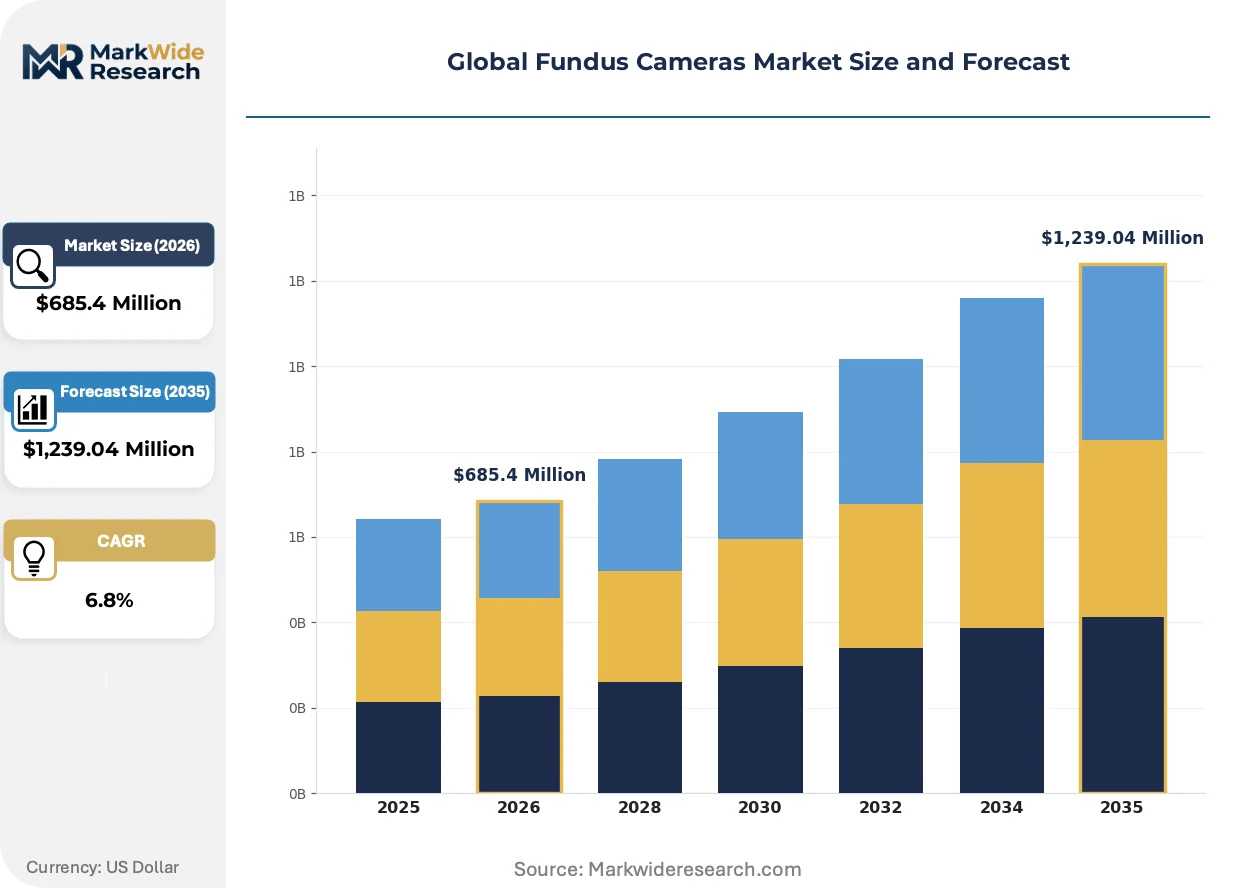
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table-top Fundus Cameras, Handheld Fundus Cameras, Portable Fundus Cameras, Smartphone-based Fundus Cameras Technology: Digital Imaging, Scanning Laser Ophthalmoscopy, Optical Coherence Tomography, Fluorescein Angiography Application: Diabetic Retinopathy Screening, Glaucoma Diagnosis, Age-related Macular Degeneration Detection, Retinal Vein Occlusion Analysis End User: Ophthalmology Clinics, Eye Care Centers, Diagnostic Laboratories, Research Institutions |
| Companies Covered | Canon, Carl Zeiss Meditec, Topcon Corporation, NIDEK, Kowa Company, Optomed, Optovue, Revenio Group, Haag-Streit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fundus Cameras Market Shifts & Advancements
Scanning laser ophthalmoscopy is converging with traditional color fundus photography to create hybrid diagnostic platforms. This unification of imaging modalities is compressing the distinction between screening and diagnostic-grade equipment.
Hybrid platforms combining scanning laser ophthalmoscopy with standard digital imaging are unifying previously separate clinical workflows. Academic medical centers in Germany and Japan are adopting these systems to reduce patient chair time and consolidate capital expenditure. The technology is unifying margin pools that historically separated screening devices from premium diagnostic instruments.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection from deployed fundus cameras. Manufacturers must now maintain technical documentation updates and periodic safety reports for CE-marked devices. European ophthalmology clinics are responding by consolidating supplier relationships toward vendors with established quality management infrastructure.
Point-of-care screening programs are compressing traditional sales cycles through direct hospital network procurement. Primary care settings in the United States and rural clinics in India are bypassing distributor channels to negotiate volume contracts with manufacturers. This behavioral shift concentrates purchasing power among integrated delivery networks and government health systems.
Global Fundus Cameras Market Segmentation
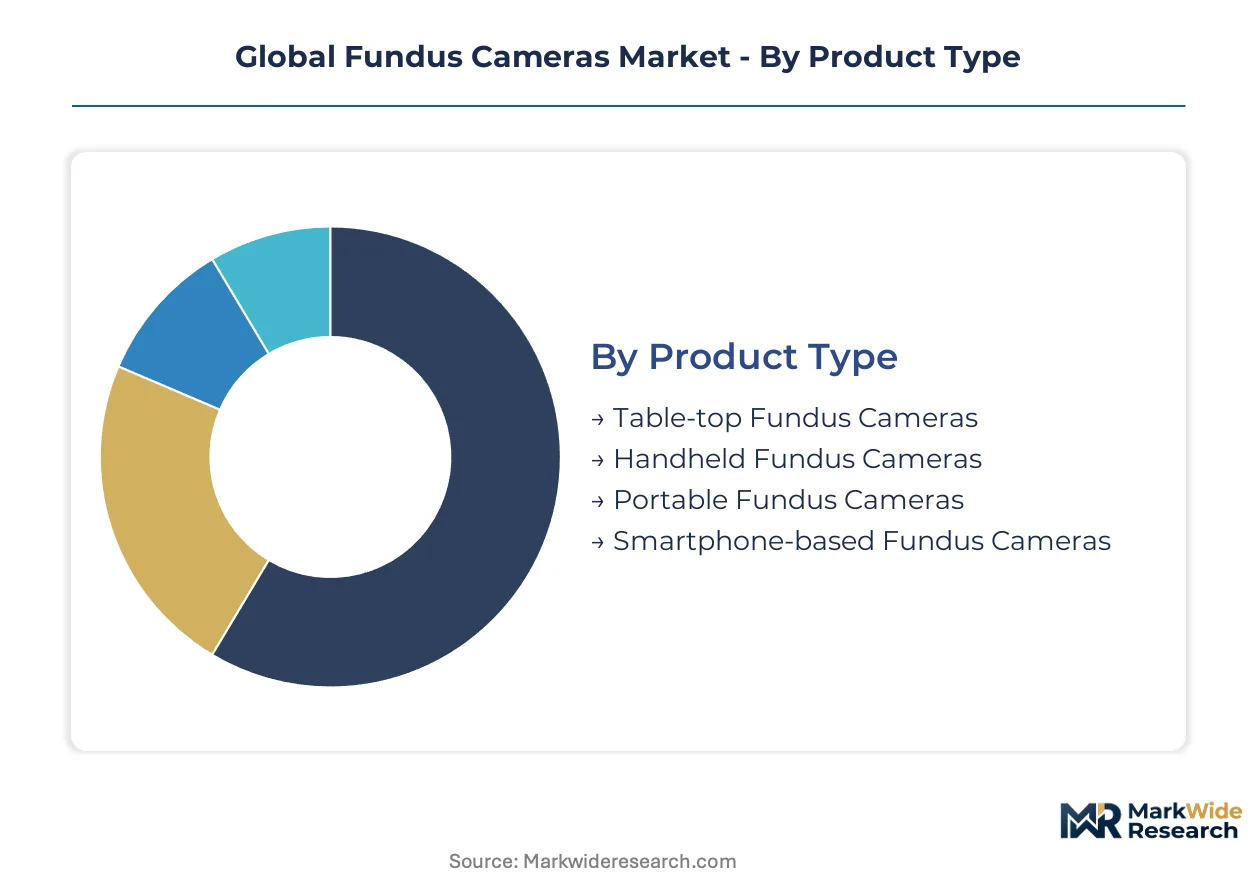
Fundus camera segmentation reveals how hardware form factors and imaging technologies map to distinct clinical workflows and procurement budgets. Understanding these divides enables manufacturers to align R&D investment with specific reimbursement environments and facility infrastructure constraints.
Product Type:
Standalone systems dominate tertiary care revenue, while embedded and portable variants penetrate point-of-care settings where integration depth varies by clinical need.
- Table-top Fundus Cameras:Stationary systems with high-resolution sensors and adjustable illumination angles serve tertiary eye care centers in Germany and Japan where throughput demands justify capital expenditure. Hospital networks in the United States negotiate multi-unit contracts for diabetic retinopathy screening programs, prioritizing image fidelity over mobility.
- Handheld Fundus Cameras:Battery-operated devices with simplified optics enable bedside imaging in intensive care units and pediatric wards where patient transport is impractical. India's government health camps procure these units for rural outreach, accepting lower resolution in exchange for field durability.
- Portable Fundus Cameras:Compact units with integrated displays bridge clinic and community settings, finding placement in mobile clinics across Brazil and Australia's remote territories.
- Smartphone-based Fundus Cameras:Adapter systems leveraging mobile device cameras reduce per-unit cost below traditional platforms, attracting primary care practices in cost-sensitive markets.
Volume placements concentrate in table-top systems; the faster expansion belongs to smartphone-based platforms.
Technology:
Cost tiers separate basic digital capture from premium modalities that command reimbursement premiums and require specialized operator training.
- Digital Imaging:Standard color fundus photography with CMOS or CCD sensors captures retinal surface anatomy for routine screening and documentation. This baseline technology saturates ophthalmology clinics in the United States where reimbursement codes favor established modalities over experimental techniques.
- Scanning Laser Ophthalmoscopy:Confocal laser scanning systems deliver high-contrast images through narrow illumination apertures, reducing media opacity interference in cataract patients. Academic medical centers in Japan adopt these platforms for research protocols requiring precise vascular mapping.
- Optical Coherence Tomography:Cross-sectional imaging systems generate retinal layer thickness measurements alongside en face photographs, enabling glaucoma progression tracking. Germany's statutory health insurance funds reimburse OCT-fundus combination devices at premium rates, concentrating demand in university hospitals.
- Fluorescein Angiography:Dye-based perfusion imaging systems visualize retinal and choroidal circulation dynamics, retaining specialized use in retinal vein occlusion analysis despite invasive procedure requirements.
Digital imaging captures the highest unit volume; OCT integration delivers the steepest margin expansion.
Application:
Application segments align with disease prevalence patterns and national screening program priorities that reshape procurement timing.
- Diabetic Retinopathy Screening:Population-scale early detection programs drive the largest addressable demand, with India's national blindness control initiative funding portable systems for district-level deployment.
- Glaucoma Diagnosis:Structural assessment of the optic nerve head and retinal nerve fiber layer supports longitudinal monitoring, with Japan's aging demographic sustaining replacement cycles for high-precision instruments.
- Age-related Macular Degeneration Detection:Drusen and neovascularization imaging requirements concentrate demand in regions with elderly population clusters, particularly Germany's urban ophthalmology networks.
- Retinal Vein Occlusion Analysis:Specialized perfusion assessment needs limit this segment to referral centers handling complex vascular pathology.
Screening applications generate the highest placement volume; diagnostic applications for complex retinal disease command premium pricing.
End User:
Customer type determines purchasing authority structure, with institutional buyers negotiating differently than independent practice owners.
- Ophthalmology Clinics:Private and group practices in the United States select devices based on EHR integration capabilities and American Academy of Ophthalmology guideline alignment.
- Eye Care Centers:Multispecialty facilities in Germany combine fundus imaging with refractive and surgical services, requiring workflow-compatible equipment footprints.
- Diagnostic Laboratories:Centralized reading centers in India process outsourced screening images from primary care, driving demand for high-throughput automated capture systems.
- Research Institutions:Academic medical centers in Japan prioritize devices with open software architectures for algorithm development and clinical trial endpoints.
Clinic placements dominate current installed base; diagnostic laboratories represent the fastest-expanding customer category as centralized screening models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for medical device manufacturing concentrate assembly operations for portable fundus systems serving government screening contracts. These zones attract component suppliers from Japan and Germany seeking tariff advantages for re-export to Southeast Asian markets.
United States
Hospital networks in Texas and Florida negotiate volume contracts for diabetic retinopathy screening programs under Medicare reimbursement codes. FDA 510(k) clearance timelines shape product launch sequencing for tabletop systems targeting academic medical centers. The Cleveland Clinic and Mayo Clinic anchor procurement clusters in Ohio and Minnesota respectively.
Germany
Statutory health insurance funds reimburse OCT-fundus combination devices at premium rates, concentrating demand in university hospitals across Bavaria and North Rhine-Westphalia. EU MDR technical documentation requirements filter market access toward established quality management systems. Heidelberg and Tübingen host research clusters advancing hybrid imaging platforms.
Japan
PMDA quality management system audits sustain replacement cycles for high-fidelity instruments in Tokyo and Osaka metropolitan eye care centers. METI funding for telemedicine infrastructure extends fundus camera deployment to rural prefectures. The aging Kanto population drives demand for glaucoma monitoring systems in suburban clinics.
China
NMPA accelerated review pathways for AI-assisted diagnostic features redirect R&D investment toward software-integrated hardware platforms in Shanghai and Shenzhen. Government blindness prevention initiatives fund portable systems for county-level hospitals in Sichuan and Yunnan provinces. Yangtze River Delta manufacturing clusters supply imaging sensors for domestic and export markets.
India
National blindness control program tenders drive portable fundus camera procurement for district-level deployment in Maharashtra and Tamil Nadu. CDSCO medical device rules shape import registration pathways for multinational manufacturers. Hyderabad and Bengaluru host diagnostic laboratory networks processing outsourced screening images from primary care.
Global Fundus Cameras Market Competitive Landscape
Japanese and German producers anchor the premium-tier segment; Chinese and South Korean specialists hold the portable and cost-optimized tier. Market structure concentrates among diversified optical conglomerates with captive sensor supply chains and established regulatory infrastructure. Three archetypes dominate: imaging conglomerates leveraging vertical integration, pure-play ophthalmic device specialists, and emerging AI-software integrators. Competitive moves center on hybrid platform development and direct hospital network procurement contracts bypassing traditional distributors.
Within the imaging conglomerate tier, Canon and Carl Zeiss Meditec exemplify players with upstream control over optical component supply. Topcon Corporation occupies a position bridging traditional fundus photography with scanning laser ophthalmoscopy convergence. These three anchors represent distinct strategic postures: sensor supply chain dominance, precision optics integration, and hybrid modality unification.
| Leading Market Players |
|---|
| Canon |
| Carl Zeiss Meditec |
| Topcon Corporation |
| NIDEK |
| Kowa Company |
| Optomed |
| Optovue |
| Revenio Group |
| Haag-Streit Group |
| Others |
Supply & Pricing Matrix
Hospital network procurement consolidation for diabetic retinopathy screening programs in the United States and Germany is forcing manufacturers to absorb longer payment terms and bundle service contracts, compressing margins on standard digital imaging platforms while preserving premium pricing for OCT-integrated systems.
Pricing Analysis
Lead-time compression commands measurable premiums in the fundus camera market, with academic medical centers in Japan and Germany paying elevated rates for expedited delivery of hybrid OCT-fundus platforms while primary care networks in India negotiate spot discounts on portable inventory. Three-tier pricing structure across premium, standard, and economy levels separates optical coherence tomography-enabled systems from digital imaging baselines and smartphone-based adapters. Cost compression in the standard digital tier is intensifying because of low-cost handheld substitution from Chinese and South Korean specialists. Government health systems and rural outreach programs exhibit the highest price sensitivity, while tertiary eye care centers prioritize image fidelity over unit economics.
Supply Chain Analysis
Ocean freight rate volatility between East Asian component hubs and European assembly facilities is elevating landed costs for German and Japanese manufacturers sourcing precision imaging sensors. Manufacturing concentration in Japan, Germany, and China draws from specialized CMOS sensor foundries, confocal laser scanning modules, and precision optical lens grinding capacity. Single-source vulnerability concentrates in Japanese suppliers of high-resolution imaging sensors, exposing European and North American device assemblers to allocation risk during semiconductor cycle tightness. Distribution runs through direct hospital network contracts for tabletop systems and government tender channels for portable units, with traditional medical device distributors losing share in high-volume screening programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in fundus cameras has become a vertical-integration race, with sensor supply chain control and regulatory infrastructure emerging as the decisive levers separating margin leaders from price-takers.
For Market Incumbents: Extend hybrid platform development roadmaps to unify scanning laser ophthalmoscopy with OCT capabilities, locking in academic medical center procurement cycles. Deepen backward integration into imaging sensor supply through captive production or long-term offtake agreements with Japanese foundries, insulating against allocation shocks. Secure EU MDR technical documentation advantages to filter out mid-tier competitors lacking quality management infrastructure. For New Entrants and Emerging Players: Begin with smartphone-based fundus adapters targeting India's district-level government health camps and Brazil's remote telemedicine networks, where cost sensitivity outweighs image fidelity requirements. Penetrate the diagnostic laboratory segment in South Asia through high-throughput automated capture systems designed for centralized reading center workflows. Pursue software-integrated hardware pathways leveraging China's NMPA accelerated review timelines for AI-assisted diagnostic features. For Investors and Strategic Acquirers: The window for entry favors mid-cap ophthalmic device specialists with established regulatory filings and open software architectures enabling algorithm integration. Long-term viability hinges on capturing recurring revenue streams from software companion products and remote diagnostic platform subscriptions rather than transactional device sales. Watch for inflection signals in hospital IT procurement patterns indicating workflow consolidation toward single-vendor hybrid imaging ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments filter market access toward established quality management systems. |
| Hospital System Partnership | Direct procurement contracts with integrated delivery networks in Texas and Florida bypass traditional distributor channels. |
| Software Companion Development | AI-assisted diagnostic algorithms trigger NMPA accelerated review pathways and redirect R&D investment in Shanghai. |
| Backward Integration into Sensors | Captive CMOS supply chains insulate Canon and Carl Zeiss Meditec from Japanese foundry allocation volatility. |
| Reimbursement Strategy | Germany's statutory health insurance funds reward OCT-fundus combination devices with premium reimbursement codes. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR technical documentation filings, and NMPA accelerated review decisions anchored the trend analysis, supplemented by interviews with ophthalmology clinic directors, hospital purchasing committee members, biomedical engineers at academic medical centers, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body certificates, hospital procurement databases tracking device placements, and CMS Medicare reimbursement code filings. Bottom-up unit shipment estimates across product type and technology segments triangulated against top-down manufacturer revenue disclosures.
Input-output matrices modeled demand drivers including diabetic retinopathy screening program expansion, aging demographic concentration, and AI diagnostic integration across the projection horizon. Segmentation dimensions spanned product type, imaging technology, clinical application, and end-user facility tier. CAGRs were derived from curve-fitting procedures applied to historical placement data and forward-looking procurement pipeline indicators. Industry-specific forecast inputs included PMDA quality management system audit completion rates and government tender award patterns for portable systems in India.
Underlying measurement precision varies by segment; tabletop fundus camera placements in tertiary eye care centers carry tighter precision than smartphone-based adapter estimates in informal primary care settings. Forecasts reflect assumptions about regulatory pathway stability and reimbursement code continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
India Ophthalmic Clinical Trials Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Astigmatism Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Orthokeratology Market