
 Global Probe Card Market | 2026-2036
Global Probe Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global Probe Card Market Foresight
South Korea's probe card supply base is fragmenting as domestic equipment vendors and foreign specialists establish parallel production ecosystems. FormFactor Inc. leverages its MEMS fabrication depth to anchor North American supply chains for advanced node testing. Technoprobe S.p.A. competes through vertical integration into tungsten needle manufacturing, while Micronics Japan Co., Ltd. sustains dominance in cantilever probe architectures for legacy node continuity.
A probe card is a high-density electromechanical interface that positions microscopic contact elements—typically tungsten, beryllium-copper, or MEMS-fabricated springs—onto semiconductor wafer pads to transmit test signals during parametric and functional verification. MEMS probe cards command premium positioning due to sub-40 micron pitch requirements at 3nm and below, whereas spring probe cards retain cost advantages in mature node automotive and power semiconductor validation. Electrical probing technology leads volume deployment, though hybrid probing architectures are gaining traction in photonics-integrated chip testing where optical and electrical stimuli must converge.
EPA hazardous substance rules and EU REACH chemical restrictions constrain material selection for probe substrates and contact metallurgy, elevating compliance costs for suppliers serving dual jurisdiction customers. Japan's METI semiconductor equipment standards and South Korea's K-Battery and K-Semiconductor Acts shape local content requirements and subsidy eligibility for probe card procurement. Stakeholders must monitor how export control expansions affect probe technology transfer to Chinese fabs and whether domestic substitution programs in Beijing and Seoul reconfigure supply chain partnerships.
Market Dynamics
Advanced packaging test requirements for high-bandwidth memory and AI accelerators are compressing probe pitch tolerances below 40 microns, forcing MEMS-based architectures to displace legacy cantilever designs across leading-edge fabs.
Growth Catalysts
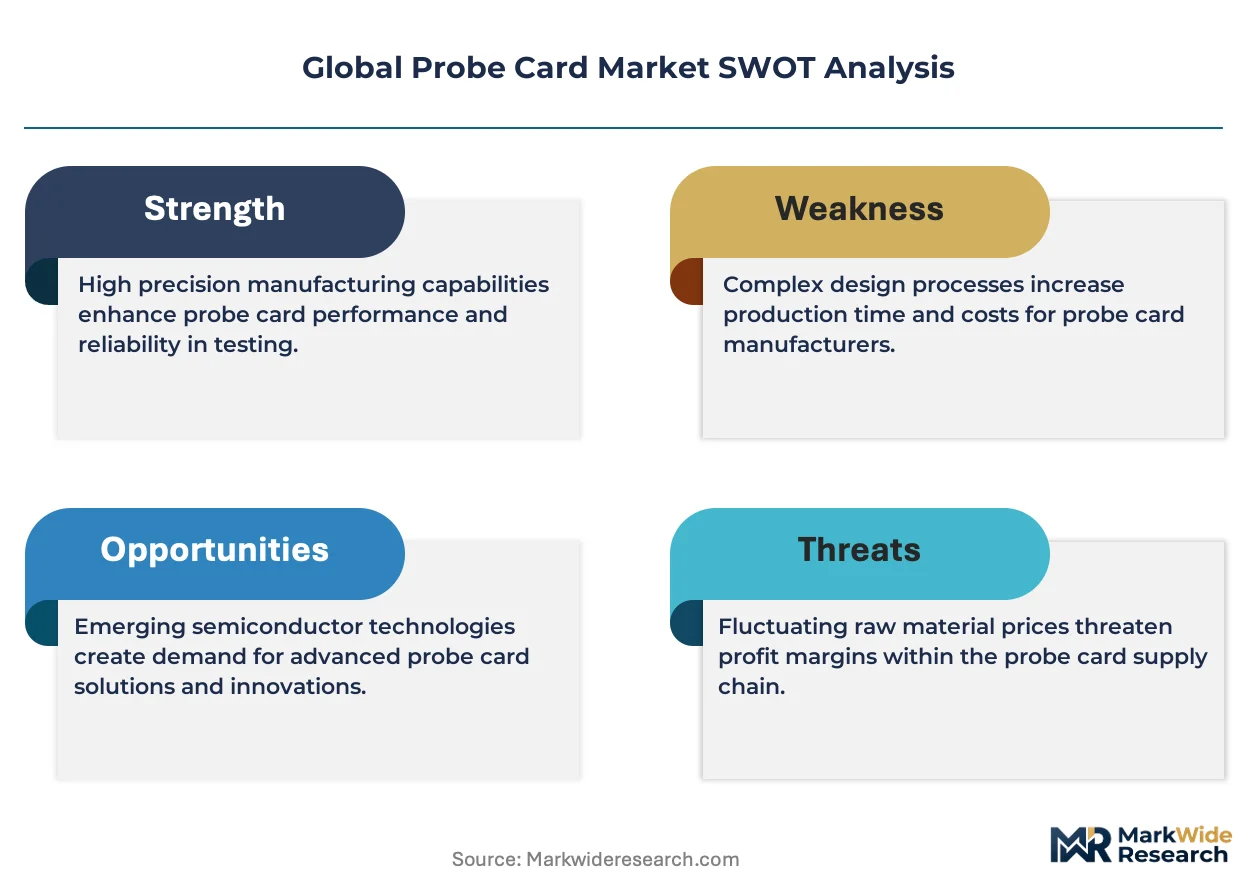
- EU REACH substance restrictions:Hazardous material constraints on beryllium-copper alloys are accelerating tungsten and MEMS spring adoption among European probe card suppliers serving dual-jurisdiction customers.
- Taiwan foundry cluster expansion:Domestic equipment vendors and foreign specialists are establishing parallel production ecosystems to capture advanced packaging test capacity growth.
- Photonics-integrated chip testing:Hybrid probing architectures combining optical and electrical stimuli are gaining traction as silicon photonics packaging scales.
Market Restraints
- Input cost volatility:Tungsten needle and precision ceramic substrate prices fluctuate with mining output constraints and energy-intensive sintering requirements.
- Supply concentration risk:MEMS fabrication depth concentrates among North American and Japanese equipment vendors, creating single-source dependencies for sub-3nm test programs.
- Technical limitation:Cantilever probe architectures face pitch floor constraints below 50 microns, locking them out of leading-edge node qualification.
Strategic Opportunities
- Underpenetrated geography:Indian semiconductor assembly and test facilities present white-space demand for cost-optimized spring probe cards in mature node automotive validation.
- Technology convergence:Co-packaged optics and electrical die testing is creating demand for hybrid probe cards that merge photonic alignment with traditional parametric verification.
- Regulatory tailwind:South Korea's K-Semiconductor Act subsidy eligibility criteria favor local probe card procurement, incentivizing foreign suppliers to establish domestic production partnerships.
Industry Challenges
- MEMS process engineer scarcity:Deep reactive-ion etching and wafer-level packaging expertise pools concentrate in Taiwan and Japan, constraining capacity expansion elsewhere.
- Cleanroom infrastructure intensity:Sub-40 micron pitch probe fabrication requires Class 10 or better environments, elevating capital requirements for new market entrants.
- Multi-jurisdiction certification timelines:Simultaneous EPA hazardous substance compliance and EU REACH registration stretches product qualification cycles for suppliers serving transatlantic customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Probe Card Market |
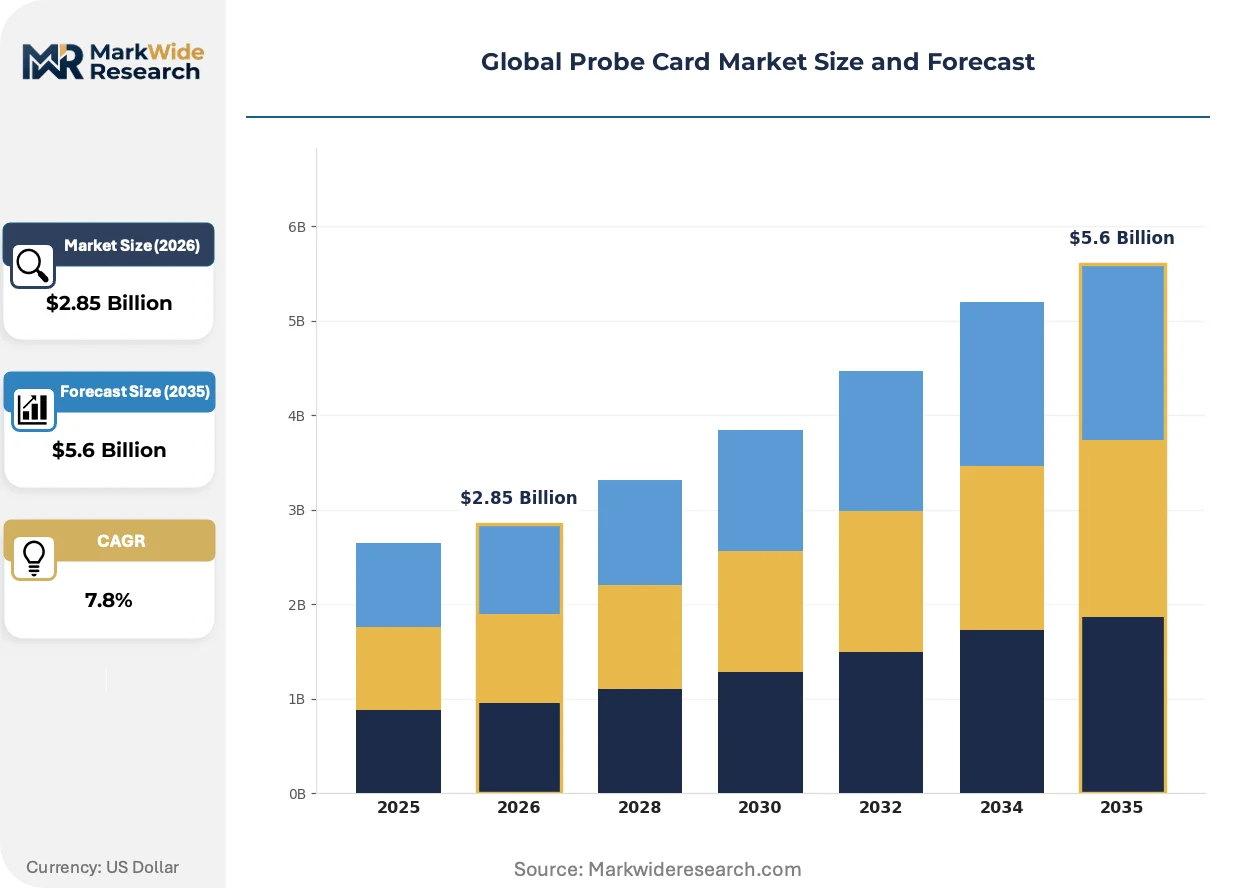
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS Probe Cards, Spring Probe Cards, Smart Probe Cards, Surgical Probe Cards Application: Semiconductor Testing, IC Testing, Wafer Testing, Device Characterization End User: Semiconductor Manufacturers, Electronics Companies, Research Institutes, Automotive Corporations Technology: Mechanical Probing, Electrical Probing, Optical Probing, Hybrid Probing |
| Companies Covered | FormFactor Inc., Technoprobe S.p.A., Micronics Japan Co., Ltd., Advantest Corporation, MPI Corporation, Japan Electronic Materials Corporation, Feinmetall GmbH, SV Probe, Chunghwa Precision Test Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Probe Card Market Shifts & Advancements
Probe technology evolution centers on pitch compression, materials substitution, and test protocol convergence as semiconductor packaging complexity outpaces legacy verification architectures.
MEMS-fabricated spring arrays are collapsing the functional boundary between electrical and thermal test interfaces. Leading-edge foundries in Taiwan and South Korea now specify MEMS probe cards for 3nm production ramps. This architecture is collapsing the market space previously occupied by cantilever designs in sub-7nm applications.
EU REACH chemical restrictions on beryllium compounds are forcing metallurgical pivots toward tungsten-rhenium and palladium-nickel contact alloys. Probe substrate suppliers serving European automotive semiconductor testers must reformulate material declarations. Japanese vendors with captive tungsten needle production are capturing share in REACH-compliant supply chains.
Consolidated procurement by memory and AI chip foundries is compressing supplier qualification cycles and unbundling after-sales service contracts. Equipment vendors now face direct benchmark pressure from captive test engineering teams. This pattern concentrates most visibly in South Korea's Samsung and SK Hynix supply bases, where multi-year framework agreements displace transactional purchasing.
Global Probe Card Market Segmentation
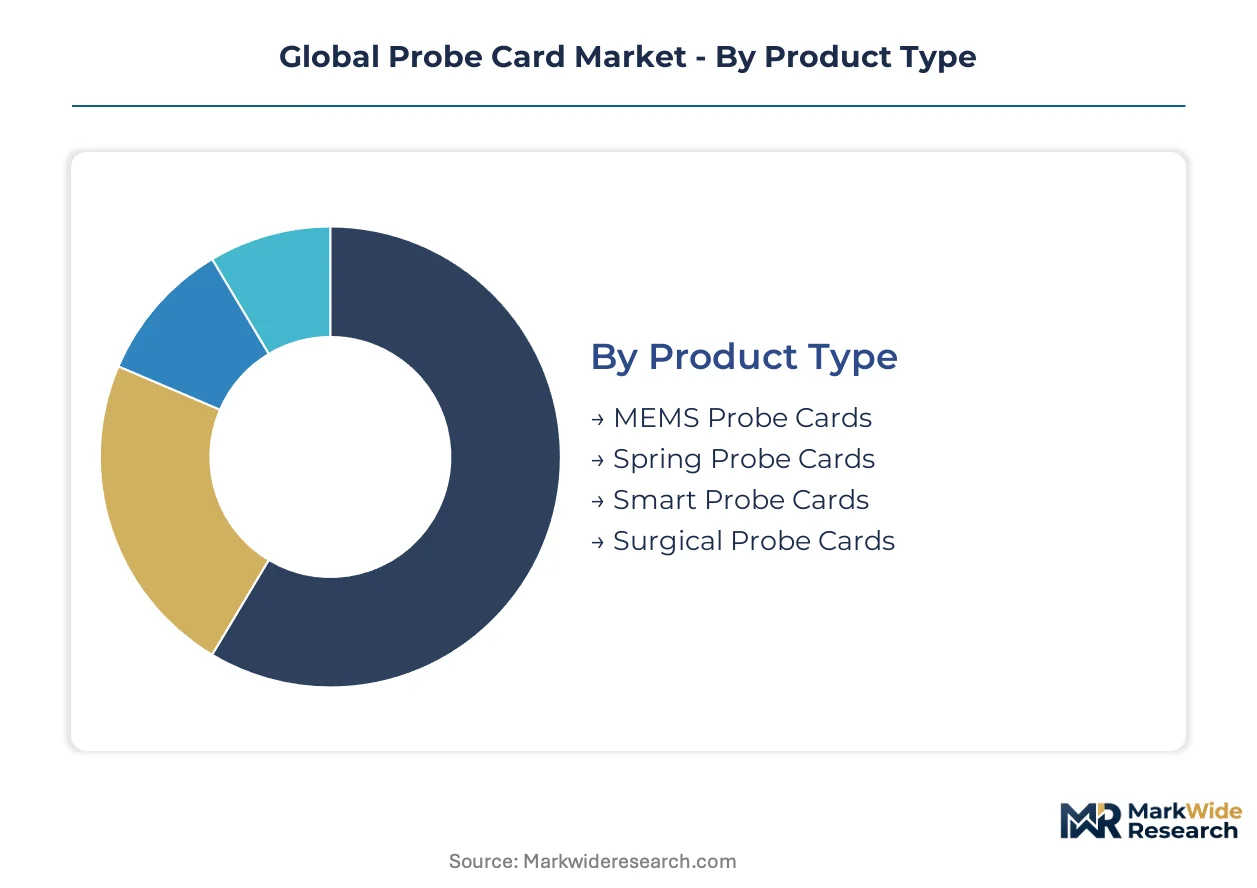
Probe card segmentation reveals how test interface architectures align with semiconductor node requirements, packaging complexity, and end-use reliability standards. Each dimension—product type, application, end user, and probing technology—carries distinct procurement criteria and supplier qualification pathways.
Product Type:
Cost tier stratification separates premium MEMS architectures from mature-node alternatives, with material compliance and pitch capability driving price positioning.
- MEMS Probe Cards:Microelectromechanical spring arrays fabricated through deep reactive-ion etching achieve sub-40 micron pitch with thermal compensation. Taiwan foundries and South Korean memory houses specify these for 3nm production ramps, though MEMS process engineer scarcity constrains capacity expansion outside established fabrication clusters.
- Spring Probe Cards:Coil-spring contact elements machined from beryllium-copper or tungsten alloys retain cost advantages in automotive and power semiconductor validation. Indian assembly and test facilities present white-space demand as these facilities scale mature-node capacity.
- Smart Probe Cards:Embedded sensor arrays enable real-time contact force monitoring and predictive maintenance signaling during wafer test.
- Surgical Probe Cards:Specialized geometries accommodate non-standard wafer layouts and reliability screening protocols for medical-grade semiconductors.
MEMS probe cards command the established base. The steepest expansion runs through spring probe cards serving cost-sensitive automotive validation in emerging test geographies.
Application:
Application focus determines probe density, signal bandwidth, and thermal management specifications as packaging architectures diverge.
- Semiconductor Testing:Parametric and functional verification of logic devices, memory arrays, and mixed-signal circuits. AI accelerator and high-bandwidth memory packaging in South Korea and Taiwan compresses pitch tolerances and forces MEMS displacement of legacy cantilever designs.
- IC Testing:Packaged die validation requiring socket-compatible probe interfaces with reduced pin counts. Electronics contract manufacturers in Vietnam and Malaysia drive procurement for consumer IC categories.
- Wafer Testing:Full-wafer parallel test at sort operations demands probe cards with thousands of simultaneous contacts.
- Device Characterization:Engineering validation and process development requiring programmable contact configurations and extended temperature ranges.
Semiconductor testing anchors volume procurement. Wafer testing climbs the fastest as foundries expand parallel test cell counts.
End User:
Customer type shapes procurement scale, qualification timelines, and service contract structures across the probe card lifecycle.
- Semiconductor Manufacturers:Integrated device foundries and memory houses with captive test engineering teams. Samsung and SK Hynix in South Korea now consolidate procurement through multi-year framework agreements that displace transactional purchasing and compress supplier qualification cycles.
- Electronics Companies:Systems integrators and OEMs with outsourced semiconductor assembly and test operations. These buyers prioritize probe card availability and regional service response over technology leadership.
- Research Institutes:Universities and national laboratories with specialized characterization requirements and extended development timelines.
- Automotive Corporations:Tier-1 suppliers and OEMs with zero-defect reliability protocols for power management and sensor ICs.
Semiconductor manufacturers dominate procurement volume. Automotive corporations gain share fastest as electrification multiplies chip content per vehicle.
Technology:
Probing modality selection converges with packaging evolution as electrical, optical, and thermal test requirements merge.
- Mechanical Probing:Physical contact interfaces with engineered force-deflection characteristics for aluminum and copper pad metallurgies. Legacy cantilever architectures face pitch floor constraints below 50 microns, locking them out of leading-edge node qualification at Taiwan foundries.
- Electrical Probing:Signal transmission architectures optimized for high-frequency measurement integrity and crosstalk suppression. This modality leads volume deployment across all foundry test floors.
- Optical Probing:Non-contact test methods for photonics-integrated devices and failure analysis applications.
- Hybrid Probing:Converged optical alignment and electrical parametric verification for silicon photonics packaging. Co-packaged optics testing in South Korean and Japanese facilities creates demand as electrical and photonic die testing merges.
Electrical probing maintains the installed base. Hybrid probing expands most quickly as photonics integration reshapes packaging test protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEMS fabrication clusters and advanced packaging test floors concentrate supply-side leverage in East Asian foundry ecosystems. Taiwan, South Korea, and Japan anchor probe card demand through captive semiconductor manufacturing capacity. Regulatory frameworks in these jurisdictions shape local content requirements and material compliance pathways.
Taiwan
TSMC and UMC foundry expansions drive sub-40 micron pitch probe specifications for 3nm production ramps. Taiwan's Industrial Development Bureau subsidizes domestic equipment vendor partnerships under the semiconductor equipment localization initiative. Hsinchu Science Park hosts parallel production ecosystems where foreign specialists and local vendors establish MEMS probe card assembly capacity.
South Korea
Samsung and SK Hynix consolidate procurement through multi-year framework agreements for high-bandwidth memory test programs. Seoul's K-Semiconductor Act subsidizes local probe card procurement, compelling foreign suppliers to establish domestic production partnerships. Pyeongtaek and Icheon foundry clusters fragment the supply base as domestic equipment vendors and foreign specialists build parallel ecosystems.
Japan
METI semiconductor equipment standards shape probe substrate material declarations and qualification protocols for automotive semiconductor testers. Nagoya and Kyushu industrial corridors concentrate MEMS process engineering expertise and captive tungsten needle production. Japanese vendors leverage upstream control over refractory metal supply chains to capture share in EU REACH-compliant export markets.
United States
EPA hazardous substance rules constrain beryllium-copper alloy specifications for probe contact metallurgy. California and Arizona foundry-adjacent test engineering operations drive demand for advanced node verification equipment. FormFactor anchors North American supply chains through MEMS fabrication depth serving sub-3nm test programs.
Germany
EU REACH chemical restrictions on beryllium compounds force metallurgical pivots toward tungsten-rhenium contact alloys among probe card suppliers serving European automotive semiconductor testers. Bavaria and Saxony host precision ceramic substrate fabrication for probe card assemblies. Feinmetall exemplifies German equipment vendor positioning in REACH-compliant supply chains.
Global Probe Card Market Competitive Landscape
MEMS fabrication specialists and cantilever probe architects split the market across node-based segmentation lines. North American and Japanese vendors concentrate sub-40 micron pitch capacity through deep reactive-ion etching expertise pools. Three archetypes dominate: vertically integrated tungsten needle producers, MEMS spring array fabricators, and legacy cantilever specialists serving mature node continuity. Competitive moves center on capacity expansion in Taiwan and South Korea alongside strategic partnerships to satisfy local content requirements.
Among North American equipment vendors, FormFactor Inc. anchors the MEMS fabrication archetype through silicon spring array production. Japanese specialists Micronics Japan Co., Ltd. and Japan Electronic Materials Corporation occupy positions in cantilever probe architectures and precision substrate supply. Italian vendor Technoprobe S.p.A. represents European positioning through upstream control over tungsten needle manufacturing. These three exemplify how geographic fabrication clusters align with distinct technology specializations.
| Leading Market Players |
|---|
| FormFactor Inc. |
| Technoprobe S.p.A. |
| Micronics Japan Co., Ltd. |
| Advantest Corporation |
| MPI Corporation |
| Japan Electronic Materials Corporation |
| Feinmetall GmbH |
| SV Probe |
| Chunghwa Precision Test Tech Co., Ltd. |
| Others |
Supply & Pricing Matrix
Hsinchu Science Park MEMS fabrication clusters concentrate sub-40 micron pitch probe capacity, translating upstream cleanroom intensity into premium pricing power for advanced node test programs. Taiwan's foundry-adjacent equipment vendors capture margin premiums through captive proximity to TSMC and UMC qualification pipelines.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across European automotive semiconductor test supply chains. Three-tier pricing stratifies across MEMS premium architectures, standard spring probe configurations, and economy cantilever designs for legacy node validation. Price differentiation hinges on certification grade for hazardous material compliance and volume scale of multi-year framework agreements. Cost compression in spring probe tiers is intensifying as Indian assembly facilities scale mature-node capacity. Automotive semiconductor manufacturers in Germany exhibit highest price sensitivity, while South Korean memory houses prioritize pitch capability over unit economics.
Supply Chain Analysis
Export control expansions limiting probe technology transfer to Chinese fabs are fragmenting sourcing strategies among multinational equipment vendors. Taiwan, South Korea, and Japan anchor upstream MEMS fabrication and tungsten needle production. Deep reactive-ion etching equipment and precision ceramic substrates draw from concentrated Japanese and North American suppliers. Single-source vulnerability runs through MEMS process engineering expertise pools in Hsinchu and Nagoya. Distribution runs through direct sales to foundry test engineering teams and specialized semiconductor equipment distributors serving contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Probe card market fragmentation creates entry niches as hybrid photonics-electrical test requirements outpace incumbent specialization. AI accelerator packaging complexity multiplies probe architecture variants beyond standardized product lines.
For Market Incumbents: Insulate MEMS fabrication depth through captive cleanroom capacity expansion in Taichung and Pyeongtaek. Acquire tungsten needle production capabilities to secure REACH-compliant metallurgy supply chains against Japanese upstream competitors. Deepen backward integration into precision ceramic substrate fabrication to defend margin position against input cost volatility. For New Entrants and Emerging Players: Cost-optimized spring probe cards for automotive validation at Indian semiconductor assembly facilities represent the most penetrable entry point. Hybrid probe architectures for silicon photonics testing in Japanese and South Korean facilities offer technology differentiation without direct MEMS competition. Partner with domestic equipment vendors under Taiwan's localization initiative to bypass qualification barriers at foundry test floors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive probe card divisions lacking scale for advanced node competition. Long-term viability centers on sub-3nm test program participation and photonics integration capabilities. Watch for inflection signals in South Korea's K-Semiconductor Act subsidy disbursement patterns indicating local content preference enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Capacity Expansion | Taiwan foundries specify sub-40 micron pitch for 3nm production ramps. |
| Tungsten Needle Backward Integration | EU REACH compliance requires captive refractory metal supply chains. |
| Hybrid Probe Architecture Development | Co-packaged optics testing merges photonic alignment with electrical verification. |
| Indian Market Entry Partnership | Mature-node automotive validation demand scales at assembly and test facilities. |
| Local Production Joint Venture | South Korea's K-Semiconductor Act subsidizes domestic probe card procurement. |
Research Methodology
A standing panel of probe card test engineering directors, semiconductor equipment procurement managers, MEMS process engineers, and foundry operations executives provided ongoing calibration across the study period. Primary interviews combined with secondary validation from SEC filings of listed equipment vendors, Taiwan's Industrial Development Bureau subsidy disclosures, and EU REACH registration databases. Bottom-up unit demand modeling and top-down equipment spending triangulation anchored market size estimation.
Scenario-bracketing framed high and low cases around foundry capex cycle amplitude and photonics integration adoption curves. Segmentation dimensions spanned product architecture, application test protocol, end-user procurement scale, and probing technology modality across the projection horizon. CAGRs derived from node migration timelines and advanced packaging test floor expansion plans. Forecast inputs incorporated tungsten price trajectories and cleanroom construction lead times.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles and memory pricing would shift the trajectory. Forecasts reflect assumptions on foundry node ramp schedules and regulatory enforcement intensity. Material shifts in export control scope or REACH substance restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Global Power MOSFET Market