
 CMP Pads Market | 2026-2036
CMP Pads Market Size, Share, and Industry Trends Forecast 2026-2036
CMP Pads Market Analysis
Advanced logic semiconductor manufacturing is repositioning CMP pad procurement toward finer-pore polyurethane formulations that withstand multiple platen cycles. DuPont de Nemours Inc sustains technology leadership through its deep materials science heritage in polymer matrix design. Fujibo Holdings Inc anchors Asian supply security with manufacturing proximity to major foundry clusters. Cabot Corporation differentiates via specialized additive integration that enhances removal rate consistency.
CMP pads are porous polyurethane matrix components impregnated with abrasive particles and chemical reactants, engineered to achieve angstrom-level surface flatness during wafer planarization. The manufacturing process requires controlled pore size distribution between 30-50 microns and precise groove patterns for slurry transport. Silicon Wafers command the largest product type volume as substrate polishing remains the dominant consumption point. Surface Planarization applications are expanding fastest as 3D NAND stacking and advanced packaging architectures multiply CMP steps per wafer. Dielectric Materials processing carries premium pricing due to defect sensitivity at sub-10nm nodes.
EPA regulations on volatile organic compound emissions constrain pad solvent formulations and manufacturing plant permitting in the United States. REACH compliance in Europe mandates full chemical substance registration throughout the polyurethane supply chain, elevating documentation burdens for importers. Taiwan's environmental regulator enforces wastewater treatment standards that affect slurry disposal protocols tied to pad usage. Stakeholders must monitor evolving PFAS restriction timelines across multiple jurisdictions to anticipate chemistry reformulation requirements and qualification cycles.
Market Dynamics
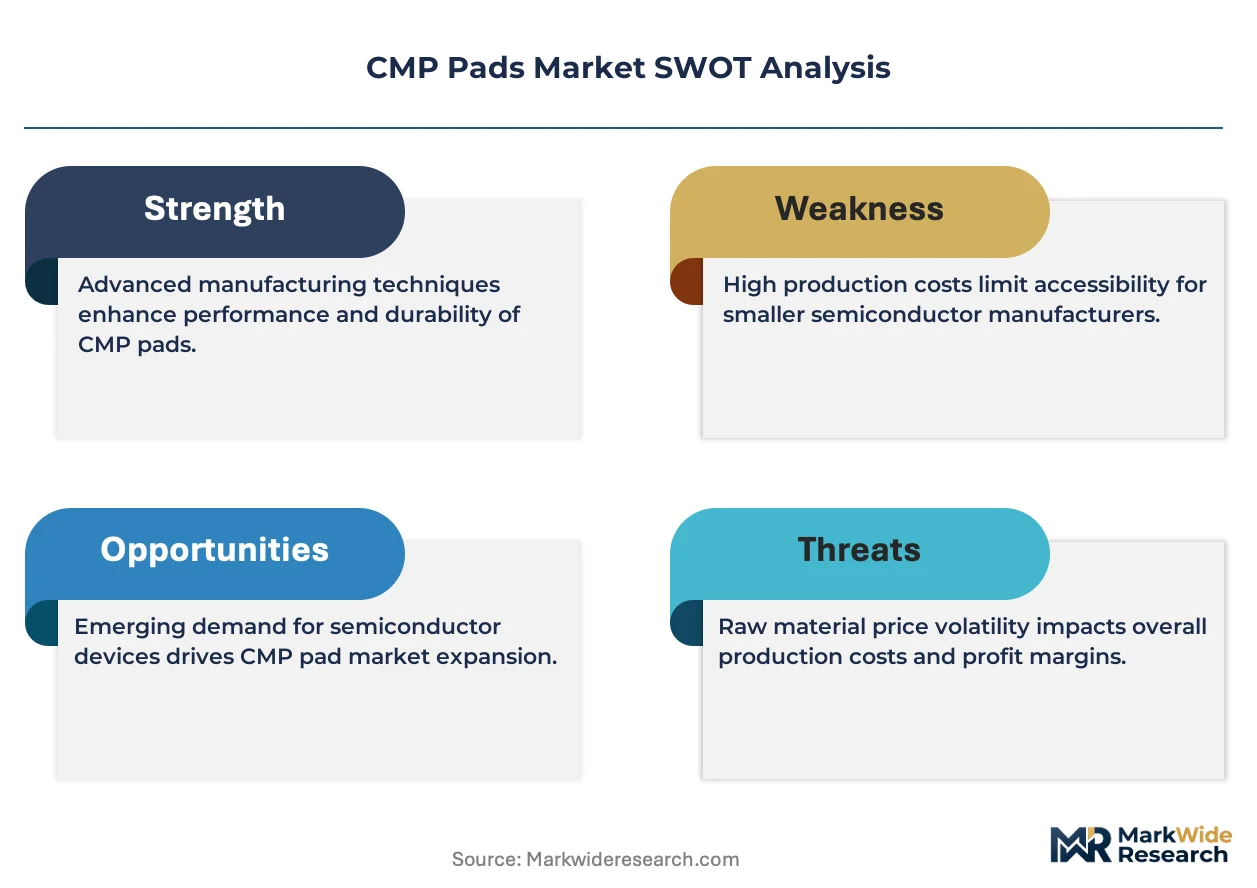
Node shrinkage below 7nm is forcing polyurethane matrix reformulation as angstrom-level flatness tolerances collide with multi-platen cycle durability requirements. This structural tension between precision and longevity is concentrating procurement power among foundries with advanced logic and memory capacity.
Growth Catalysts
- 3D NAND stacking:Vertical memory architectures multiply CMP steps per wafer, expanding pad consumption per substrate.
- REACH compliance:Full chemical substance registration mandates are accelerating qualification of cleaner polyurethane formulations across European supply chains.
- Taiwan foundry clustering:Leading-edge capacity concentration in Hsinchu and Tainan Science Parks is generating localized demand density for just-in-time pad delivery.
Market Restraints
- Isocyanate price volatility:Feedstock cost swings for MDI and TDI precursors compress polyurethane matrix margins unpredictably.
- Single-source groove pattern tooling:Precision machining equipment for slurry channel formation concentrates among Japanese and German equipment builders.
- Sub-10nm defect sensitivity:Dielectric polishing at advanced nodes demands contamination controls that extend qualification cycles.
Strategic Opportunities
- India semiconductor fabs:PLI scheme subsidies for domestic foundry construction are creating greenfield pad supply relationships outside established clusters.
- Advanced packaging integration:Hybrid bonding and chiplets are introducing CMP steps at packaging stages previously limited to front-end processing.
- Slurry-pad bundling:Integrated consumable procurement contracts are displacing separate chemical and pad sourcing in Taiwan and South Korea.
Industry Challenges
- Pore size distribution control:Maintaining 30-50 micron uniformity across production lots requires metrology capabilities scarce among mid-tier manufacturers.
- PFAS chemistry transition:Anticipating multi-jurisdiction restriction timelines demands R&D coordination with polyurethane additive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMP Pads Market |
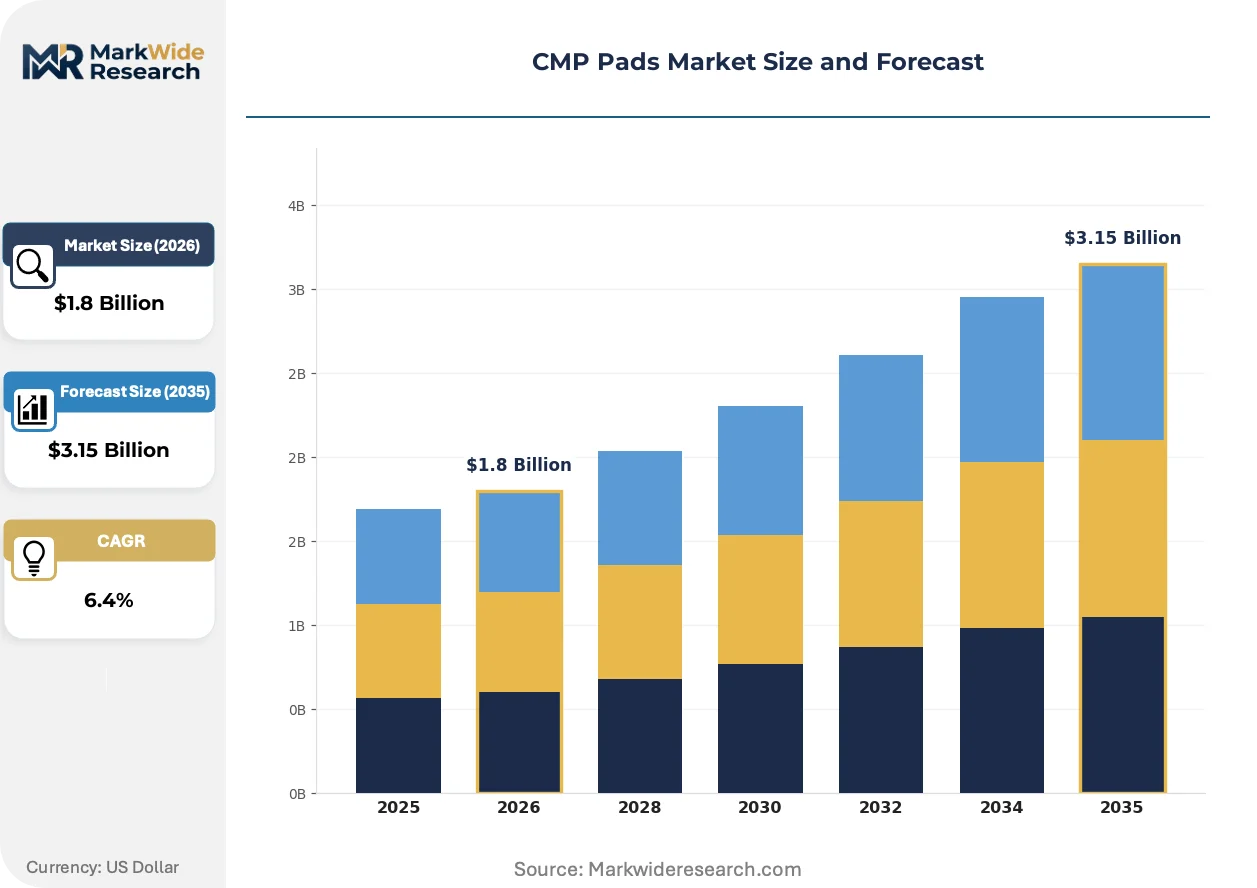
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Wafers, Dielectric Materials, Polishing Slurries, Additives End User: Semiconductor Manufacturers, Electronics Producers, Optical Component Makers, Laboratories Application: Wafer Fabrication, Electronics Packaging, Thin Film Deposition, Surface Planarization Technology: Chemical Mechanical Planarization, Slurry-Based Processing, Tooling Systems, Automated Solutions |
| Companies Covered | Fujibo Holdings Inc, Pureon, DuPont de Nemours Inc, Hubei DingLong, SK enpulse, 3M Company, Cabot Corporation, Thomas West Inc, Entegris Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMP Pads Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are reshaping how polyurethane matrices achieve planarization performance. The convergence of environmental compliance and precision manufacturing is opening new formulation pathways.
Sub-50nm pore polyurethane technology is converging with ceramic abrasive integration to achieve removal rate consistency at angstrom-level surface finishes. Memory fabs in South Korea are adopting these formulations fastest for 3D NAND string stacking. The structural consequence is compressing pad replacement cycles as multi-platen durability becomes the binding constraint.
EPA volatile organic compound emission limits are constraining solvent formulations used in pad manufacturing plant permitting across the United States. Facilities in Arizona and Texas face extended environmental review timelines for capacity expansion. Dielectric processing applications bear the highest compliance burden as contamination sensitivity limits alternative solvent options.
Consolidated procurement contracts are displacing separate slurry and pad sourcing arrangements among Taiwan-based foundries. Integrated consumable vendors are capturing volume commitments previously split across chemical and pad specialists. This pattern is most visible in Hsinchu Science Park where leading-edge logic manufacturers negotiate bundled supply agreements.
CMP Pads Market Segmentation
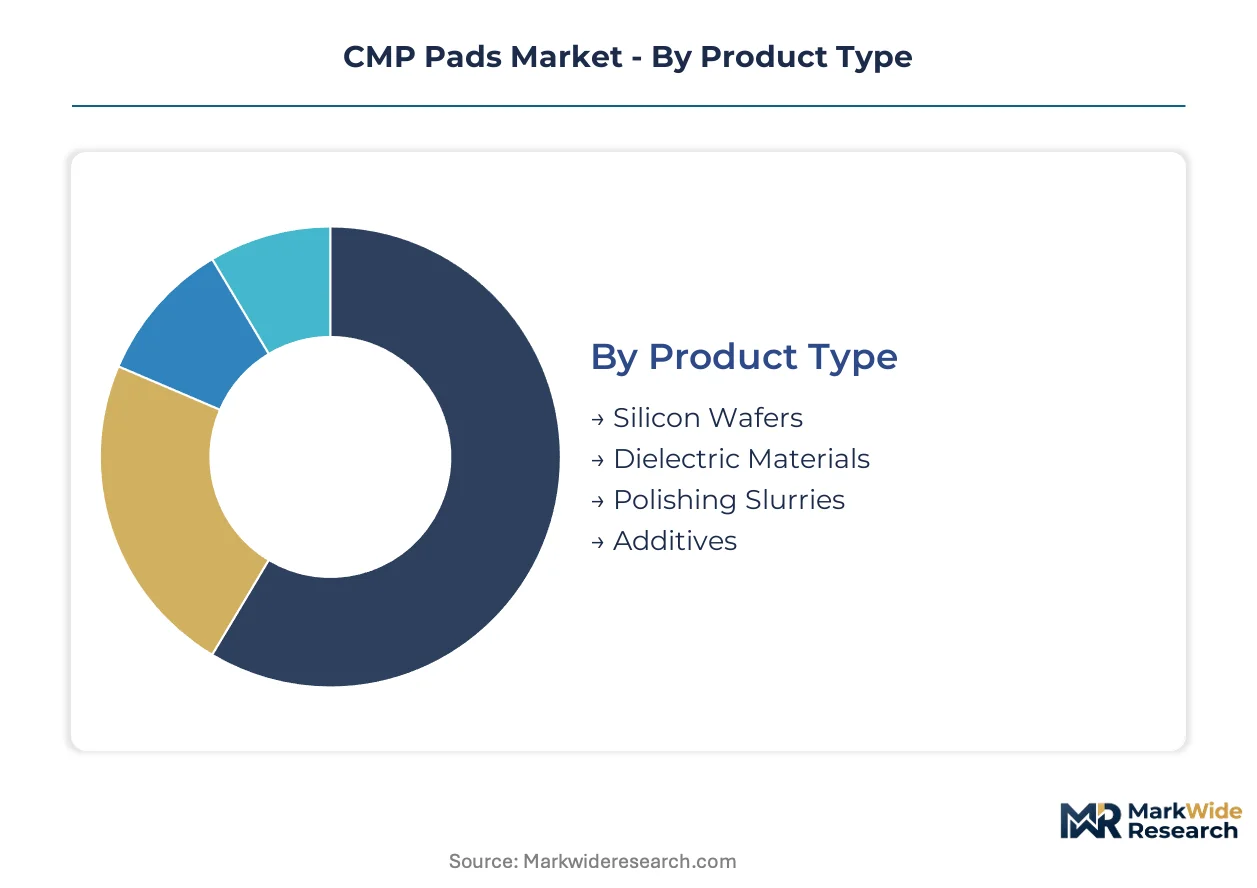
CMP pad procurement patterns diverge sharply across semiconductor process steps, with node complexity and contamination sensitivity dictating formulation requirements. Understanding these segment boundaries clarifies where polyurethane matrix investments concentrate and where qualification cycles extend.
Product Type:
Capital intensity peaks where pore size distribution tolerances tighten and groove pattern precision demands specialized metrology infrastructure.
- Silicon Wafers:Porous polyurethane matrices engineered for substrate polishing dominate volume consumption across foundry operations. Taiwan-based manufacturers in Hsinchu Science Park drive procurement density for standard silicon polishing applications where multi-platen durability outweighs premium formulation costs.
- Dielectric Materials:Ultra-low defect polyurethane formulations command the highest per-pad pricing due to angstrom-level flatness requirements at sub-10nm nodes. South Korean memory fabs absorb the majority of dielectric-specific capacity as 3D NAND string stacking multiplies planarization steps per wafer.
- Polishing Slurries:Abrasive particle dispersions requiring compatible pad surface chemistry for consistent removal rates.
- Additives:Chemical reactants integrated into pad matrices to enhance selectivity and reduce scratching.
Silicon Wafers absorb the bulk of installed capacity; Dielectric Materials is expanding most quickly.
End User:
Customer scale determines procurement leverage, with the largest fabs consolidating supply relationships through multi-year integrated consumable contracts.
- Semiconductor Manufacturers:Leading-edge logic and memory foundries in Taiwan, South Korea, and the United States specify custom polyurethane formulations qualified to their exact tool configurations. These buyers negotiate slurry-pad bundling agreements that displace separate chemical and pad sourcing arrangements.
- Electronics Producers:OSATs and IDMs with trailing-edge capacity purchase standardized pads through distribution channels with shorter qualification cycles and lower minimum order quantities.
- Optical Component Makers:Precision optics manufacturers requiring surface flatness for lens polishing and photonics substrates.
- Laboratories:R&D facilities and academic institutions procuring small-batch pads for process development and materials characterization.
Semiconductor Manufacturers concentrate procurement power; Electronics Producers are gaining share fastest as advanced packaging capacity expands.
Application:
Process step location within the fabrication flow determines pad replacement frequency and contamination control requirements.
- Surface Planarization:Angstrom-level finishing applications for 3D NAND stacking and advanced packaging architectures multiply CMP steps per wafer. Memory fabs in South Korea adopt sub-50nm pore polyurethane formulations fastest as vertical string stacking compresses pad replacement cycles.
- Wafer Fabrication:Front-end processing steps including oxide and metal polishing where standard groove patterns suffice.
- Electronics Packaging:Hybrid bonding and chiplet integration introduce CMP steps at packaging stages previously limited to front-end processing.
- Thin Film Deposition:Pre-deposition surface preparation requiring controlled removal rates to preserve underlying structures.
Wafer Fabrication holds the largest installed base; Surface Planarization is climbing the fastest as 3D architectures proliferate.
Technology:
Equipment integration depth separates vendors capable of full-stack solutions from component specialists.
- Chemical Mechanical Planarization:The dominant process technology combining abrasive slurry with polyurethane pad mechanical action. EPA volatile organic compound emission limits constrain solvent formulations in United States manufacturing facilities, extending environmental review timelines for capacity expansion in Arizona and Texas.
- Slurry-Based Processing:Chemistry-centric approaches where pad properties are secondary to abrasive particle engineering.
- Tooling Systems:Precision machining equipment for groove pattern formation concentrates among Japanese and German equipment builders, creating single-source dependencies.
- Automated Solutions:Pad handling and conditioning systems reducing particle contamination through robotic integration.
Chemical Mechanical Planarization anchors the technology base; Automated Solutions are gaining traction fastest as contamination controls tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park tax incentives concentrate Taiwan's leading-edge foundry capacity, generating the densest CMP pad procurement cluster worldwide. Localized demand density forces just-in-time delivery networks and integrated consumable contracting patterns.
Taiwan
Advanced logic fabs in Hsinchu and Tainan Science Parks multiply CMP steps per wafer as node sizes shrink below 7nm. The country's environmental regulator enforces wastewater treatment standards affecting slurry disposal protocols tied to pad usage. Hsinchu Science Park anchors localized demand density where foundries negotiate bundled slurry-pad supply agreements.
United States
Memory and logic manufacturing expansion in Arizona and Texas drives polyurethane matrix consumption for sub-10nm planarization. EPA volatile organic compound emission limits constrain solvent formulations and extend environmental review timelines for capacity expansion. Greater Phoenix and Austin metro areas concentrate new fab construction where dielectric processing applications bear the highest compliance burden.
South Korea
3D NAND string stacking at Pyeongtaek and Yongin complexes multiplies CMP steps per wafer, accelerating sub-50nm pore polyurethane adoption. The country's national environmental regulator enforces industrial wastewater standards affecting slurry disposal from pad conditioning. Samsung and SK Hynix operations in Gyeonggi Province dominate dielectric-specific capacity absorption.
China
Domestic memory and logic fab construction in Shanghai and Beijing-Tianjin-Hebei corridors expands polyurethane matrix demand for local supply security. The Ministry of Ecology and Environment implements dual carbon goals constraining manufacturing plant energy intensity. Yangtze River Delta fabs in Wuxi and Hefei represent the fastest-expanding regional consumption point.
Japan
Precision groove pattern tooling and metrology equipment manufacturing in Nagoya and Osaka sustains critical supply chain dependencies for pad producers. METI industrial standards govern polyurethane matrix quality certification for semiconductor applications. Chubu and Kansai industrial corridors concentrate Japanese and German equipment builder relationships for slurry channel formation machinery.
CMP Pads Market Vendor Landscape
Top-tier vendors anchor technology leadership through polymer matrix design heritage, while mid-scale specialists occupy regional supply security positions. The vendor base stratifies across integrated materials science conglomerates, Asian proximity fabricators, and additive integration specialists. Three archetypes dominate: heritage chemical conglomerates with deep R&D infrastructure, geography-anchored suppliers serving clustered foundry demand, and component specialists focusing on removal rate consistency. Competitive moves concentrate on multi-year integrated consumable contracting and chemistry reformulation partnerships anticipating PFAS restriction timelines.
Among heritage-anchored materials conglomerates, DuPont de Nemours Inc exemplifies polymer matrix design leadership, while Fujibo Holdings Inc represents Asian supply security through manufacturing proximity to major foundry clusters. Cabot Corporation occupies the additive integration specialist position, enhancing removal rate consistency through specialized chemical reactant incorporation. These three entities illustrate how competitive positioning diverges between technology depth, geographic embedding, and component specialization vectors.
| Leading Market Players |
|---|
| Fujibo Holdings Inc |
| Pureon |
| DuPont de Nemours Inc |
| Hubei DingLong |
| SK enpulse |
| 3M Company |
| Cabot Corporation |
| Thomas West Inc |
| Entegris Inc |
| Others |
Supply Flow & Price Mechanics
Captive polyurethane matrix production in Taiwan and South Korea anchors both supply security and pricing leverage for leading-edge foundries. This integration choice concentrates procurement power among fabs with multi-year qualification cycles, while spot buyers face extended lead times for dielectric-grade formulations.
Pricing Analysis
Short-lead-time premiums of 15-25% apply to dielectric-grade pads for sub-10nm node qualification, while spot inventory in standard silicon polishing trades at discounts. Contract-based long-term offtake dominates Taiwan and South Korea, with pricing stratifying across premium (dielectric, sub-50nm pore), standard (silicon substrate, multi-platen durability), and economy (trailing-edge, shorter cycle) tiers. Cost compression in standard silicon polishing intensifies as Chinese suppliers expand capacity. Electronics producers with trailing-edge fabs exhibit highest price sensitivity; leading-edge logic foundries prioritize qualification stability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German equipment builders supplying precision groove pattern tooling for slurry channel formation. Polyurethane matrix production concentrates in Taiwan, South Korea, and the United States, drawing from MDI and TDI isocyanate feedstocks plus ceramic abrasive suppliers. Tariff exposure on Chinese precursor imports threatens margin stability for US-based pad manufacturers. Distribution runs through direct foundry contracts in Hsinchu and Pyeongtaek, with consolidated slurry-pad bundling displacing separate channel arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pore size distribution metrology scarcity props pricing for qualified suppliers, creating a supply-constrained market structure favoring incumbents with capital-intensive quality infrastructure.
For Market Incumbents: Anchor technology leadership through backward integration into isocyanate precursor supply and captive metrology capabilities for 30-50 micron pore uniformity. Threats from Chinese capacity expansion in standard silicon polishing demand certification investment in REACH-compliant formulations. Capacity addition in Arizona and Texas captures US fab construction momentum while EPA permitting timelines extend competitive moats. For New Entrants and Emerging Players: Enter via India's PLI-subsidized fab construction, where greenfield supplier relationships lack incumbent lock-in. The most penetrable segment sits in trailing-edge silicon polishing for domestic Chinese memory fabs, where qualification cycles compress versus dielectric grades. A joint venture with established abrasive suppliers accelerates removal rate consistency without multi-year R&D timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated consumable vendors capturing slurry-pad bundling volume in Taiwan. Long-term viability favors suppliers with demonstrated PFAS chemistry transition capabilities and foundry-qualified sub-50nm pore formulations. Watch EPA restriction timelines on perfluorinated compounds as the inflection signal for chemistry reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | MDI and TDI feedstock control insulates margins from petrochemical volatility affecting polyurethane matrix costs. |
| Sub-50nm Pore Technology Qualification | Samsung and SK Hynix 3D NAND stacking demands compress replacement cycles for premium dielectric formulations. |
| PFAS Chemistry Reformulation Partnership | REACH and EPA restriction timelines force R&D coordination with additive suppliers for compliant pad matrices. |
| India Greenfield Supply Relationship | PLI scheme subsidies for domestic fab construction create first-mover advantages outside established Taiwan-South Korea clusters. |
| Slurry-Pad Bundling Contract Capture | Integrated consumable procurement in Hsinchu Science Park displaces separate chemical and pad sourcing arrangements. |
Methodological Framework
Independent corroboration across fab procurement executives, polyurethane R&D directors, and slurry formulation specialists underwrites the qualitative findings. Primary interviews with plant managers at Hsinchu and Pyeongtaek facilities, combined with secondary validation through SEMI equipment spending data, customs trade records for isocyanate imports, and EPA permitting disclosures, established supply chain topology. Bottom-up wafer start projections and top-down consumable intensity modeling triangulate market sizing.
Comparable-period anchoring to historical CMP step multiplication rates across 3D NAND generations and logic node transitions structured the projection horizon. Segmentation dimensions modeled include product type (silicon wafer, dielectric, slurry, additive), end user scale (leading-edge foundry, trailing-edge IDM, OSAT), and application stage (front-end planarization, advanced packaging). CAGRs derived from wafer start forecasts and consumable intensity curves, with node shrinkage pace and environmental regulation timing as key uncertainty inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction implementation or isocyanate supply disruption scenarios. Forecasts reflect documented assumptions on foundry capacity buildout schedules and qualification cycle durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market