
 APAC Semiconductor Device for Industrial Applications Market | 2026-2036
APAC Semiconductor Device for Industrial Applications Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Semiconductor Device for Industrial Applications Market Insights
A widening capability gap in advanced node fabrication is unwinding competitive parity among APAC semiconductor suppliers. Nvidia Corporation leverages its CUDA ecosystem and AI accelerator architectures to dominate high-performance industrial computing workloads. Intel Corporation sustains significant manufacturing scale through its foundry investments across the region. Texas Instruments Inc. anchors its position with deep analog portfolios purpose-built for harsh industrial environments.
APAC semiconductor devices for industrial applications comprise integrated circuits, discrete components, and module assemblies engineered for operating temperatures spanning negative forty to one hundred twenty-five degrees Celsius, with primary functions spanning motor control, power conversion, real-time sensing, and deterministic logic execution in automated production environments. Microcontrollers and power transistors command the largest revenue pools owing to their ubiquity across automation systems and robotics platforms, while sensors represent the fastest-expanding category as predictive maintenance architectures proliferate in manufacturing and energy end-use segments. Mixed-signal technology captures disproportionate margins by bridging precision measurement with digital processing in closed-loop control applications.
Japan's METI enforces JIS standards for industrial semiconductor reliability, while China's MIIT administers GB standards governing electromagnetic compatibility and energy efficiency in factory equipment. South Korea's MFDS intersects with semiconductor quality frameworks through its broader industrial safety mandates, creating layered compliance obligations for suppliers. Stakeholders must monitor how divergent national standardization timelines across these three regulatory jurisdictions reshape product certification costs and time-to-market strategies.
Market Dynamics
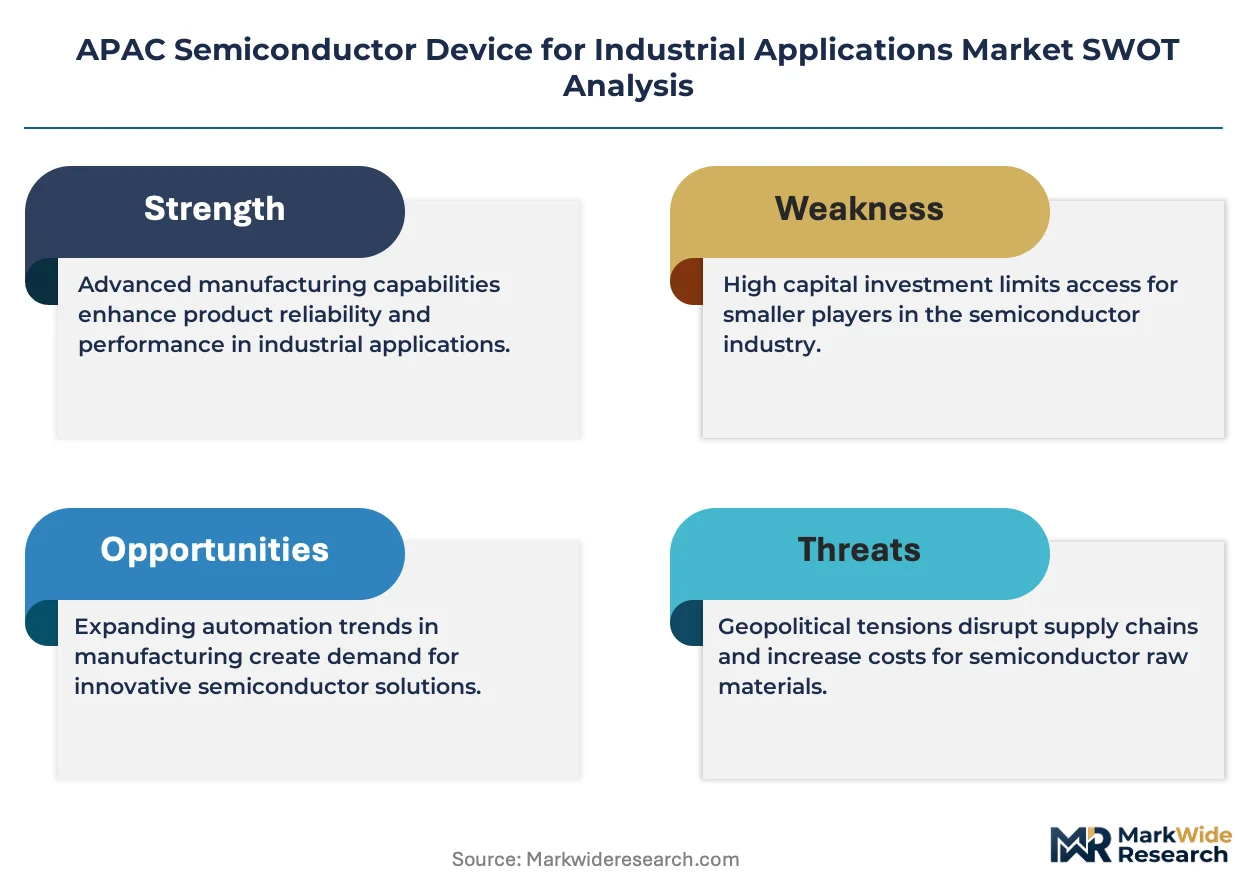
China's MIIT dual carbon mandates are compressing supplier margins while accelerating analog-to-digital transitions in motor control systems across East Asian manufacturing clusters.
Growth Catalysts
- Factory Automation Density:South Korean semiconductor manufacturing clusters are deploying edge-computing nodes at machine-tool interfaces. Real-time deterministic logic execution is displacing relay-based architectures in precision assembly lines.
- MEE Energy-Efficiency Mandates:China's dual carbon goals are forcing industrial equipment OEMs to source wide-bandgap power transistors. GB standards compliance now gates market access for motor drive inverters above 75kW.
- Predictive Maintenance Architectures:Vibration and thermal sensing arrays are proliferating in Japanese automotive stamping plants. Sensor fusion algorithms demand mixed-signal ICs with sub-microsecond latency.
Market Restraints
- Advanced Node Concentration:Sub-7nm logic fabrication is consolidating in Taiwan and South Korea. Industrial MCU suppliers face foundry allocation constraints during consumer electronics demand spikes.
- Silicon Carbide Substrate Scarcity:150mm SiC wafer supply is tightening as automotive traction inverters compete for material. Power module lead times for industrial motor drives have extended to 26-30 weeks.
- Cross-Border Certification Friction:Divergent JIS, GB, and MFDS testing protocols force redundant qualification cycles. Multi-jurisdiction product launches now require 14-18 month certification timelines.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Industrial zones in Bac Ninh and Hai Phong are attracting semiconductor packaging investment. Localized module assembly can bypass ASEAN tariff escalations on finished goods.
- Digital Twin Integration:Physics-based simulation platforms are converging with embedded sensor networks. Semiconductor vendors can capture recurring revenue through firmware-enabled feature licensing.
- India PLI Scheme Tailwinds:Production-linked incentives for electronic components are reducing effective tax rates for greenfield fab investments. Industrial power discrete packaging is qualifying under revised eligibility criteria.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Precision analog circuit expertise is concentrating among senior engineers in Tokyo and Seoul. Succession planning gaps are delaying next-generation ADC architectures.
- Legacy Fieldbus Integration:EtherCAT and PROFINET migration requires backward-compatible PHY designs. Customers demand 15-year supply continuity for installed-base maintenance.
- IP Licensing Complexity:ARM architecture royalties and RISC-V patent pools are creating royalty stacking risks. MCU vendors must navigate instruction-set licensing across multiple foundry partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Semiconductor Device for Industrial Applications Market |
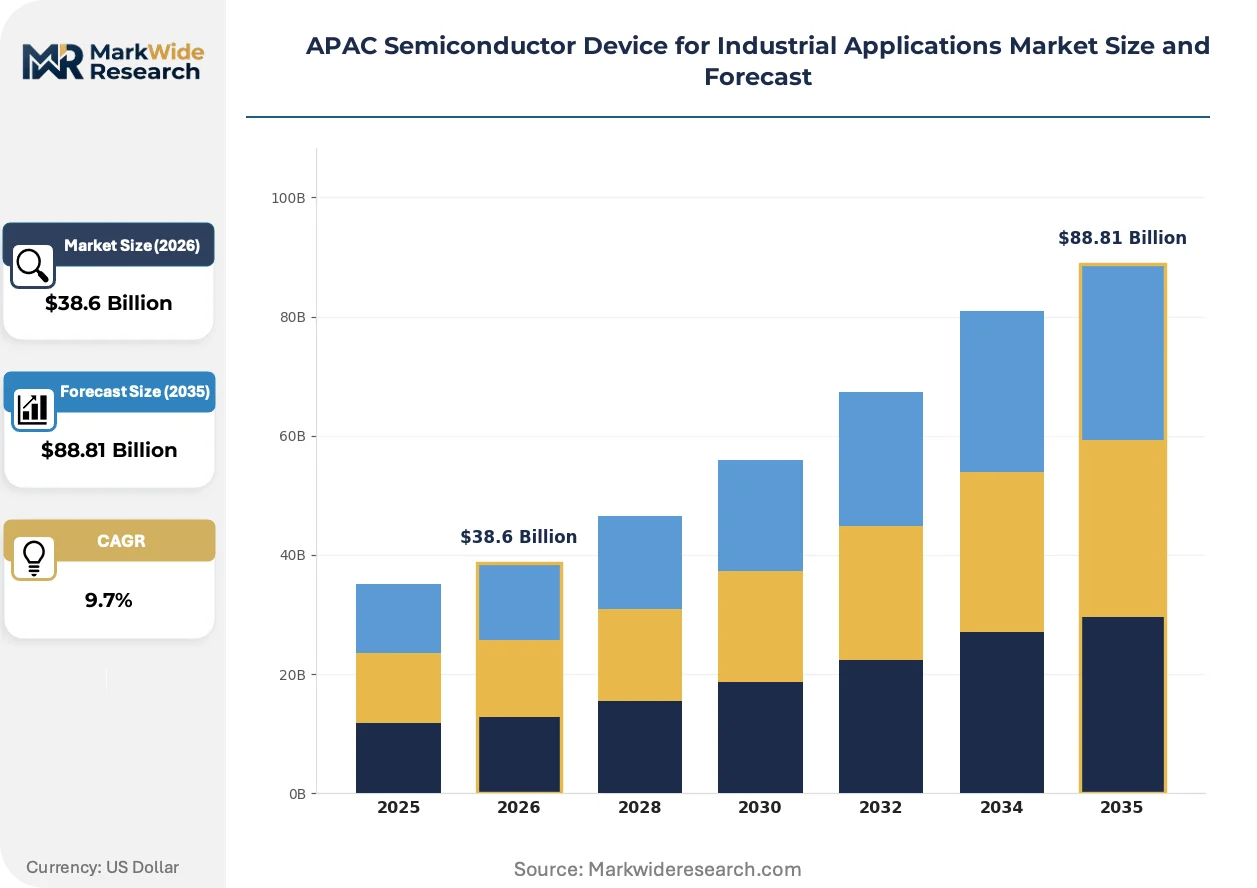
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $88.81 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Sensors, Power Transistors, Memory Chips Technology: Analog, Digital, Mixed-Signal, RF Application: Automation Systems, Robotics, Energy Management, Control Systems End User: Manufacturing, Transportation, Energy, Telecommunications |
| Companies Covered | Nvidia Corporation, Intel Corporation, Qualcomm Incorporated, STMicroelectronics NV, Infineon Technologies AG, NXP Semiconductors NV, Texas Instruments Inc., ON Semiconductor Corporation, ROHM Semiconductor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Semiconductor Device for Industrial Applications Market Trends and Innovations
Silicon carbide and gallium nitride power devices are restructuring thermal management paradigms in industrial motor drives. Edge AI inference is compressing latency requirements for real-time control loops.
GaN HEMT technology is miniaturizing power conversion stages in compact servo amplifiers. Japanese machine tool builders are adopting 650V GaN devices for spindle drives below 5kW. Package thermal resistance is shrinking by 40% versus silicon superjunction MOSFETs, enabling air-cooled designs previously requiring liquid cooling.
China's MIIT GB/T 18488 standard revisions are mandating electromagnetic compatibility testing above 150kHz for variable frequency drives. Industrial equipment OEMs must redesign gate driver isolation architectures. South Korean inverter manufacturers are accelerating qualification of integrated isolated power modules to compress recertification timelines.
Direct procurement contracts between semiconductor vendors and industrial OEMs are displacing tiered distribution networks. Large automation integrators in South Korea are negotiating multi-year die-bank agreements. Price transparency is improving as volume commitments replace spot-market purchasing for power discretes above 100A ratings.
APAC Semiconductor Device for Industrial Applications Market Segmentation
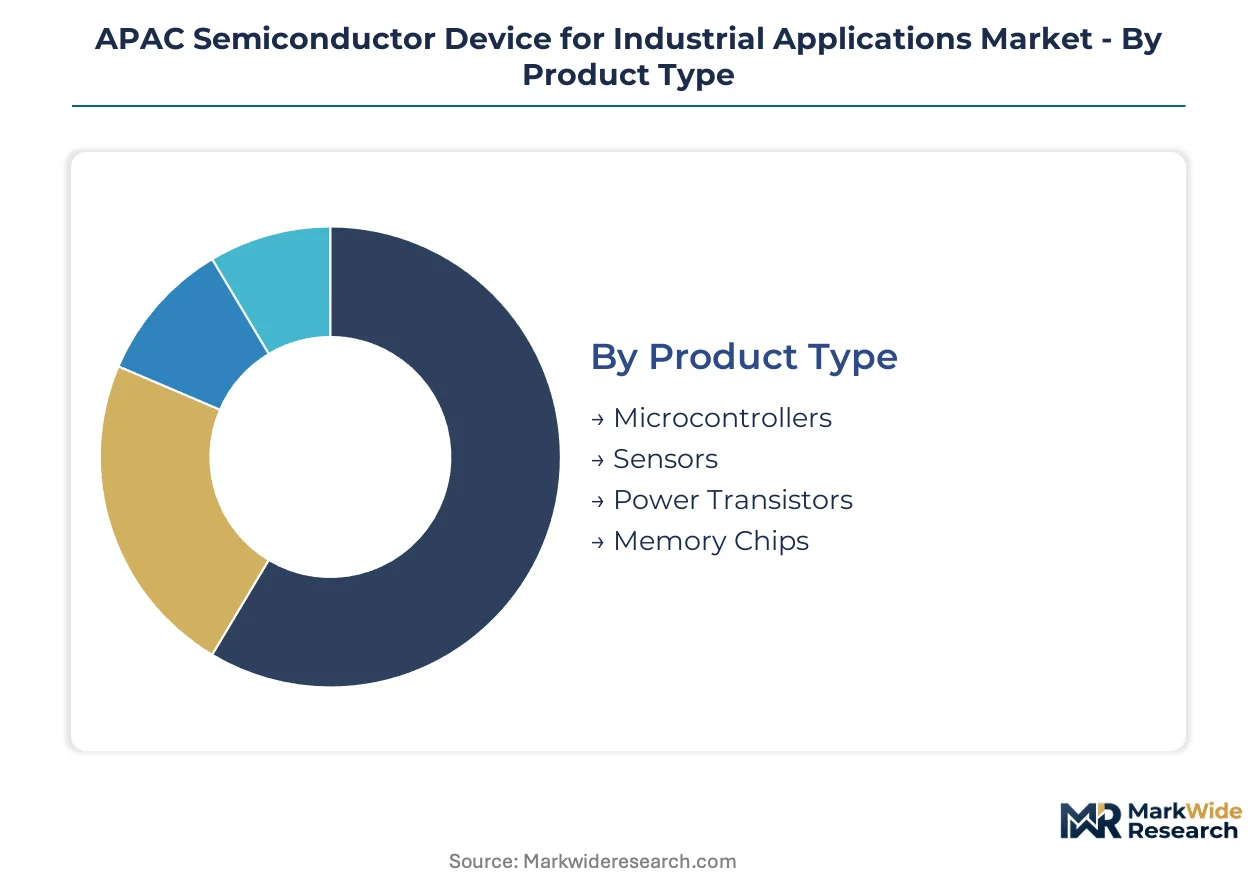
Industrial semiconductor procurement in APAC follows distinct technical and economic logics across product architectures, signal processing methods, and deployment contexts. Segmentation reveals where substitution pressures from wide-bandgap materials and edge AI are compressing legacy categories, and where analog durability sustains pricing power.
Product Type:
Power transistors face the most acute substitution threat as silicon carbide and gallium nitride devices displace silicon superjunction MOSFETs in motor drive applications above 75kW.
- Microcontrollers:Integrated deterministic logic engines with real-time operating system support, clock speeds from 16MHz to 1GHz, and industrial temperature ratings. Demand clusters in South Korean semiconductor fabs deploying edge-computing nodes at machine-tool interfaces; factory automation density mandates are forcing 32-bit architecture upgrades from legacy 8-bit relay replacements.
- Sensors:Vibration, thermal, and current-sensing elements with sub-microsecond latency for closed-loop control. Japanese automotive stamping plants in Toyota City and Yokohama are proliferating predictive maintenance arrays; sensor fusion algorithms for bearing-failure prediction are accelerating mixed-signal ADC integration.
- Power Transistors:Silicon, silicon carbide, and gallium nitride switching devices rated from 600V to 1700V for motor drives and inverters.
- Memory Chips:Non-volatile storage for firmware and data logging in programmable logic controllers and human-machine interfaces.
Microcontrollers retain volume leadership; sensors hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium mixed-signal integration from commodity digital standard cells, with analog commanding 40-60% gross margins in precision control applications.
- Mixed-Signal:Precision ADC and DAC architectures bridging sensor front-ends with digital processing cores. South Korean inverter manufacturers are accelerating integrated isolated power module qualification to compress MIIT GB/T 18488 recertification timelines; gate driver isolation redesigns for electromagnetic compatibility above 150kHz are forcing architectural consolidation.
- Analog:Operational amplifiers, voltage references, and linear regulators for signal conditioning and power management. Tokyo and Seoul engineering centers concentrate scarce precision analog design expertise; succession planning gaps are delaying next-generation successive-approximation ADC releases.
- Digital:Standard-cell logic and programmable gate arrays for deterministic control execution.
- RF:Wireless connectivity modules for industrial IoT backhaul and over-the-air firmware updates.
Mixed-signal captures the highest margin tier; digital provides the volume foundation for foundry economies.
Application:
Application concentration tracks manufacturing FDI flows, with automation systems and robotics absorbing two-thirds of regional microcontroller and power discrete procurement.
- Automation Systems:Programmable logic controllers, distributed I/O modules, and motion controllers for discrete manufacturing. China's MIIT dual carbon mandates are compressing supplier margins while accelerating analog-to-digital transitions in motor control systems; GB standards compliance now gates market access for motor drive inverters above 75kW.
- Robotics:Servo amplifiers, joint motor controllers, and safety-rated processing units for collaborative and industrial arms. South Korean semiconductor manufacturing clusters are deploying real-time deterministic logic execution at machine-tool interfaces; precision assembly lines are displacing relay-based architectures.
- Energy Management:Power factor correction, grid-tied inverters, and battery management systems.
- Control Systems:Process controllers and safety instrumented systems for continuous manufacturing.
Automation systems dominate procurement volume; robotics is climbing the fastest on precision motor control density.
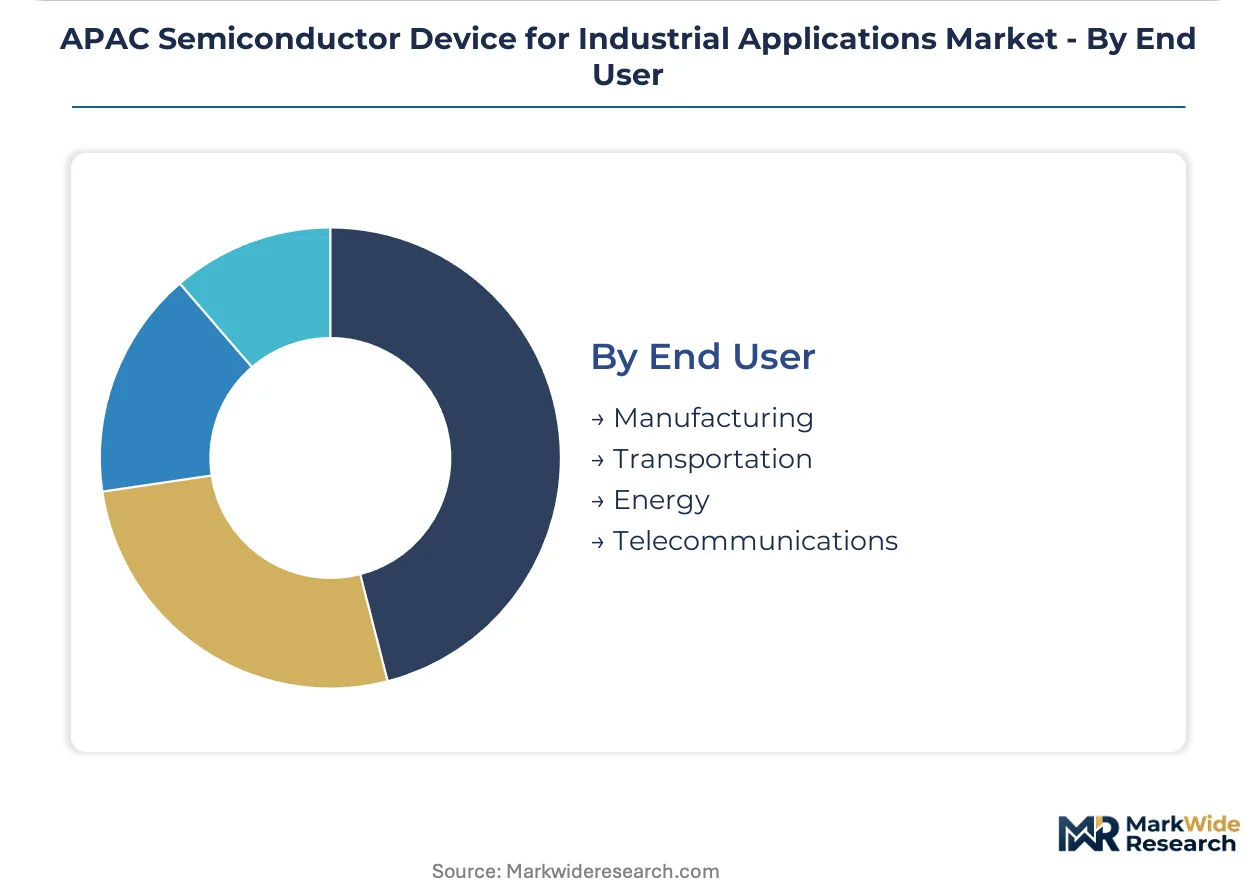
End User:
Customer type segmentation separates heavy-industry procurement with 15-year supply continuity requirements from electronics manufacturing with rapid technology refresh cycles.
- Manufacturing:Automotive stamping, electronics assembly, and process industries. Japanese machine tool builders in Nagoya and Osaka are adopting 650V GaN devices for spindle drives below 5kW; package thermal resistance advantages are enabling air-cooled designs previously requiring liquid cooling infrastructure.
- Energy:Renewable generation, grid infrastructure, and industrial electrification. China's MEE energy-efficiency mandates are forcing industrial equipment OEMs to source wide-bandgap power transistors; dual carbon goals are tightening compliance thresholds for factory equipment.
- Transportation:Railway signaling, electric vehicle charging, and port automation.
- Telecommunications:Base station power supplies and data center cooling controls.
Manufacturing anchors demand volume; energy is gaining share fastest on electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's pricing power in industrial semiconductors exceeds Vietnam's by roughly 40% on comparable microcontroller specifications, reflecting divergent ecosystem maturity and certification burdens across East Asian manufacturing corridors.
China
MIIT's dual carbon mandates are forcing industrial equipment OEMs to source wide-bandgap power transistors for motor drives above 75kW. GB standards compliance now gates market access for variable frequency inverters. Yangtze River Delta clusters in Suzhou and Wuxi are absorbing foundry capacity for automotive-qualified MCUs.
Japan
Predictive maintenance architectures are proliferating in automotive stamping plants across Toyota City and Yokohama. METI enforces JIS standards for industrial semiconductor reliability that extend qualification timelines. Nagoya machine tool builders are adopting 650V GaN devices for spindle drives below 5kW.
South Korea
Semiconductor manufacturing clusters are deploying edge-computing nodes at machine-tool interfaces with real-time deterministic logic execution. MFDS intersects with semiconductor quality frameworks through broader industrial safety mandates. Samsung and SK Hynix captive demand in Pyeongtaek and Icheon is tightening foundry allocation for external MCU suppliers.
Vietnam
Industrial zones in Bac Ninh and Hai Phong are attracting semiconductor packaging investment to bypass ASEAN tariff escalations on finished goods. Localized module assembly is compressing logistics costs for power discrete shipments. Foreign direct investment from South Korean conglomerates is accelerating cleanroom construction in northern provinces.
India
Production-linked incentives for electronic components are reducing effective tax rates for greenfield fab investments. Industrial power discrete packaging is qualifying under revised PLI scheme eligibility criteria. Karnataka and Tamil Nadu are emerging as preferred locations for assembly and test operations serving domestic automation OEMs.
APAC Semiconductor Device for Industrial Applications Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the APAC industrial semiconductor landscape. The market structures around a consolidated tier of diversified analog and mixed-signal suppliers and a fragmented tier of specialized power discrete vendors. Three archetypes dominate: GPU-centric AI acceleration platforms, precision analog specialists with deep industrial temperature-grade portfolios, and wide-bandgap power device pioneers. Competitive moves concentrate on foundry partnerships for advanced node access and die-bank agreements that secure multi-year supply commitments.
Among US-based diversified suppliers, Nvidia Corporation, Intel Corporation, and Texas Instruments Inc. occupy distinct positioning vectors. Nvidia exemplifies the AI-centric acceleration archetype through its CUDA ecosystem dominance in high-performance industrial computing workloads. Intel represents manufacturing scale commitment through regional foundry investments. Texas Instruments anchors the precision analog tier with purpose-built portfolios for harsh industrial environments spanning negative forty to one hundred twenty-five degrees Celsius operating ranges.
| Leading Market Players |
|---|
| Nvidia Corporation |
| Intel Corporation |
| Qualcomm Incorporated |
| STMicroelectronics NV |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Texas Instruments Inc. |
| ON Semiconductor Corporation |
| ROHM Semiconductor |
| Others |
Pricing and Supply Chain Analysis
26-30 week lead times for silicon carbide power modules compress supplier pricing power while amplifying foundry allocation leverage across East Asian manufacturing corridors. This inventory pressure concentrates cost pass-through capacity among integrated device manufacturers with captive wafer supply.
Pricing Analysis
Configured-to-order pricing for JIS-certified industrial MCUs commands 35-45% premiums over standard-grade catalog parts. Contract-based long-term offtake dominates procurement above 100A power discrete ratings, with volume scale and GB standards certification tier as primary price differentiation drivers. Cost compression in wide-bandgap power transistors is intensifying because automotive traction inverters compete for 150mm SiC wafer supply. Contract manufacturing services exhibit highest price sensitivity; precision analog specialists with temperature-grade portfolios maintain lowest.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for sub-7nm logic and advanced memory, while China concentrates backend packaging and test capacity. Raw material flows draw from Japanese silicon carbide substrate suppliers, German epitaxial equipment, and Malaysian leadframe providers. Single-source vulnerability concentrates in 150mm SiC wafer supply where automotive and industrial demand collide. Distribution runs through direct procurement contracts displacing tiered networks, with South Korean automation integrators negotiating multi-year die-bank agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision analog design expertise has concentrated among senior engineers in Tokyo and Seoul, creating succession planning gaps that delay next-generation ADC architectures and constrain supply expansion.
For Market Incumbents: Fortify gate driver isolation architectures against MIIT GB/T 18488 electromagnetic compatibility mandates above 150kHz. Secure captive supply of 150mm SiC substrates through backward integration into Japanese or Korean wafer sources. Defensive consolidation should prioritize mixed-signal talent acquisition in Nagoya and Osaka engineering centers. For New Entrants and Emerging Players: Anchor in Vietnam's Bac Ninh and Hai Phong industrial zones where ASEAN tariff escalations on finished goods create localization arbitrage. Target industrial power discrete packaging qualifying under India's revised PLI scheme eligibility criteria. Go-to-market leverage rests on firmware-enabled feature licensing for digital twin integration platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive semiconductor divisions lacking scale efficiency. Long-term viability over the next decade hinges on wide-bandgap power device qualification velocity and foundry partnership depth. Watch for inflection when integrated isolated power module adoption accelerates among South Korean inverter manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Captive 150mm wafer supply secures allocation priority against automotive demand surges. |
| Integrated Isolated Power Module Launch | South Korean inverter manufacturers accelerate qualification to compress MIIT recertification timelines. |
| Mixed-Signal Design Center Expansion | Tokyo and Seoul engineering concentration demands succession planning for ADC architecture pipelines. |
| Direct Procurement Contract Negotiation | Multi-year die-bank agreements with South Korean automation integrators displace spot-market purchasing. |
| Vietnam Packaging Localization | Bac Ninh cleanroom construction bypasses ASEAN tariff escalations on finished industrial modules. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the APAC industrial semiconductor ecosystem, including automation system procurement managers, power electronics design engineers, foundry planning officers, and regulatory compliance specialists at MIIT and METI. Secondary validation drew from customs trade databases, SEC semiconductor supplier filings, JIS and GB standards documentation, and foundry capacity announcements. Bottom-up segment sizing triangulated against top-down manufacturing FDI flow analysis.
Across the analysis window, forecasts model product type segmentation by microcontroller architecture, power transistor material system, and sensor fusion integration level; technology tier by mixed-signal, analog, digital, and RF capability; and application concentration across automation systems, robotics, energy management, and control systems. CAGRs derive from regression against industrial capital expenditure cycles and semiconductor content-per-system trajectories. Key inputs include MIIT dual carbon mandate compliance timelines and JIS reliability qualification duration estimates.
Underlying assumptions cover continued 150mm SiC wafer supply tightness and stable ASEAN tariff structures, with deviation risk concentrated in automotive demand spikes diverting foundry allocation. Recalibration cycles align with material shifts in MIIT energy-efficiency mandate revisions and South Korean semiconductor cluster expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Automotive Grade Emmc Market