
 India Milk Protein Market | 2026-2036
India Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Milk Protein Market Outlook
Fitness centers and direct-to-consumer sports nutrition buyers is collapsing the historical dominance of institutional food manufacturers as the primary volume purchasers. GCMMF (Amul) leverages its cooperative procurement network to anchor raw milk supply security across western India. Danone India competes through specialized pediatric and active nutrition portfolios. Britannia Industries extends its bakery ingredient relationships into protein-enriched product lines.
India milk protein encompasses casein, whey derivatives, and blended concentrates extracted via ultrafiltration, ion exchange, and spray-drying to achieve protein contents ranging from 34% to over 90% by dry weight. These ingredients serve as functional emulsifiers, gelling agents, and complete amino acid sources across food and clinical nutrition systems. Whey protein isolate commands premium positioning due to superior leucine density and minimal lactose residue. Casein retains structural dominance in infant formula and medical nutrition where slow-release nitrogen kinetics matter. Milk protein blends occupy mid-tier formulation slots in bakery and sports nutrition.
FSSAI governs protein content claims and additive thresholds for dairy-derived ingredients sold in India. BIS standards specify microbiological limits and heavy metal ceilings for edible caseinates and whey powders. The PLI scheme for food processing incentivizes capital investment in precision separation and cold-chain infrastructure. Stakeholders must monitor how FSSAI's evolving protein fortification guidelines reshape product registration pathways and procurement specifications.
Market Dynamics
FSSAI's tightened protein labeling norms are forcing reformulation cycles across nutraceutical portfolios while cooperative dairy networks in Maharashtra and Gujarat consolidate raw milk procurement leverage.
Growth Catalysts
- PLI scheme incentives:Capital subsidies for precision separation equipment are accelerating cold-chain infrastructure buildout in organized dairy clusters. Food processors are expanding ultrafiltration capacity to capture higher-value whey fractions.
- Sports nutrition demand:Fitness centers and direct-to-consumer buyers are collapsing the historical dominance of institutional food manufacturers as primary volume purchasers. Whey protein isolate procurement is intensifying for leucine-dense formulations.
- Medical nutrition applications:Casein's slow-release nitrogen kinetics are anchoring infant formula and clinical nutrition formulations. Pediatric and geriatric segments are driving specialized protein blend development.
Market Restraints
- Raw milk supply volatility:Monsoon-dependent fodder cycles create input cost swings that compress margin predictability for spray-drying operations. Cooperative procurement networks partially buffer this exposure.
- Western India supply concentration:Organized processing clusters in Maharashtra and Gujarat control critical ultrafiltration infrastructure. Eastern and northeastern states lack comparable separation capacity.
- Regulatory compliance friction:FSSAI's evolving fortification guidelines create product registration uncertainty. BIS microbiological testing timelines extend go-to-market cycles for new caseinate variants.
Strategic Opportunities
- Eastern India penetration:Odisha and West Bengal present underdeveloped procurement infrastructure for whey concentrate distribution. Cold-chain gaps currently limit sports nutrition ingredient access.
- Plant-dairy hybrid formulations:Blended protein systems combining casein with pea or rice isolates are opening clean-label positioning in bakery applications. Formulators are targeting flexitarian consumer segments.
- Direct-to-clinic channels:Medical nutrition buyers are bypassing traditional distributor tiers for specialized casein hydrolysate procurement. Hospital pharmacy networks in tier-2 cities are piloting this model.
Industry Challenges
- Skilled technician scarcity:Ion exchange chromatography and membrane filtration operations require specialized dairy engineering expertise that training institutes have not scaled to match plant expansion.
- Capex intensity for 90%+ isolates:Achieving whey protein isolate purity thresholds demands multi-stage diafiltration systems that strain mid-tier processor balance sheets.
- FSSAI registration timelines:Protein content claim substantiation requires extended analytical documentation that delays product launches for reformulated concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Milk Protein Market |
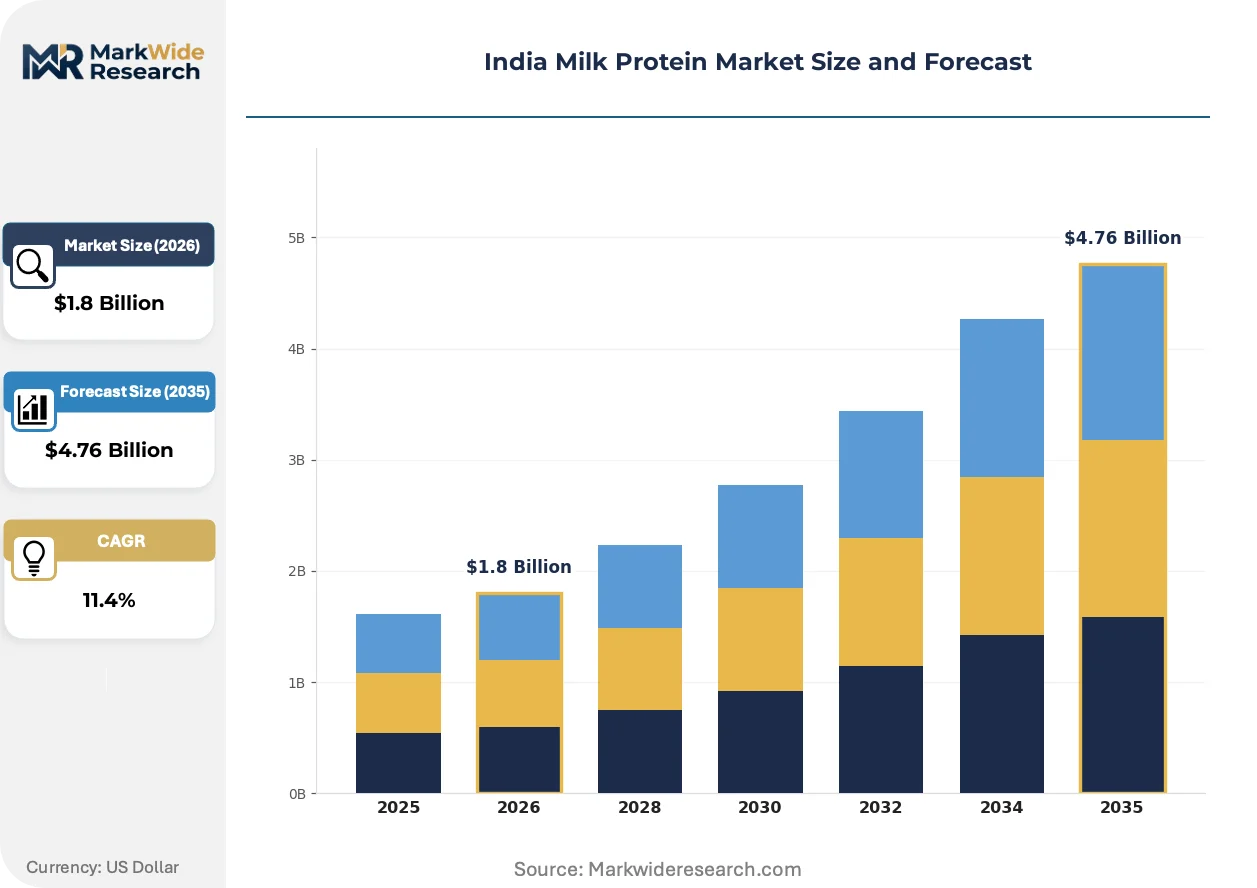
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Whey Protein Concentrate, Whey Protein Isolate, Milk Protein Blend Application: Dairy Products, Nutritional Supplements, Bakery Products, Infant Formula End User: Food Manufacturers, Nutraceutical Companies, Hospitals, Fitness Centers Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Wholesale |
| Companies Covered | Glanbia plc, Danone India, GCMMF (Amul), Britannia Industries, Royal FrieslandCampina N.V., Fonterra Co-operative Group Limited, Parag Milk Foods, Lactalis Ingredients, Nestlé S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Milk Protein Market Strategic Shifts
Membrane filtration advances and shifting buyer procurement patterns are restructuring competitive positioning across ingredient tiers, while regulatory tightening on label claims forces transparency investments.
Microfiltration combined with ceramic membrane cascades is displacing traditional centrifugal separation in premium whey fractionation. Sports nutrition formulators are specifying these ceramic systems for superior lactose reduction and leucine retention. The technology is compressing price premiums between isolate and concentrate grades as yield efficiency improves.
FSSAI's protein fortification guidelines are mandating third-party analytical verification for all dairy-derived supplement claims. Nutraceutical registrants must now submit batch-level amino acid profiling documentation. Pediatric nutrition portfolios face the steepest compliance burden due to stringent infant formula safety thresholds.
Direct procurement from dairy cooperatives is collapsing the traditional multi-tier distributor model for bulk whey concentrate buyers. Bakery and confectionery manufacturers in Gujarat are negotiating supply agreements directly with Amul-affiliated chilling centers. This channel compression is most visible in Ahmedabad and Surat where ingredient volumes justify dedicated logistics contracts.
India Milk Protein Market Segmentation
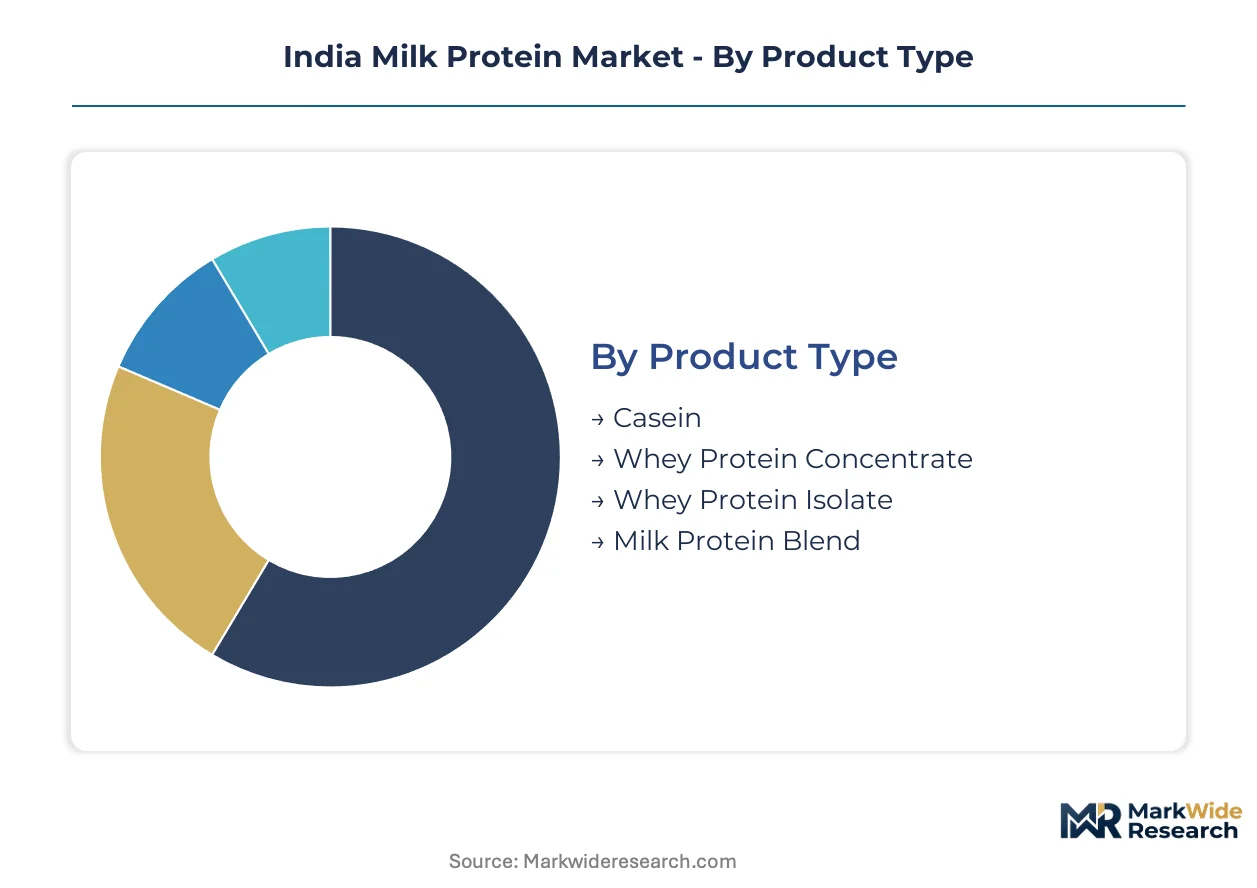
India milk protein procurement flows through distinct channel architectures that reshape how casein and whey derivatives reach end-formulators. Understanding these pathway structures clarifies where margin capture concentrates and where new entrants face entrenched distributor relationships.
Product Type:
Channel access varies sharply by protein purity tier, with ultrafiltration-intensive isolates commanding dedicated cold-chain logistics distinct from commodity-grade concentrates.
- Casein:Micellar precipitation yields protein fractions exceeding 90% purity with slow-digesting nitrogen release kinetics. Demand concentrates in Gujarat and Maharashtra infant formula plants where FSSAI-mandated safety documentation requirements favor established dairy cooperative supply lines.
- Whey Protein Isolate:Multi-stage diafiltration achieves lactose content below 1% with leucine density optimized for sports nutrition absorption windows. Direct procurement from Amul-affiliated chilling centers is collapsing traditional distributor tiers for Ahmedabad and Surat fitness center buyers.
- Whey Protein Concentrate:Lower purity grades serve bakery emulsification with broader lactose tolerance. Procurement runs through wholesale dairy ingredient distributors serving mid-tier confectionery manufacturers.
- Milk Protein Blend:Casein-whey combinations target mid-market sports nutrition with cost-optimized amino acid profiles. Hypermarket private-label lines in Mumbai and Pune represent the primary volume outlet.
Casein dominates installed base through infant formula anchoring. Whey protein isolate is where expansion concentrates as sports nutrition bypasses institutional buyers.
Application:
Cost tier stratification separates premium clinical formulations from commodity food processing applications.
- Dairy Products:Standardized milk protein fortification in yogurt and cheese analogs. Gujarat dairy cooperatives integrate backward into captive caseinate production for processed cheese lines.
- Nutritional Supplements:Leucine-optimized isolates for post-workout recovery formulations. Direct-to-consumer ecommerce channels in Bangalore and Delhi NCR are gaining share fastest from pharmacy retail.
- Bakery Products:Emulsification-grade concentrates for protein-enriched bread and biscuit doughs. Britannia Industries leverages existing ingredient relationships for portfolio extension.
- Infant Formula:Slow-release casein hydrolysates for pediatric medical nutrition. CDSCO registration timelines create compliance moats around specialized hospital pharmacy procurement.
Infant formula commands the steepest margin tier. Nutritional supplements represent the volume expansion frontier.
End User:
Customer-type concentration is shifting from institutional procurement toward fragmented fitness and clinical channels.
- Food Manufacturers:Bulk concentrate buyers for processed dairy and bakery integration. Danone India and GCMMF negotiate long-term supply security through cooperative procurement networks.
- Nutraceutical Companies:Isolates and specialized hydrolysates for sports and active nutrition portfolios. Reformulation cycles accelerate under FSSAI's tightened protein labeling norms.
- Hospitals:Medical nutrition procurement of casein hydrolysates for enteral feeding. Tier-2 city pharmacy networks pilot direct-to-clinic distribution bypassing traditional tiers.
- Fitness Centers:Direct bulk purchasing of leucine-dense isolates for member supplement resale. Maharashtra gym chains in Mumbai and Pune drive spot-market whey procurement.
Food manufacturers retain volume dominance. Fitness centers are climbing the fastest as channel intermediaries collapse.
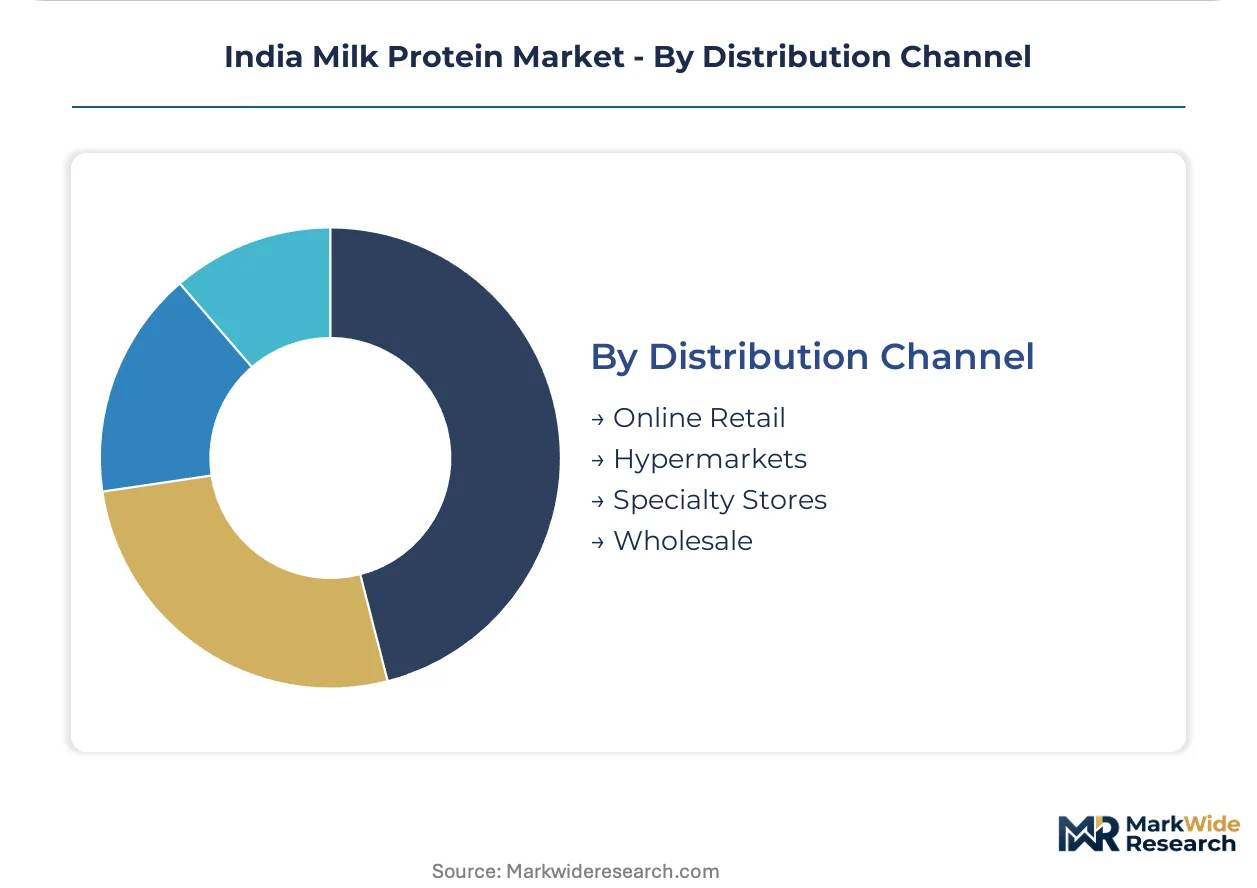
Distribution Channel:
Geography determines viable channel economics, with cold-chain infrastructure gaps constraining eastern India access.
- Online Retail:Direct-to-consumer sports nutrition isolate sales with batch-level amino acid documentation. Third-party analytical verification requirements under FSSAI fortification guidelines raise compliance costs for marketplace sellers.
- Hypermarkets:Private-label milk protein blends and concentrates for mass-market bakery and dairy fortification. Ahmedabad and Surat locations justify dedicated logistics contracts from cooperative chilling centers.
- Specialty Stores:Premium isolate and hydrolysate SKUs for discerning sports nutrition buyers. Bangalore and Delhi NCR clusters support specialized retail footprint.
- Wholesale:Bulk concentrate distribution to mid-tier food processors and regional bakery chains. Eastern India penetration remains limited by ultrafiltration infrastructure concentration in western states.
Wholesale dominates current volume throughput. Online retail is where channel investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultrafiltration infrastructure clusters in western India control the bulk of whey fractionation capacity, while eastern states remain dependent on long-haul logistics from Gujarat and Maharashtra cooperatives.
Maharashtra
Mumbai and Pune fitness center chains drive spot-market procurement of leucine-dense whey isolates for member resale. FSSAI's batch-level amino acid verification requirements favor established chilling center networks with in-house testing laboratories. Organized dairy clusters around Nashik and Kolhapur are expanding ceramic membrane capacity for premium sports nutrition fractions.
Gujarat
Ahmedabad and Surat bakery manufacturers negotiate direct supply agreements with Amul-affiliated cooperatives, bypassing traditional wholesale tiers. The PLI scheme for food processing subsidizes precision separation equipment investments in Anand and Banaskantha districts. Infant formula plants in Vadodara anchor casein hydrolysate demand for pediatric medical nutrition.
Karnataka
Bangalore's direct-to-consumer ecommerce channels for sports nutrition isolates are gaining share fastest from pharmacy retail. CDSCO registration timelines for specialized clinical nutrition products create compliance moats around hospital procurement networks. Tier-2 city pharmacy pilots in Mysore and Mangalore test direct-to-clinic distribution models.
West Bengal
Kolkata's underdeveloped cold-chain infrastructure limits sports nutrition ingredient access compared to western states. BIS microbiological testing requirements extend go-to-market cycles for reformulated caseinate variants entering from out-of-state processors. Eastern India penetration gaps present strategic openings for whey concentrate distribution networks.
Haryana
Delhi-NCR nutraceutical companies source blended protein systems for flexitarian positioning in bakery applications. DGFT import regulations on dairy-derived ingredients shape procurement strategies for processors lacking captive ultrafiltration capacity. Bahadurgarh and Sonipat industrial zones host contract manufacturing for protein-enriched confectionery lines.
India Milk Protein Market Competitive Environment
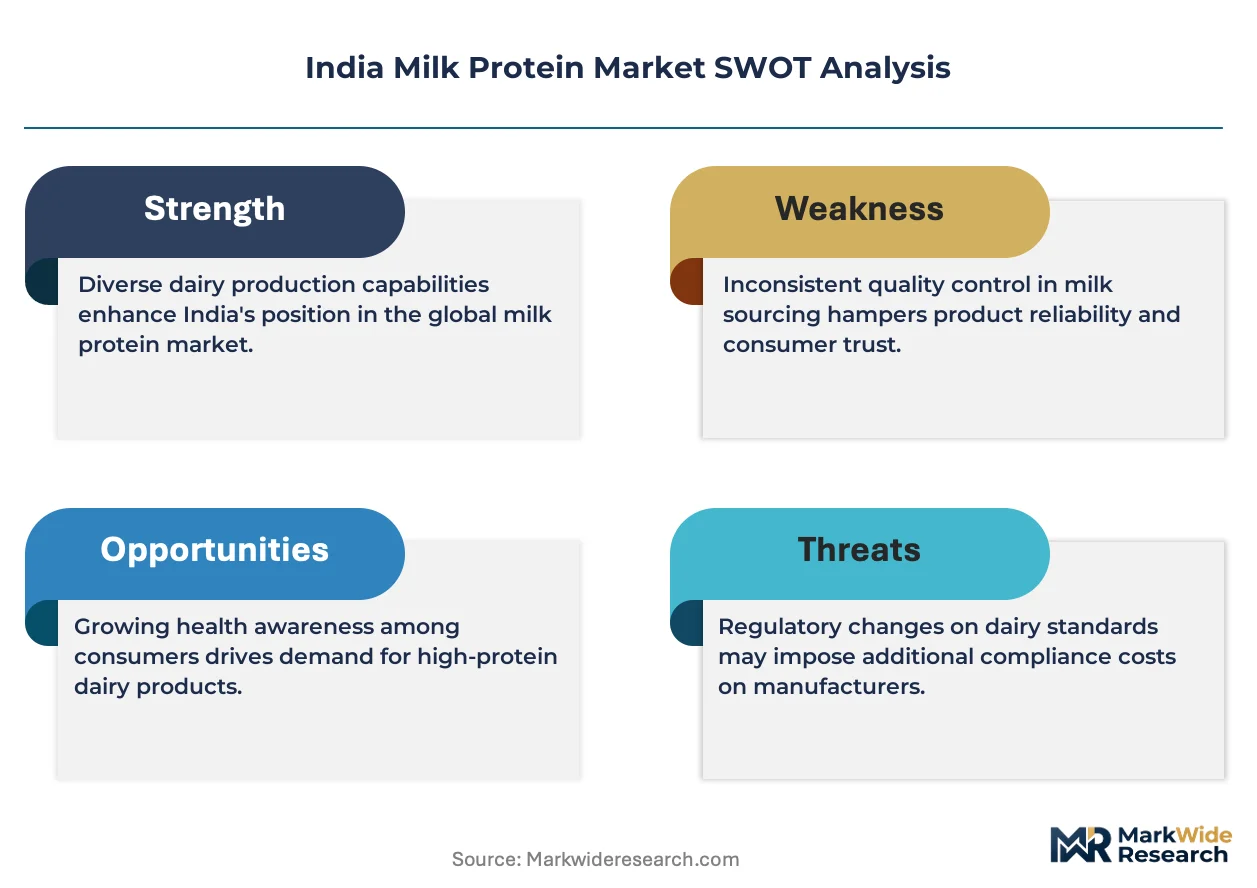
Concentration sits with cooperative dairy networks and multinational nutrition portfolios that anchor raw milk security and specialized formulation expertise. The competitive terrain splits between western India procurement leverage held by dairy cooperatives and the pediatric-active nutrition specialization of global food majors. Three archetypes dominate: cooperative-backed domestic processors with captive milk supply, multinational nutrition specialists with clinical registration depth, and diversified food conglomerates extending ingredient relationships into protein-enriched lines. Capacity expansion in ceramic membrane systems and direct cooperative procurement contracts constitute the primary competitive moves reshaping channel access.
Among the cooperative-backed tier, GCMMF (Amul) exemplifies raw milk security through its western India chilling center network. Danone India occupies a position within the multinational nutrition specialist archetype, while Britannia Industries represents the diversified food conglomerate path extending bakery ingredient relationships. Glanbia plc and Fonterra Co-operative Group Limited sit within the global dairy ingredients tier supplying isolate and concentrate grades to Indian formulators.
| Leading Market Players |
|---|
| Glanbia plc |
| Danone India |
| GCMMF (Amul) |
| Britannia Industries |
| Royal FrieslandCampina N.V. |
| Fonterra Co-operative Group Limited |
| Parag Milk Foods |
| Lactalis Ingredients |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Gujarat dairy cooperatives and Ahmedabad bakery manufacturers lock in both raw whey concentrate supply access and six-month price visibility against monsoon-driven fodder volatility. These contracts compress spot-market exposure for buyers while anchoring processor margins through guaranteed volume commitments.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade casein hydrolysates from commodity whey concentrates and sports nutrition isolates. Price differentiation hinges on FSSAI certification tiers and ceramic membrane filtration investment levels. Pricing pressure stems from eastern India's cold-chain infrastructure gaps forcing long-haul logistics premiums. Institutional food manufacturers exhibit highest price sensitivity, while pediatric nutrition buyers tolerate premium positioning for CDSCO-registered formulations.
Supply Chain Analysis
Ultrafiltration infrastructure chokepoints in Maharashtra and Gujarat control India's whey fractionation capacity, leaving West Bengal and Odisha dependent on western state output. Raw milk procurement draws from monsoon-dependent fodder cycles and cooperative chilling center networks. Single-source vulnerability concentrates in Amul-affiliated supply lines dominating western India. Distribution runs through direct cooperative contracts for bulk buyers and wholesale dairy ingredient tiers for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled technician scarcity for ion exchange chromatography and membrane filtration operations constitutes the binding constraint on capacity expansion, with training institute output lagging plant investment cycles by a structural margin.
For Market Incumbents: Compound raw milk security through cooperative procurement network densification in Nashik and Kolhapur, while accelerating ceramic membrane capacity additions to defend against global dairy ingredient suppliers targeting sports nutrition isolate share. FSSAI's evolving fortification guidelines threaten registration moats—prioritize in-house analytical laboratories for batch-level amino acid verification. For New Entrants and Emerging Players: Anchor in eastern India's underdeveloped whey concentrate distribution infrastructure, specifically Odisha and West Bengal cold-chain gaps that limit sports nutrition ingredient access. Target tier-2 city hospital pharmacy networks piloting direct-to-clinic casein hydrolysate procurement, bypassing traditional wholesale tiers through specialized medical nutrition positioning. For Investors and Strategic Acquirers: Dairy cooperative-affiliated membrane filtration specialists with captive ultrafiltration capacity represent the most defensible acquisition profile against commodity price volatility. Long-term viability rests on PLI scheme subsidy capture and FSSAI registration depth. Watch ceramic membrane yield efficiency improvements as the signal compressing isolate-concentrate price premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Improves whey isolate yield efficiency while reducing lactose residue for FSSAI compliance. |
| Direct Cooperative Procurement Contracts | Collapses distributor tiers for Ahmedabad and Surat bakery manufacturers seeking supply security. |
| In-House Analytical Laboratory Investment | Accelerates batch-level amino acid documentation for FSSAI protein fortification guidelines. |
| Eastern India Cold-Chain Infrastructure Buildout | Unlocks Odisha and West Bengal sports nutrition ingredient access currently constrained by logistics. |
| Pediatric Nutrition CDSCO Registration | Creates compliance moats around specialized casein hydrolysate hospital pharmacy procurement. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with dairy cooperative procurement managers, membrane filtration plant engineers, FSSAI regulatory affairs specialists, and sports nutrition formulators; and secondary validation through BIS standards documentation, FSSAI fortification guidelines, PLI scheme disclosures, and cooperative chilling center capacity records. Bottom-up volume triangulation across western India ultrafiltration clusters converged with top-down expenditure estimates from nutritional supplement and infant formula manufacturers.
Across the analysis window, forecasts model product type segmentation by purity tier, application stratification across clinical and commodity nutrition, end-user channel shifts from institutional to fitness center procurement, and distribution architecture evolution. CAGRs derive from installed capacity trajectories, regulatory compliance burden projections, and buyer procurement pattern migration. Forecast inputs incorporate monsoon cycle fodder cost volatility and ceramic membrane technology diffusion curves.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme subsidy availability and stable FSSAI regulatory timelines; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as eastern India infrastructure investment and global dairy ingredient import parity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Ghee Market
Dairy Products
Global Goat Cheese Market
Dairy Products
UHT Milk Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Cheese Color Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Europe Dairy Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Cream Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Middle East Dairy Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Dry Whole Milk Powder Market