
 Europe Milk Protein Market | 2026-2036
Europe Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Milk Protein Market Foresight
Buyer concentration among European sports nutrition and functional food brands is recalibrating procurement volumes across the milk protein value chain. FrieslandCampina Ingredients leverages its Dutch dairy cooperative structure to sustain long-term supply contracts with continental manufacturers. LACTALIS Ingredients anchors its position through backward integration into French and Italian milk collection networks. Glanbia plc competes by specializing in high-purity whey protein isolates for performance nutrition applications.
Europe milk protein comprises casein, whey protein, and milk protein concentrates and isolates extracted through membrane filtration, ion exchange, or precipitation processes, yielding protein contents ranging from 35% to over 90% depending on grade and intended application. These ingredients serve as structural agents, emulsifiers, and nutritional fortifiers across food and supplement manufacturing. Whey protein dominates value generation in sports nutrition and clinical dietary supplements, while casein retains strong positions in processed cheese and sustained-release protein formulations. Milk protein concentrates occupy expanding niches in clean-label bakery and beverage applications where moderate protein enhancement replaces synthetic additives.
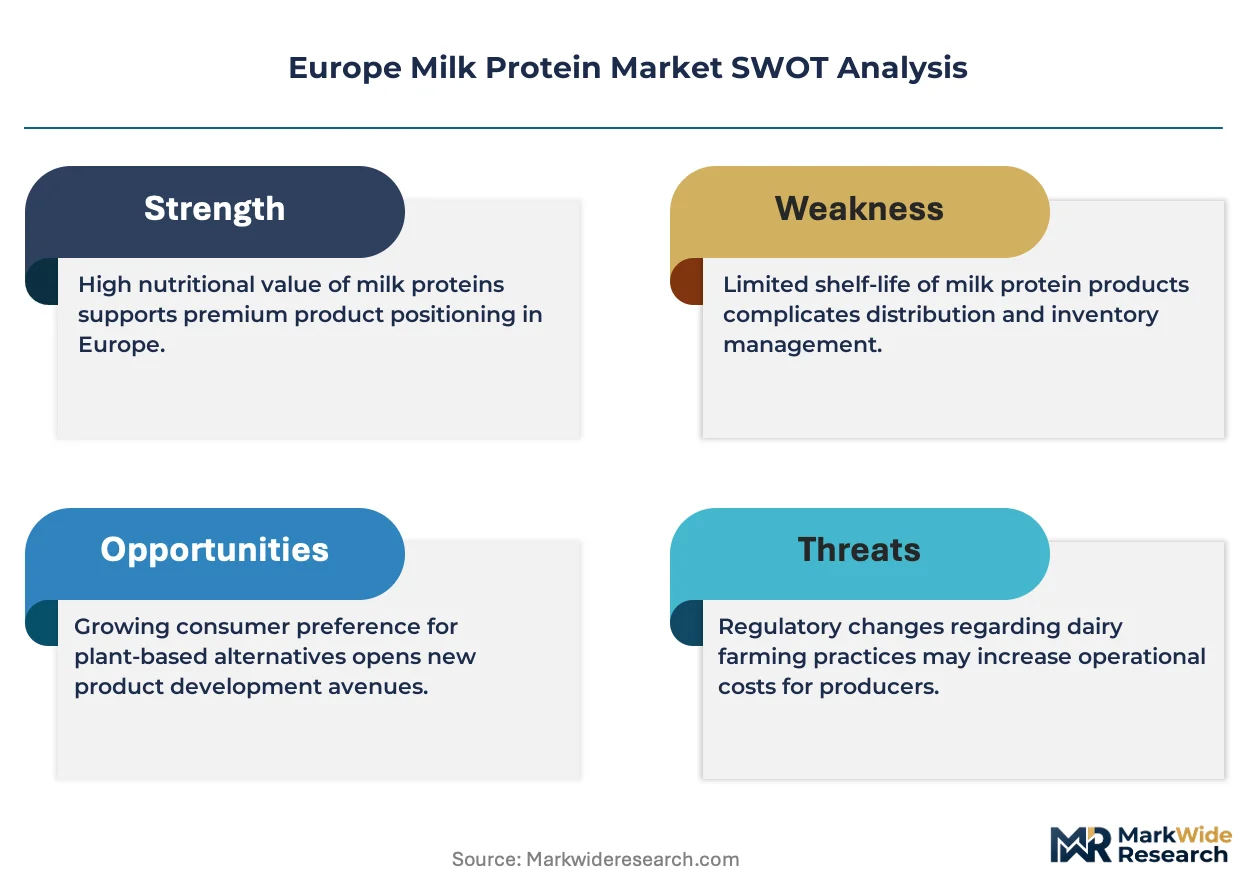
EMA food contact material guidelines, EFSA novel food authorization pathways, and EU Farm to Fork Strategy sustainability disclosure requirements collectively shape product formulation standards and market access conditions for milk protein suppliers across the continent. REACH chemical safety protocols and emerging CSRD corporate sustainability reporting obligations further constrain processing methods and supply chain documentation. Stakeholders must monitor evolving EU protein labeling regulations and carbon footprint accounting standards to anticipate compliance costs and competitive positioning shifts.
Market Dynamics
The EU Farm to Fork Strategy's sustainability disclosure mandates are compressing procurement timelines for dairy processors, forcing simultaneous investment in carbon accounting infrastructure and membrane filtration upgrades across the continent's ingredient manufacturing corridors.
Growth Catalysts
- Clean-label bakery reformulation:Manufacturers across France and the Netherlands are replacing synthetic emulsifiers with milk protein concentrates in bread and pastry applications.
- REACH chemical safety protocols:These regulations are accelerating substitution of petrochemical-derived protein alternatives with dairy-derived functional ingredients in food contact materials.
- Sports nutrition procurement expansion:German and French performance nutrition brands are locking multi-year whey protein supply contracts to secure volume commitments ahead of processing capacity constraints.
Market Restraints
- Feed cost volatility:European dairy farm input expenses for soybean meal and energy fluctuate with Black Sea grain corridor disruptions, compressing processor margins.
- Regional supply concentration:Brittany's dairy cluster and the Dutch cooperative network control disproportionate raw milk flows, creating single-source vulnerability for isolated buyers.
- Plant protein substitution:Pea and fava protein isolates are capturing share in mass-market nutrition bars where taste differentiation is minimal.
Strategic Opportunities
- Eastern European processing expansion:Poland and Romania offer underutilized dairy infrastructure for fractionation capacity serving Central European markets.
- Clinical nutrition applications:Medical food formulators are specifying micellar casein for sarcopenia management in aging populations.
- CSRD corporate sustainability reporting:Early compliance with EU disclosure rules creates differentiation for suppliers offering verified carbon footprint data to institutional buyers.
Industry Challenges
- Specialized membrane engineering talent:The shortage of process engineers skilled in ceramic ultrafiltration system optimization constrains plant expansion timelines.
- EFSA novel food authorization timelines:Extended safety assessment durations for new protein hydrolysate formats delay product commercialization by 18-24 months.
- Legacy ERP integration:Traceability requirements under EU Farm to Fork Strategy force costly upgrades to decade-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Milk Protein Market |
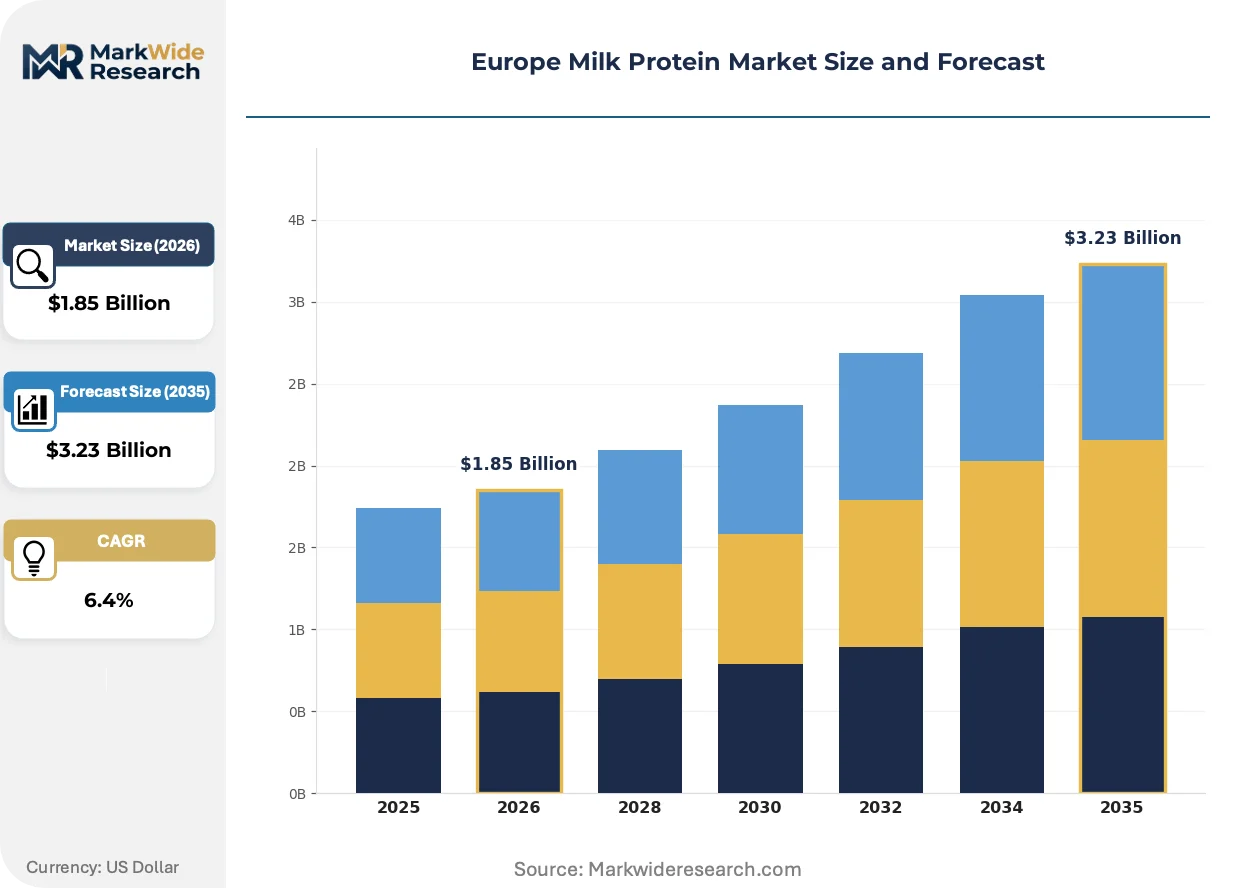
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Protein Concentrate, Milk Protein Isolate End User: Dairy Products, Bakery, Beverages, Dietary Supplements Packaging Type: Bags, Tins, Bottles, Sachets Form: Powder, Liquid, Gel, Granule |
| Companies Covered | Arla Foods Ingredients Group P/S, FrieslandCampina Ingredients, LACTALIS Ingredients, Glanbia plc, Unternehmensgruppe Theo Müller, Kerry Group PLC, wheyco GmbH, Hoogwegt, Lactoprot Deutschland GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Milk Protein Market Shifts & Advancements
Membrane filtration advances and regulatory disclosure mandates are restructuring how milk protein suppliers compete, with technology adoption speed and sustainability verification emerging as the primary axes of differentiation.
Precision fermentation-derived whey proteins are integrating into hybrid ingredient portfolios alongside traditional dairy extraction. Sports nutrition manufacturers in Germany are piloting these materials at 10-15% blend ratios to test consumer acceptance. The technology is integrating sustainability claims into product positioning without fully displacing established supply relationships.
CSRD corporate sustainability reporting obligations are mandating Scope 3 emissions disclosure across dairy value chains. Processors must now document farm-level methane and energy inputs for every protein batch sold to institutional customers. French ingredient manufacturers are most affected, with Brittany-based cooperatives investing in satellite-linked farm monitoring systems to meet 2025 disclosure deadlines.
Direct-to-brand procurement contracts are displacing traditional trader-mediated spot purchasing for whey protein isolates. Large German and Dutch sports nutrition brands are negotiating 3-5 year offtake agreements with specific processing facilities, bypassing commodity brokers. This pattern concentrates most visibly in the Netherlands' ingredient manufacturing corridor, where FrieslandCampina's cooperative structure enables volume commitments unavailable through spot markets.
Europe Milk Protein Market Segmentation
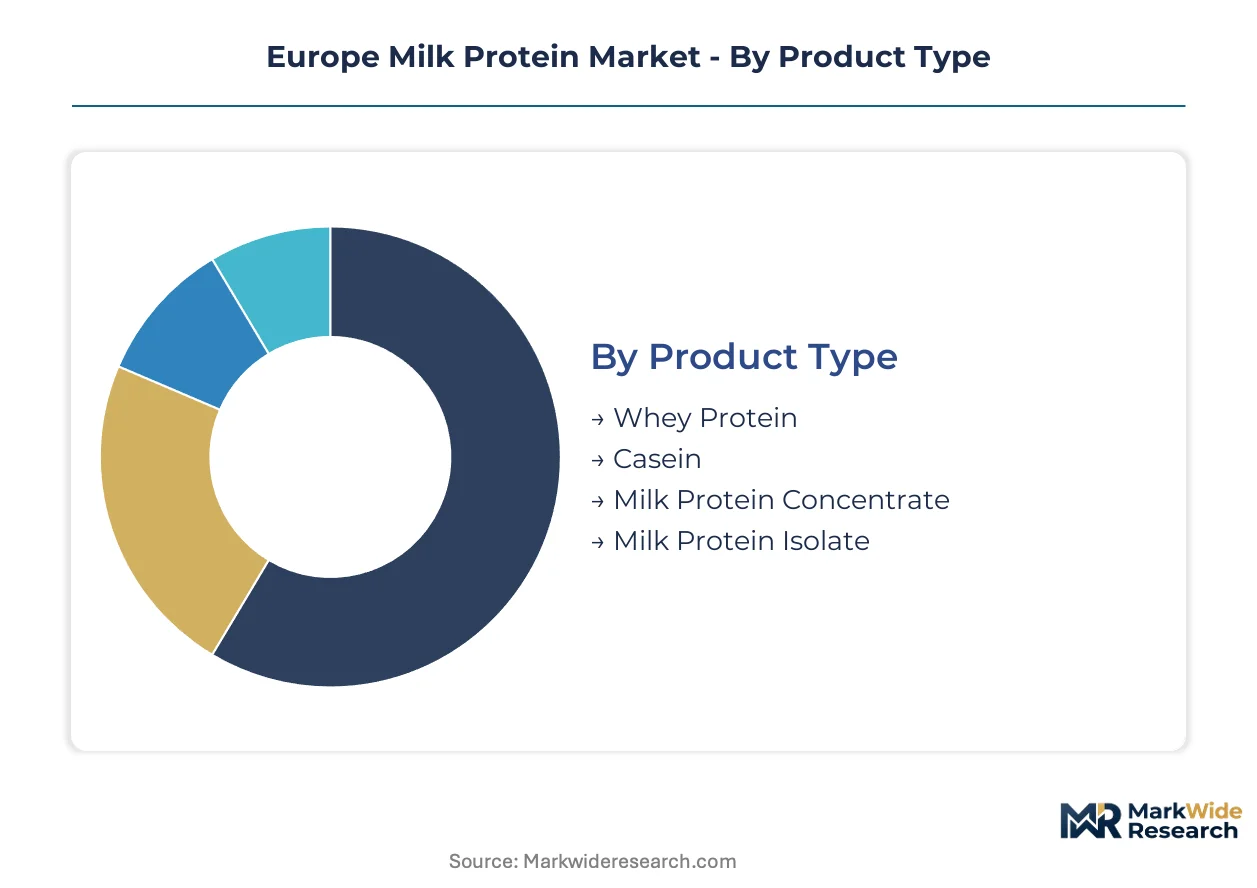
Segmentation in the Europe milk protein market reveals how protein functionality, processing specifications, and end-use requirements determine value capture across the value chain. Manufacturers align fractionation investments with specific application demands rather than pursuing commodity scale alone.
Product Type:
Membrane filtration selectivity and protein denaturation thresholds define the technical boundaries between product categories, with each serving distinct formulation requirements across food and nutrition applications.
- Whey Protein:Rapidly absorbed protein fractions (beta-lactoglobulin, alpha-lactalbumin) extracted through ultrafiltration and diafiltration, typically delivering 80-90% protein content. German sports nutrition brands in Cologne and Munich are locking multi-year supply contracts for whey protein isolates ahead of processing capacity constraints.
- Casein:Slow-digesting phosphoprotein micelles precipitated through acid or rennet treatment, valued for gelation and sustained amino acid release. French medical food formulators in Brittany are specifying micellar casein for sarcopenia management in aging populations.
- Milk Protein Concentrate:Intermediate protein content (35-85%) achieved through less intensive membrane filtration, balancing cost and functionality for clean-label bakery reformulation.
- Milk Protein Isolate:Highest purity grade exceeding 90% protein with minimal lactose and fat, commanding premium positioning in clinical nutrition and infant formula applications.
Whey protein leads on scale; milk protein isolate leads on momentum.
End User:
Application-driven formulation requirements create divergent procurement patterns, with each end-use sector imposing distinct solubility, flavor, and certification demands on suppliers.
- Dietary Supplements:Performance nutrition and clinical dietary applications demanding highest purity grades with batch-level certification. Dutch manufacturers in the ingredient manufacturing corridor are expanding whey protein procurement volumes to serve German and French brand expansion.
- Dairy Products:Processed cheese, yogurt fortification, and dairy-based desserts utilizing casein for texture control and whey for protein standardization.
- Bakery:Clean-label bread and pastry reformulation replacing synthetic emulsifiers with milk protein concentrates for dough conditioning and moisture retention.
- Beverages:Ready-to-drink protein formulations requiring cold-dispersible powders with neutral flavor profiles and extended shelf stability.
Dietary supplements command premium pricing; bakery applications are expanding most quickly.
Packaging Type:
Packaging specifications align with customer scale, shelf-life requirements, and handling infrastructure across industrial, foodservice, and retail channels.
- Bags:Multi-wall paper or polyethylene bulk containers (10-25kg) dominating industrial procurement for manufacturing integration.
- Tins:Metal canisters preserving powder integrity in humid conditions, preferred for premium retail positioning and export stability.
- Bottles:Rigid containers for liquid protein concentrates and ready-to-drink formulations requiring dispensing convenience.
- Sachets:Single-serve flexible pouches capturing foodservice and sampling applications with portion control benefits.
Bags dominate procurement volume; sachets show steepest expansion trajectory in foodservice channels.
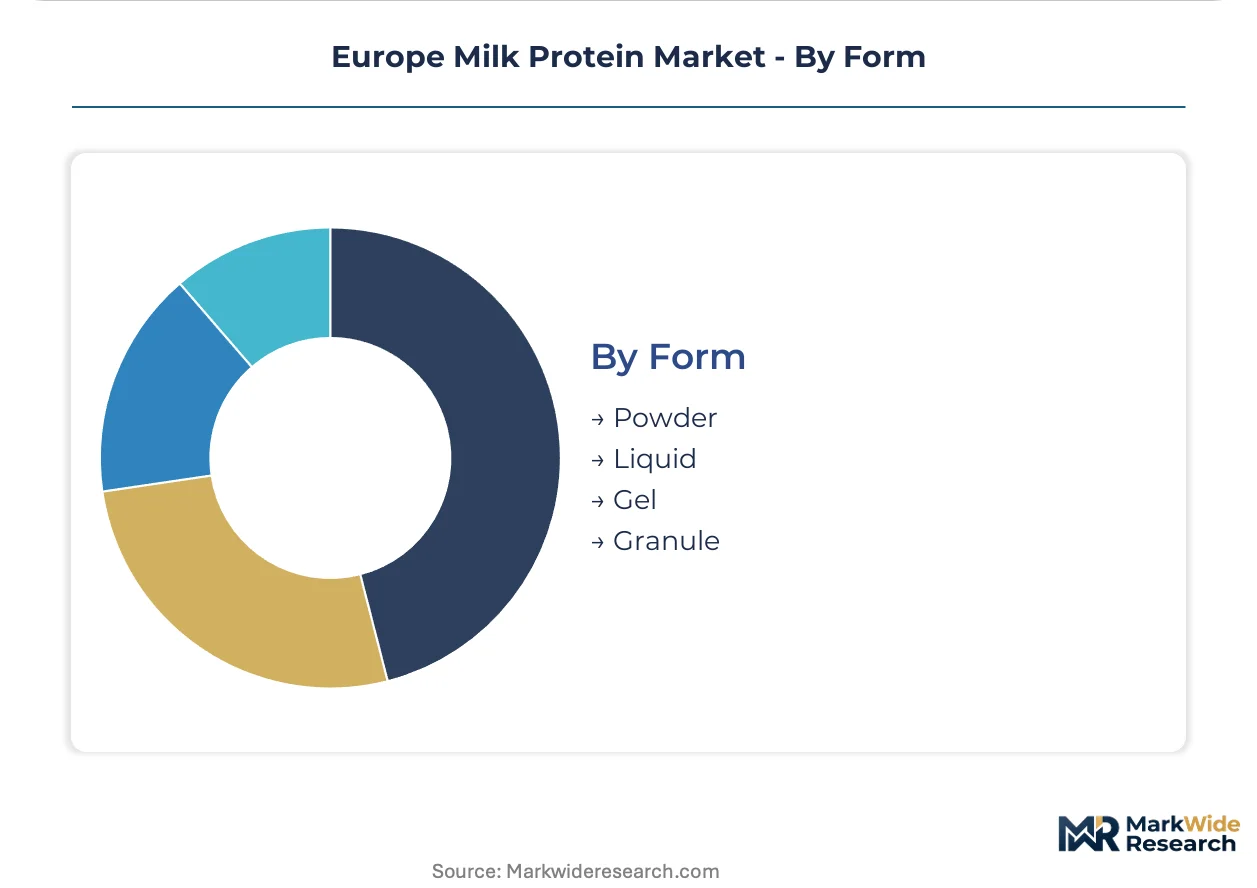
Form:
Physical state determines handling economics, reconstitution behavior, and application flexibility across manufacturing environments.
- Powder:Spray-dried protein with extended shelf stability and lowest logistics cost, standard for bulk manufacturing and consumer repackaging.
- Liquid:Protein concentrates and hydrolysates for immediate processing integration, reducing reconstitution steps in beverage manufacturing.
- Gel:Hydrated protein matrices for specific texture applications in processed cheese and dessert formulations.
- Granule:Agglomerated powders with enhanced flow properties and reduced dusting, improving handling in high-speed packaging lines.
Powder maintains supply dominance; liquid forms are gaining share fastest in integrated beverage operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane filtration engineers and dairy process technologists concentrate in the Netherlands' ingredient corridor and Brittany's dairy cluster, anchoring Europe's protein fractionation capabilities. These talent pools sustain proprietary diafiltration expertise that processors elsewhere struggle to replicate.
Netherlands
Dutch sports nutrition brands in Amsterdam and Utrecht are locking multi-year whey protein supply contracts ahead of processing capacity constraints. EFSA novel food authorization pathways govern hydrolysate approvals for clinical applications. FrieslandCampina's cooperative structure in the northern dairy belt enables volume commitments unavailable through spot markets.
France
Medical food formulators in Brittany specify micellar casein for sarcopenia management in aging populations. EU Farm to Fork Strategy sustainability disclosure mandates compress procurement timelines for processors in the western dairy cluster. LACTALIS Ingredients leverages backward integration into regional milk collection networks to secure raw material flows.
Germany
Cologne and Munich-based performance nutrition brands are expanding whey protein procurement volumes to serve domestic and export demand. REACH chemical safety protocols accelerate substitution of petrochemical-derived alternatives with dairy-derived functional ingredients. Bavarian dairy cooperatives are investing in ceramic ultrafiltration system upgrades to meet clean-label bakery reformulation specifications.
Poland
Central European food manufacturers are sourcing milk protein concentrates for cost-optimized bakery and beverage applications. CSRD corporate sustainability reporting obligations extend disclosure requirements to Polish processing subsidiaries of Western European parents. Underutilized dairy infrastructure in the Masovian and Greater Poland voivodeships offers fractionation capacity expansion opportunities.
Ireland
Infant formula manufacturers in Cork and Limerick specify highest-purity milk protein isolates for nutritional fortification. EMA food contact material guidelines constrain packaging specifications for exported dairy ingredients. Kerry Group PLC leverages regional dairy processing heritage to serve pharmaceutical and clinical nutrition formulators requiring batch-level certification.
Europe Milk Protein Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Cooperative-owned processors leverage captive milk supply to defend margin positions against publicly traded ingredient specialists. Three archetypes dominate: vertically integrated dairy cooperatives, standalone fractionation specialists, and multinational nutrition ingredient platforms. Capacity expansion in membrane filtration and strategic partnerships for precision fermentation feedstock dominate competitive moves.
Among cooperative-structured processors, FrieslandCampina Ingredients and LACTALIS Ingredients exemplify the vertically integrated archetype, anchoring positions through upstream control over raw milk flows. Glanbia plc occupies a position within the publicly traded specialist tier, representing focused investment in high-purity protein isolation capabilities. These three entities illustrate how governance structure—cooperative versus corporate—shapes competitive options available to market participants.
| Leading Market Players |
|---|
| Arla Foods Ingredients Group P/S |
| FrieslandCampina Ingredients |
| LACTALIS Ingredients |
| Glanbia plc |
| Unternehmensgruppe Theo Müller |
| Kerry Group PLC |
| wheyco GmbH |
| Hoogwegt |
| Lactoprot Deutschland GmbH |
| Others |
Supply & Pricing Matrix
Soybean meal and energy feed costs transmit from Black Sea grain corridor disruptions through French and Dutch dairy cooperatives into tiered protein pricing. Whey protein isolates for German sports nutrition brands absorb these upstream shocks differently than milk protein concentrates serving Polish bakery manufacturers.
Pricing Analysis
Bundled long-term offtake contracts with embedded sustainability certification trade at premiums against unbundled spot purchases without carbon footprint documentation. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade isolates with batch-level traceability from commodity concentrates for industrial applications. Pricing pressure stems from feed cost volatility compressing processor margins in the standard tier. Mass-market nutrition bar manufacturers exhibit highest price sensitivity, while infant formula producers in Ireland accept premium positioning for verified supply security.
Supply Chain Analysis
Reverse-logistics flows for membrane filtration system refurbishment concentrate technical service capacity in the Netherlands and northern Germany, extending equipment lifecycles for fractionation plants. Raw milk supply draws from Brittany's dairy cluster, the Dutch cooperative network, and Bavarian processing hubs. Dependency on ceramic membrane imports from specialized engineering centers in Germany and Switzerland creates single-source vulnerability for ultrafiltration upgrades. Distribution runs through direct-to-brand procurement channels displacing traditional commodity brokers, with institutional buyers negotiating facility-specific offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreversible clean-label reformulation mandates across European food manufacturing. Sports nutrition procurement expansion and clinical nutrition applications provide durable demand foundations.
For Market Incumbents: Deploy membrane filtration capacity additions in Poland and Romania to escape feed cost volatility concentrated in western European dairy belts. Secure multi-year whey protein supply contracts with German performance nutrition brands before processing capacity constraints harden. Invest in satellite-linked farm monitoring systems to meet CSRD disclosure requirements and differentiate against competitors lacking verified Scope 3 documentation. Plant protein substitution in mass-market nutrition bars demands premium positioning reinforcement through clinical-grade certification.
For New Entrants and Emerging Players: Begin with micellar casein production for sarcopenia management applications in aging European populations, where medical food formulators specify functional ingredients ahead of commodity scale. Target underutilized dairy infrastructure in Poland's Masovian and Greater Poland voivodeships for fractionation capacity serving Central European cost-optimized bakery and beverage manufacturers. Partner with precision fermentation technology providers to develop hybrid protein portfolios at 10-15% blend ratios for German sports nutrition pilot programs.
For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative-owned processors lack capital deployment flexibility for CSRD compliance infrastructure against corporate competitors with ESG-linked financing access. Five-to-ten year viability favors fractionation specialists with captive membrane engineering talent and established clinical nutrition certification pathways. Acquisition target archetype: mid-scale processors in Eastern Europe with underutilized infrastructure and proximity to expanding Central European demand. Monitor EFSA novel food authorization timelines for protein hydrolysate formats as inflection indicator for product pipeline velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Polish and Romanian installations capture Central European bakery and beverage demand growth. |
| CSRD Compliance Infrastructure Investment | Satellite-linked farm monitoring systems in Brittany meet institutional buyer disclosure requirements. |
| Direct-to-Brand Procurement Contracts | Three-to-five year offtake agreements with Dutch and German sports nutrition manufacturers displace commodity brokers. |
| Precision Fermentation Feedstock Partnerships | Hybrid protein portfolios at 10-15% blend ratios test consumer acceptance in German pilot programs. |
| Clinical Nutrition Certification Pathway | Micellar casein specifications for sarcopenia management access premium medical food pricing tiers. |
Research Methodology
Bottom-up dietary supplement and bakery modeling reconciled against top-down dairy processor capacity tracking forms the analytical core of this study. Primary interviews with membrane filtration process engineers, sports nutrition procurement directors, clinical food formulators, and cooperative dairy board members combined with secondary validation from EFSA novel food authorization databases, REACH chemical safety protocol filings, EU Farm to Fork Strategy implementation reports, and dairy cooperative sustainability disclosures. Triangulation between farm-level input cost data and end-use manufacturer procurement patterns ensures supply-demand balance integrity.
Input-output matrices map protein fractionation capacity across processing grades and end-use applications throughout the forecast period. Segmentation dimensions modeled include product type functionality, end-use formulation requirements, packaging specifications for industrial versus retail channels, and regional production cluster proximity to demand centers. CAGRs derive from capacity utilization trends, clean-label reformulation penetration rates, and sports nutrition brand expansion trajectories. Forecast inputs incorporate membrane filtration technology adoption curves and CSRD disclosure timeline compliance patterns.
Several conditions sit outside the modeled scope, including Black Sea grain corridor disruption severity, precision fermentation regulatory classification decisions, and plant protein taste profile breakthroughs. Forecasts reflect documented assumptions about cooperative capital access and clinical nutrition reimbursement stability. Practitioners should monitor EFSA authorization backlog durations and ceramic ultrafiltration engineering talent migration patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Latin America Cheese Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Butter and Margarine Market
Dairy Products
Condensed Whey Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Fermented Milk Products Market
Dairy Products
India Dairy Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Yogurt and Probiotic Drink Market