
 Cream Market | 2026-2036
Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Cream Market Intelligence
Major dairy cooperatives in Europe and North America are pivoting their processing capacity toward higher-value cream products to serve premium culinary markets. This strategic shift targets the professional food service and artisanal bakery sectors. Arla Foods leverages its extensive cooperative network to ensure a consistent supply of high-fat cream. Fonterra Co-operative Group specializes in dairy ingredients for industrial applications, while Lactalis controls significant market presence through its diverse brand portfolio.
Cream is a dairy product composed of the higher-butterfat layer skimmed from the top of milk before homogenization. Its functional properties, determined by fat content ranging from 18% for light cream to over 36% for heavy cream, are essential for texture and flavor in culinary applications. Heavy Cream and Whipping Cream formats lead the product landscape due to their versatility. The food service and baking applications represent the largest value pools, driven by professional chefs and industrial food manufacturers.
Product standards and labeling are governed by national food safety authorities, including the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). In India, the Food Safety and Standards Authority of India (FSSAI) sets composition and purity requirements for dairy products, influencing market access. Future success depends on navigating consumer demand for clean-label ingredients while managing volatile raw milk input costs.
Market Dynamics
The central structural force shaping the cream market is the dual demand for clean-label, natural ingredients and the high-performance functional properties required by industrial food service applications, creating a persistent tension between formulation simplicity and processing complexity.
Growth Catalysts
- Food Service Expansion:The proliferation of artisanal bakeries, cafes, and premium dessert parlors, particularly in urban centers across North America and Europe, drives consistent demand for high-fat whipping and heavy creams.
- Emerging Market Palates:Rising disposable incomes in India and other parts of Asia are shifting dietary habits towards Western-style baked goods and dairy-rich beverages, expanding the consumer base for processed cream products.
- Clean-Label Movement:A strong consumer preference for recognizable ingredients is compelling food manufacturers to substitute artificial emulsifiers and thickeners with natural cream, boosting its use in soups, sauces, and ready-to-eat meals.
Market Restraints
- Input Cost Volatility:The market is directly exposed to fluctuations in raw milk prices, which are influenced by feed costs, weather conditions, and agricultural policies, creating significant margin pressure for cream processors.
- Logistical Hurdles:Fresh cream's short shelf life necessitates a robust and expensive cold chain infrastructure, limiting market access in regions with underdeveloped logistics and increasing the risk of spoilage and waste.
- Plant-Based Substitution:A growing threat comes from plant-based alternatives derived from coconut, soy, and oats, which appeal to vegan consumers and those with lactose intolerance, eroding market share in certain applications.
Strategic Opportunities
- Shelf-Stable Formats:Developing and marketing UHT and extended shelf-life cream products opens new export channels to markets in Southeast Asia and the Middle East where cold chain infrastructure is less reliable.
- Specialty Ingredient Development:Formulating cream products with specific functional properties, such as enhanced stability for frozen desserts or unique flavor profiles for savory sauces, allows for value-added pricing.
- Certified-Origin Products:There is a significant opportunity in marketing organic, grass-fed, or single-origin creams, which command a premium price from consumers who prioritize animal welfare, sustainability, and product traceability.
Industry Challenges
- Regulatory Divergence:Navigating the complex and often conflicting composition and labeling standards set by authorities like the FSSAI in India, the FDA in the US, and EFSA in Europe complicates international trade and product formulation.
- Energy-Intensive Processing:The high energy consumption required for pasteurization, separation, and refrigeration processes exposes manufacturers to volatile energy prices and increasing pressure to reduce their carbon footprint.
- Standardization Gaps:The lack of globally harmonized definitions for terms like "light," "heavy," and "whipping" cream creates procurement challenges for industrial buyers operating across different regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream Market |
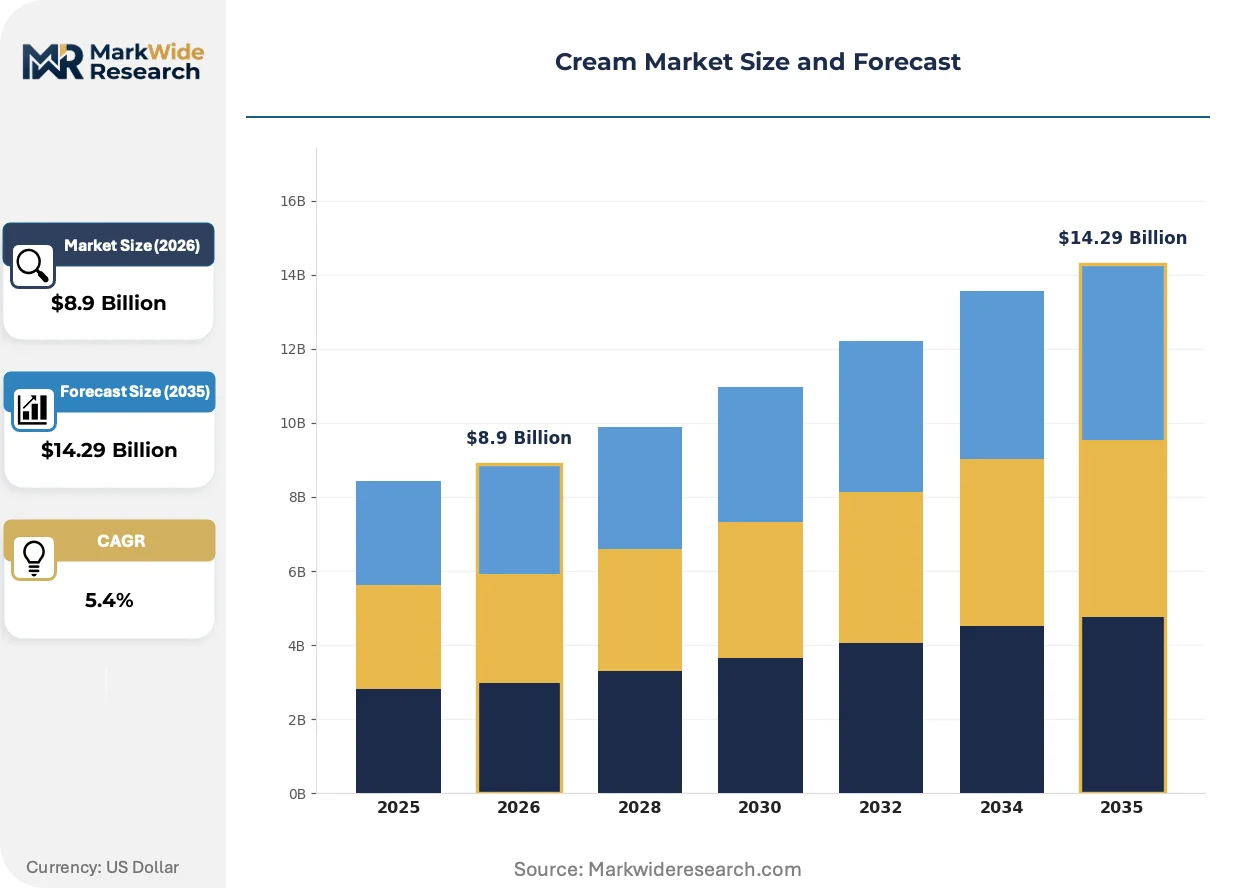
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.29 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Cream, Whipping Cream, Sour Cream, Double Cream Application: Baking, Cooking, Food Service, Dairy Products Packaging Type: Cartons, Tubs, Bottles, Sachets Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Wholesalers |
| Companies Covered | Nestlé S.A., Danone, Arla Foods, Royal FrieslandCampina, Fonterra Co-operative Group, Lactalis, Land O'Lakes, Dairy Farmers of America, Amul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream Market Strategic Shifts & Innovations
Product innovation is focused on achieving specific functional outcomes for industrial clients while simultaneously appealing to consumer demand for naturalness and transparency. This balancing act drives advancements in both processing technology and supply chain traceability to meet dual objectives.
Advanced membrane filtration technology allows for the precise separation of milk components to create customized cream formulations. Industrial food manufacturers are rapidly adopting this process to achieve specific fat percentages and functional properties for applications like high-stability whipped toppings and rich sauces. This level of precision processing is overtaking traditional centrifugal separation, enabling the creation of novel dairy ingredients with superior performance.
Stricter country-of-origin labeling (COOL) and protected designation of origin (PDO) rules in the European Union are increasing the emphasis on supply chain transparency. These regulations compel processors to document and verify the source of their raw milk, adding a layer of compliance complexity. The premium and artisanal cream segments are most affected, leveraging these designations as a marketing tool to justify higher price points and communicate product authenticity to consumers.
A notable behavioral shift is occurring as large-scale food manufacturers move from purchasing cream as a simple commodity to sourcing it as a functional ingredient. This disrupts the role of broadline distributors, fostering direct partnerships between food companies and dairy cooperatives to co-develop application-specific cream products. The trend is most visible in the industrial bakery and confectionery sectors, where texture, mouthfeel, and stability are critical to final product quality.
Cream Market Segmentation
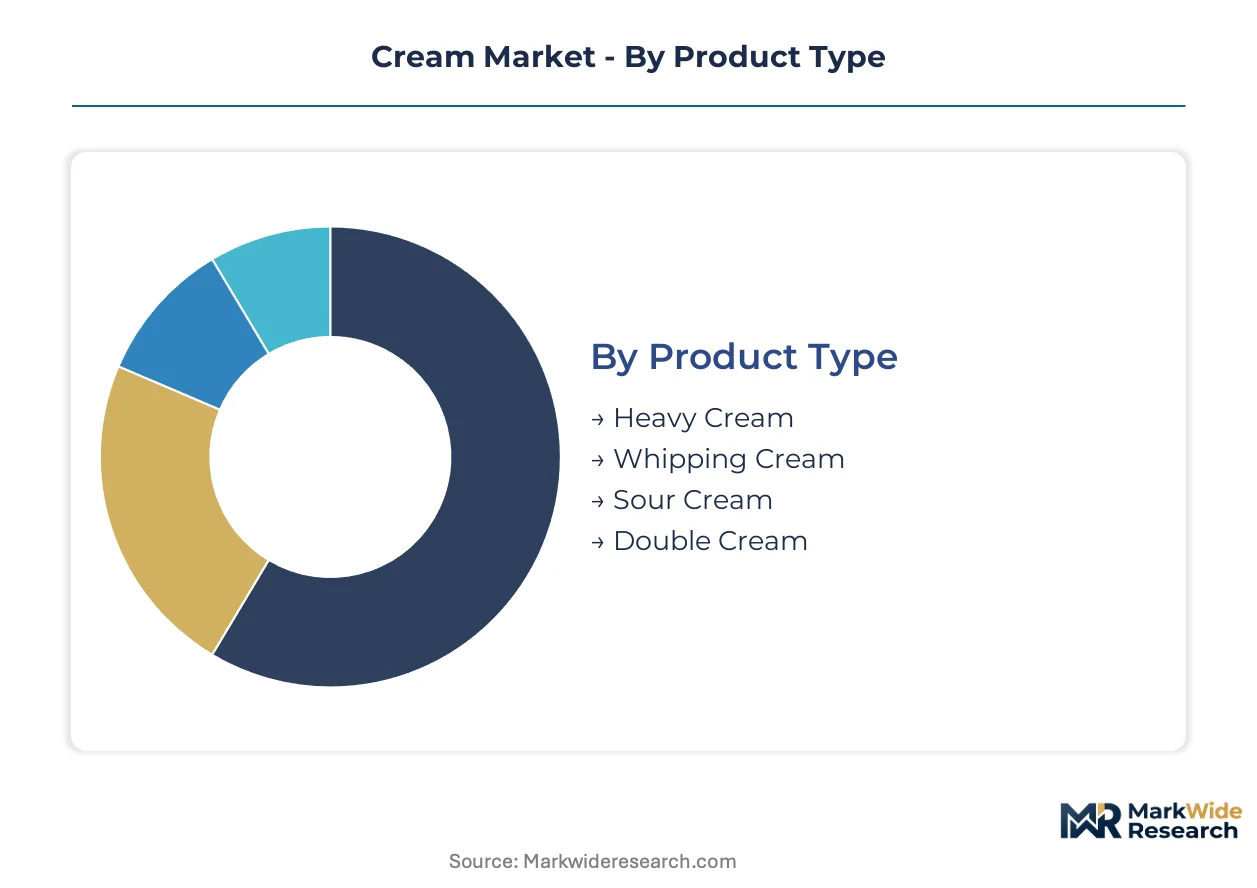
The cream market's structure reflects diverse product specifications and end-use requirements. Understanding these segments clarifies demand patterns and competitive dynamics across various consumer and industrial applications. This granular view highlights areas of growth and specific market needs.
Product Type:
Product type segmentation delineates cream varieties based on their butterfat content and functional properties, which are critical for specific culinary outcomes.
- Heavy Cream:This product typically contains over 36% butterfat, providing superior richness and stability for culinary applications. Demand concentrates in professional food service kitchens, where its high fat content is essential for achieving desired textures in sauces and desserts.
- Whipping Cream:Characterized by a butterfat content generally between 30% and 36%, it is formulated for aeration and volume expansion. Artisanal bakeries and premium dessert parlors in urban centers drive consistent demand for this versatile cream.
- Sour Cream:This fermented cream product offers a tangy flavor and thick texture, widely used in savory dishes and as a condiment in North America.
- Double Cream:This very high-fat cream, often exceeding 48%, is a rich, pourable product popular in European dessert and sauce preparations.
Mature deployment sits with Heavy Cream. Newer deployment is concentrated in Double Cream.
Application:
Application segments highlight the primary end-uses for cream, ranging from industrial food manufacturing to direct consumer consumption.
- Food Service:This segment encompasses professional kitchens, restaurants, and catering operations, utilizing cream for a wide array of dishes and preparations. The proliferation of cafes and premium dessert parlors, particularly in Europe, drives significant volume demand.
- Baking:Cream is an essential ingredient in cakes, pastries, and other confectionery items, providing moisture, richness, and texture. Industrial food manufacturers in India increasingly source cream for Western-style baked goods production.
- Cooking:This category includes cream used in household cooking and ready-to-eat meals, contributing to flavor and consistency in soups and sauces.
- Dairy Products:Cream serves as a base ingredient for other dairy items like ice cream, butter, and cheese, particularly in large-scale processing facilities.
The Food Service segment maintains consistent demand. Baking applications show the steepest expansion trajectory.
Packaging Type:
Packaging type segmentation reflects the diverse needs for preservation, distribution, and consumer convenience across various market channels.
- Cartons:Aseptic and UHT cartons offer extended shelf life, supporting broader distribution channels and export to regions with less developed cold chain infrastructure, such as Southeast Asia.
- Tubs:These containers are common for thicker cream products like sour cream and double cream, providing resealability and ease of use for consumers and food service operators. Their convenience drives consistent retail demand.
- Bottles:Primarily used for liquid cream products, bottles cater to specific consumer preferences and portion control in some European markets.
- Sachets:Single-serve sachets offer portion control and convenience, particularly for individual consumption in cafes and travel catering.
Packaging concentration favors cartons for shelf-stable products. Tubs remain essential for refrigerated cream varieties.
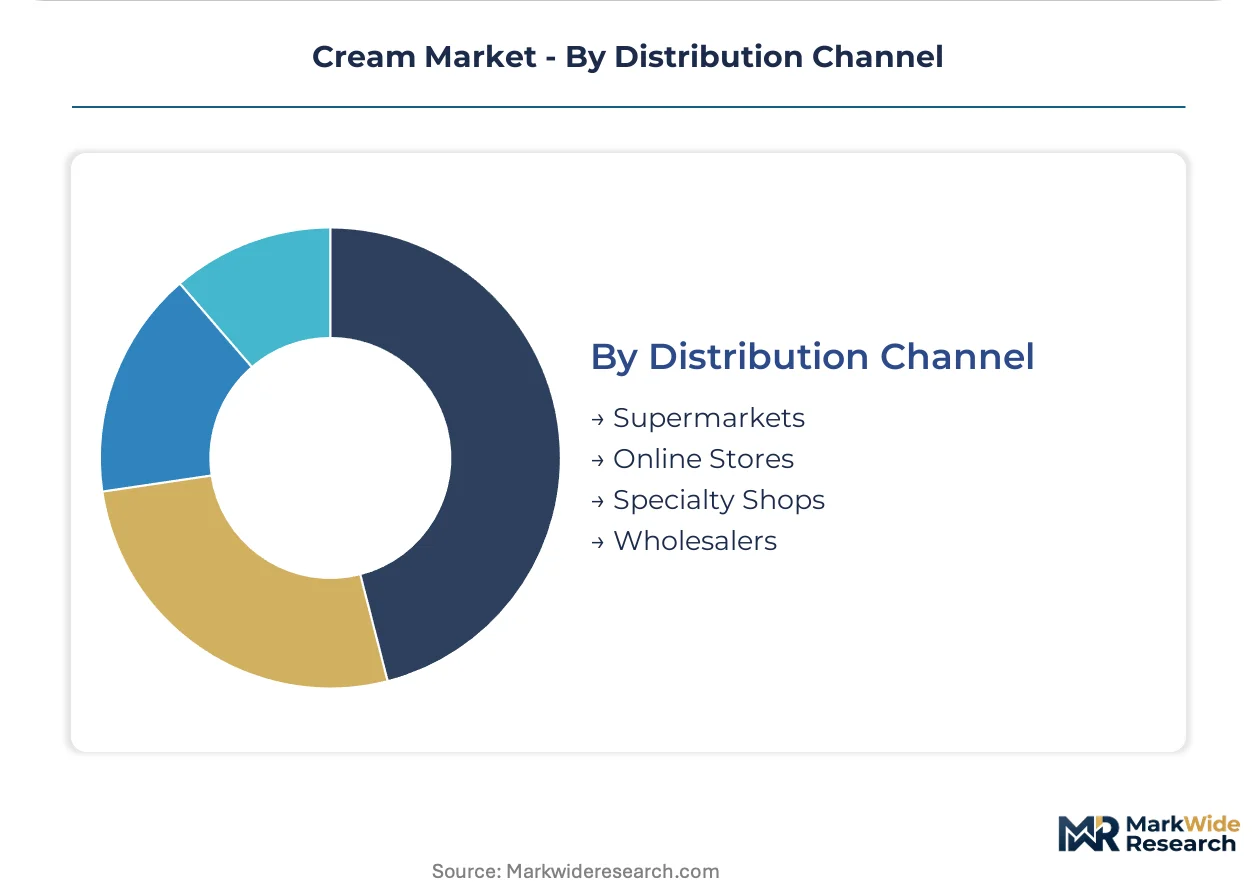
Distribution Channel:
Distribution channel segmentation outlines the primary avenues through which cream products reach end-users, influencing market accessibility and consumer reach.
- Supermarkets:These large retail chains serve as the primary point of sale for consumer-packaged cream, benefiting from extensive geographic reach and high foot traffic in urban and suburban areas. Organized retail expansion in India drives volume through this channel.
- Wholesalers:This channel supplies bulk cream to industrial food manufacturers, professional food service establishments, and smaller retailers. Direct partnerships between dairy cooperatives and food companies are increasingly leveraging this route.
- Online Stores:E-commerce platforms facilitate direct-to-consumer sales, offering convenience and broader product selection, particularly for niche or premium cream brands.
- Specialty Shops:These outlets, including artisanal bakeries and gourmet food stores, focus on premium, organic, or certified-origin cream products, serving discerning consumers.
Supermarkets capture significant consumer market share. Wholesalers underpin industrial and food service supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major milk-producing regions anchor the cream market, with dairy farming traditions and advanced processing capabilities influencing supply and demand dynamics. Consumer preferences for natural ingredients and specific culinary applications shape regional market growth. Regulatory frameworks ensure product safety and quality across diverse geographies.
India
Rising disposable incomes in India drive demand for Western-style baked goods and dairy-rich beverages. The Food Safety and Standards Authority of India (FSSAI) sets strict purity requirements for dairy products, influencing market access. Expansion of organized retail and food processing industries in urban centers like Mumbai and Delhi boosts cream consumption.
United States
The United States sees consistent demand for high-fat whipping and heavy creams from its professional food service sector. The US Food and Drug Administration (FDA) governs product standards and labeling for dairy items. Artisanal bakeries and cafes in cities like New York and Los Angeles contribute significantly to premium cream sales.
Germany
Germany represents a strong European market for high-value cream products, serving premium culinary markets. The European Food Safety Authority (EFSA) ensures rigorous food safety standards for dairy processing. Dairy cooperatives in Bavaria and North Rhine-Westphalia focus on specialized cream formulations for industrial and artisanal applications.
New Zealand
New Zealand's dairy industry focuses on industrial dairy ingredients and exports, leveraging its efficient milk production. Its national food safety authority ensures stringent quality control for exported dairy products. Fonterra Co-operative Group, headquartered in Auckland, specializes in high-performance cream ingredients for global food manufacturers.
France
French consumers and chefs prioritize cream for its essential role in traditional cuisine and patisserie. The European Union's protected designation of origin (PDO) rules impact premium cream segments. Lactalis, a major dairy company with strong roots in Laval, produces a diverse portfolio of cream products for domestic and international markets.
Cream Market Key Industry Players
Global majors compete with regional champions across the dairy processing and distribution landscape. The market structure exhibits a tiered approach, with large cooperatives and multinational food companies dominating supply. Strategic archetypes include integrated dairy giants, specialized ingredient providers, and regional fresh product suppliers. Market players engage in capacity expansion and portfolio diversification to secure their positions.
Among the large-scale dairy cooperatives and multinational food companies, Arla Foods occupies a significant position, leveraging its extensive network for consistent supply. Fonterra Co-operative Group exemplifies a specialist in industrial dairy ingredients, catering to global food manufacturers. Lactalis represents a major player through its diverse brand portfolio and substantial market presence across various product categories.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone |
| Arla Foods |
| Royal FrieslandCampina |
| Fonterra Co-operative Group |
| Lactalis |
| Land O'Lakes |
| Dairy Farmers of America |
| Amul |
| Others |
Cost & Logistics Intelligence
Skilled dairy processing labor in Europe contributes to the premium pricing of specialized cream formulations, creating distinct pricing-tier spreads compared to commodity bulk product. Global raw milk prices, influenced by feed costs and weather, directly impact processor margins across all segments.
Pricing Analysis
Technical support and application guidance bundled with high-value cream products forms part of the overall offering. The dominant pricing structure for industrial buyers involves contract-based long-term offtake agreements. Price differentiation drivers include quality grade for artisanal applications and specific functional properties for industrial food manufacturers. Pricing softness reflects intense competition from plant-based alternatives in certain consumer segments. Industrial food manufacturers are typically the most price-sensitive buyers, while premium patisseries demonstrate lower price sensitivity for specialized creams.
Supply Chain Analysis
Regional cold storage hubs and specialized refrigerated transport networks are critical for maintaining fresh cream quality. Geographic supply concentration for dairy ingredients centers on New Zealand, Germany, and the United States. Raw milk, specialized packaging materials, and energy for refrigeration represent critical input dependencies. Logistics chokepoints, particularly for cross-border fresh cream shipments, present a structural supply chain risk. Distribution runs through a dual model of wholesalers serving industrial clients and supermarkets catering to consumer demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
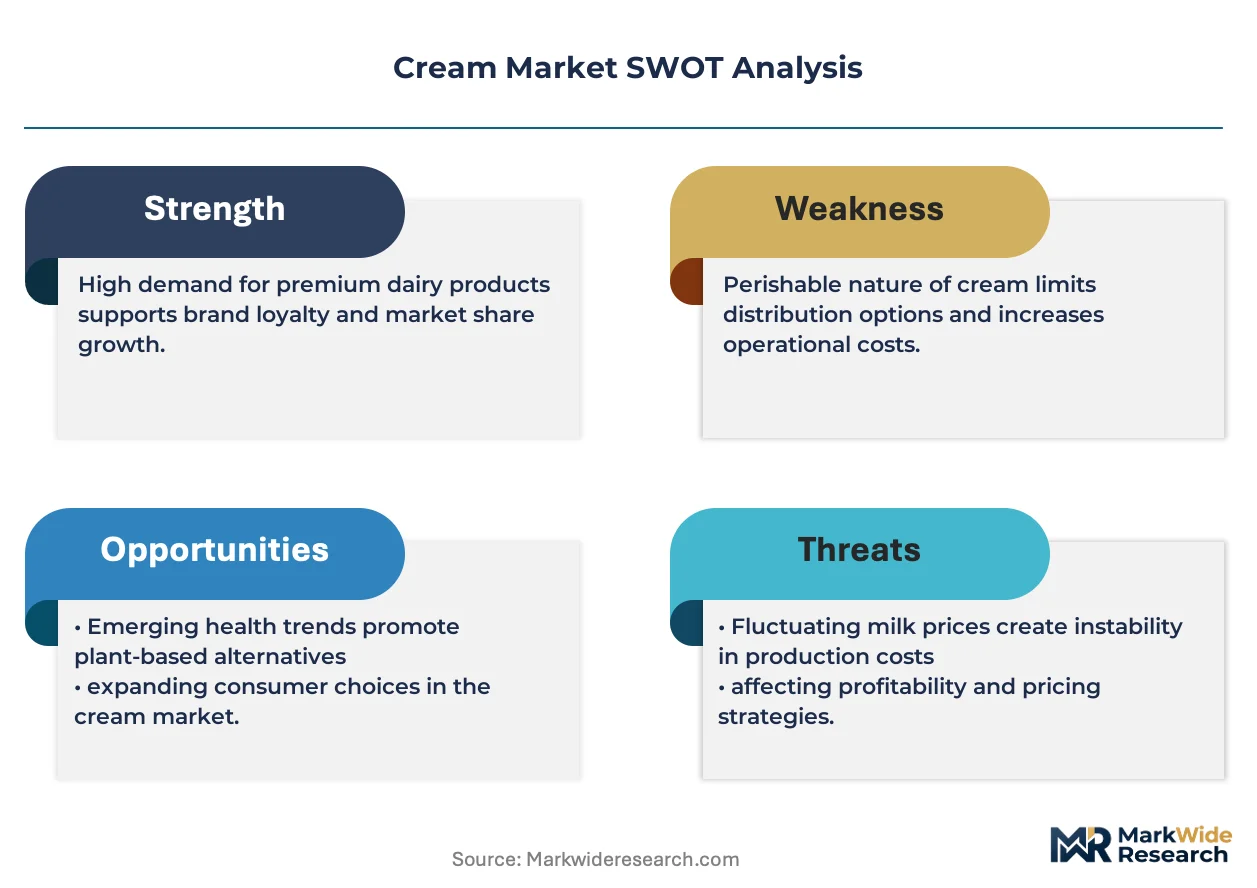
The cream market functions as a supply-constrained story, with specialized processing capacity for high-fat cream acting as a key bottleneck propping up pricing power.
For Market Incumbents: Hedge against raw milk price volatility through long-term supply contracts with dairy farmers. Invest in advanced UHT processing technology to extend shelf life, mitigating logistical hurdles and opening new export markets in Asia. This proactive stance helps counter the threat from plant-based substitution in consumer applications. Focus R&D on developing application-specific cream formulations with superior functional properties.
For New Entrants and Emerging Players: Protected Designation of Origin (PDO) rules in the European Union open a window for niche players to command premium pricing. Target underpenetrated premium segments, such as certified organic or grass-fed creams, appealing to discerning consumers. A direct-to-consumer online sales model can bypass established distribution channels. Focus on regions with developing cold chain infrastructure but high demand for shelf-stable dairy, like Southeast Asia.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized ingredient providers and regional processors given the growing demand for functional, natural ingredients. Long-term viability rests on securing stable raw material sourcing and investing in value-added processing capabilities. The acquisition target archetype includes mid-sized dairy companies with strong regional supply chain control or unique processing technologies. Consolidation among mid-sized players serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply for growing food service demand in urban centers. |
| Green Manufacturing Transition | Reduces energy costs and appeals to sustainability-conscious consumers. |
| Long-term Supply Agreement | Mitigates raw milk price volatility for cream processors. |
| Product Launch | Introduces new functional cream formulations for industrial clients. |
| Distribution Channel Expansion | Reaches new markets in Southeast Asia with shelf-stable products. |
Research Approach
FSSAI reports, EFSA guidelines, and USDA dairy statistics formed the secondary backbone for market sizing and trend identification. This was combined with primary interviews conducted with dairy cooperative executives, food manufacturers' R&D heads, professional chefs, and retail procurement managers. The analysis incorporated both bottom-up and top-down triangulation to validate market figures and growth projections.
Historical trendline analysis established the foundation for forecasting market trajectory across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, packaging type, distribution channel, and butterfat content. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating inputs such as raw milk production volumes and disposable income growth rates.
The model assumes a particular technology adoption path; alternative pathways for membrane filtration technology would alter the outlook. Forecasts reflect underlying assumptions regarding raw material availability and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Colombia Dairy Market
Dairy Products
South America Dairy Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
United States Dairy Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Recombined Milk Market
Dairy Products
Ricotta Market