
 Middle East Dairy Market | 2026-2036
Middle East Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Dairy Market Insights
The capital-intensity divergence between integrated desert farming operations and import-reliant packagers is rotating competitive advantage toward firms with captive milk supply. Almarai Company leverages its vertically controlled dairy farms across Saudi Arabia to sustain margin stability against feed-cost volatility. Arla Foods AmbA anchors its Gulf position through long-life UHT exports that compete on reliability where local fresh milk falls short. NADEC specializes in value-added labneh and strained yogurt, occupying a niche between mass-market and artisan positioning.
Middle East dairy encompasses fluid milk, fermented products, and fat-based derivatives processed under halal certification and often fortified with vitamins A and D to address regional nutritional gaps. UHT treatment dominates liquid milk due to ambient storage needs, while chilled segments require continuous cold-chain integrity from farm to retail. Yogurt and labneh command the strongest household penetration across Levant and Gulf markets, with cheese experiencing faster growth in foodservice channels as pizza and burger chains expand. Tetra Pak aseptic cartons lead packaging formats for ambient milk, though pouches gain traction in price-sensitive Egyptian and Yemeni border trade.
Saudi Arabia's SFDA enforces halal slaughter and processing protocols that extend to dairy enzymes and cultures, while UAE's MOHAP monitors fortification compliance and additive limits across Dubai and Abu Dhabi import channels. Egypt's central food regulator maintains price-ceiling mechanisms on white cheese and milk that distort private-label investment cycles. Stakeholders must track how Gulf economic diversification agendas redirect agricultural subsidies from water-intensive local farming toward processed dairy imports and re-exports.
Market Dynamics
Capital intensity at the farm-gate level is consolidating competitive advantage toward processors with captive milk supply, as feed-cost volatility and water scarcity render import-dependent packagers structurally exposed.
Growth Catalysts
- Foodservice Professionalization:Restaurants and cafés across the Gulf are expanding dairy procurement as hospitality chains standardize supply contracts and centralize purchasing functions.
- SFDA Shelf-Life Labeling Mandates:Saudi Arabia's tightened requirements are pushing processors toward cold-chain investments that improve product integrity and extend distribution reach.
- Urban Retail Infrastructure:Saudi Arabia and the UAE are concentrating demand through premium chilled categories supported by modern supermarket networks and temperature-controlled logistics.
Market Restraints
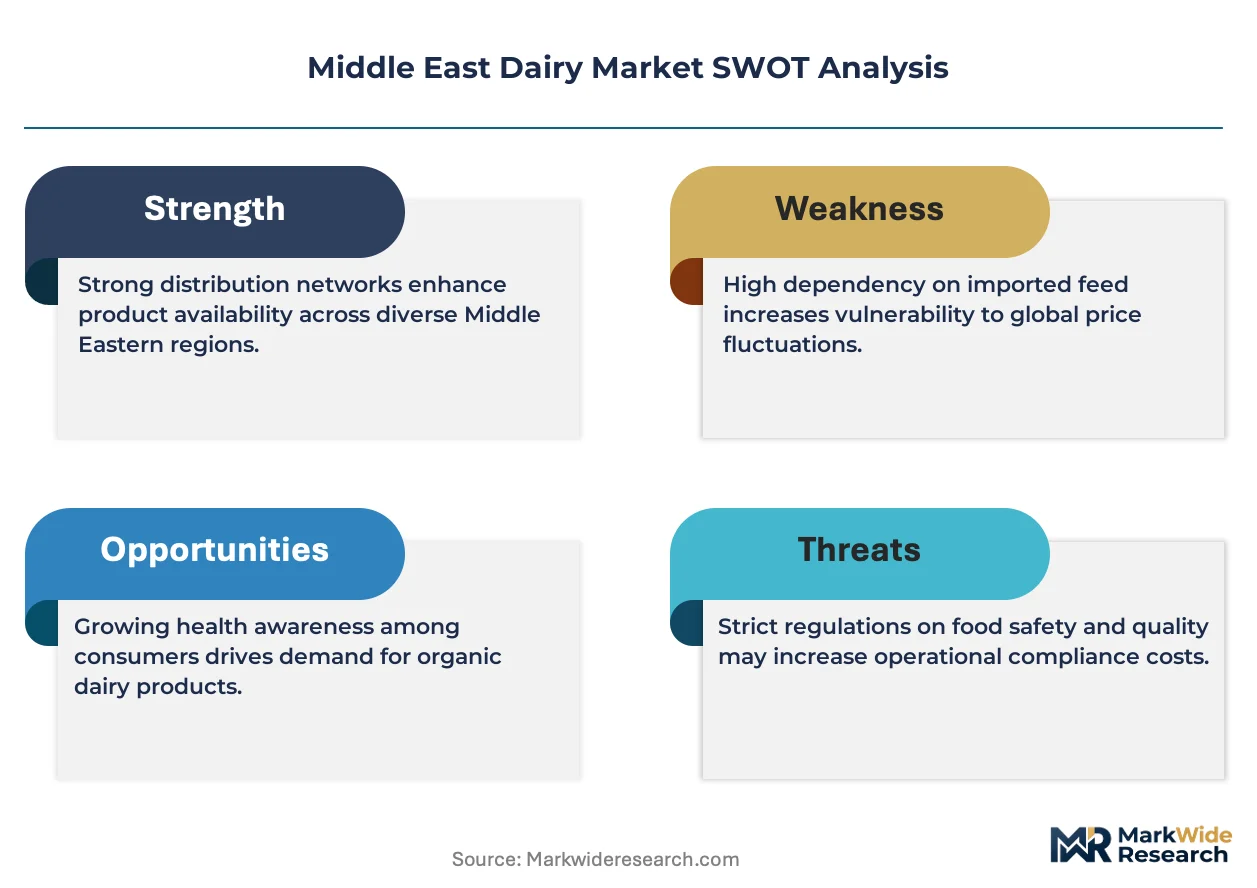
- Feed Cost Volatility:Alfalfa and soybean meal price swings destabilize margin structures for integrated desert farming operations dependent on imported inputs.
- Water Scarcity Constraints:Gulf governments are redirecting agricultural subsidies away from water-intensive local dairy farming toward processed imports and re-exports.
- UHT Reliability Gap:Local fresh milk supply interruptions strengthen Arla Foods AmbA's long-life export position, constraining domestic processor volume expansion.
Strategic Opportunities
- Egyptian Border Trade:Pouch packaging formats are gaining traction in price-sensitive Egyptian and Yemeni cross-border channels underserved by premium carton suppliers.
- Fortification Compliance:UAE's MOHAP monitoring of vitamin A and D additive limits creates first-mover advantage for processors with validated fortification protocols.
- Cheese Foodservice Penetration:Pizza and burger chain expansion across Levant markets opens white space for mozzarella and processed cheese variants beyond traditional yogurt dominance.
Industry Challenges
- Halal Certification Complexity:SFDA enforcement of halal slaughter protocols extending to dairy enzymes and cultures lengthens product development timelines and supplier qualification cycles.
- Cold-Chain Capex Burden:Continuous temperature integrity from farm to retail requires refrigerated transport fleet expansion and warehouse automation investments that strain mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Dairy Market |
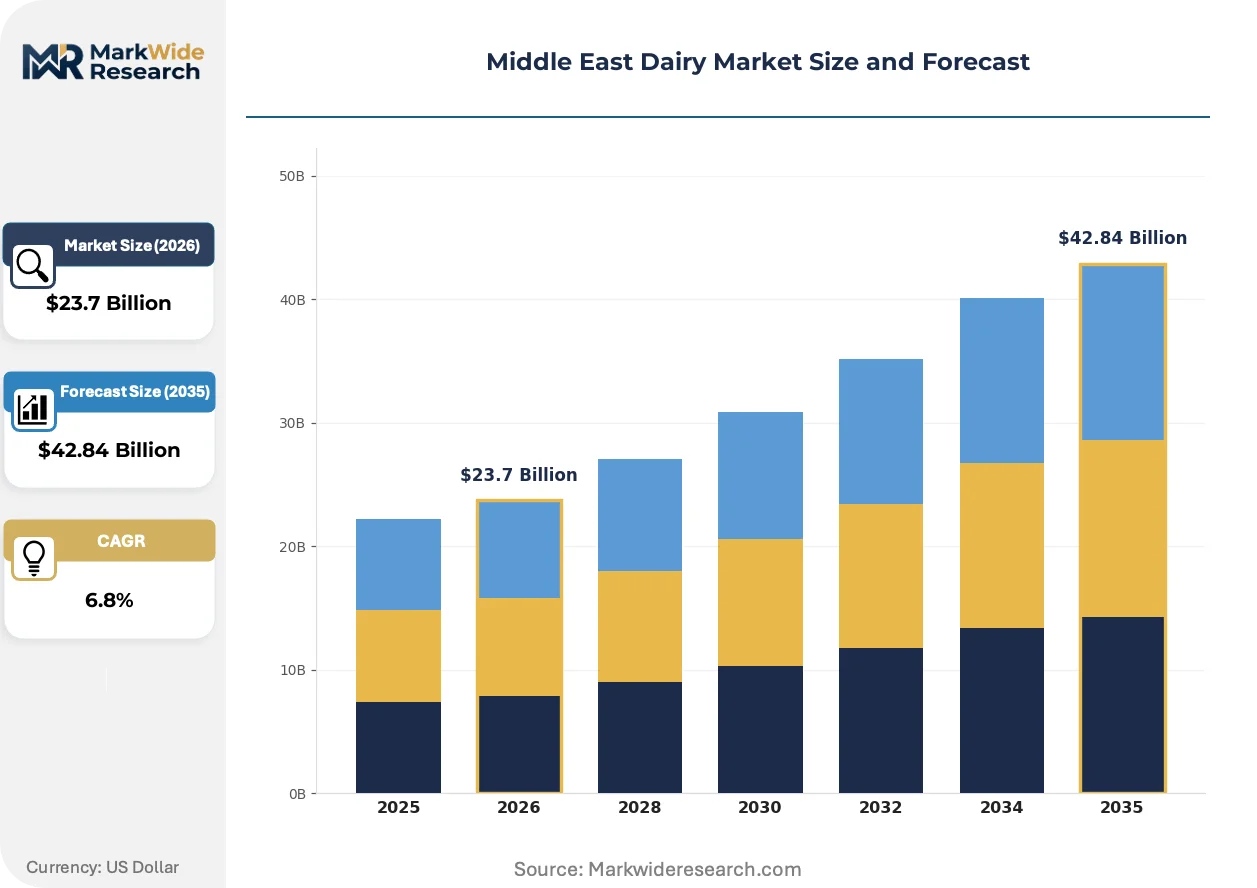
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Cream Packaging Type: Bottles, Tetra Packs, Pouches, Cartons Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers End User: Households, Restaurants, Cafés, Bakeries |
| Companies Covered | Saudia Dairy and Foodstuff Company (SADAFCO), Arla Foods AmbA, Almarai Company, AlRawabi Dairy Company, Groupe Lactalis, Nestlé SA, National Agricultural Development Company (NADEC), Fonterra Co-operative Group, Danone SA, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Dairy Market Trends and Innovations
Aseptic processing advances and regulatory fortification mandates are compressing traditional processing margins while opening premium positioning through certified nutritional claims and extended shelf-life formats.
Extended shelf-life (ESL) processing technology is decomposing the historical trade-off between ambient UHT stability and fresh taste credentials. Saudi processors with integrated farm operations are adopting membrane filtration and advanced pasteurization to bridge the gap between mass-market UHT and premium chilled segments. This technology is decomposing the binary market structure that previously forced consumers to choose between convenience and sensory quality.
SFDA halal certification protocols for dairy enzymes and starter cultures are tightening ingredient traceability requirements across Saudi processing facilities. The industrial consequence is accelerated supplier consolidation as smaller culture houses lack documentation infrastructure for slaughter-derived rennet alternatives. Fermented products and specialty cheeses face the steepest compliance ramps, with NADEC and Almarai investing in dedicated halal culture banks to secure supply continuity.
Foodservice buyers across Dubai and Abu Dhabi hospitality clusters are consolidating procurement through centralized purchasing cooperatives that bypass traditional distributor markups. Hotel chains and contract caterers are negotiating direct supply agreements with processors for bulk labneh, strained yogurt, and portion-controlled cheese formats. This concentration is most visible in UAE's premium hospitality vertical, where procurement leverage has compressed distributor margins by fifteen to twenty percent over two contract cycles.
Middle East Dairy Market Segmentation
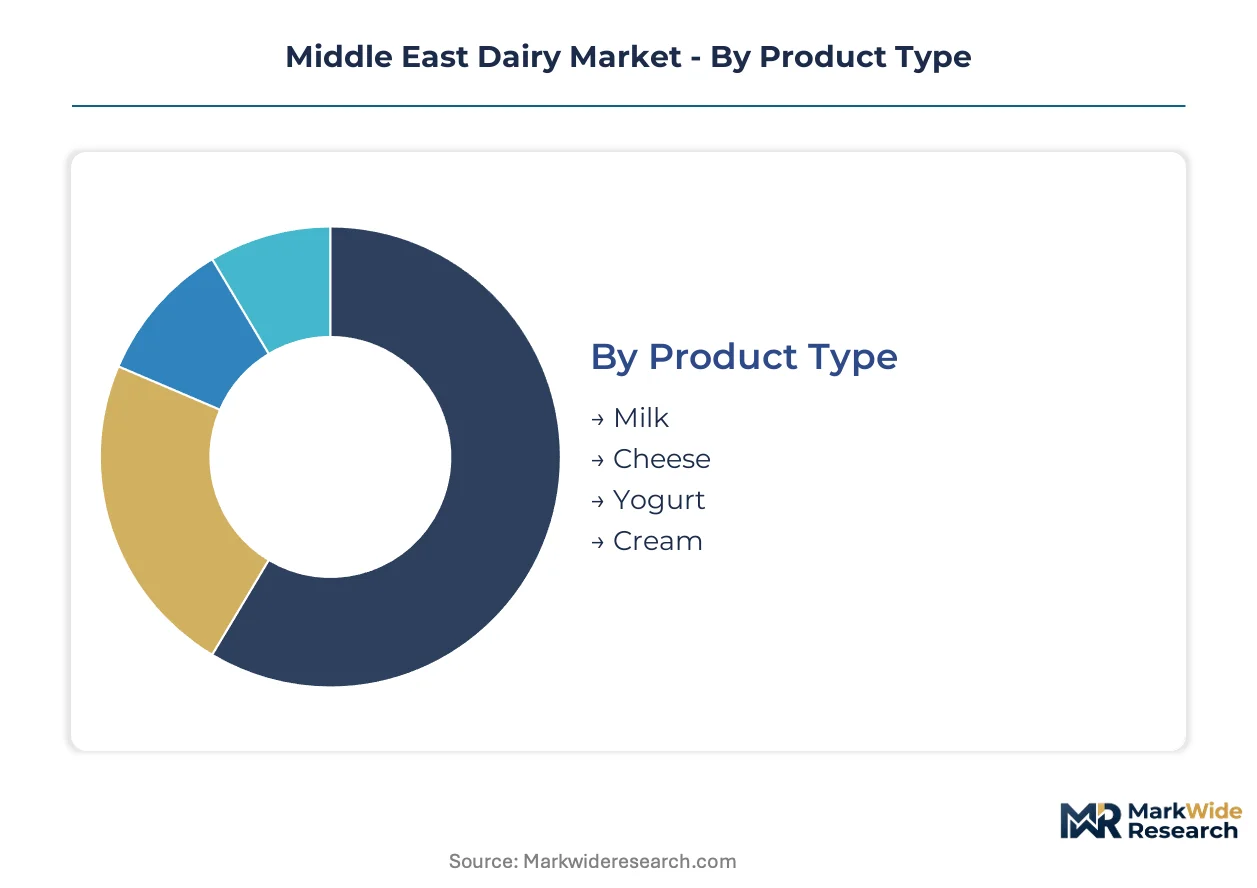
Segmentation across the Middle East dairy market reveals how regulatory requirements, distribution infrastructure, and end-use concentration create distinct competitive arenas. Each dimension carries specific compliance burdens and margin structures that reshape processor investment priorities.
Product Type:
SFDA halal certification protocols for dairy enzymes and starter cultures apply differentially across product categories, with fermented items facing steeper documentation requirements than fluid milk.
- Milk:UHT-treated ambient milk dominates volume through Tetra Pak aseptic cartons, with Saudi Arabia and the UAE concentrating demand for vitamin A and D fortified variants. SFDA shelf-life labeling mandates are accelerating cold-chain investments for chilled fresh milk segments.
- Yogurt:Strained varieties and labneh command the strongest household penetration across Levant and Gulf markets, requiring continuous temperature integrity from processing through retail. MOHAP fortification monitoring in the UAE creates compliance differentiation for validated protocols.
- Cheese:Pizza and burger chain expansion across Levant markets drives mozzarella and processed cheese demand through foodservice channels.
- Cream:Fat-based derivatives serve bakery and hospitality applications with halal slaughter protocols extending to enzyme-derived processing aids.
Milk handles the majority of throughput; cheese is expanding most quickly on share as foodservice channels professionalize.
Packaging Type:
Packaging selection maps directly to cold-chain maturity and price sensitivity across distribution corridors, with ambient-stable formats dominating where refrigeration infrastructure remains uneven.
- Tetra Packs:Aseptic carton technology leads ambient milk distribution through Saudi supermarket networks and UAE retail channels, enabling extended shelf life without continuous refrigeration. The format supports SFDA-compliant labeling and fortification visibility requirements.
- Pouches:Flexible packaging gains traction in Egyptian and Yemeni border trade where price sensitivity outweighs premium carton positioning. Lower unit economics serve informal retail and cross-border wholesale movements.
- Bottles:HDPE and PET formats serve chilled fresh milk segments requiring cold-chain integrity from Riyadh and Dubai processing facilities through temperature-controlled retail.
- Cartons:Gable-top chilled cartons support premium positioning in Saudi urban retail infrastructure with shorter shelf life and higher sensory quality credentials.
Tetra Packs handle the majority of throughput; pouches are gaining share fastest in underserved border corridors.
Distribution Channel:
Channel concentration reflects urban retail infrastructure development and hospitality procurement professionalization across Gulf metropolitan centers.
- Supermarkets:Modern retail networks in Riyadh, Jeddah, Dubai, and Abu Dhabi anchor premium chilled category distribution with temperature-controlled logistics and centralized purchasing functions. SFDA labeling compliance and MOHAP fortification monitoring flow through these formal channels.
- Restaurants and Cafés:Hospitality chains across Dubai and Abu Dhabi hospitality clusters consolidate procurement through centralized purchasing cooperatives, negotiating direct supply agreements for bulk labneh and portion-controlled cheese formats.
- Convenience Stores:Smaller-format urban retail extends UHT and ambient yogurt reach with limited cold-chain requirements.
- Online Retail:E-commerce platforms build chilled delivery capabilities through insulated packaging and same-day logistics in Saudi and UAE urban corridors.
- Wholesalers:Traditional distribution serves price-sensitive Egyptian and Yemeni border markets with pouch-packed ambient products.
Supermarkets handle the majority of throughput; restaurants and cafés are climbing the fastest on share as hospitality procurement centralizes.
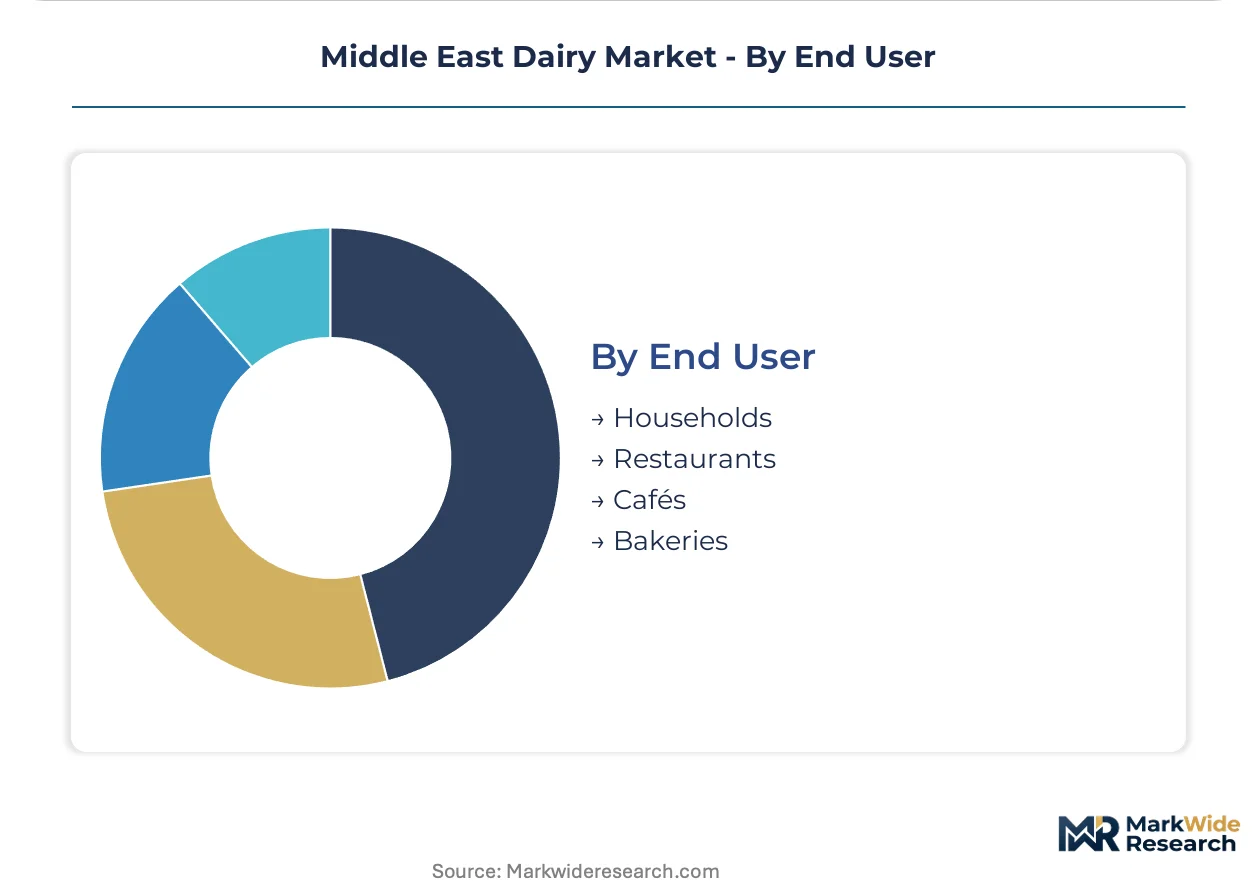
End User:
End-use segmentation tracks the divergence between household fortification-driven consumption and foodservice operational scale requirements.
- Households:Family consumption concentrates in yogurt and labneh with vitamin A and D fortification addressing regional nutritional gaps. Saudi and UAE urban households drive premium chilled segment demand through modern retail access.
- Restaurants:Full-service dining and quick-service chains standardize supply contracts for mozzarella, processed cheese, and bulk fermented products across Levant expansion markets.
- Cafés:Coffee shop chains and independent operators in Dubai and Abu Dhabi procure portion-controlled cream and labneh formats through direct processor agreements.
- Bakeries:Traditional and industrial baking operations utilize fat-based cream derivatives with halal-certified enzyme processing.
Households handle the majority of throughput; restaurants are gaining share fastest as chain expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency shapes competitive positioning across Middle East dairy markets, with local production capacity concentrated in Saudi Arabia and the UAE while smaller markets rely on cross-border trade and re-export hubs for supply security.
Saudi Arabia
Integrated desert farming operations anchor domestic fluid milk supply, with Almarai and NADEC controlling captive feed-to-retail chains. SFDA shelf-life labeling mandates and halal certification protocols for dairy enzymes tighten compliance burdens on fermented product lines. Riyadh and Jeddah processing clusters concentrate cold-chain investments as urban retail infrastructure expands premium chilled distribution.
United Arab Emirates
Dubai and Abu Dhabi hospitality clusters drive foodservice dairy demand through centralized procurement cooperatives negotiating direct processor agreements. MOHAP fortification monitoring of vitamins A and D creates compliance differentiation for validated protocols. Re-export logistics through Jebel Ali position the UAE as a regional distribution hub for ambient UHT formats entering Levant and African markets.
Egypt
Price-ceiling mechanisms on white cheese and fluid milk distort private-label investment cycles and compress processor margins. Central food regulator oversight maintains affordability mandates that limit premium category development. Cairo and Alexandria urban corridors concentrate modern retail expansion, though informal wholesale channels dominate volume through pouch-packed ambient products.
Jordan
Labneh and strained yogurt production serves Levant household consumption patterns with strong penetration in traditional retail. Cross-border trade with Saudi Arabia and UAE supplies UHT and processed cheese variants where local fresh milk falls short. Amman processing facilities face cold-chain infrastructure gaps that constrain chilled segment expansion beyond supermarket networks.
Qatar
Foodservice procurement from Dubai and Saudi Arabia dominates hospitality supply as local dairy farming remains limited by water scarcity constraints. Government agricultural subsidy redirection favors processed import reliance over domestic production investment. Doha retail modernization supports premium chilled categories through temperature-controlled logistics partnerships with regional processors.
Middle East Dairy Market Competitive Landscape
Concentration sits with integrated national champions controlling captive milk supply, while multinational exporters anchor ambient segments and regional specialists occupy fermented product niches. The vendor base stratifies across three tiers: desert farming integrators with feed-cost hedging, long-life exporters competing on reliability, and value-added specialists in traditional categories. Dominant competitive moves include cold-chain capacity expansion to meet SFDA compliance and direct procurement agreements bypassing distributor networks in UAE hospitality clusters.
Within the integrated farming tier, Almarai Company and National Agricultural Development Company exemplify upstream control strategies stabilizing margin exposure against imported feed volatility. Arla Foods AmbA represents the reliability-focused export archetype, anchoring ambient UHT positioning where local fresh supply interruptions create volume opportunities. Among value-added specialists, NADEC occupies a position between mass-market scale and artisan positioning in fermented and strained yogurt segments.
| Leading Market Players |
|---|
| Saudia Dairy and Foodstuff Company (SADAFCO) |
| Arla Foods AmbA |
| Almarai Company |
| AlRawabi Dairy Company |
| Groupe Lactalis |
| Nestlé SA |
| National Agricultural Development Company (NADEC) |
| Fonterra Co-operative Group |
| Danone SA |
| Others |
Pricing and Supply Chain Analysis
Feed-to-retail scale economies at Almarai and NADEC concentrate supply-side power among integrated Saudi operators, compressing price floors for import-dependent packagers while elevating premium tiers for cold-chain-compliant chilled segments. This structural asymmetry between captive milk supply and feed-cost-exposed competitors anchors pricing stratification across Gulf markets.
Pricing Analysis
Foodservice buyers anchor pricing stratification across premium, standard, and economy tiers in Middle East dairy markets. Certification grade under SFDA halal protocols and cold-chain integrity separate premium chilled formats from ambient UHT mass-market positioning. Price erosion runs through Egyptian border trade channels where pouch-packed products compete on unit economics alone. Small-format retailers and informal wholesalers exhibit highest price sensitivity; Dubai hospitality clusters with centralized procurement cooperatives demonstrate lowest sensitivity due to operational standardization requirements.
Supply Chain Analysis
Saudi Arabia and the UAE anchor integrated dairy processing capacity across the Middle East, with Jordan and Qatar drawing from cross-border supply for fresh milk shortfalls. Alfalfa and soybean meal imports from North and South American suppliers feed captive desert farming operations. Single-source vulnerability concentrates in chilled distribution networks where temperature-controlled logistics lack redundant capacity. Distribution runs through Jebel Ali re-export hubs for ambient UHT formats entering Levant and African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle East dairy sits in early-cycle expansion as foodservice professionalization and SFDA compliance mandates accelerate adoption of premium chilled categories and certified halal formats.
For Market Incumbents: Shield margin structures by deepening upstream control over feed supply contracts and halal-certified culture banks before competitor replication accelerates. SFDA shelf-life labeling mandates threaten mid-tier processors lacking cold-chain capex capacity; priority investment in refrigerated transport fleets and warehouse automation secures compliance differentiation in Saudi urban retail corridors. For New Entrants and Emerging Players: SFDA halal certification fast-tracks for dairy enzymes and starter cultures open white-space penetration in fermented product lines where documentation infrastructure barriers limit incumbent supplier flexibility. Egyptian border trade channels with pouch-format positioning offer most penetrable volume entry; direct wholesale relationships with informal retailers bypass distributor markups that compress margins in formal supermarket networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with validated ESL membrane filtration capabilities bridging UHT stability and fresh sensory credentials. Long-term viability over a five-to-ten-year horizon rests on cold-chain infrastructure ownership rather than brand equity alone. Watch for inflection in Dubai hospitality procurement consolidation rates as direct processor agreements displace traditional distributor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | SFDA shelf-life mandates require refrigerated transport fleet investments to extend distribution reach beyond ambient UHT dominance. |
| Halal Certification Program Investment | Documented culture banks and enzyme traceability secure supply continuity under tightening SFDA slaughter-protocol extensions. |
| Direct Foodservice Procurement Agreements | Centralized purchasing cooperatives in Dubai and Abu Dhabi hospitality clusters bypass fifteen-to-twenty percent distributor markups. |
| ESL Processing Technology Adoption | Membrane filtration and advanced pasteurization bridge mass-market UHT and premium chilled segments for margin expansion. |
| Pouch Format Market Development | Flexible packaging economics serve price-sensitive Egyptian and Yemeni border trade channels underserved by premium carton suppliers. |
Research Methodology
A standing panel of dairy processing executives, cold-chain logistics operators, SFDA regulatory affairs specialists, and UAE hospitality procurement directors provided ongoing calibration across primary fieldwork and secondary validation. Trade data from Saudi customs authorities, SFDA enforcement bulletins, MOHAP fortification compliance records, and Tetra Pak packaging shipment disclosures anchored bottom-up volume estimates against top-down market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, packaging format, distribution channel, and end-user concentration dimensions. CAGRs derived from trend extrapolation of historical trade flows and adoption curves for ESL processing technology. Feed-cost volatility indices and hospitality procurement consolidation rates served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued SFDA enforcement intensity and Gulf agricultural subsidy redirection toward processed imports; material deviation in halal certification timelines or water scarcity policy would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement patterns and foodservice procurement centralization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
US Cheese Market
Dairy Products
Africa Yogurt Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
A2 Milk Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Yogurt Drink Market
Dairy Products
South America Dairy Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Global Butter Market
Dairy Products
North America Milk Powder Market
Dairy Products
Butter and Margarine Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Cream Powder Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Parmesan Cheese Market