
 Ghee Market | 2026-2036
Ghee Market Size, Share, and Industry Trends Forecast 2026-2036
Ghee Market Analysis
Modern trade and e-commerce platforms is reconfiguring how ghee reaches end consumers in India. Amul leverages its cooperative federation structure to sustain pan-India cold chain coverage. Britannia Industries anchors its ghee portfolio within broader dairy diversification, competing against regional specialists. Mother Dairy controls Delhi-NCR distribution density through exclusive retail tie-ups.
Ghee is clarified butter produced by heating butter to remove water and milk solids, yielding a fat content exceeding 99% with a smoke point near 250°C, rendering it suitable for high-temperature cooking and shelf-stable storage in tropical climates. Organic ghee commands widening shelf space in health stores as consumers prioritize residue-free dairy sourcing. Glass jar packaging dominates premium positioning, while pouch formats penetrate price-sensitive rural markets where unit economics favor lower per-gram costs.
FSSAI mandates govern ghee composition and labeling across India, with BIS standards further specifying Reichert-Meissl and Polenske values for fat authenticity verification. The EU's EFSA dairy hygiene protocols shape export eligibility for Indian processors targeting European diaspora retail channels. Stakeholders must monitor evolving adulteration detection technologies and certification costs that will determine which processing scales remain viable.
Market Dynamics
India's FSSAI adulteration crackdown is forcing processors to rebuild supply chains around certified sourcing, compressing margins for unverified traders while rewarding integrated dairies with laboratory testing capabilities.
Growth Catalysts
- Urban premiumization:India's metropolitan households are displacing conventional clarified butter with A2 and organic variants, creating price-tier expansion opportunities for processors with breed-traceable herds.
- Processed food integration:South Asian snack and confectionery manufacturers are expanding ghee procurement for industrial formulations, anchoring B2B volume growth.
- Export protocol alignment:EFSA dairy hygiene standards are reshaping eligibility for Indian processors targeting European diaspora retail channels, filtering out sub-scale operators.
Market Restraints
- Feed cost volatility:Indian dairy farmers face fluctuating fodder prices that compress milk fat yields, transmitting input instability to ghee processors.
- Regional supply concentration:Gujarat and Maharashtra cooperatives control disproportionate clarified butter output, creating geographic vulnerability for buyers outside their distribution radius.
- Plant-based substitution:Coconut oil and refined palm oil formulations are capturing price-sensitive institutional buyers in South Asian commercial kitchens.
Strategic Opportunities
- Direct-to-consumer channels:E-commerce platforms are opening shelf access for artisanal ghee producers previously locked out of modern trade slotting.
- Functional positioning:Ayurvedic wellness applications are creating premium pricing power for processors with documented butyric acid and conjugated linoleic acid content.
- PLI scheme leverage:India's production-linked incentive framework for food processing is subsidizing cold chain infrastructure investments that extend shelf-stable dairy fat distribution.
Industry Challenges
- Laboratory capacity scarcity:FSSAI-mandated Reichert-Meissl and Polenske testing requires specialized chemists that smaller processors struggle to recruit and retain.
- Packaging format transition:Glass jar premium positioning demands capital-intensive filling lines that conflict with rural market pouch economics, forcing parallel production systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghee Market |
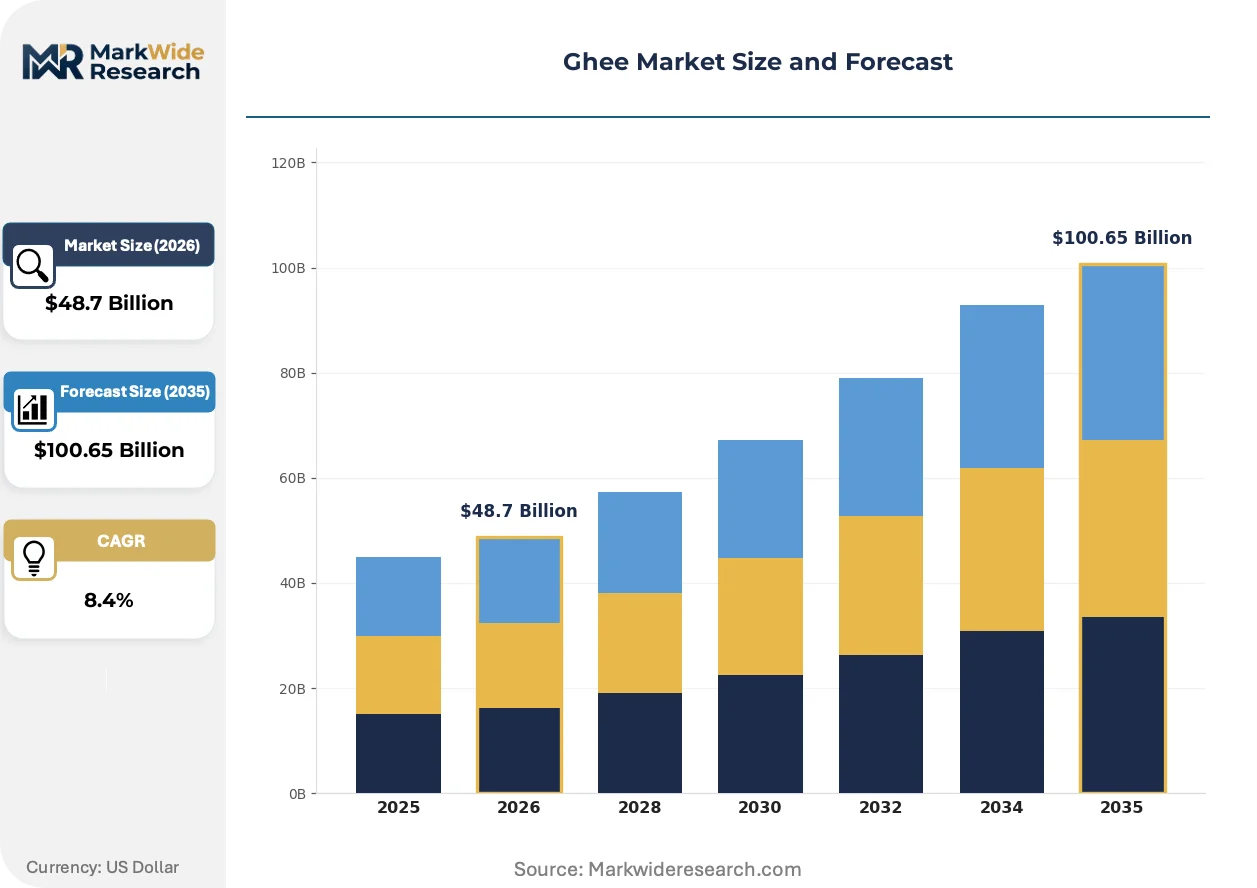
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clarified Butter, Organic Ghee, Grass-Fed Ghee, A2 Ghee Packaging Type: Glass Jar, Plastic Container, Pouch, Tin Can Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops End User: Households, Food Service Providers, Restaurants, Food Manufacturers |
| Companies Covered | Patanjali, Britannia Industries, Amul, Karnataka Milk Federation, Milkfood Limited, Mother Dairy, Verka, Nestle, Parag Milk Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghee Market Emerging Trajectories
Traceability infrastructure and certification protocols are reshaping competitive position in clarified butter, separating integrated operators from commodity traders.
Blockchain-enabled supply chain tracking is digitizing herd-to-jar documentation for premium A2 and organic ghee lines. Indian cooperatives with federated data systems are deploying these tools fastest. The technology is digitizing audit trails that FSSAI inspectors now expect, compressing verification timelines from weeks to hours.
India's BIS standards revision for dairy fat authenticity is tightening Reichert-Meissl value tolerances. Processors must retest legacy inventory and reformulate blends that previously passed. Export-oriented facilities are responding by installing in-house gas chromatography units to preempt rejection at port.
Subscription-based replenishment models are capturing urban household demand for shelf-stable clarified butter. E-commerce platforms with predictive logistics are displacing monthly bazaar purchases. This pattern concentrates most visibly in Bangalore and Hyderabad's tech-employed consumer segments.
Ghee Market Segmentation
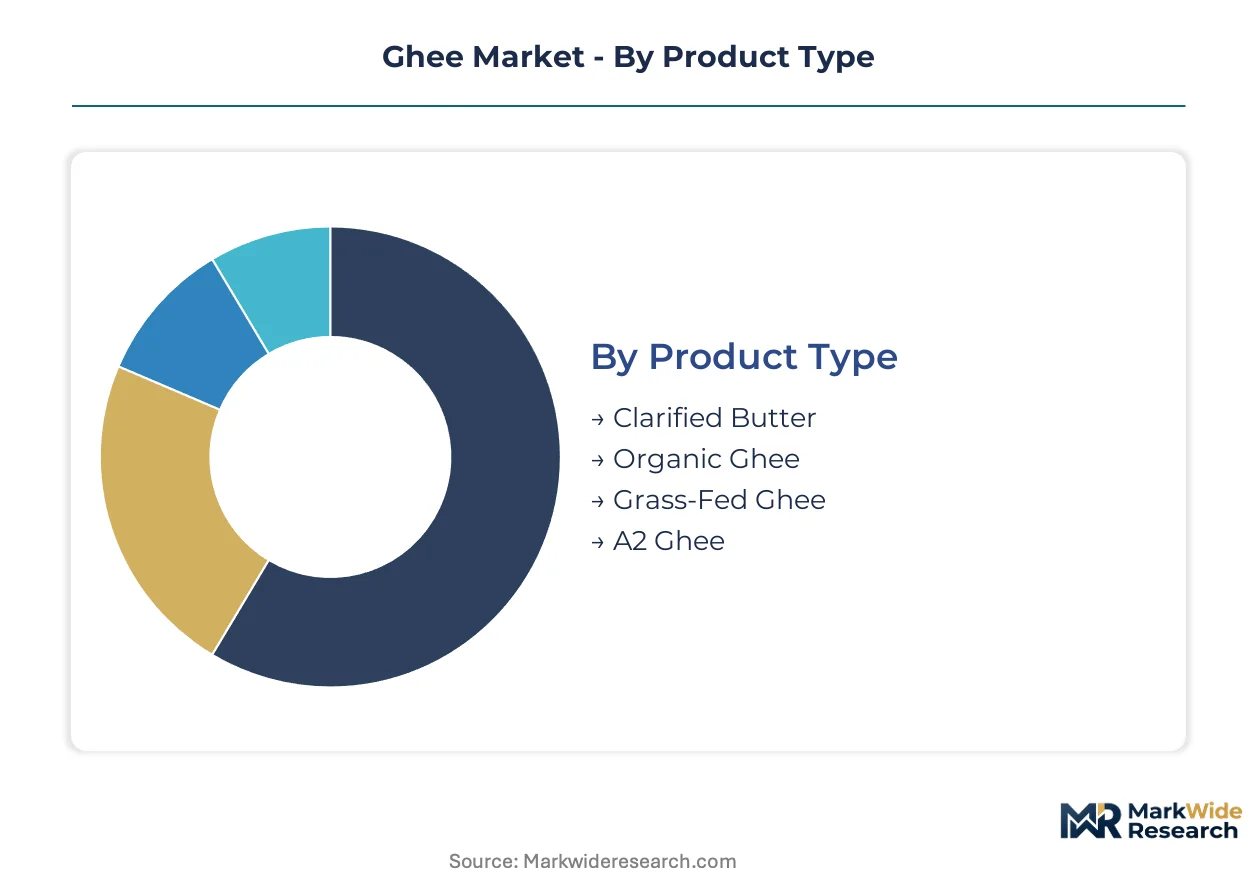
Segmentation in the ghee market determines procurement priorities and margin architecture for processors. Breed traceability, packaging format economics, and channel access requirements create distinct operational profiles that reward specialized over generalized supply strategies.
Product Type:
After-sales service intensity varies sharply across product tiers, with certified organic and A2 variants demanding laboratory documentation support that conventional clarified butter does not require.
- Clarified Butter:Standard heat-reduced butterfat with milk solids removed, typically 99.5% fat content. Volume concentrates in South Asian commercial kitchens and price-sensitive urban households where unit cost governs procurement decisions.
- Organic Ghee:Derived from cattle raised on certified residue-free fodder without synthetic inputs. Demand clusters in metropolitan health-conscious segments across India and European diaspora channels where EFSA hygiene documentation is mandatory.
- Grass-Fed Ghee:Sourced from pasture-raised cattle with elevated conjugated linoleic acid profiles. Niche positioning in functional wellness applications with limited processing scale.
- A2 Ghee:Produced exclusively from indigenous breeds carrying the A2 beta-casein allele. Premium tier expansion in India's urban households with documented herd genetics.
By volume, Clarified Butter leads. By growth pace, A2 Ghee is expanding most quickly.
Packaging Type:
Cost tier separation in packaging determines capital allocation between premium positioning and mass-market penetration strategies.
- Glass Jar:Inert material preserving flavor integrity with premium shelf presence. Dominates urban modern trade and export channels where breakage costs are offset by price realization.
- Plastic Container:Polymer-based formats balancing durability with moderate cost. Captures mid-tier household demand in India's tier-2 cities where refrigeration access is inconsistent.
- Pouch:Flexible laminate structures minimizing per-gram packaging cost. Rural market penetration in Maharashtra and Gujarat cooperative distribution networks.
- Tin Can:Metal containment for institutional bulk procurement. Food service and restaurant segments in South Asian commercial hubs.
By volume, Pouch leads. By growth pace, Glass Jar is climbing the fastest.
Distribution Channel:
Channel configuration dictates working capital cycles and traceability documentation requirements for ghee processors.
- Supermarkets:Organized retail with standardized slotting fees and cold chain requirements. Modern trade expansion in Bangalore and Hyderabad drives branded ghee placement.
- Online Retail:Platform-mediated direct-to-consumer fulfillment with predictive logistics. Subscription models capture tech-employed urban segments seeking replenishment automation.
- Health Stores:Curated retail emphasizing certified organic and functional positioning. Ayurvedic wellness positioning commands premium markup in metropolitan clusters.
- Specialty Shops:Ethnic retail serving diaspora communities in Europe and North America. FSSAI export certification and EFSA alignment determine shelf eligibility.
By volume, Supermarkets lead. By growth pace, Online Retail is gaining share fastest.
End User:
Customer type segmentation separates stable institutional demand from fluctuating household purchasing patterns.
- Households:Individual consumers purchasing for domestic culinary use. India's urban premiumization trend displaces conventional clarified butter with certified variants.
- Food Service Providers:Institutional catering operations with volume procurement and specification consistency requirements. BIS standard compliance for fat authenticity verification is mandatory.
- Restaurants:Commercial kitchens prioritizing smoke point performance and shelf stability. South Asian cuisine establishments in Gulf Cooperation Council cities anchor import demand.
- Food Manufacturers:Industrial processors integrating ghee into snack and confectionery formulations. Processed food integration in South Asia drives B2B volume expansion.
By volume, Households lead. By growth pace, Food Manufacturers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors Indian ghee export flows to Gulf Cooperation Council markets, while the Delhi-Mumbai Industrial Corridor underpins cold chain distribution density across the subcontinent.
India
FSSAI adulteration crackdowns are compressing margins for unverified traders while rewarding integrated dairies with laboratory testing capabilities. India's PLI scheme for food processing subsidizes cold chain infrastructure that extends shelf-stable dairy fat distribution. Gujarat and Maharashtra cooperatives control disproportionate clarified butter output, creating geographic concentration around Anand and Kolhapur processing clusters.
Pakistan
Urban households in Karachi and Lahore are displacing conventional clarified butter with premium variants as disposable incomes rise. The Pakistan Standards and Quality Control Authority enforces composition standards for dairy fats that align with Codex Alimentarius frameworks. Punjab Province dominates production gravity, with Faisalabad and Multan anchoring buffalo milk sourcing for traditional ghee manufacture.
Bangladesh
Processed food manufacturers in Dhaka are expanding ghee procurement for confectionery and snack formulations. The Bangladesh Standards and Testing Institution governs labeling requirements for clarified butter products in domestic commerce. Chittagong Port facilitates import substitution dynamics as local processors scale capacity to serve regional demand.
United Arab Emirates
MOHAP dairy hygiene protocols filter import eligibility for Indian and Pakistani processors targeting expatriate retail channels. Dubai's Jebel Ali Port serves as the Gulf's primary re-export hub for South Asian ghee shipments. The emirate's hypermarket chains concentrate demand for premium packaged clarified butter among South Asian diaspora households.
Saudi Arabia
SFDA food safety standards mandate detailed compositional documentation for clarified butter entering the Kingdom's retail sector. Riyadh and Jeddah anchor consumption clusters where institutional catering operations drive volume procurement. The Saudi Food Security Strategy incentivizes backward integration into dairy processing to reduce import dependency.
Ghee Market Vendor Landscape
On the supply side, the industry is consolidating around cooperative federations with captive milk sourcing and integrated cold chain infrastructure. Processing capacity concentrates in western and northern India where dairy cooperative density is highest. Three archetypes dominate: cooperative giants with pan-India distribution, regional dairy specialists with state-level procurement lock-in, and FMCG conglomerates leveraging existing retail slotting. Competitive moves center on breed-traceable herd expansion and laboratory certification investments that satisfy tightening FSSAI protocols.
Among cooperative federations, Amul and Karnataka Milk Federation exemplify the scale-driven archetype with federated procurement structures. Britannia Industries occupies a position within the FMCG-anchored tier, leveraging existing modern trade relationships. Mother Dairy represents the regional density model with concentrated distribution control in the Delhi-NCR corridor.
| Leading Market Players |
|---|
| Patanjali |
| Britannia Industries |
| Amul |
| Karnataka Milk Federation |
| Milkfood Limited |
| Mother Dairy |
| Verka |
| Nestle |
| Parag Milk Foods |
| Others |
Supply Flow & Price Mechanics
FSSAI adulteration crackdowns compress margins for unverified traders while rewarding integrated dairies with laboratory testing capabilities, determining both tier spreads and supply chain configuration. Feed cost volatility transmits directly to price realization, with Gujarat and Maharashtra cooperatives commanding premium positioning through captive sourcing.
Pricing Analysis
Volume-discount tiering separates A2 and organic certification grades from conventional clarified butter, with breed-traceable documentation commanding substantial markups. Price differentiation rests on FSSAI compliance status and cold chain infrastructure access, not brand equity alone. Cost compression in rural pouch segments intensifies as regional cooperatives scale filling capacity. Food manufacturers exhibit lowest price sensitivity due to specification lock-in, while household procurement in tier-3 cities remains most elastic.
Supply Chain Analysis
Export-control regimes through EFSA dairy hygiene protocols filter Indian processor eligibility for European diaspora channels, restricting flows to facilities with in-house gas chromatography. Supply concentrates in India, Pakistan, and Bangladesh, with Gujarat and Punjab cooperatives anchoring buffalo milk sourcing. Raw material dependencies center on fodder availability, veterinary pharmaceutical residues, and packaging laminate structures. Single-source vulnerability concentrates around Anand and Kolhapur processing clusters. Distribution runs through cooperative federations with exclusive retail tie-ups and platform-mediated e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability infrastructure is reconfiguring ghee as a platform economy where data interoperability between cooperatives, regulators, and e-commerce platforms determines competitive position.
For Market Incumbents: Pre-empt FSSAI laboratory capacity scarcity by recruiting specialized chemists ahead of BIS standards revision enforcement. Anchor backward integration into breed-traceable herd expansion to defend against A2 specialist entrants. Lock in exclusive retail tie-ups in Delhi-NCR and Bangalore before platform disintermediation accelerates. For New Entrants and Emerging Players: Artisanal producers locked out of modern trade slotting represent the most penetrable entry point, with direct-to-consumer subscription models capturing tech-employed urban segments in Hyderabad and Pune. Target health store channels with documented butyric acid and conjugated linoleic acid content for Ayurvedic wellness positioning. Deploy predictive logistics partnerships with established e-commerce platforms to bypass cooperative distribution density. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated dairies with captive milk sourcing and laboratory certification capabilities. Long-term viability hinges on cold chain infrastructure ownership extending shelf-stable distribution reach. Monitor FSSAI inspector deployment timelines as the inflection signal for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Breed-Traceable Herd Expansion | A2 certification unlocks premium tier pricing power in India's metropolitan households. |
| In-House Laboratory Investment | Gas chromatography units preempt FSSAI rejection and EFSA port-of-entry barriers. |
| Direct-to-Consumer Platform Launch | Subscription models displace monthly bazaar purchases in Bangalore's tech-employed segments. |
| Cold Chain Infrastructure Scale-Up | PLI scheme subsidies extend shelf-stable dairy fat distribution into tier-2 cities. |
| Blockchain Traceability Deployment | Federated data systems compress FSSAI verification timelines from weeks to hours. |
Methodological Framework
Operator-level perspectives from dairy cooperative managers, FSSAI compliance officers, modern trade category buyers, and e-commerce platform supply chain heads anchored the qualitative base. Secondary validation drew from FSSAI notification records, BIS standards documentation, EU EFSA dairy hygiene protocols, and cooperative federation annual reports. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Scenario-bracketing around feed cost volatility and regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions spanned product certification tier, packaging format economics, distribution channel access requirements, and end-user procurement patterns. CAGRs derived from trend extrapolation with elasticity adjustments for urban premiumization and processed food integration. Forecast inputs incorporated PLI scheme subsidy disbursement trajectories and cold chain infrastructure buildout timelines.
Macroeconomic conditions sit as an overlay; deviation in fodder price indices, dairy farmer credit availability, and diaspora disposable income would shift the trajectory. Cross-checking against customs export volume data and cooperative federation procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Flavoured Milk Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Goat Milk Market
Dairy Products
Lactose Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
GCC Casein Market