
 Cheese Color Market | 2026-2036
Cheese Color Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Color Market Analysis
Foodservice cheese applications are repositioning toward visually consistent, heat-stable color solutions as quick-service chains standardize global menu aesthetics. Chr. Hansen Holding A/S leverages its microbial fermentation expertise to dominate natural colorant supply to European dairy cooperatives. DDW The Color House anchors North American distribution through direct relationships with Wisconsin cheddar processors. Sensient Technologies Corporation competes on application-specific formulations that survive UHT and extrusion cooking.
Cheese color comprises food-grade pigments and dyes added to milk curd or finished cheese to achieve standardized visual identity across production batches. Annatto extracts, carotenoid concentrates, and turmeric oleoresins constitute the primary natural pigment classes, with dosage rates typically ranging from 0.1 to 20 grams per 1,000 pounds of milk depending on target hue intensity and cheese variety. The natural type segment leads absolute volume as retail private-label programs mandate recognizable ingredient declarations, while the foodservice application channel generates premium pricing for customized color-matching services that protect brand consistency across multinational restaurant footprints.
FDA color additive regulations and USDA dairy grading standards jointly determine permissible pigment sources and maximum usage levels for domestically produced and imported cheese products. The EU's EFSA-led re-evaluation of food dyes under the reauthorization program creates compliance complexity for exporters serving both North American and European manufacturing customers. Stakeholders must monitor evolving natural color stability under extended shelf-life packaging conditions and decide between captive extraction investments and specialized supplier partnerships.
Market Dynamics
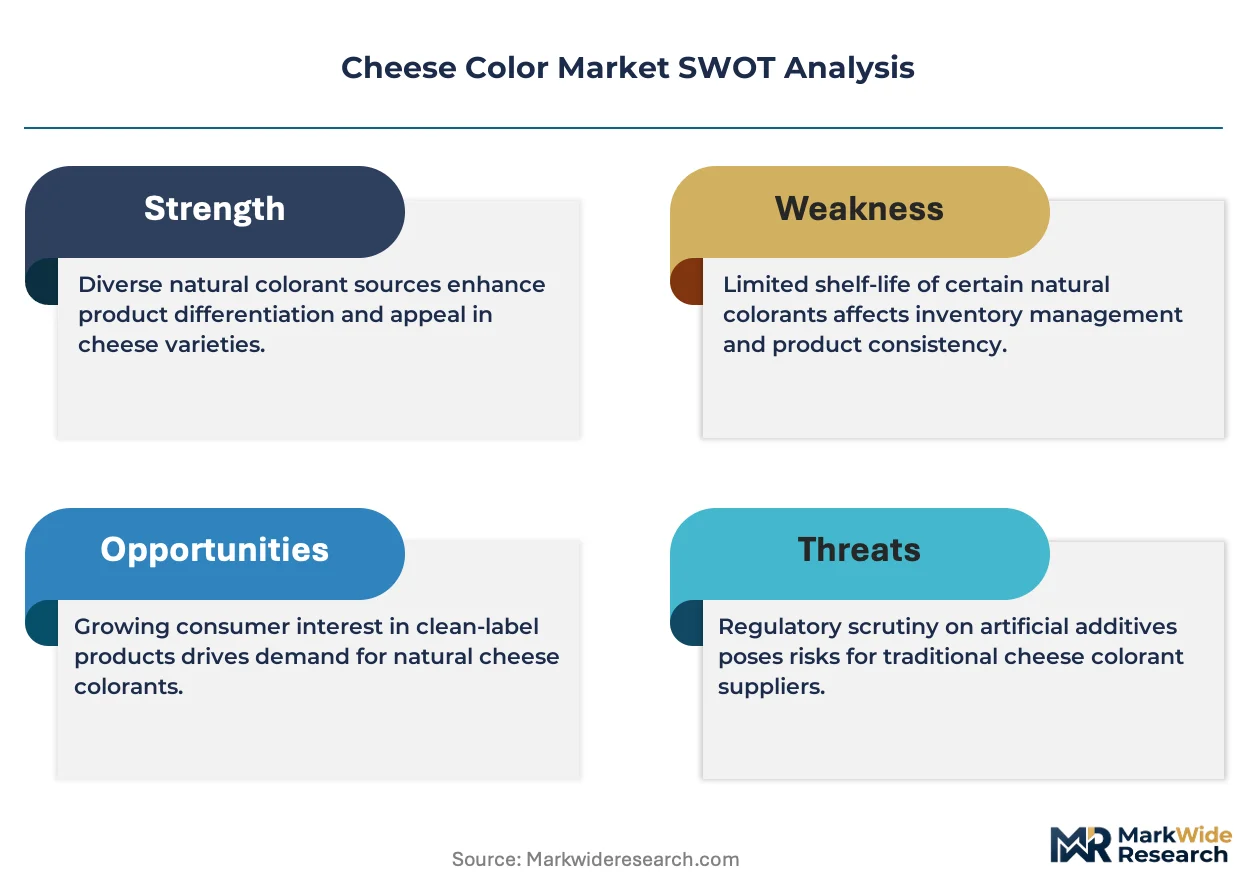
Clean-label reformulation mandates from FDA and EFSA are compressing synthetic dye usage windows, forcing dairy processors to rebuild colorant supply chains around annatto and carotenoid fermentation sources.
Growth Catalysts
- USDA Grading Standards:Federal visual quality requirements for cheddar and colby cheeses create baseline demand for standardized colorant dosing across commercial production batches.
- Quick-service chains:Global menu standardization programs at multinational restaurant operators require heat-stable, batch-consistent color solutions for cheese sauce and shred applications.
- Microbial fermentation:Bioprocess advances in carotenoid biosynthesis are reducing extraction yield variability that has historically constrained natural colorant supply security.
Market Restraints
- Annatto seed supply volatility:Weather-dependent harvests in Latin American growing regions create input cost instability that squeezes processor margins during poor yield seasons.
- EFSA reauthorization timelines:Pending safety reviews for certain carotenoid additives under the EU food additive reauthorization program generate regulatory uncertainty for exporters.
- Technical color stability gaps:Natural pigments exhibit faster degradation under LED retail lighting and modified-atmosphere packaging compared to synthetic alternatives.
Strategic Opportunities
- Plant-based cheese analogs:Dairy-alternative manufacturers lack established colorant protocols, creating first-mover advantage for suppliers offering application-specific formulation support.
- Direct-to-processor digital platforms:E-procurement channels bypass traditional distributor markups and enable real-time color-matching technical service for mid-size creameries.
- Extended shelf-life packaging:Oxygen-scavenging film technologies paired with stabilized natural pigments open premium export markets for aged cheese varieties.
Industry Challenges
- Fermentation scale-up expertise:Microbial pigment production requires bioprocess engineering talent that remains concentrated in pharmaceutical and enzyme manufacturing sectors.
- Dual-jurisdiction compliance:Exporters serving both FDA and EFSA jurisdictions must maintain parallel formulation databases and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Color Market |
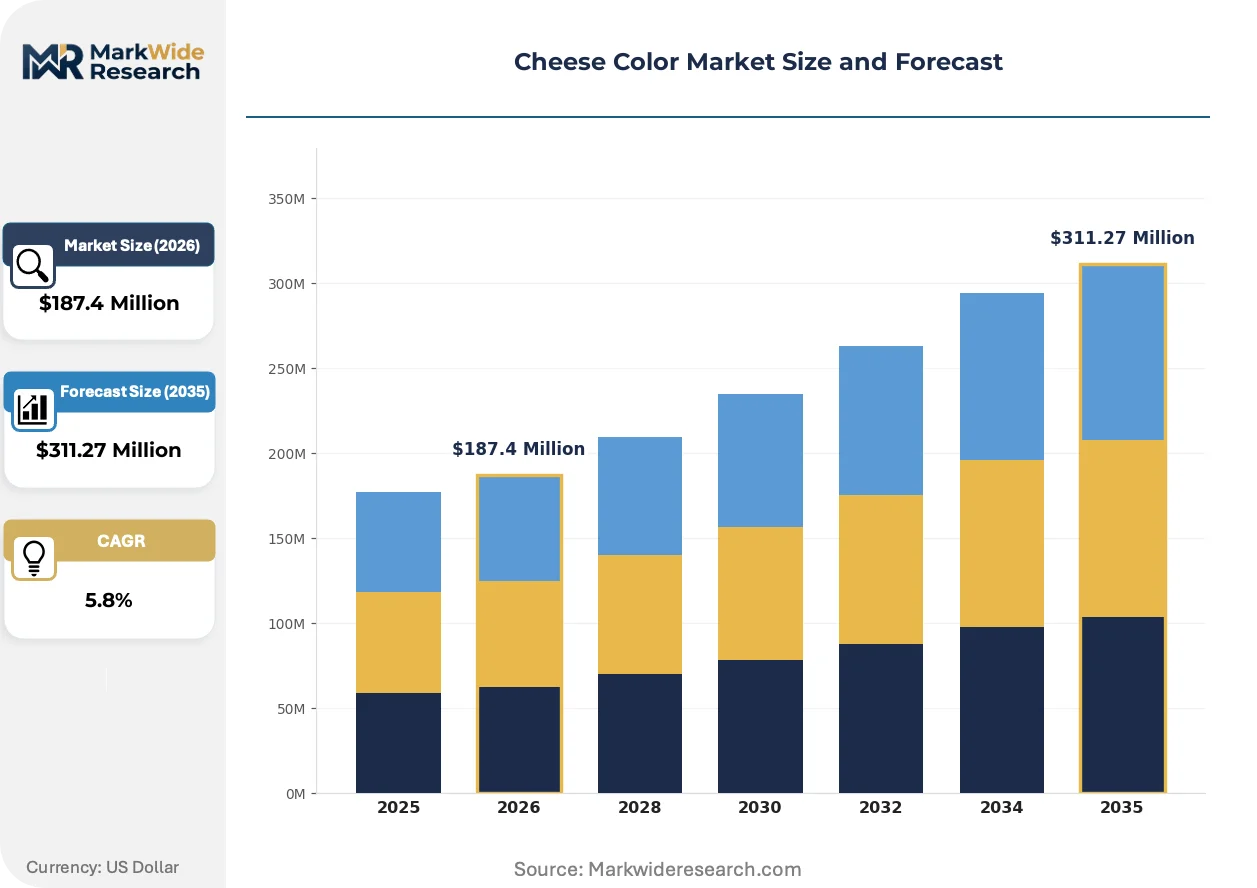
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Artificial, Non-Dairy, Organic Application: Processing, Retail, Foodservice, Snacks Form: Liquid, Powder, Block, Paste Distribution Channel: Online, Retailers, Distributors, Wholesalers |
| Companies Covered | Chr. Hansen Holding A/S, DDW The Color House, Sensient Technologies Corporation, BASF SE, Arla Foods, Saputo Inc., DSM-Firmenich, Kalsec Inc., Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Color Market Emerging Trajectories
Bioprocess engineering and packaging science are converging to solve the stability limitations that have historically constrained natural pigment adoption in long-life cheese applications.
Precision fermentation for carotenoid production is converging with dairy industry demand for cost-competitive natural alternatives. European dairy cooperatives are piloting microbial-derived beta-carotene at commercial scale. This convergence is compressing the price premium between fermentation-based and agricultural-extraction supply chains.
EFSA's systematic re-evaluation of food additives under the 2020-2025 reauthorization program is accelerating reformulation timelines. Manufacturers serving EU export markets face compressed product development cycles. Aged cheddar and gouda producers with significant European sales are prioritizing annatto-only formulations ahead of pending determinations.
Retail private-label programs are mandating single-ingredient colorant declarations that disqualify blended or chemically modified solutions. Mass-market grocers in Germany and the United Kingdom are rejecting turmeric-annatto combinations. Wisconsin and California processors report specification tightening from national supermarket chains seeking simplified ingredient panels for consumer-facing packaging.
Cheese Color Market Segmentation
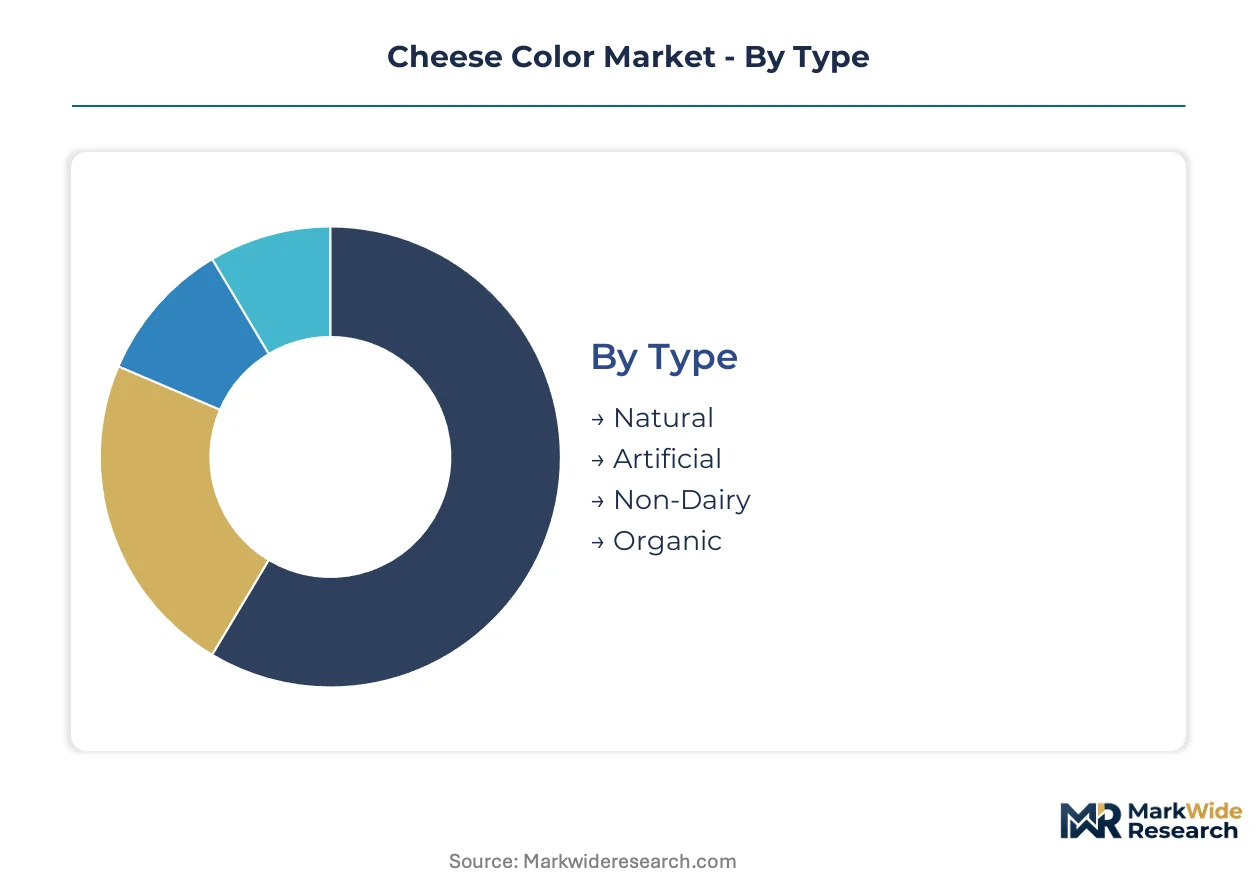
Cheese color segmentation tracks procurement patterns across dairy processors navigating clean-label mandates and export compliance complexity. Category boundaries matter because formulation choices lock processors into specific regulatory pathways and shelf-life performance profiles.
Type:
Natural pigments command volume leadership while artificial alternatives retain niche premium positioning in specific export corridors.
- Natural:Annatto extracts, carotenoid concentrates, and turmeric oleoresins dominate procurement from Wisconsin and California dairy clusters. FDA labeling scrutiny intensifies procurement of these solutions as processors face retail private-label mandates for recognizable ingredient declarations.
- Artificial:Synthetic dyes persist in foodservice applications requiring extreme heat stability and batch-to-batch consistency across multinational quick-service footprints. EFSA reauthorization timelines compress remaining usage windows for certain synthetic carotenoids.
- Non-Dairy:Plant-based cheese analog manufacturers lack established colorant protocols, creating formulation partnerships with suppliers offering application-specific technical support.
- Organic:Certified organic annatto and turmeric sources command supply premiums from processors targeting EU organic dairy export quotas.
Mature deployment sits with Natural. Newer deployment is concentrated in Non-Dairy.
Application:
Channel requirements diverge sharply between industrial scale and customized color-matching services.
- Processing:Bulk cheddar and colby manufacturers standardize dosing at 0.1 to 20 grams per 1,000 pounds of milk to meet USDA visual grading requirements across commercial production batches.
- Retail:Private-label programs mandate single-ingredient colorant declarations that disqualify blended solutions, with German and UK mass-market grocers rejecting turmeric-annatto combinations.
- Foodservice:Global menu standardization at multinational restaurant operators requires heat-stable, batch-consistent color solutions for cheese sauce and shred applications.
- Snacks:Extruded cheese products and flavored coatings demand pigments surviving UHT processing and high-shear manufacturing environments.
Volume concentration centers on Processing. Premium pricing attaches to Foodservice.
Form:
Physical format selection determines dosing precision, storage economics, and integration with existing dairy processing equipment.
- Liquid:Standard annatto suspensions integrate directly into milk vats with minimal equipment modification, dominating high-volume cheddar operations.
- Powder:Dried carotenoid concentrates offer extended shelf stability and reduced shipping costs for export-oriented processors.
- Block:Concentrated solid formats serve small-batch artisan creameries with limited liquid handling infrastructure.
- Paste:High-viscosity formulations target specific cheese varieties requiring localized color distribution without milk phase dispersion.
Liquid formats anchor mainstream deployment. Powder is gaining share fastest in export-focused supply chains.
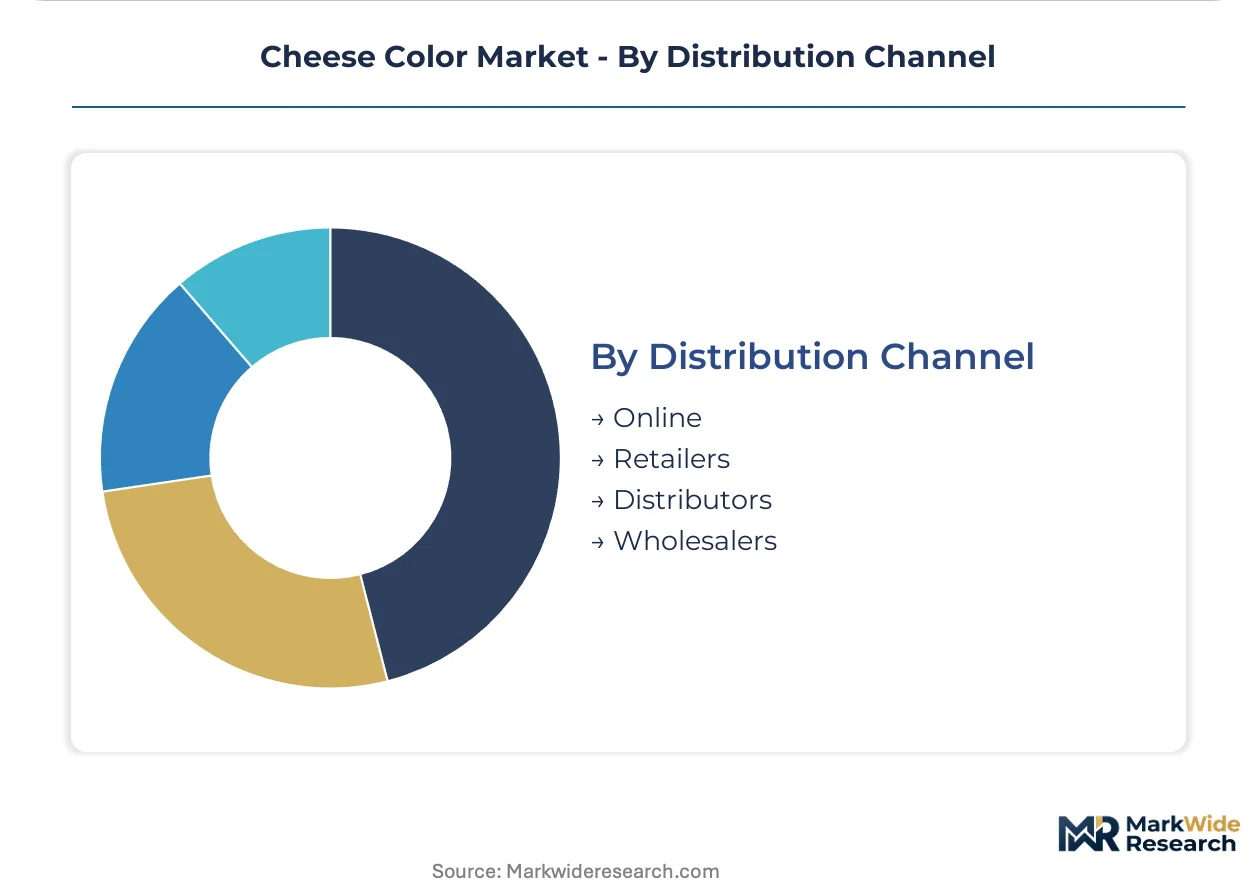
Distribution Channel:
Procurement pathway selection reflects processor scale, technical service requirements, and margin pressure tolerance.
- Online:E-procurement platforms enable real-time color-matching technical service for mid-size creameries bypassing traditional distributor markups.
- Retailers:Direct relationships with ingredient suppliers anchor North American distribution through Wisconsin cheddar processor corridors.
- Distributors:Regional chemical and dairy ingredient distributors maintain inventory buffers against annatto seed harvest volatility from Latin American growing regions.
- Wholesalers:Volume aggregators serve smaller processors lacking direct supplier relationships or technical formulation support needs.
Established procurement runs through Distributors. Online channels represent the steepest expansion trajectory among mid-tier processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Wisconsin and California concentrate North American cheese color procurement through tax-advantaged dairy processing infrastructure. These zones anchor global supply chain decisions for annatto-based natural colorants.
United States
Wisconsin's dairy processing corridor drives annatto extract procurement as FDA labeling scrutiny intensifies for clean-label reformulation. USDA grading standards for cheddar and colby cheeses mandate standardized colorant dosing across commercial batches. California's Central Valley dairy clusters are expanding natural colorant storage capacity ahead of retail private-label specification tightening.
Germany
Mass-market grocers in Germany reject turmeric-annatto colorant combinations under single-ingredient declaration mandates. EFSA's food additive reauthorization program creates compliance complexity for exporters serving both German and North American manufacturing customers. Bavarian dairy cooperatives are piloting microbial-derived beta-carotene at commercial scale.
Netherlands
Dutch dairy exporters prioritize annatto-only formulations ahead of pending EFSA determinations on carotenoid additives. The country's central position in EU dairy trade routes positions Rotterdam-area processors as formulation standard-setters for cross-border compliance. Friesland's aged cheese producers are investing in oxygen-scavenging film technologies paired with stabilized natural pigments.
Brazil
Weather-dependent annatto seed harvests in Latin American growing regions create input cost instability that squeezes processor margins during poor yield seasons. Brazilian agricultural regulators monitor harvest forecasts to anticipate supply disruptions. São Paulo-state distributors maintain inventory buffers against harvest volatility for export-oriented processors.
India
FSSAI standards for dairy product labeling are aligning with clean-label trends observed in European and North American export markets. Indian dairy processors lack established colorant protocols for plant-based cheese analogs, creating formulation partnership opportunities. Gujarat's dairy cooperatives are evaluating direct-to-processor digital platforms for technical service bypassing traditional distributor markups.
Cheese Color Market Vendor Landscape
Top-tier vendors anchor microbial fermentation expertise, while agricultural extraction specialists compete on cost stability. The vendor base spans biotechnology firms with pharmaceutical bioprocess heritage and legacy natural extract houses with Latin American supply relationships. Three archetypes dominate: fermentation-based pigment innovators, annatto seed procurement consolidators, and application-specific formulation service providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as natural color stability gaps compress synthetic dye usage windows.
Within the fermentation tier, Chr. Hansen Holding A/S and DSM-Firmenich exemplify bioprocess engineering capabilities transferred from enzyme manufacturing sectors. DDW The Color House occupies a position among North American distribution anchors with direct relationships across Wisconsin cheddar processor corridors. Sensient Technologies Corporation represents the application-specific formulation archetype, with technical services targeting heat-stable solutions for UHT and extrusion cooking environments.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DDW The Color House |
| Sensient Technologies Corporation |
| BASF SE |
| Arla Foods |
| Saputo Inc. |
| DSM-Firmenich |
| Kalsec Inc. |
| Givaudan |
| Others |
Supply Flow & Price Mechanics
Captive annatto seed procurement in Latin American growing regions anchors both supply security and margin control for processors navigating weather-driven harvest volatility. Wisconsin and California dairy clusters leverage direct supplier relationships to compress distributor markups while securing batch-consistent colorant volumes for USDA-graded production runs.
Pricing Analysis
Short lead-time premiums attach to spot annatto extract purchases during poor harvest seasons in Brazil and Peru, while contract-based offtake agreements command discounts through volume commitments and harvest risk transfer. Price differentiation rests on certification tier — organic annatto commands substantial premiums for EU export quotas — and formulation complexity, with heat-stable UHT solutions priced above standard liquid suspensions. Cost compression in synthetic dye alternatives is intensifying because EFSA reauthorization timelines compress remaining usage windows. Mid-size creameries exhibit highest price sensitivity due to limited storage infrastructure and inability to forward-contract seed harvests.
Supply Chain Analysis
Returns and refurbishment flows are minimal in cheese colorant supply chains given food-grade contamination protocols, though packaging material recovery programs operate at major Wisconsin distribution hubs. Geographic supply concentrates in Brazil, Peru, and India for annatto seeds, with fermentation-derived carotenoids emerging from Danish and Dutch bioprocess facilities. Raw material dependencies include Bixa orellana seed harvests, microbial fermentation feedstocks, and turmeric oleoresin extraction from Indian rhizome processors. Single-source vulnerability runs through Latin American weather patterns that trigger harvest volatility and input cost spikes. Distribution runs through regional chemical distributors maintaining inventory buffers against harvest uncertainty, though direct-to-processor digital platforms are gaining share among mid-tier creameries seeking technical service bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as fermentation-based pigment innovators pursue captive seed procurement and agricultural extract houses build in-house bioprocess capabilities. The upstream lever driving this consolidation is microbial fermentation scale-up expertise concentrated in pharmaceutical manufacturing sectors.
For Market Incumbents: Deploy fermentation capacity expansion to defend against agricultural extraction competitors capturing share through cost stability. Prioritize backward integration into annatto seed procurement in Brazil to neutralize weather-driven margin volatility. Secure USDA and EFSA dual-jurisdiction compliance documentation ahead of reauthorization determinations to lock in multinational processor relationships. For New Entrants and Emerging Players: Capture formulation partnership opportunities in plant-based cheese analogs where established protocols remain undeveloped. Target India's Gujarat dairy cooperatives with direct-to-processor digital platforms offering real-time color-matching technical service. Lead with application-specific UHT and extrusion-stable solutions that incumbent agricultural extract houses lack technical capacity to replicate. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by biotechnology firms seeking dairy industry application channels for pharmaceutical-derived bioprocess capabilities. Long-term viability favors fermentation-based pigment innovators with demonstrated commercial scale and regulatory dossier depth. Watch EFSA reauthorization determinations on carotenoid additives as inflection indicator for synthetic-to-natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Procurement | Captive annatto supply from Brazilian growing regions neutralizes harvest volatility squeezing processor margins. |
| Microbial Fermentation Scale-Up | Bioprocess engineering transfer from pharmaceutical sectors compresses natural colorant price premiums toward extraction parity. |
| Dual-Jurisdiction Compliance Investment | Parallel FDA and EFSA documentation systems protect export market access amid reauthorization uncertainty. |
| Direct-to-Processor Digital Platform Launch | E-procurement channels bypass traditional distributor markups for mid-size Wisconsin and California creameries. |
| Oxygen-Scavenging Packaging Partnership | Extended shelf-life film technologies paired with stabilized pigments open premium aged cheese export corridors. |
Methodological Framework
Document review covered FDA color additive regulations, EFSA food additive reauthorization filings, USDA dairy grading standards, and customs trade data for annatto seed imports, complemented by interviews with dairy processing procurement directors, natural colorant supplier technical sales leads, and regulatory affairs specialists at multinational food manufacturers. Primary fieldwork engaged Wisconsin cheddar processors, California Central Valley dairy clusters, and Bavarian cooperative fermentation pilots. Secondary validation drew from SEC 10-K disclosures of listed ingredient suppliers, dairy industry association technical bulletins, and patent filings for microbial carotenoid production. Bottom-up volume estimates from processor consumption patterns were triangulated against top-down market sizing from trade flow analysis.
Cross-referencing historical price series for annatto extracts against expert panel assessments of fermentation cost curves anchored the analytical framework across the analysis window. Segmentation dimensions modeled include colorant type, application channel, physical form, and distribution pathway, with regulatory jurisdiction treated as an overlay dimension given dual FDA-EFSA compliance complexity. CAGRs were derived from regression analysis of processor procurement volumes against clean-label mandate implementation timelines. Industry-specific forecast inputs incorporated annatto seed harvest yield projections from Brazilian agricultural monitoring and bioprocess capacity expansion announcements from European fermentation facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA reauthorization determinations, microbial fermentation yield breakthroughs, and plant-based cheese analog adoption velocity. Forecasts reflect documented assumptions regarding regulatory timeline adherence and seed harvest pattern stability. Practitioners should monitor Latin American weather indices, EFSA scientific opinion publication schedules, and quick-service chain global menu standardization announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Disposable Curd Cups Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Buttermilk Powder Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
Flavoured Milk Market
Dairy Products
Gruyere Market
Dairy Products
A2 Milk Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Low Fat Yogurt Calories Market