
 India Major Home Appliances Market | 2026-2036
India Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
India Major Home Appliances Market Foresight
The capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is reorganizing competitive tiers across India. LG Electronics leverages captive compressor production to sustain margin resilience against input volatility. Voltas anchors its position through deep channel control in western India, while IFB Industries specializes in front-loading washing machines for premium urban households. Haier competes aggressively on smart-feature bundling, extending its reach into connected-home ecosystems.
Major home appliances comprise electrically powered durables designed for domestic climate control, food preservation, fabric care, and cooking, typically operating on 230V/50Hz single-phase supply with rated capacities from 150L to 600L for refrigeration and 1-ton to 2.5-ton for cooling. These products serve residential and commercial end users requiring standardized performance under tropical humidity conditions. Refrigerators occupy the largest value share due to universal household necessity, while air conditioners represent the fastest-expanding category as urban heat intensifies and BEE star-rating upgrades push replacement cycles. The smart-technology feature segment commands premium positioning, though energy-efficiency variants dominate volume through government-subsidized distribution schemes.
BIS certification under the Compulsory Registration Scheme governs safety and electromagnetic compatibility for all imported and domestically manufactured units. The Bureau of Energy Efficiency mandates star-label compliance, directly influencing procurement decisions in institutional and hospitality tenders. State-level electricity regulators in Maharashtra and Tamil Nadu enforce demand-side management programs that subsidize efficient appliance uptake. Stakeholders must monitor evolving BEE notification schedules and state-level rebate harmonization to align inventory planning with compliance deadlines.
Market Dynamics
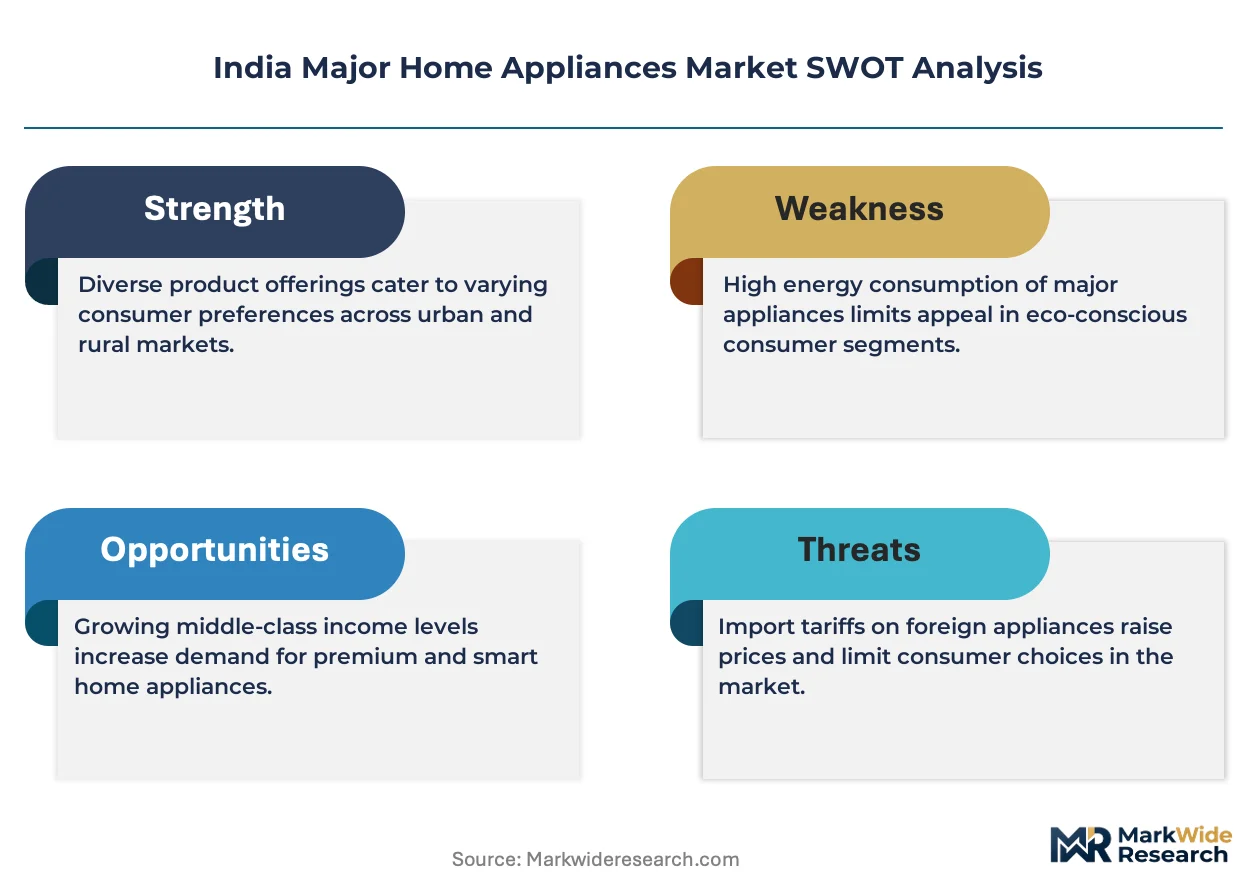
BIS energy-efficiency mandates and BEE star-rating upgrades are compressing replacement cycles while forcing manufacturers to absorb compliance costs that assembly-dependent competitors struggle to pass through. This regulatory pressure is reorganizing competitive tiers between integrated producers and import-reliant assemblers.
Growth Catalysts
- Urban nuclear family expansion:Maharashtra, Gujarat, and Tamil Nadu residential complexes are accelerating refrigerator and air conditioner procurement as household formation rates outpace national averages.
- BEE star-rating protocols:Institutional and hospitality tenders now mandate minimum efficiency grades, locking in demand for certified products and disqualifying uncertified imports.
- State-level electricity subsidies:Maharashtra and Tamil Nadu demand-side management programs directly reduce consumer acquisition costs for efficient appliances, stimulating volume uptake.
Market Restraints
- Copper and compressor import dependency:Domestic production capacity for critical refrigeration components remains concentrated in China and Thailand, exposing margins to currency and logistics volatility.
- Freight cost inflation:Container rates from Southeast Asian component hubs to Nhava Sheva and Mundra ports have structurally elevated landed costs for non-integrated assemblers.
- Skilled technician scarcity:Installation and after-sales service networks in tier-2 and tier-3 cities face persistent gaps in refrigerant handling certification and inverter technology repair capability.
Strategic Opportunities
- Tier-2 city penetration acceleration:Appliance ownership rates in Madhya Pradesh, Rajasthan, and Uttar Pradesh secondary cities trail southern states by 15-20 percentage points, creating expansion headroom.
- Smart-home ecosystem convergence:Wi-Fi-enabled appliance control and energy monitoring interfaces are opening premium positioning for manufacturers bundling connected features with core climate products.
- PLI scheme for white goods:The government's production-linked incentive framework for air conditioners and LED components is reducing effective capital costs for domestic manufacturing expansion.
Industry Challenges
- BIS certification timeline compression:Compulsory Registration Scheme testing queues at designated laboratories routinely extend product launch schedules by 8-12 weeks.
- Refrigerant transition complexity:Phasedown obligations under the Kigali Amendment are forcing simultaneous R-410A inventory management and R-32 production line retooling.
- Channel credit risk concentration:Traditional electronics retail networks in western India operate on extended payment terms that strain working capital for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Major Home Appliances Market |
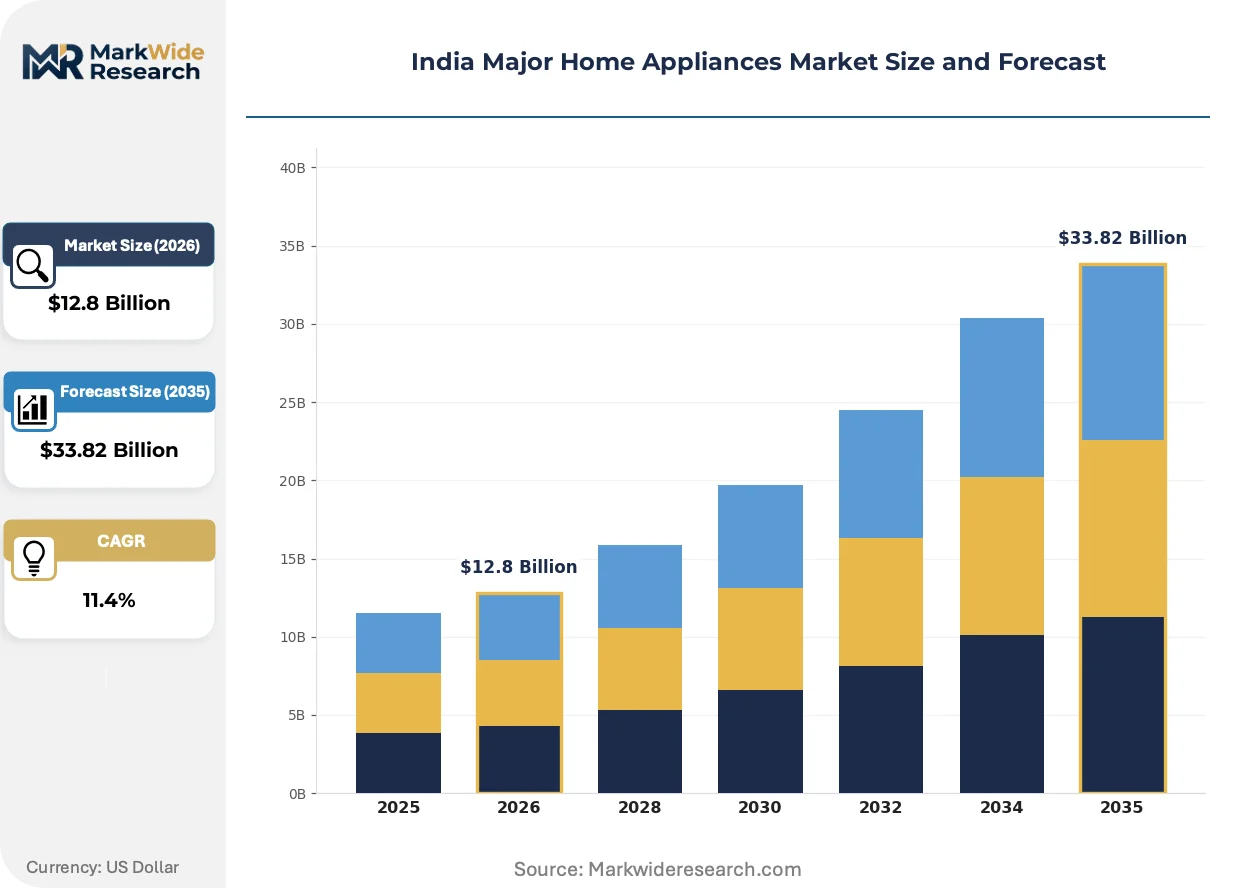
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Microwave Ovens End User: Residential, Commercial, Institutional, Hospitality Sales Channel: Online, Offline, Direct Sales, Retail Technological Feature: Smart Technology, Energy Efficiency, Multi-Functionality, IoT Enabled |
| Companies Covered | Godrej Appliances, Bosch, LG Electronics, Haier, Panasonic, Samsung, Voltas, IFB Industries, Whirlpool, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Major Home Appliances Market Shifts & Advancements
Inverter compressor technology is rewriting efficiency benchmarks across refrigeration and cooling categories, compressing the performance gap between premium and mid-tier product lines. This shift is forcing pricing realignment and compressing legacy fixed-speed model viability.
Variable-speed drive systems are fragmenting traditional segmentation boundaries. Urban households in Bengaluru and Hyderabad are adopting inverter refrigerators at rates previously associated only with air conditioner purchases. The technology is fragmenting the historical correlation between price tier and efficiency performance, enabling mid-market brands to challenge established premium positioning.
The Bureau of Energy Efficiency's 2023 notification tightening star-label thresholds has triggered accelerated model turnover. Manufacturers must retire sub-3-star inventory ahead of enforcement deadlines. Western India distribution channels are absorbing the highest compliance friction as Voltas and regional competitors reconfigure warehouse stock.
Buying patterns are rotating toward energy-efficiency-certified products even where upfront premiums persist. Tier-2 city consumers in Tamil Nadu and Gujarat now prioritize BEE labels over brand heritage in retail environments. This preference shift is compressing traditional brand loyalty cycles and elevating private-label and secondary brand competitiveness in subsidized distribution schemes.
India Major Home Appliances Market Segmentation
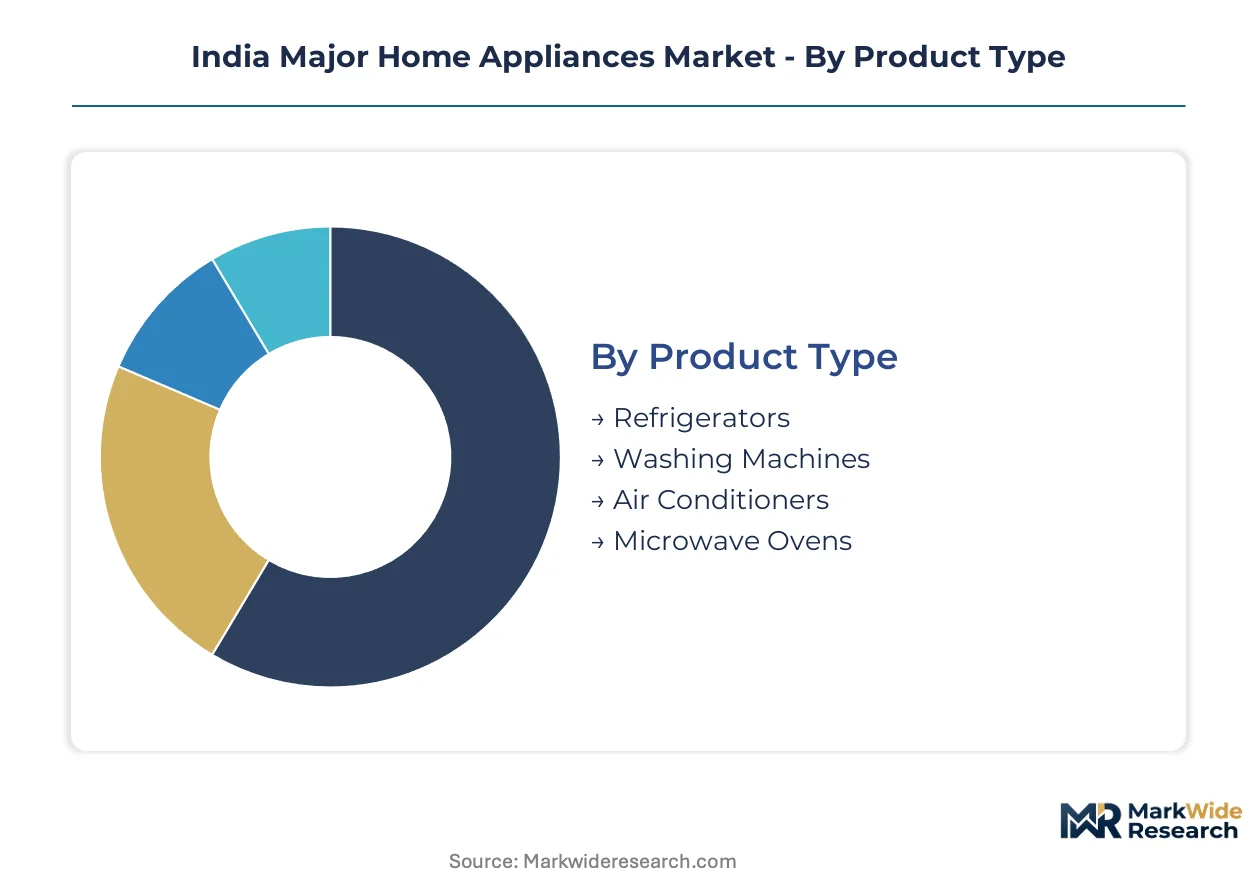
Segmentation in India's major home appliances market reveals how regulatory mandates, channel evolution, and technology adoption reshape procurement patterns. Manufacturers must calibrate portfolio depth across product categories while navigating divergent compliance requirements and distribution economics.
Product Type:
Domestic demand concentrates in climate-control and food-preservation categories, with Maharashtra and Tamil Nadu residential complexes driving refrigerator and air conditioner procurement. Export-oriented assembly remains limited due to BIS Compulsory Registration Scheme requirements.
- Refrigerators:Units span 150L to 600L capacity ratings operating on 230V/50Hz single-phase supply. Demand clusters in Gujarat and Tamil Nadu tier-2 cities where nuclear family formation outpaces national averages and BEE star-rating upgrades compress replacement cycles.
- Air Conditioners:Cooling capacity ranges from 1-ton to 2.5-ton configurations designed for tropical humidity conditions. Western India channels absorb the highest compliance friction as BEE notification deadlines force accelerated model turnover and inventory reconfiguration.
- Washing Machines:Front-loading configurations target premium urban households in Bengaluru and Hyderabad.
- Microwave Ovens:Compact and convection variants serve space-constrained Mumbai and Delhi kitchens.
Refrigerators command the established base. The steepest expansion runs through air conditioners.
End User:
Cost-tier stratification separates premium urban households from price-sensitive institutional bulk procurement, with margin structures varying dramatically across customer types.
- Residential:Nuclear families in Maharashtra, Gujarat, and Tamil Nadu drive volume through replacement cycles and first-time ownership in tier-2 cities. BEE star-rating protocols now override brand heritage in retail purchase decisions.
- Commercial:Small enterprises and food-service operators require durable units under extended warranty terms. Channel credit risk concentrates in western India retail networks operating on extended payment terms.
- Institutional:Government and educational tenders mandate minimum efficiency grades, locking demand for certified products.
- Hospitality:Hotels and serviced apartments prioritize energy monitoring interfaces and connected features for operational cost control.
Residential segments anchor volume throughput. Hospitality applications are gaining share fastest through premium positioning.
Sales Channel:
Volume concentration tilts toward offline retail in tier-2 and tier-3 cities, while metro markets accelerate online migration with installation service bundling.
- Online:E-commerce platforms capture urban metro demand through financing schemes and exchange offers. Logistics networks struggle with last-mile installation and refrigerant handling certification gaps in secondary cities.
- Offline:Electronics retail chains and exclusive brand outlets dominate Gujarat and Maharashtra. Extended payment terms strain working capital for smaller manufacturers competing against established channel controllers.
- Direct Sales:Project-based institutional and hospitality procurement bypasses retail markup.
- Retail:General trade and multi-brand outlets serve price-sensitive segments in Madhya Pradesh and Rajasthan.
Offline channels command the established base. Online penetration shows the steepest expansion trajectory in metro markets.
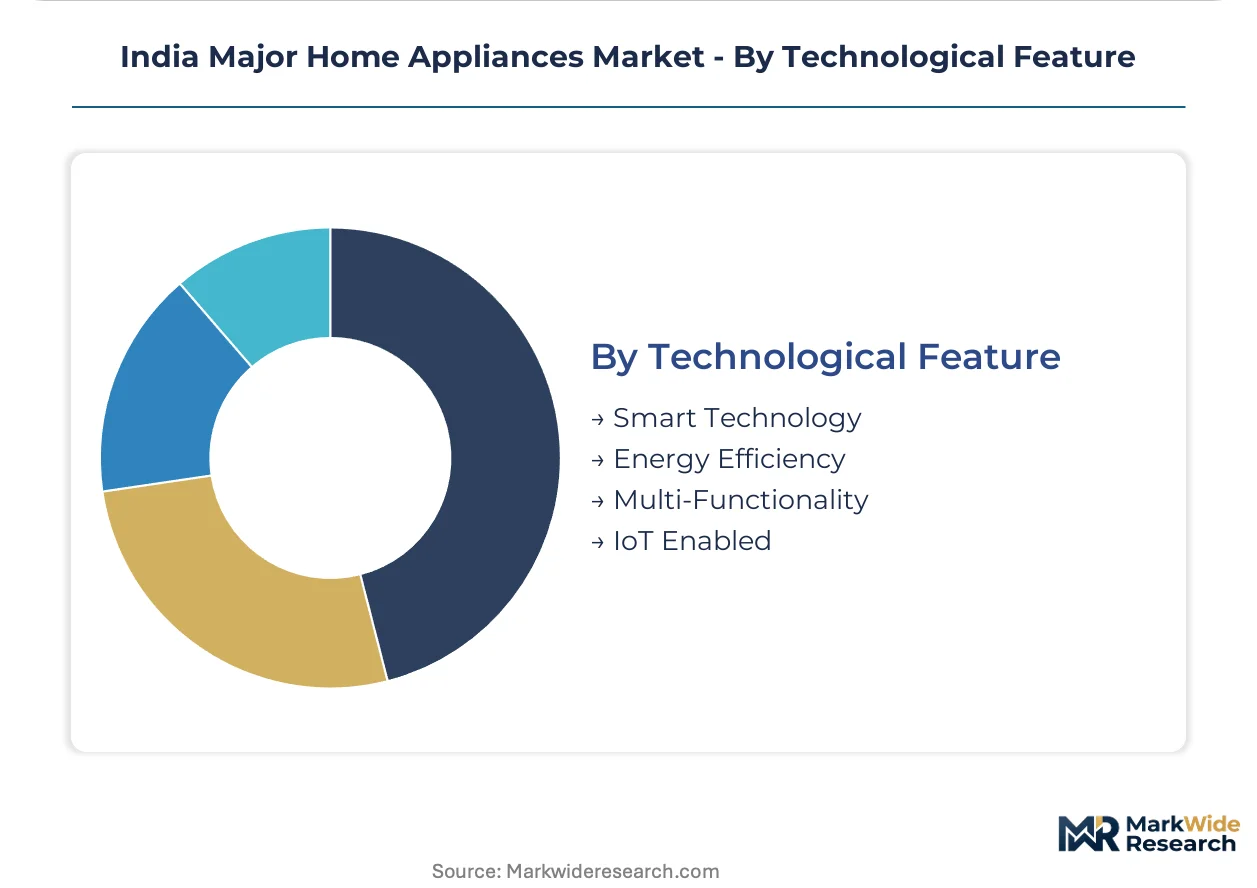
Technological Feature:
Margin differentiation separates certified efficiency variants from premium smart-feature bundles, with subsidy programs distorting volume distribution toward compliance-grade products.
- Smart Technology:Wi-Fi-enabled control and energy monitoring interfaces open premium positioning. Bengaluru and Hyderabad households adopt connected refrigerators at rates previously associated only with air conditioner purchases.
- Energy Efficiency:BEE star-rated variants dominate volume through Maharashtra and Tamil Nadu demand-side management subsidies. Tier-2 city consumers now prioritize labels over brand heritage.
- Multi-Functionality:Combined cooking and convection modes target space-constrained urban kitchens.
- IoT Enabled:Connected-home ecosystem integration extends manufacturer reach beyond core appliance sales.
Energy efficiency variants command the established base. Smart technology applications are climbing the fastest through premium urban adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in western Indian states where channel density and manufacturing scale create margin advantages unavailable to eastern markets. Maharashtra and Gujarat command premium positioning through established distribution infrastructure and BIS compliance clustering. Tamil Nadu and Karnataka operate as secondary pricing nodes with accelerating volume but compressed premiums.
Maharashtra
Mumbai and Pune residential complexes drive refrigerator and air conditioner procurement as nuclear family formation outpaces national averages. BEE star-rating protocols now override brand heritage in retail purchase decisions across Mumbai electronics chains. The Maharashtra State Electricity Distribution Company demand-side management programs subsidize efficient appliance uptake in tier-2 cities including Nagpur and Nashik.
Gujarat
Ahmedabad and Surat industrial corridors anchor western India distribution networks with the deepest channel control in the country. BIS Compulsory Registration Scheme testing facilities cluster in Gandhinagar, compressing certification timelines for regional manufacturers. The state electricity regulator enforces rebate harmonization that directly reduces consumer acquisition costs for certified products in Vadodara and Rajkot.
Tamil Nadu
Chennai and Coimbatore manufacturing bases supply compressor components and finished assemblies to southeastern markets. Tamil Nadu Generation and Distribution Corporation demand-side management programs stimulate volume uptake through institutional tender mandates. Tier-2 cities including Madurai and Tiruchirappalli accelerate appliance penetration at rates trailing southern state averages by narrowing margins.
Karnataka
Bengaluru and Hyderabad households adopt inverter refrigerators and connected appliances at rates previously associated only with air conditioner purchases. The state's electricity regulator enforces minimum efficiency grades for government procurement, locking demand for certified products. Mysuru and Hubli-Dharwad distribution networks face refrigerant handling certification gaps that constrain after-sales service expansion.
Delhi-NCR
The National Capital Territory concentrates hospitality and institutional procurement requiring energy monitoring interfaces for operational cost control. Delhi Electricity Regulatory Commission programs subsidize efficient appliance uptake in neighboring Noida and Gurugram residential developments. Ghaziabad and Faridabad retail networks operate on extended payment terms that strain working capital for smaller manufacturers competing against established channel controllers.
India Major Home Appliances Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the India market, with integrated manufacturers sustaining margin resilience against input volatility while assembly-dependent competitors struggle to pass through compliance costs. The vendor base fragments across captive compressor producers, regional channel controllers, and smart-feature bundlers. Three archetypes dominate: integrated component manufacturers with backward control over critical inputs, western India channel specialists with deep retail penetration, and connected-home ecosystem extenders. Competitive moves concentrate on capacity expansion under the PLI scheme for white goods and strategic partnerships for refrigerant transition compliance.
Among integrated manufacturers with captive compressor production, LG Electronics and Voltas occupy positions that exemplify margin resilience against copper and logistics volatility. Haier represents the connected-home ecosystem archetype, while IFB Industries anchors premium urban specialization. Godrej Appliances and Whirlpool sit within the established domestic fabricator tier with broad portfolio coverage across climate-control and food-preservation categories.
| Leading Market Players |
|---|
| Godrej Appliances |
| Bosch |
| LG Electronics |
| Haier |
| Panasonic |
| Samsung |
| Voltas |
| IFB Industries |
| Whirlpool |
| Others |
Supply & Pricing Matrix
BIS Compulsory Registration Scheme certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb testing costs that compress margins while enabling certified players to command premiums over uncertified imports. This dual gating mechanism stratifies the market into compliance-validated tiers where BEE star-rating performance directly determines pricing power in institutional tenders.
Pricing Analysis
The customization-premium spread between configured-to-order inverter systems and standard fixed-speed models runs wide across residential procurement. Three-tier pricing structure across premium, standard, and economy levels tracks BEE certification grade and compressor sourcing strategy, with integrated manufacturers sustaining margin resilience against copper volatility. Pricing pressure stems from freight cost inflation at Nhava Sheva and Mundra ports, squeezing assembly-dependent competitors. Tier-2 city households in Madhya Pradesh and Rajasthan exhibit highest price sensitivity, while hospitality operators in Mumbai and Delhi-NCR prioritize energy monitoring interfaces over upfront cost.
Supply Chain Analysis
China and Thailand anchor compressor component fabrication for Indian refrigeration and cooling assembly. Domestic manufacturing draws from imported copper coils, refrigerant gases, and variable-speed drive controllers, with PLI scheme incentives reducing effective capital costs for air conditioner production expansion. Single-source vulnerability concentrates in Southeast Asian component hubs exposed to currency and logistics volatility. Distribution runs through western India electronics retail chains and exclusive brand outlets, with e-commerce platforms capturing metro demand through installation service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Major Home Appliances Market represents an early-cycle expansion story, with nuclear family formation in tier-2 cities driving replacement and first-time ownership rates that trail southern state averages by narrowing margins.
For Market Incumbents: Compound channel control in Gujarat and Maharashtra through exclusive outlet expansion and technician certification programs that address refrigerant handling gaps. Defend margin position against Haier's smart-feature bundling by accelerating captive compressor capacity under PLI scheme incentives. Prioritize BEE 4-star and 5-star inventory positioning ahead of notification enforcement deadlines that will retire sub-3-star models.
For New Entrants and Emerging Players: Anchor in Madhya Pradesh, Rajasthan, and Uttar Pradesh secondary cities where appliance ownership rates trail Maharashtra and Tamil Nadu by 15-20 percentage points. Target front-loading washing machine segments in Bengaluru and Hyderabad premium households where IFB's specialization has validated pricing power. Pursue direct-to-institutional procurement channels that bypass retail markup and extended payment terms straining smaller competitors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across air conditioner manufacturing as PLI subsidies compress effective equipment costs for domestic fabrication. Long-term viability favors integrated producers with backward control over compressor supply and BIS certification infrastructure. Monitor BEE notification schedules and state-level rebate harmonization as inflection indicators for inventory reconfiguration cycles and working capital stress among assembly-dependent players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production at LG Electronics and Voltas insulates margins against copper import volatility from China and Thailand. |
| Smart-Home Ecosystem Platform Integration | Haier's Wi-Fi-enabled bundling extends manufacturer reach beyond core climate products into connected-home services. |
| PLI Scheme Capacity Expansion | Government production-linked incentives reduce effective capital costs for domestic air conditioner and LED component fabrication. |
| BEE Star-Rating Certification Investment | Testing queue compression at Gandhinagar facilities accelerates product launch timelines against 8-12 week laboratory delays. |
| Tier-2 City Distribution Channel Expansion | Electronics retail penetration in Madhya Pradesh and Rajasthan captures ownership rate convergence with southern state benchmarks. |
Research Methodology
Operator-level perspectives from product development heads at integrated manufacturers, procurement leads at regional assemblers, channel sales directors in western India, and service network managers in tier-2 cities anchored the qualitative base. These primary interviews combined with secondary validation from BEE notification schedules, Maharashtra State Electricity Distribution Company subsidy program documentation, Bureau of Indian Standards CRS testing records, and customs import data for compressor components. Bottom-up demand modeling across refrigerator, air conditioner, washing machine, and microwave categories triangulated against top-down macroeconomic indicators.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, end-user category, sales channel, and technological feature tier. CAGRs derived from replacement cycle compression rates, nuclear family formation trajectories, and BEE star-rating upgrade schedules. Forecast inputs incorporated PLI scheme disbursement timelines, refrigerant transition obligations under Kigali Amendment phasedown, and state-level electricity regulator rebate harmonization patterns.
Material uncertainties — BIS certification timeline extensions, container rate volatility at Southeast Asian hubs, and skilled technician scarcity in refrigerant handling — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and subsidy program continuity. Recalibration cycles align with material shifts in BEE notification schedules, PLI scheme revisions, and state-level demand-side management program expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
North America Electric Fireplace Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Household Appliance Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
US Household Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
United States Major Home Appliances Market