
 Electric Fireplace Market | 2026-2036
Electric Fireplace Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Fireplace Market Analysis
Residential renovation spending is recalibrating demand patterns across the electric fireplace landscape. Glen Dimplex Group leverages its manufacturing scale to dominate European and North American distribution networks. Twin Star Home sustains channel control through big-box retail partnerships and direct-to-consumer platforms. Napoleon anchors its position with technology leadership in flame simulation and heat management systems.
An electric fireplace converts electrical energy into radiant and convective heat through resistive heating elements or infrared quartz tubes, typically operating at 120V or 240V with outputs ranging from 4,000 to 9,000 BTU, while LED or holographic flame effects provide visual ambiance without combustion byproducts. Wall-mounted and insert product types capture the strongest margin pools as consumers prioritize space-efficient installation and existing masonry retrofit compatibility. Infrared technology leads in cold-climate performance, while LED-based systems expand in milder regions where supplemental heating dominates purchase intent.
EPA efficiency guidelines and DOE appliance standards shape minimum performance thresholds for electric heating equipment sold in the United States, while CE marking and EU Ecodesign requirements govern European market access. The EU F-Gas Regulation indirectly influences competitive positioning by restricting refrigerant-based heat pumps in certain retrofit scenarios, channeling demand toward electric resistance and infrared alternatives. Stakeholders must monitor evolving building electrification codes and utility rebate structures that determine total cost of ownership calculations for end users.
Market Dynamics
Building electrification codes and utility rebate structures are compressing the total cost of ownership calculus for residential heating equipment, redirecting retrofit capital toward electric resistance and infrared alternatives.
Growth Catalysts
- EPA Appliance Standards:Minimum efficiency thresholds for electric heating equipment sold in the United States are phasing out legacy resistance models and accelerating infrared quartz adoption.
- Single-Family Housing Retrofits:Residential renovation spending in the United States is channeling demand toward wall-mounted and insert product types compatible with existing masonry.
- EU F-Gas Regulation:Restrictions on refrigerant-based heat pumps in certain European retrofit scenarios are diverting demand toward electric fireplace alternatives.
Market Restraints
- Copper and Semiconductor Input Volatility:Resistive heating elements and LED flame simulation systems face cost pressure from concentrated raw material supply chains.
- Heat Pump Substitution:Cold-climate heat pump performance improvements threaten infrared electric fireplace positioning in primary heating applications.
- DOE Certification Timelines:Extended testing protocols for electric heating equipment create launch delays for new product iterations.
Strategic Opportunities
- Smart Home Integration:Voice control and energy management system convergence with electric fireplace controls opens premium positioning in connected home ecosystems.
- Direct-to-Consumer Channels:Big-box retail partnerships and e-commerce platforms enable margin capture previously allocated to distributor networks.
- Mild-Climate Supplemental Heating:LED-based systems without full heating output are penetrating Sun Belt states where ambiance dominates purchase intent.
Industry Challenges
- Flame Simulation Engineering Talent:Specialized optical design and thermal management expertise remains concentrated among a narrow supplier base.
- CE Marking and UL Certification Parallel Tracks:Dual compliance requirements for North American and European market entry compress development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Fireplace Market |
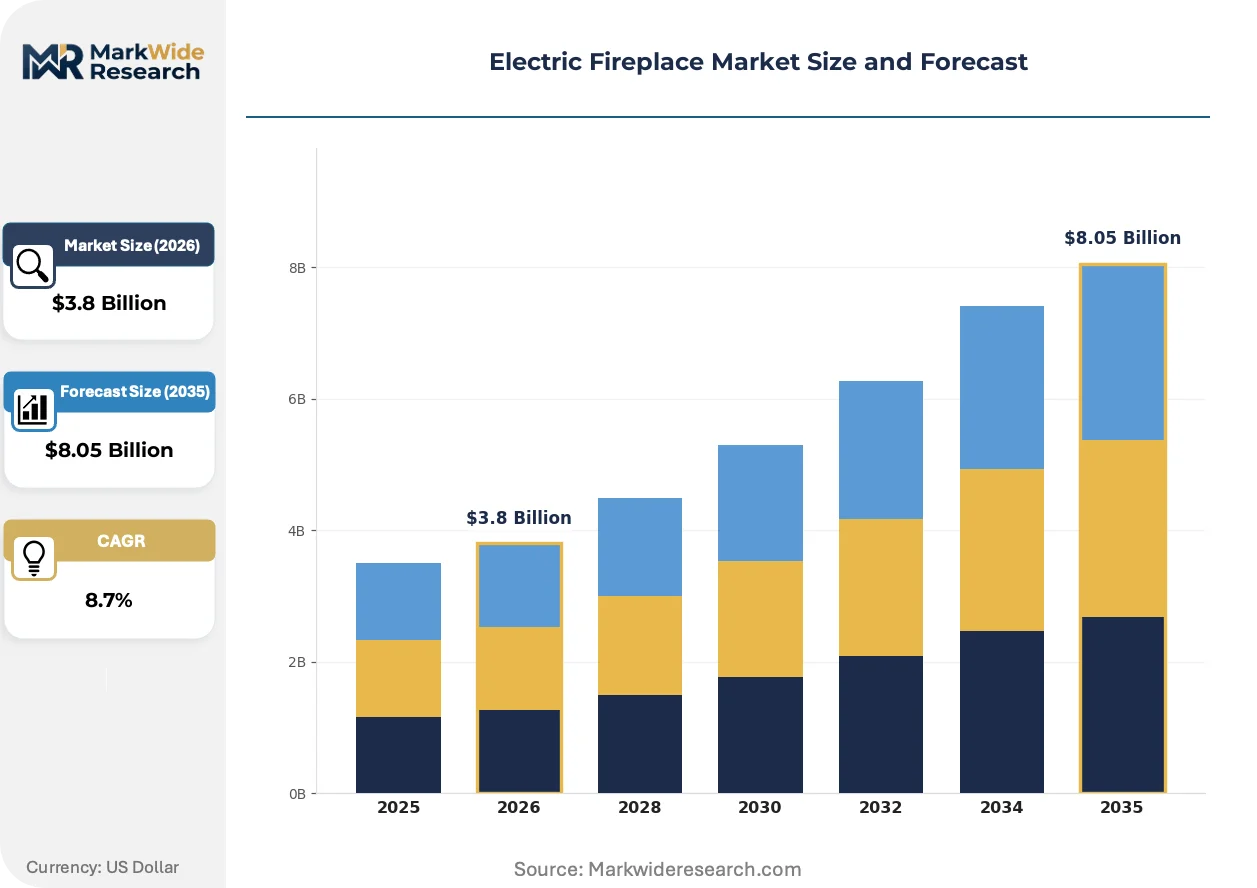
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Insert, Multimedia Technology: Infrared, LED, Traditional, Eco-Friendly End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Glen Dimplex Group, Twin Star Home, Napoleon, Hearth & Home Technologies, Empire Comfort Systems, Amantii Electric Fireplaces, Touchstone Home Products, Modern Flames, BFM Europe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Fireplace Market Emerging Trajectories
Product development is converging on modular, installation-flexible platforms that bridge residential retrofit and new construction specifications while integrating with home energy management infrastructure.
Holographic flame technology is unifying visual realism with programmable thermal output in single chassis designs. High-end residential buyers in cold-climate zones are specifying these systems at accelerating rates. The technology is unifying previously separate aesthetic and functional purchasing decisions into single-transaction specifications.
EU Ecodesign requirements are tightening standby power limits and mandating seasonal efficiency disclosures for electric heating equipment sold in member states. Manufacturers are reconfiguring control electronics and standby circuits to maintain market access. Wall-mounted product categories face the steepest redesign cycles to meet 2027 implementation deadlines.
Buyer preference is fragmenting across installation type rather than brand loyalty, with consumers prioritizing masonry retrofit compatibility and space-efficient mounting over legacy hearth aesthetics. Specialty contractors and interior designers are displacing traditional fireplace retailers as the primary specification influencers. This pattern concentrates in United States metropolitan markets where condominium and townhouse stock dominates housing turnover.
Electric Fireplace Market Segmentation
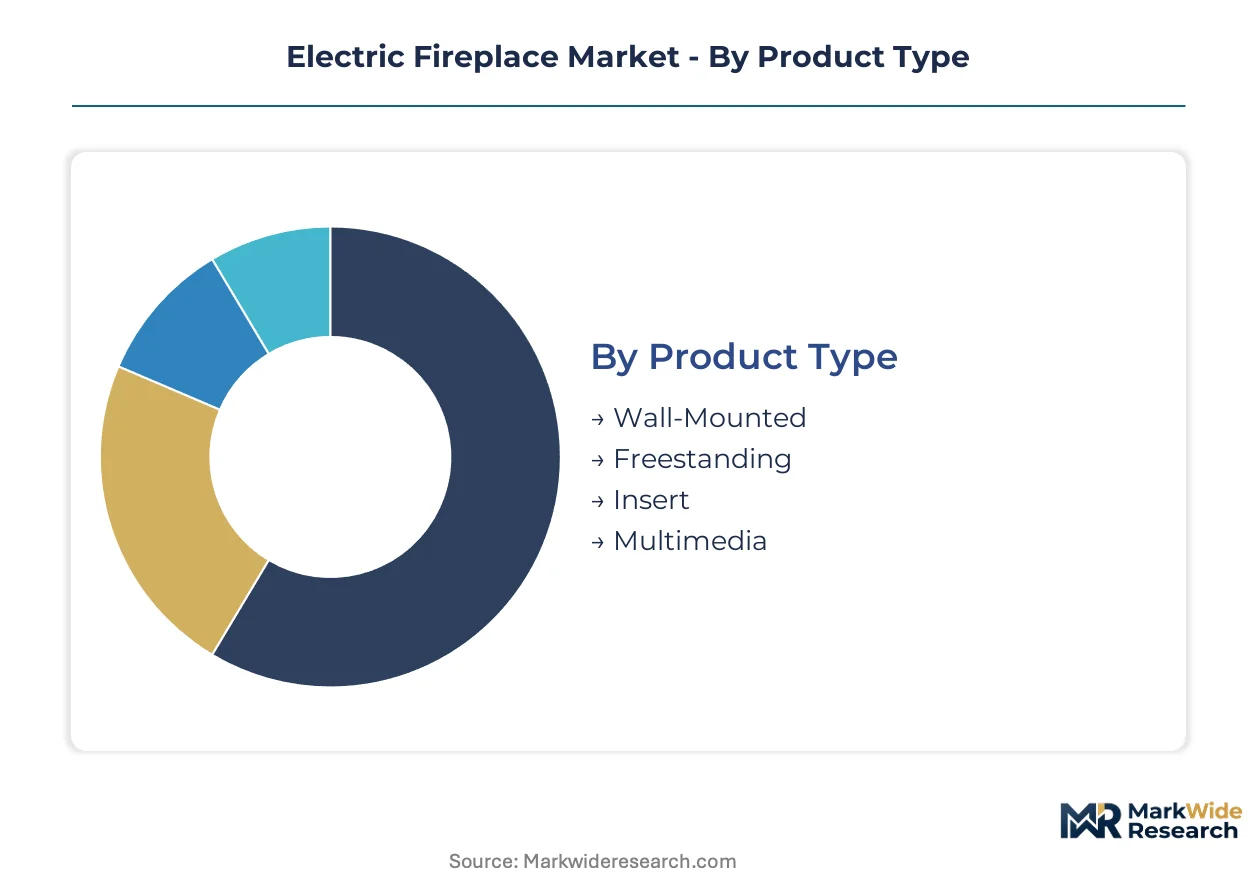
Product configuration determines installation feasibility and thermal output range, shaping replacement decisions when homeowners upgrade from masonry hearths or landlords retrofit rental units. Segment boundaries blur as manufacturers engineer multi-modal platforms that shift across mounting types via modular chassis designs.
Product Type:
Upgrade cycles accelerate where existing masonry infrastructure creates compatibility constraints, pushing demand toward formats that minimize structural modification.
- Wall-Mounted:Thin-profile units affix directly to vertical surfaces without floor footprint, requiring only standard electrical outlet access. Demand clusters in United States metropolitan condominiums and United Kingdom urban apartments where space constraints override traditional hearth aesthetics. EPA efficiency thresholds favor these units in new construction specifications.
- Insert:Self-contained fireboxes slide into existing masonry openings, preserving surround stonework while eliminating venting requirements. United States single-family housing retrofits drive volume as homeowners seek to deactivate wood-burning systems without structural demolition. DOE certification timelines create launch delays for new insert iterations.
- Freestanding:Portable chassis with integrated mantel or stove styling relocate without installation permanence.
- Multimedia:Combined entertainment center and heating platforms integrate display mounting with flame effects.
Volume placements concentrate in Wall-Mounted; the faster expansion belongs to Insert.
Technology:
Cost tier stratification separates premium thermal performance from entry-level ambiance systems, with mid-range hybrids capturing renovation budgets that balance efficiency and aesthetics.
- Infrared:Quartz tube elements emit radiant heat without drying ambient air, operating at higher wattage for cold-climate primary heating. United States northern tier states and Canadian provinces specify these for supplemental zone heating in detached homes. EU Ecodesign standby power limits force control circuit redesigns.
- LED:Low-wattage flame simulation without substantial heat output dominates Sun Belt installations where visual ambiance drives purchase intent. United States southern states and Mediterranean Europe absorb volume for seasonal decorative use. F-Gas Regulation restrictions on refrigerant heat pumps indirectly channel retrofit demand toward electric resistance alternatives.
- Traditional:Resistive coil elements with basic flame effects occupy entry price bands.
- Eco-Friendly:Recycled chassis materials and low-standby electronics address sustainability scoring in commercial specifications.
Volume placements concentrate in LED; the faster expansion belongs to Infrared.
End User:
Customer type determines specification authority, with residential buyers prioritizing installation flexibility while commercial procurement emphasizes warranty terms and fleet maintenance protocols.
- Residential:Individual homeowners and renters purchase through retail channels for primary living spaces, basements, and supplemental bedrooms. United States housing turnover and renovation spending recalibrate demand toward insert and wall-mounted formats compatible with existing infrastructure.
- Commercial:Office landlords and property managers specify hardwired installations with centralized control for lobby and common area deployment.
- Hospitality:Hotel chains and restaurant groups standardize on brand-consistent flame aesthetics across property portfolios.
- Retail:Showroom and customer space applications prioritize visual impact over thermal output.
Volume placements concentrate in Residential; Commercial posts the steepest expansion trajectory.
Distribution Channel:
Supply concentration among big-box networks and direct platforms is displacing legacy distributor intermediaries, compressing margin pools and accelerating price transparency.
- Online Retail:E-commerce platforms capture consumer research-to-purchase journeys with comparison tools and installation video content. United States direct-to-consumer volume climbs as manufacturers bypass distributor markups.
- Specialty Stores:Hearth and home showrooms retain influence for insert retrofits requiring masonry assessment and contractor coordination.
- Wholesale:Builder and contractor supply houses serve new construction specifications with volume pricing.
- Direct Sales:Manufacturer-owned channels capture full margin on premium holographic and smart-integrated systems.
Volume placements concentrate in Online Retail; Direct Sales gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban census tracts channel renovation capital toward electric fireplace retrofits in United States metropolitan cores. Single-family housing stock turnover and condominium conversion projects concentrate specification activity in designated tax-advantaged districts.
United States
Single-family housing retrofits and new construction electrification dominate volume as homeowners deactivate wood-burning masonry systems. EPA efficiency guidelines and DOE appliance standards phase out legacy resistance models across northern tier states. Chicago, Minneapolis, and Boston metropolitan clusters absorb wall-mounted and insert formats compatible with existing infrastructure.
Canada
Cold-climate supplemental heating demand in Ontario and Quebec provinces accelerates infrared quartz specification for detached home zone heating. Natural Resources Canada EnerGuide labeling requirements shape minimum performance thresholds for electric heating equipment. Toronto and Montreal urban cores concentrate condominium retrofit activity toward thin-profile wall-mounted units.
Germany
Building energy efficiency regulations and district heating transition programs redirect residential retrofit capital toward electric resistance alternatives. EU Ecodesign standby power limits and seasonal efficiency disclosure mandates compress development timelines for control electronics. Munich and Hamburg metropolitan areas drive demand for masonry-compatible insert formats in historic building renovations.
United Kingdom
Gas boiler phase-out commitments and building electrification codes channel demand toward electric fireplace alternatives in residential retrofits. CE marking and UKCA conformity requirements govern market access for flame simulation and heating systems. London and Birmingham urban apartment markets prioritize space-efficient wall-mounted installations over traditional hearth aesthetics.
France
Rural property renovation subsidies and historic building preservation incentives sustain demand for insert formats preserving existing stonework. ANSM product safety oversight and EU F-Gas Regulation restrictions on refrigerant heat pumps divert certain retrofit scenarios toward electric alternatives. Paris and Lyon metropolitan clusters concentrate specification authority among interior designers and specialty contractors.
Electric Fireplace Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated flame-technology developers commanding premium positioning while OEM assemblers serve volume retail channels. The vendor base organizes around three archetypes: heritage hearth manufacturers extending into electric formats, dedicated electric fireplace specialists, and diversified consumer appliance conglomerates. Competitive moves concentrate on smart home integration partnerships and direct-to-consumer channel expansion.
Within the heritage-extension archetype, Glen Dimplex Group and Napoleon occupy positions exemplifying manufacturing scale and technology leadership respectively. Twin Star Home represents the specialist tier with channel control through big-box retail and e-commerce platforms. These three entities anchor the competitive structure across North American and European distribution networks.
| Leading Market Players |
|---|
| Glen Dimplex Group |
| Twin Star Home |
| Napoleon |
| Hearth & Home Technologies |
| Empire Comfort Systems |
| Amantii Electric Fireplaces |
| Touchstone Home Products |
| Modern Flames |
| BFM Europe |
| Others |
Supply Flow & Price Mechanics
EPA efficiency guidelines mandating higher thermal performance thresholds are forcing manufacturers toward infrared quartz systems and holographic flame platforms, compressing margins on legacy resistive models and rewarding suppliers with certified component streams.
Pricing Analysis
Short lead-time premiums attach to UL-certified infrared modules and CE-marked control electronics as OEMs rush to meet 2027 Ecodesign deadlines. Three-tier pricing structure across premium holographic systems, mid-range infrared platforms, and economy LED units stratifies by certification grade and thermal output capability. Cost compression in entry-level LED segments intensifies because of semiconductor input volatility and direct-to-consumer channel expansion. Commercial procurement teams exhibit lowest price sensitivity due to warranty bundling and fleet maintenance protocols, while residential renovators drive hard bargains on insert retrofits.
Supply Chain Analysis
Quartz tube manufacturing for infrared elements rests on Chinese and German specialty ceramic producers, while LED flame simulation chipsets draw from Taiwanese semiconductor foundries and South Korean display component specialists. Copper winding stock for resistive elements, optical-grade acrylics for holographic projection, and certified fire-rated plastics constitute critical input dependencies. Single-source vulnerability concentrates in quartz tube suppliers serving cold-climate infrared specifications. Distribution runs through big-box retail networks and direct-to-consumer platforms that displace legacy distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric fireplace sector sits in a technology-transition phase as holographic flame systems displace conventional LED simulation and infrared quartz overtakes legacy resistive heating.
For Market Incumbents: Deepen backward integration into quartz tube manufacturing and optical component supply to defend margin position against semiconductor cost volatility. Accelerate UL and CE certification pipelines for holographic platforms before Ecodesign standby power limits tighten. Channel control through direct-to-consumer platforms and big-box exclusivity agreements protects pricing power as distributor networks erode. For New Entrants and Emerging Players: Capture white-space in smart home integration partnerships and voice-control compatibility layers where heritage manufacturers lag. The most penetrable segment spans Sun Belt residential markets seeking ambiance-dominant LED systems without full heating output. A direct-to-consumer go-to-market angle with installation video content and comparison tools bypasses entrenched retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors specialized holographic flame technology developers and certified component suppliers with EPA and EU regulatory clearances. Long-term viability hinges on building electrification code acceleration and utility rebate expansion across northern tier states. Watch heat pump cold-climate performance improvements as the signal for infrared electric fireplace demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Voice control compatibility with Amazon Alexa and Google Home opens premium positioning in connected residential ecosystems. |
| Direct-to-Consumer Channel Launch | Manufacturer-owned e-commerce platforms capture margin pools previously allocated to distributor networks and specialty retailers. |
| Holographic Flame Technology Licensing | Optical design IP partnerships with European historic renovation specialists address insert retrofit demand in protected building stock. |
| Backward Integration into Quartz Supply | In-house infrared tube production insulates margin from Chinese ceramic supplier concentration and tariff exposure. |
| EU Ecodesign Certification Acceleration | Early standby power compliance secures market access ahead of 2027 implementation deadlines for wall-mounted categories. |
Methodological Framework
Multi-period observation of EPA certification timelines, EU Ecodesign implementation schedules, and housing retrofit permit data anchored the trend analysis, supplemented by interviews with electric fireplace product managers, UL certification engineers, big-box retail category buyers, and specialty hearth contractors. Secondary validation drew from DOE appliance standard filings, EPA efficiency guideline updates, EU F-Gas Regulation impact assessments, and residential construction spending databases. Bottom-up unit shipment modeling triangulated against top-down market value estimates.
Input-output matrices mapped quartz tube supply constraints, semiconductor lead times, and channel inventory turns against price realization data across product tiers. Segmentation dimensions spanned installation type, heating technology, end-user category, and distribution channel, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from fitted growth curves calibrated to housing turnover rates and electrification code adoption patterns, incorporating utility rebate program expansion and heat pump substitution elasticities as scenario variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to heat pump technology advances, copper and semiconductor commodity cycles, and building code electrification acceleration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Household Refrigerator Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Electric Household Appliances Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
UAE Major Home Appliances Market