
 GCC Small Home Appliances Market | 2026-2036
GCC Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Small Home Appliances Market Foresight
Hypermarket and e-commerce distribution in the GCC is fragmenting as consumers split purchases between brick-and-mortar showrooms and quick-commerce platforms. Samsung Electronics leverages its regional logistics hubs to sustain shelf dominance across Carrefour and Lulu networks. Haier Electronics Group Co. Ltd. competes aggressively on price in the mid-tier electric kettle and iron segments. Dyson differentiates through boutique retail partnerships and direct-to-consumer digital channels in Dubai and Riyadh.
GCC small home appliances encompass compact, electrically powered devices designed for domestic tasks, typically operating at 220-240V with power ratings from 500W to 2,000W, manufactured through injection-molded plastic housing assembly and motor integration. These units serve residential and light-commercial users seeking task-specific convenience without full-scale appliance investment. Vacuum cleaners and coffee makers command the largest revenue pools, with cordless technology variants capturing premium positioning as lithium-ion battery costs decline. Food processors anchored by brushless motor designs represent the fastest-growing product category as home cooking participation rises across Gulf urban centers.
SASO, the UAE's Ministry of Industry and Advanced Technology standards arm, and Bahrain's Industry, Commerce and Tourism Ministry collectively enforce energy-labeling and product-safety certifications that determine market access for imported appliances. These frameworks compel manufacturers to redesign motor efficiencies and insulation materials before customs clearance. Stakeholders must monitor evolving Gulf-wide harmonization of efficiency tiers and the pace at which Saudi local-content requirements expand beyond existing industrial incentive schemes.
Market Dynamics
SASO energy-efficiency labeling mandates are forcing manufacturers to redesign motor systems and insulation materials before customs clearance, compressing product development cycles and elevating compliance costs across the Gulf.
Growth Catalysts
- Apartment construction acceleration:Riyadh-Jeddah corridor development is expanding the addressable base of young professionals seeking compact convenience appliances for rental units.
- Lithium-ion battery cost decline:Cordless vacuum and kitchen tool variants are capturing premium positioning as cell economics improve, enabling cordless technology to penetrate mid-tier price bands.
- Home cooking participation rise:Food processors anchored by brushless motor designs are expanding household penetration as Gulf urban centers embrace meal preparation.
Market Restraints
- Copper and rare-earth price volatility:Motor winding materials and permanent magnet inputs face supply pressure from concentrated Chinese refining capacity, squeezing margin structures.
- Customs certification friction:SASO, UAE Ministry of Industry, and Bahrain Industry Ministry requirements create multi-month pre-market timelines that delay revenue recognition.
- Full-size appliance substitution:Built-in kitchen systems in new luxury developments reduce standalone small appliance need among affluent purchasers.
Strategic Opportunities
- Quick-commerce platform expansion:Instant delivery networks in Dubai and Riyadh are creating new impulse-purchase channels for electric kettles and garment care devices.
- Local-content incentive alignment:Saudi industrial incentive schemes beyond existing frameworks may reward regional assembly investment with preferential customs treatment.
- Brushless motor-food processor convergence:Advanced motor control electronics paired with precision blade systems enable premium positioning in the fastest-growing category.
Industry Challenges
- Certification timeline compression:Gulf-wide efficiency tier harmonization requires simultaneous multi-jurisdiction testing, straining quality assurance bandwidth.
- Logistics hub reconfiguration:Samsung's regional distribution dominance forces competitors to build parallel cold-chain and last-mile capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Small Home Appliances Market |
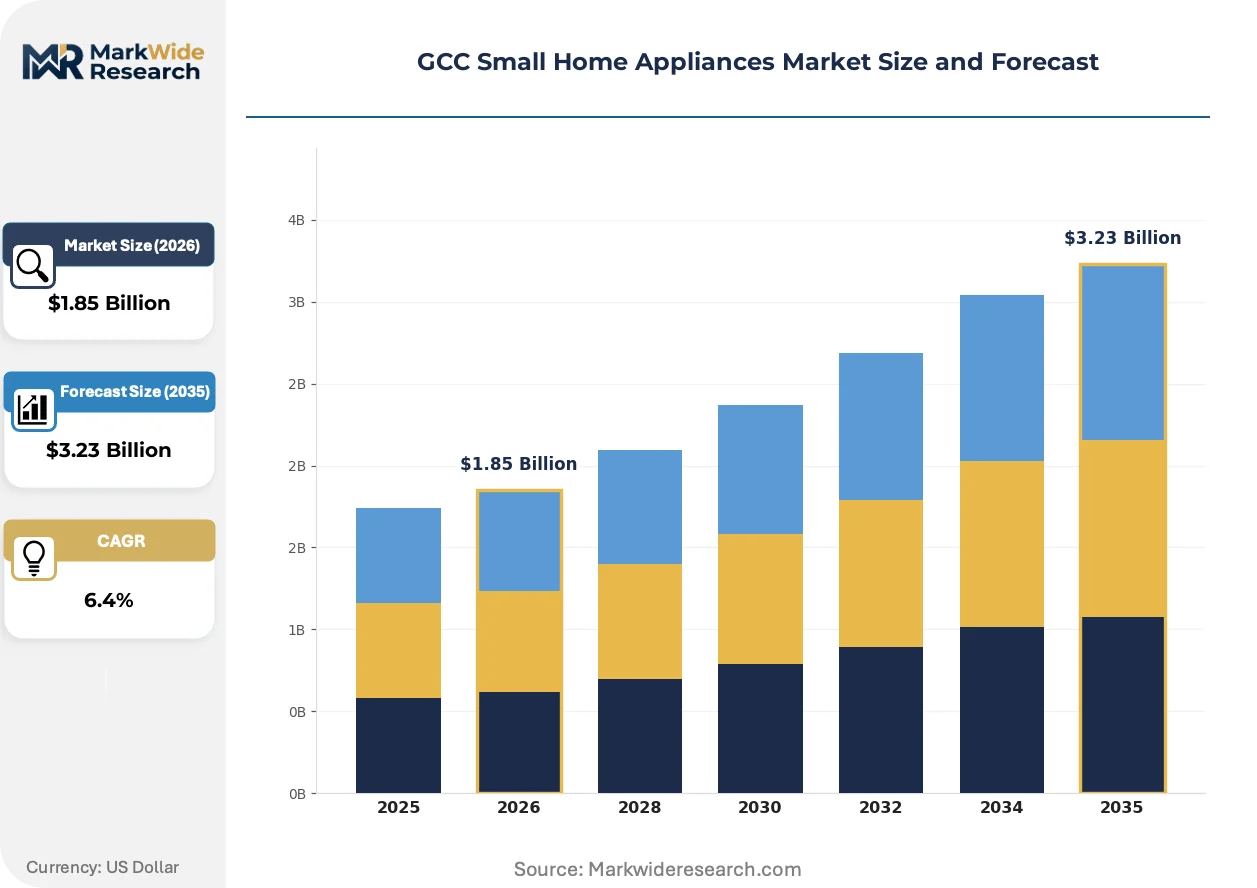
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
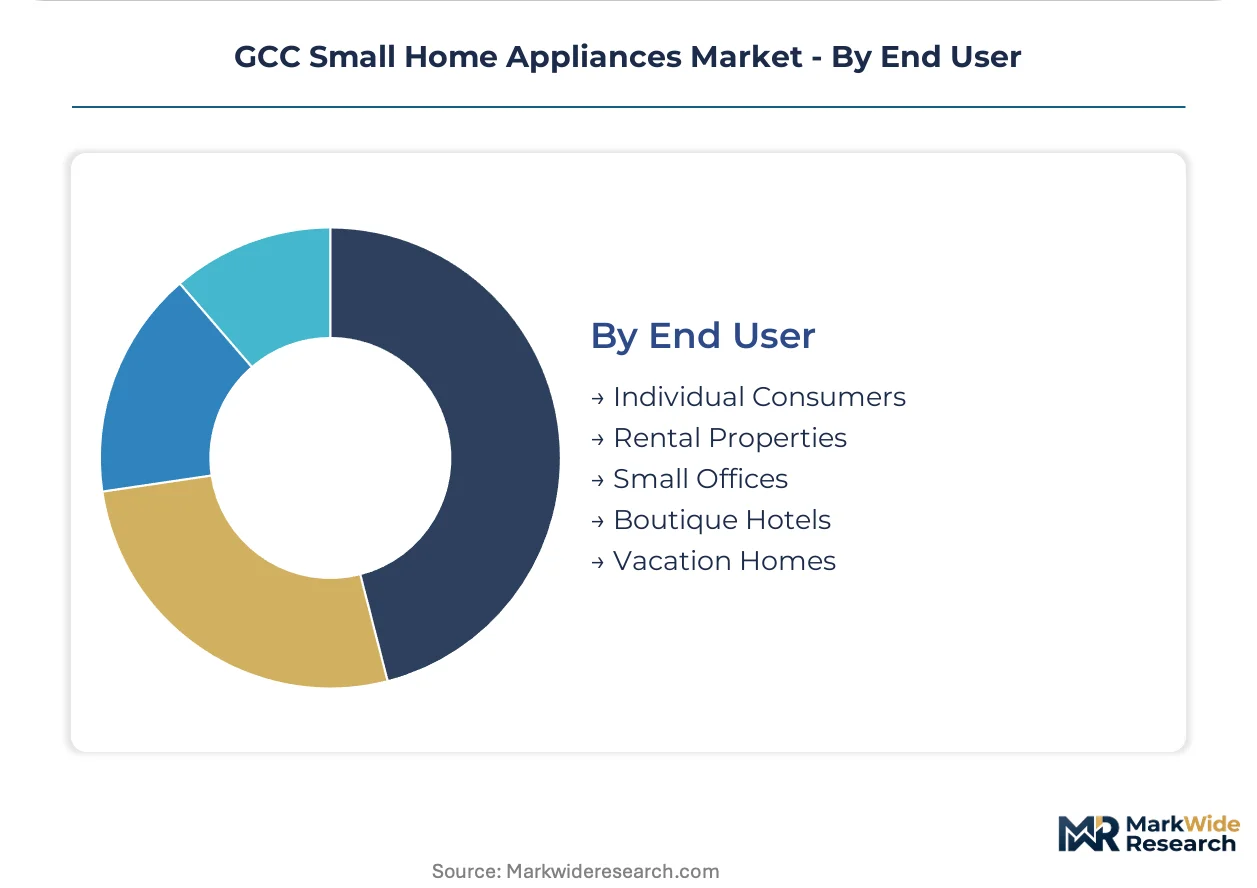
| Segmentation | Product Type: Food Processors, Vacuum Cleaners, Irons, Electric Kettles, Coffee Makers Technology: Induction, Steam, Cordless, Brushless Motor, Energy Efficient Application: Household Cooking, Cleaning, Laundry Care, Beverage Preparation, Personal Grooming End User: Individual Consumers, Rental Properties, Small Offices, Boutique Hotels, Vacation Homes |
| Companies Covered | Haier Electronics Group Co. Ltd., Samsung Electronics, Electrolux AB, BSH Home Appliance, Hitachi, Philips, Panasonic Corporation, LG Electronics, Dyson, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Small Home Appliances Market Shifts & Advancements
Three forces are compressing traditional product lifecycles across the GCC small appliance sector: cordless power systems, regulatory efficiency mandates, and the fragmentation of purchase behavior across physical and digital channels.
Brushless DC motor technology is rendering obsolete traditional brushed motor designs in food processing and vacuum categories. Young professionals in Saudi urban rental properties are adopting cordless variants at accelerated replacement cycles. This shift is compressing the premium tier definition and forcing legacy suppliers to accelerate R&D spend or retreat to commodity positioning.
SASO energy-labeling mandates are tightening minimum efficiency thresholds for vacuum cleaners and heating appliances imported into Saudi Arabia. Manufacturers must redesign thermal insulation and motor winding specifications to achieve customs clearance. The coffee maker and electric kettle segments face the steepest redesign costs as heating element efficiency becomes the binding constraint.
Purchase behavior is splitting between hypermarket showroom evaluation and quick-commerce fulfillment. Consumers in Dubai and Riyadh are inspecting products at Carrefour and Lulu locations before ordering identical SKUs through instant delivery platforms. This channel arbitrage is compressing retail margin pools and forcing brands to maintain price parity across incompatible cost structures.
GCC Small Home Appliances Market Segmentation
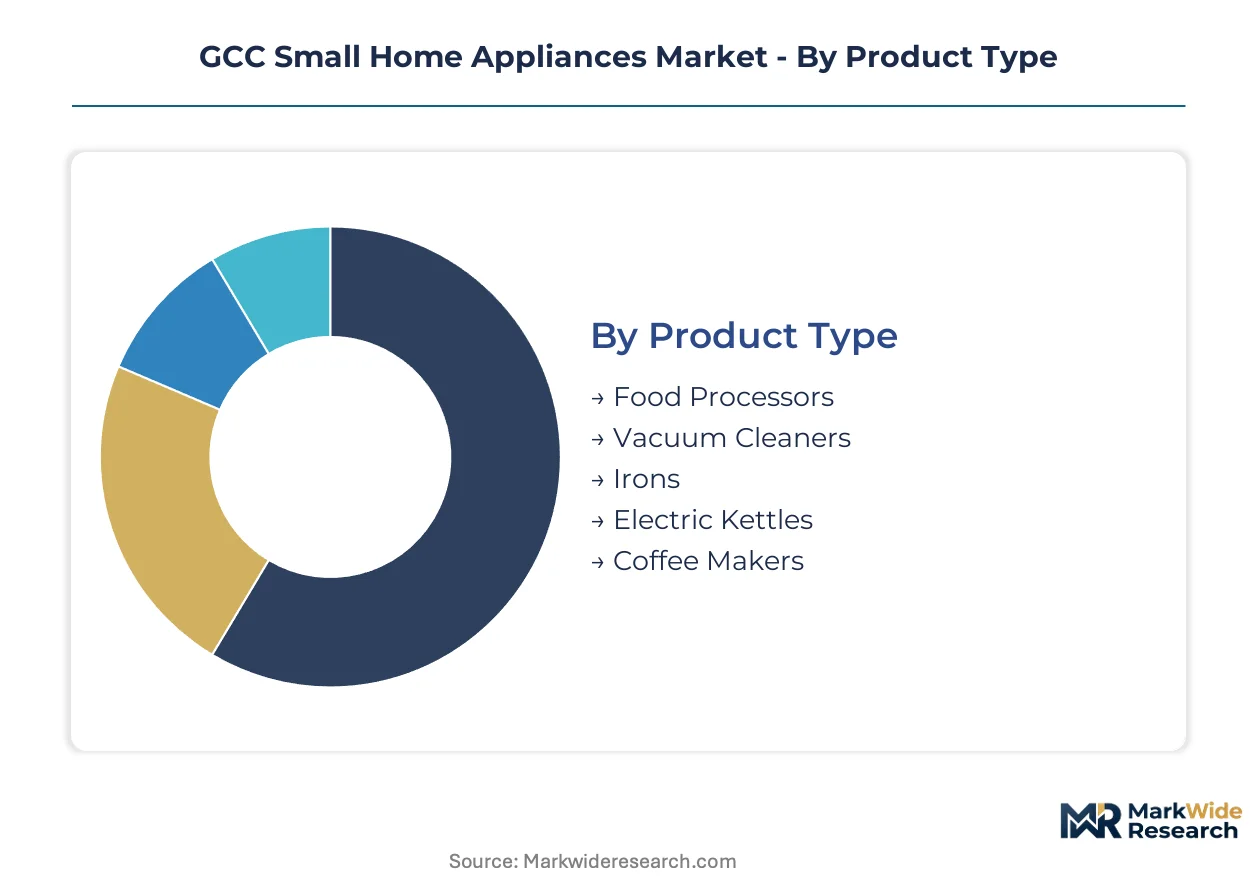
Segmentation in the GCC small home appliances market reveals how product design, energy compliance, and distribution channels must align with distinct usage intensities across residential and commercial settings. Understanding these divides enables manufacturers to calibrate warranty terms, service networks, and SKU portfolios for maximum penetration.
Product Type:
After-sales service intensity varies sharply across product categories, with motor-driven units demanding spare-part availability and heating-element appliances requiring calibration support.
- Vacuum Cleaners:Cordless lithium-ion variants dominate premium positioning as battery cell economics improve, with demand concentrating in Saudi Arabia's Riyadh-Jeddah corridor where apartment construction accelerates and young professionals prioritize compact storage.
- Food Processors:Brushless motor designs anchor the fastest-expanding category as home cooking participation rises across Gulf urban centers, with precision blade systems requiring specialized technical support networks.
- Coffee Makers:Heating-element efficiency constraints under SASO mandates drive redesign cycles, with boutique hotel procurement favoring programmable units.
- Electric Kettles:Price-competitive positioning in hypermarket channels limits margin for extended warranty investment.
- Irons:Steam and dry variants split between garment care specialists and mass-market retail, with rental property demand favoring basic durability.
By volume, vacuum cleaners lead. By growth pace, food processors are expanding most quickly.
Technology:
Cost tier stratification separates premium motor-control electronics from commodity heating elements, with regulatory compliance adding a third pricing band.
- Brushless Motor:Advanced control electronics paired with precision systems enable premium positioning in food processing and vacuum categories, with SASO efficiency thresholds accelerating displacement of brushed alternatives.
- Cordless:Lithium-ion battery integration penetrates mid-tier price bands as cell costs decline, with quick-commerce platforms in Dubai and Riyadh driving impulse replacement cycles.
- Energy Efficient:SASO labeling mandates compress development timelines for thermal insulation redesigns across heating appliances.
- Induction:Precision temperature control serves household cooking applications with higher initial equipment investment.
- Steam:Garment care and cleaning applications require water reservoir engineering and descaling service protocols.
By installed base, energy efficient variants dominate. By technology transition speed, brushless motor adoption is climbing the fastest.
Application:
Customer type determines volume concentration versus margin potential, with commercial users accepting higher upfront costs for durability.
- Household Cooking:Food processors and induction appliances serve meal-preparation trends in Saudi urban rental units, with young professionals expanding appliance ownership beyond traditional household structures.
- Cleaning:Vacuum cleaner demand splits between cordless convenience for apartments and corded power for larger villas, with lithium-ion variants gaining share fastest in compact living spaces.
- Beverage Preparation:Coffee makers face steepest redesign costs as heating element efficiency becomes the binding constraint under SASO mandates.
- Laundry Care:Irons serve dual household and small commercial use with varying steam output requirements.
- Personal Grooming:Niche positioning with specialized retail distribution and higher margin structures.
By unit shipments, cleaning applications lead. By margin expansion, household cooking is gaining share fastest.
End User:
Geography and property type combine to determine purchase channel preference, with rental properties favoring quick-commerce and boutique hotels requiring direct vendor relationships.
- Rental Properties:Young professionals in Saudi Arabia's Riyadh-Jeddah corridor drive compact appliance adoption, splitting purchases between Carrefour and Lulu showroom evaluation and instant delivery platform fulfillment.
- Individual Consumers:Villa owners in Dubai and Riyadh sustain demand for full-featured variants with extended warranty expectations.
- Boutique Hotels:Dyson's direct-to-consumer digital channels and boutique retail partnerships serve premium positioning requirements.
- Small Offices:Beverage preparation and basic cleaning appliances with standardized procurement through corporate supply contracts.
- Vacation Homes:Seasonal usage patterns favor durability over feature complexity, with service network proximity less critical.
By transaction frequency, individual consumers lead. By growth contribution, rental properties are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO energy-efficiency mandates anchor Saudi Arabia's regulatory framework, creating compliance gravity that pulls manufacturer attention toward Riyadh-Jeddah corridor demand clusters. This concentration shapes product redesign priorities across the Gulf.
Saudi Arabia
Apartment construction acceleration in the Riyadh-Jeddah corridor expands the addressable base for compact appliances among young professional renters. SASO labeling mandates force motor system and insulation redesigns before customs clearance. Dammam's logistics infrastructure supports distribution throughput for imported finished goods.
United Arab Emirates
Dubai's quick-commerce platform density creates impulse-purchase channels for electric kettles and garment care devices. The Ministry of Industry and Advanced Technology standards arm enforces product-safety certifications alongside energy benchmarks. Abu Dhabi's retail network anchors showroom evaluation behavior before digital fulfillment.
Qatar
Boutique hotel procurement sustains premium positioning demand for programmable coffee makers and precision appliances. The Qatar General Organization for Standardization maintains harmonized efficiency thresholds with Saudi and UAE frameworks. Doha's hospitality construction pipeline concentrates high-specification commercial orders.
Kuwait
Individual consumer villa ownership sustains full-featured variant demand with extended warranty expectations. The Public Authority for Industry administers conformity assessment procedures for imported electrical goods. Kuwait City's retail corridor maintains hypermarket showroom presence for brand evaluation.
Bahrain
Small office and corporate procurement segments standardize beverage preparation appliance contracts across commercial real estate. The Industry, Commerce and Tourism Ministry enforces certification timelines that compress revenue recognition windows. Manama's position as a regional trade facilitation hub influences customs processing efficiency.
GCC Small Home Appliances Market Competitive Landscape
Full-line conglomerates and specialist innovators split the market into distinct competitive spheres with divergent capability requirements. Samsung Electronics leverages regional logistics infrastructure to sustain shelf presence across Carrefour and Lulu hypermarket networks. Dyson occupies boutique retail partnerships and direct-to-consumer digital channels. Haier Electronics Group Co. Ltd. competes aggressively on price in mid-tier segments. The dominant competitive moves center on quick-commerce platform integration and multi-jurisdiction certification pre-positioning.
Within the full-line conglomerate tier, Samsung Electronics and LG Electronics exemplify scale-driven positioning through logistics hub dominance and retail network saturation. Haier Electronics Group Co. Ltd. represents the cost-optimized archetype with aggressive mid-tier pricing. Dyson anchors the specialist premium tier through differentiated channel strategy. Each occupies a distinct competitive space without direct overlap in positioning architecture.
| Leading Market Players |
|---|
| Haier Electronics Group Co. Ltd. |
| Samsung Electronics |
| Electrolux AB |
| BSH Home Appliance |
| Hitachi |
| Philips |
| Panasonic Corporation |
| LG Electronics |
| Dyson |
| Others |
Supply & Pricing Matrix
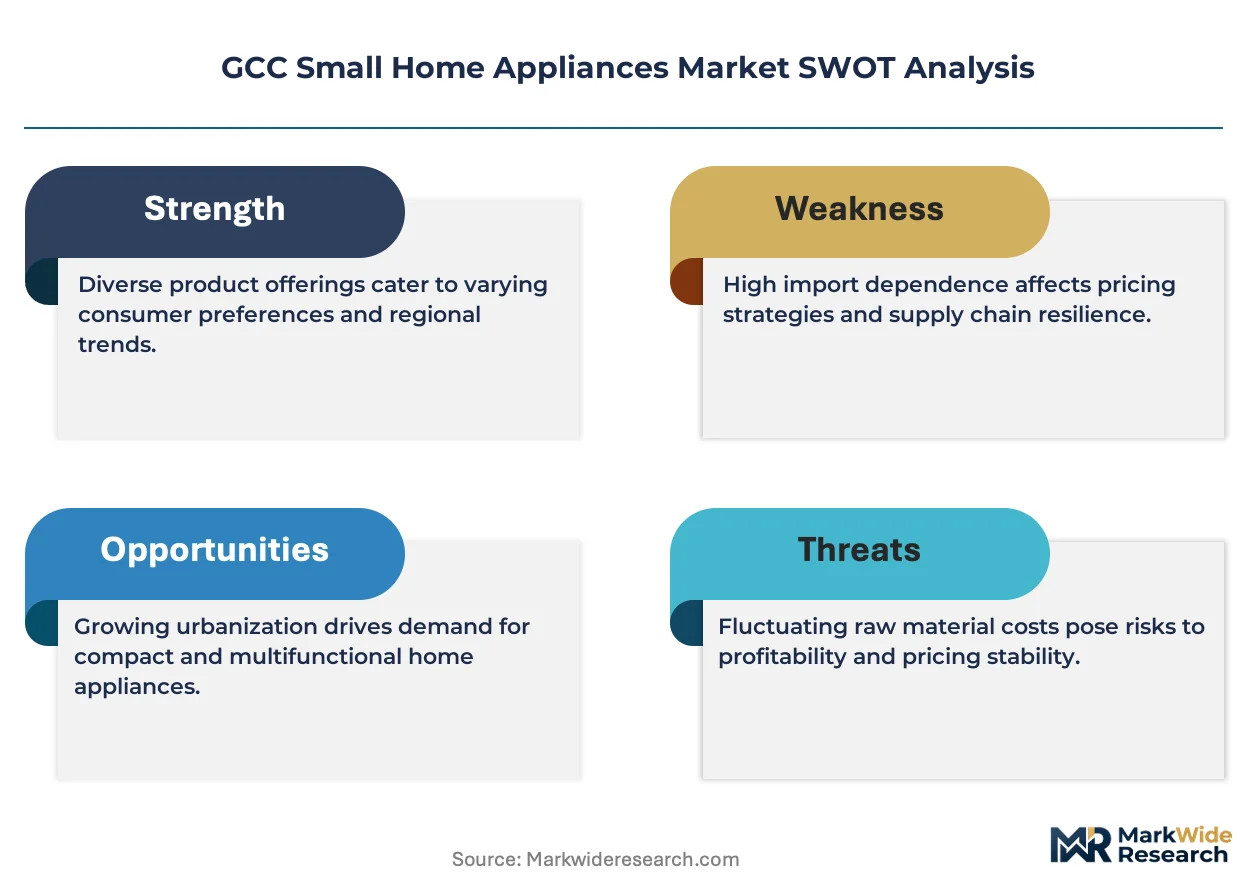
Overcapacity in Chinese motor-winding facilities is compressing supplier pricing power across the Gulf, forcing manufacturers to absorb copper and rare-earth volatility while maintaining retail price parity across incompatible channel cost structures.
Pricing Analysis
Price spreads between Riyadh showroom floors and Dubai quick-commerce platforms compress margin pools as consumers arbitrage identical SKUs across channels. Three-tier pricing structure across premium, standard, and economy levels separates Dyson's boutique positioning from Samsung's mass-market saturation and Haier's commodity aggression. Pricing pressure stems from lithium-ion cell cost declines pulling cordless variants into mid-tier bands. Rental property young professionals exhibit highest price sensitivity; boutique hotel procurement shows lowest.
Supply Chain Analysis
Export-control scrutiny over brushless motor control electronics and precision magnet alloys limits technology transfer into regional assembly operations. Manufacturing concentrates in China, South Korea, and Vietnam for motor systems, with Turkey and Egypt emerging as near-shore alternatives. Copper winding wire, neodymium permanent magnets, and lithium-ion cells anchor material dependencies. Single-source vulnerability in Chinese rare-earth refining capacity threatens input security. Distribution runs through Jebel Ali and Dammam logistics hubs before hypermarket and instant-delivery fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service networks and extended warranty penetration are expanding faster than hardware unit economics across the GCC, converting transactional appliance sales into recurring revenue streams through calibration support and spare-part subscription programs.
For Market Incumbents: Harden brushless motor R&D pipelines against SASO efficiency tier escalations while consolidating regional logistics infrastructure to match Samsung's hub-and-spoke dominance. Defend shelf position at Carrefour and Lulu through exclusive SKU variants that resist quick-commerce price transparency. Vertical integration into regional assembly operations may capture local-content incentives before competitor pre-positioning.
For New Entrants and Emerging Players: Build out specialized technical support networks for food processor blade calibration and vacuum motor servicing, white-space territories where full-line conglomerates underinvest. Target Saudi Arabia's Riyadh-Jeddah rental corridor with compact cordless variants optimized for apartment storage constraints. Go-to-market leverage rests on instant-delivery platform partnerships rather than hypermarket slotting fee competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brushless motor food processor specialists with embedded service contracts and blade replacement subscriptions. Long-term viability favors acquisition targets with established SASO pre-certification capabilities and existing UAE Ministry of Industry relationships. Watch for Gulf-wide efficiency tier harmonization announcements as inflection signals for compliance-cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Quick-Commerce Platform Integration | Instant delivery networks in Dubai and Riyadh capture impulse replacement cycles for electric kettles and garment care devices. |
| Brushless Motor R&D Investment | Advanced control electronics paired with precision blade systems enable premium positioning in food processing categories. |
| Regional Assembly Footprint Expansion | Saudi industrial incentive schemes reward local-content alignment with preferential customs treatment for imported components. |
| Multi-Jurisdiction Certification Pre-Positioning | Simultaneous SASO, UAE Ministry of Industry, and Bahrain Industry Ministry testing compresses revenue recognition timelines. |
| After-Sales Service Network Buildout | Calibration support and spare-part availability differentiate motor-driven categories where technical complexity exceeds commodity positioning. |
Research Methodology
Initial hypotheses were tested against primary input from appliance category buyers at Carrefour and Lulu, procurement directors at boutique hotel chains, logistics managers at Jebel Ali and Dammam hubs, and regulatory affairs leads navigating SASO certification protocols, then refined against customs trade records, SASO energy-labeling databases, SEC filings from listed manufacturers, and Gulf construction permit data. Bottom-up channel volume estimates and top-down macroeconomic absorption models were cross-validated for triangulation.
Demand-supply balance dynamics across the projection horizon were modeled through product-type, technology tier, application intensity, and end-user property-type segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and regulatory implementation timelines. Forecast inputs incorporated lithium-ion battery cost decline trajectories and apartment construction pipeline data from Saudi Arabia's Riyadh-Jeddah corridor.
Stress conditions across copper and rare-earth price volatility, SASO efficiency tier acceleration, and quick-commerce platform penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization pace and battery economics evolution. Material shifts in Gulf-wide local-content requirement expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Oman Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Italy Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Chile Home Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Kuwait Home Appliances Market