
 Europe Residential Water Heaters Market | 2026-2036
Europe Residential Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Residential Water Heaters Market Foresight
Retrofit-conscious single-family homeowners is collapsing as the dominant buyer archetype while apartment developers and social housing operators gain specification share. Vaillant Group leverages its German manufacturing base to dominate the replacement boiler segment. Robert Bosch GmbH competes through integrated heat pump and control system bundles. NIBE Industrier AB specializes in compact heat pump water heaters sized for Nordic multi-family installations.
Europe residential water heaters are pressurized vessels designed to store or instantaneously heat potable water for domestic use, typically operating at 0.1–0.6 MPa with insulation ratings between 40–100 mm polyurethane foam to minimize standby losses. Their primary purpose is delivering sanitary hot water at 55–60°C for bathing, cleaning, and space heating support across single and multi-family dwellings. Heat pump technology is displacing gas-fired storage units in new construction, while tankless electric systems lead in apartment renovations where space constraints dominate. Solar thermal hybrids occupy a premium niche in Southern Europe where irradiance supports meaningful collector contribution. The electric-gas technology split is shifting as renewable electricity pricing and grid decarbonization alter lifetime cost calculations.
The EU Ecodesign Directive and ErP Regulation set mandatory minimum efficiency thresholds and labeling requirements that manufacturers must meet for market access, effectively filtering out sub-80% efficiency gas storage units. The F-Gas Regulation phases down hydrofluorocarbon refrigerants used in heat pump water heaters, forcing R&D investment in propane and CO₂-based systems. National transpositions vary, with Germany's Building Energy Act and France's RE2020 environmental regulation imposing stricter local standards than baseline EU requirements. Stakeholders must monitor how the EU Green Deal's building renovation wave targets and national boiler ban timelines reshape replacement demand cycles and product portfolio priorities.
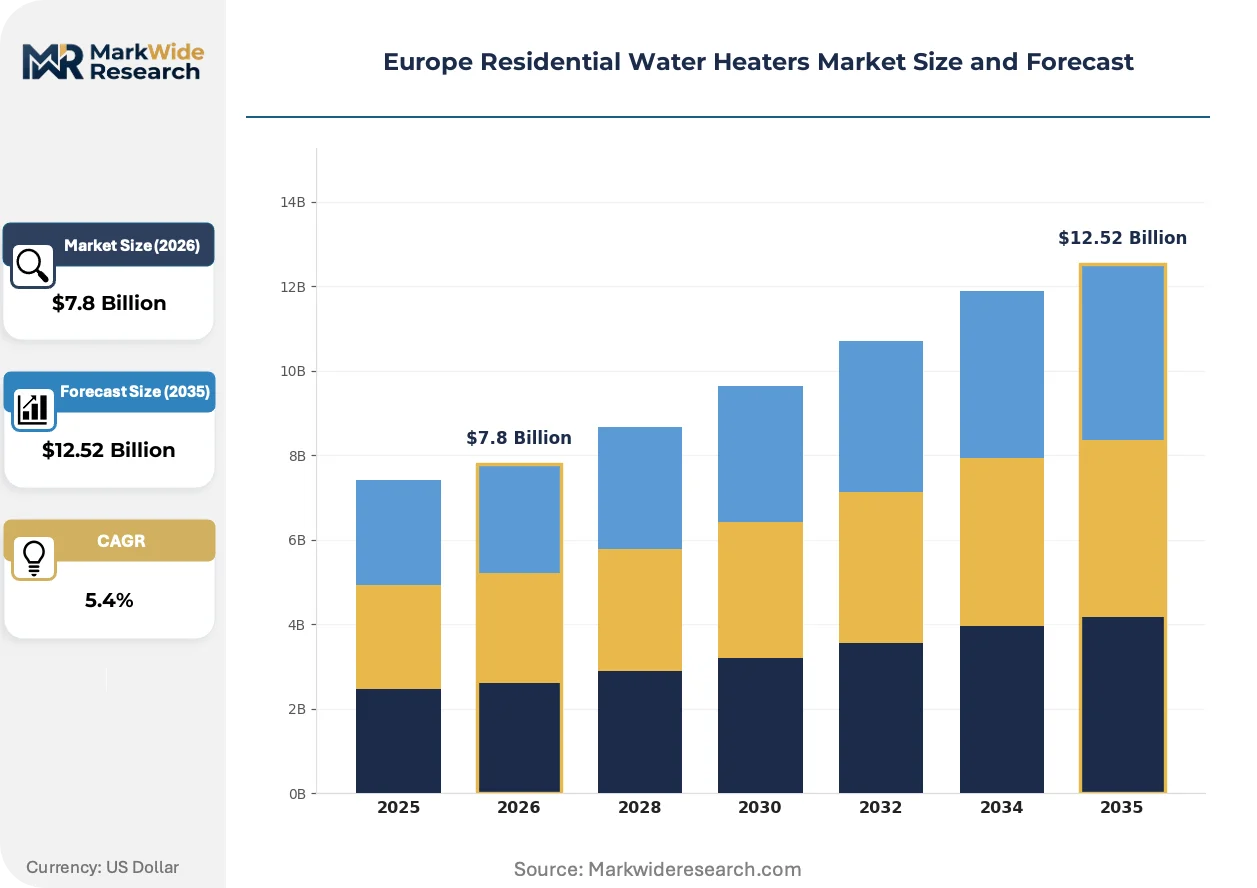
Market Dynamics
The Europe Residential Water Heaters Market is undergoing a fundamental technology transition as heat pump systems capture specification share from gas-fired storage units, driven by building renovation mandates and refrigerant phase-down requirements under the F-Gas Regulation.
Growth Catalysts
- Building renovation mandates:Germany's Building Energy Act and France's RE2020 regulation accelerate boiler replacement cycles in single-family retrofit applications, creating sustained replacement demand.
- Heat pump technology maturation:Nordic manufacturers have refined compact heat pump water heater designs that fit multi-family mechanical rooms, expanding addressable market beyond detached homes.
- REPowerEU targets:The EU Green Deal's building renovation wave establishes national heat pump deployment quotas that channel public financing toward residential thermal system upgrades.
Market Restraints
- Copper and steel input volatility:Pressure vessel fabrication depends on commodity metals whose price swings compress manufacturing margins and destabilize project quoting.
- Refrigerant supply concentration:Propane and CO₂ compressor production clusters in German and Japanese component suppliers, creating bottleneck risk for heat pump water heater scaling.
- Electrical infrastructure gaps:Older apartment buildings across Southern and Eastern Europe lack panel capacity and wiring gauge for heat pump electrical loads, forcing costly upgrade deferrals.
Strategic Opportunities
- Polish multi-family new construction:Warsaw and Kraków development pipelines specify centralized heat pump water heating systems at rates exceeding Western European adoption curves.
- Solar thermal hybrid integration:Southern European irradiance profiles support collector-heat pump combinations that reduce electrical load and operating cost for Mediterranean households.
- Digital service bundling:Remote monitoring and predictive maintenance subscriptions create recurring revenue streams as hardware margins compress on standardized heat pump platforms.
Industry Challenges
- Heat pump technician scarcity:Refrigerant handling certification and electrical commissioning skills outpace vocational training output across France, Italy, and Spain.
- Legacy system integration complexity:Hydronic retrofit compatibility with existing radiator sizing and distribution piping constrains heat pump water heater specification in 1970s-era housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Residential Water Heaters Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage, Heat Pump, Solar Technology: Electric, Gas, Hybrid, Renewable End User: Households, Apartments, Commercial Buildings, Hotels Installation Type: Built-in, Freestanding, Point-of-use, Centralized |
| Companies Covered | Ariston Holding N.V., Robert Bosch GmbH (Bosch Thermotechnology), Vaillant Group, Groupe Atlantic, Viessmann Werke GmbH & Co. KG, A.O. Smith Corporation, NIBE Industrier AB, Stiebel Eltron GmbH & Co. KG, BDR Thermea Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Residential Water Heaters Market Shifts & Advancements
Technology convergence and regulatory chemistry restrictions are compressing product development cycles across European water heater manufacturing. Manufacturers now optimize for refrigerant transition, digital integration, and installation labor reduction simultaneously.
CO₂ transcritical heat pump cycles are supplanting R-134a and R-410A systems in premium residential segments. German and Austrian manufacturers lead adoption of this technology for its ability to deliver 65°C outlet temperatures without auxiliary heating. The higher thermodynamic efficiency enables smaller storage volumes, reducing mechanical room footprint constraints that previously blocked heat pump specification in urban apartments.
The F-Gas Regulation's hydrofluorocarbon phase-down timeline forces refrigerant chemistry transitions across all heat pump water heater portfolios. Manufacturers must redesign compressor architectures and safety systems for flammable propane or high-pressure CO₂ alternatives. Nordic markets with earlier environmental regulation exposure show faster model turnover, while Southern European producers lag in certification completion.
Social housing operators now specify performance-contracting procurement models that transfer operational risk to equipment providers. Dutch and Danish housing associations lead this shift, replacing capital purchase with guaranteed hot water service fees tied to metered consumption. This restructures manufacturer revenue toward long-term service relationships and remote diagnostics capability investment.
Europe Residential Water Heaters Market Segmentation
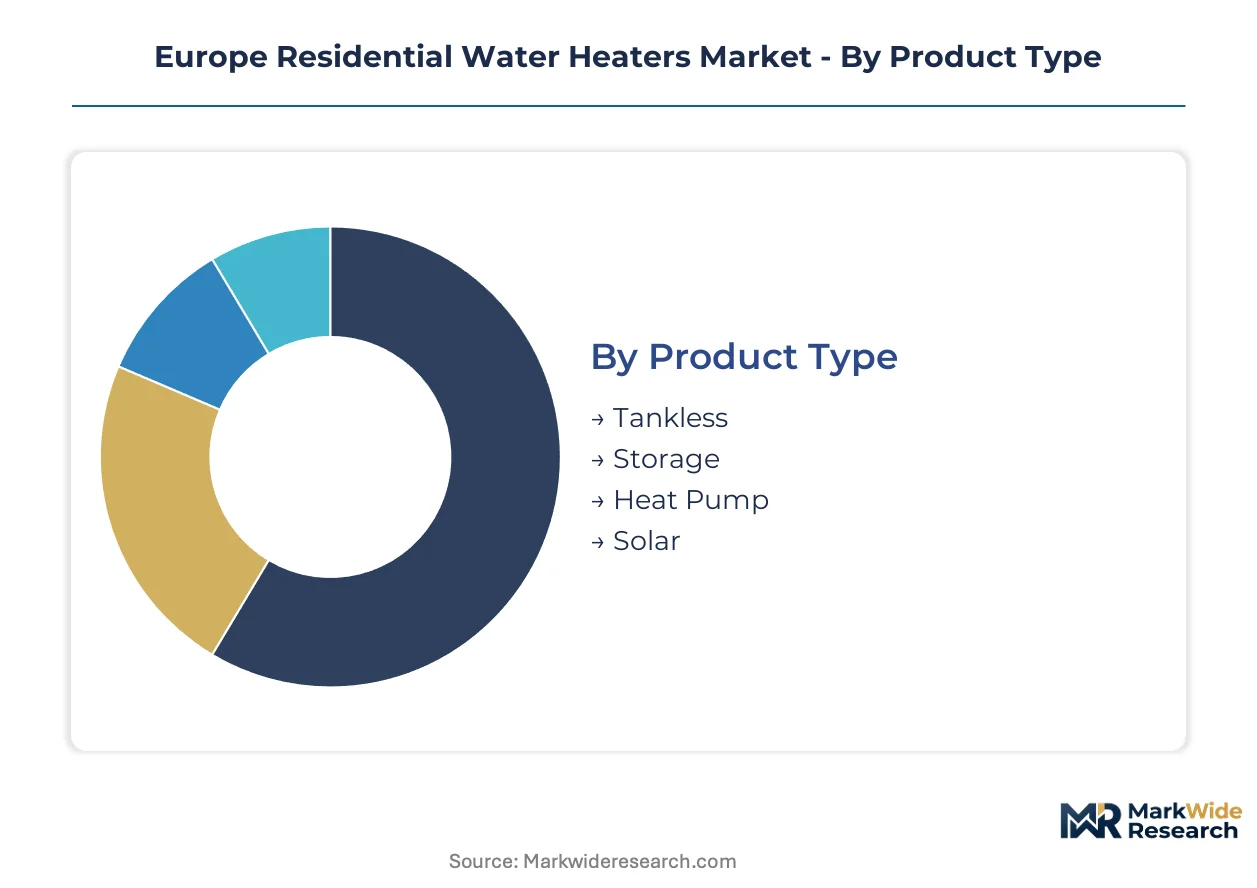
Segmentation in the Europe Residential Water Heaters Market reveals how distinct buyer archetypes channel demand through specialized distribution networks. Product specifications diverge sharply between German retrofit contractors and Polish multi-family developers, with each segment commanding tailored sales approaches.
Product Type:
Distribution channels segment sharply by product architecture, with tankless units flowing through electrical wholesalers while heat pump systems route through HVAC specialists requiring refrigerant handling certification.
- Heat Pump:CO₂ transcritical and propane-based systems deliver 65°C outlet temperatures without auxiliary heating, enabling smaller storage volumes. Demand concentrates in German single-family retrofits driven by Building Energy Act replacement mandates and France's RE2020 environmental regulation in new construction.
- Storage:Pressurized vessels with 40–100 mm polyurethane foam insulation operate at 0.1–0.6 MPa, dominating replacement cycles in older housing stock. Polish and Romanian distributors move high volumes through construction merchant channels serving apartment renovation contractors.
- Tankless:Instantaneous electric systems address space constraints in urban apartment renovations across Southern Europe. Italian and Spanish electrical installers specify these for 1970s-era buildings lacking mechanical room capacity.
- Solar:Collector-heat pump hybrids exploit Mediterranean irradiance profiles to reduce electrical load. Portuguese and Greek projects specify these for premium residential developments seeking operational cost differentiation.
Storage units dominate installed base across Europe. Heat pump systems are where expansion concentrates, climbing the fastest as F-Gas Regulation compliance deadlines approach.
Technology:
Cost tier stratification separates premium heat pump platforms from commodity electric resistance models, with hybrid systems occupying a mid-market position where gas-to-electric transitions remain incomplete.
- Electric:Resistance and heat pump architectures split between budget point-of-use applications and premium efficiency platforms. Nordic markets favor heat pump variants while Southern Europe retains resistance units for seasonal use patterns.
- Gas:Condensing storage and tankless combustion systems face phase-out timelines under national boiler bans. German and Dutch installers still specify these where building envelope quality precludes heat pump feasibility.
- Hybrid:Dual-fuel systems combine heat pump efficiency with gas auxiliary heating for cold climate performance. Austrian and Swiss alpine applications specify these to guarantee output during extended sub-zero periods.
- Renewable:Solar thermal and biomass integration addresses net-zero building targets in Danish and Swedish social housing procurement. These systems require specialized design-build contractors with thermal modeling capability.
Gas technology retains largest installed base. Electric heat pump platforms are where manufacturer R&D investment and policy support converge most intensively.
End User:
Customer type determines specification authority and procurement rhythm, with social housing operators consolidating demand through framework agreements while single-family homeowners trigger fragmented replacement cycles.
- Households:Single-family homeowners in Germany and France initiate replacement demand through installer recommendations. Building Energy Act compliance deadlines compress decision timelines in the retrofit segment.
- Apartments:Multi-family developers in Warsaw and Kraków specify centralized heat pump systems at adoption rates exceeding Western European curves. Polish construction permits for 50+ unit buildings increasingly mandate thermal system pre-qualification.
- Commercial Buildings:Small-scale residential developers and mixed-use projects require modular systems with expansion capability. Czech and Hungarian contractors favor standardized skids reducing on-site commissioning time.
- Hotels:Hospitality operators prioritize redundancy and recovery rate performance over capital cost minimization. Mediterranean resort properties specify solar-heat pump hybrids to manage peak summer demand spikes.
Single-family households dominate transaction volume. Apartment developers are where specification standardization and volume procurement reshape competitive dynamics.
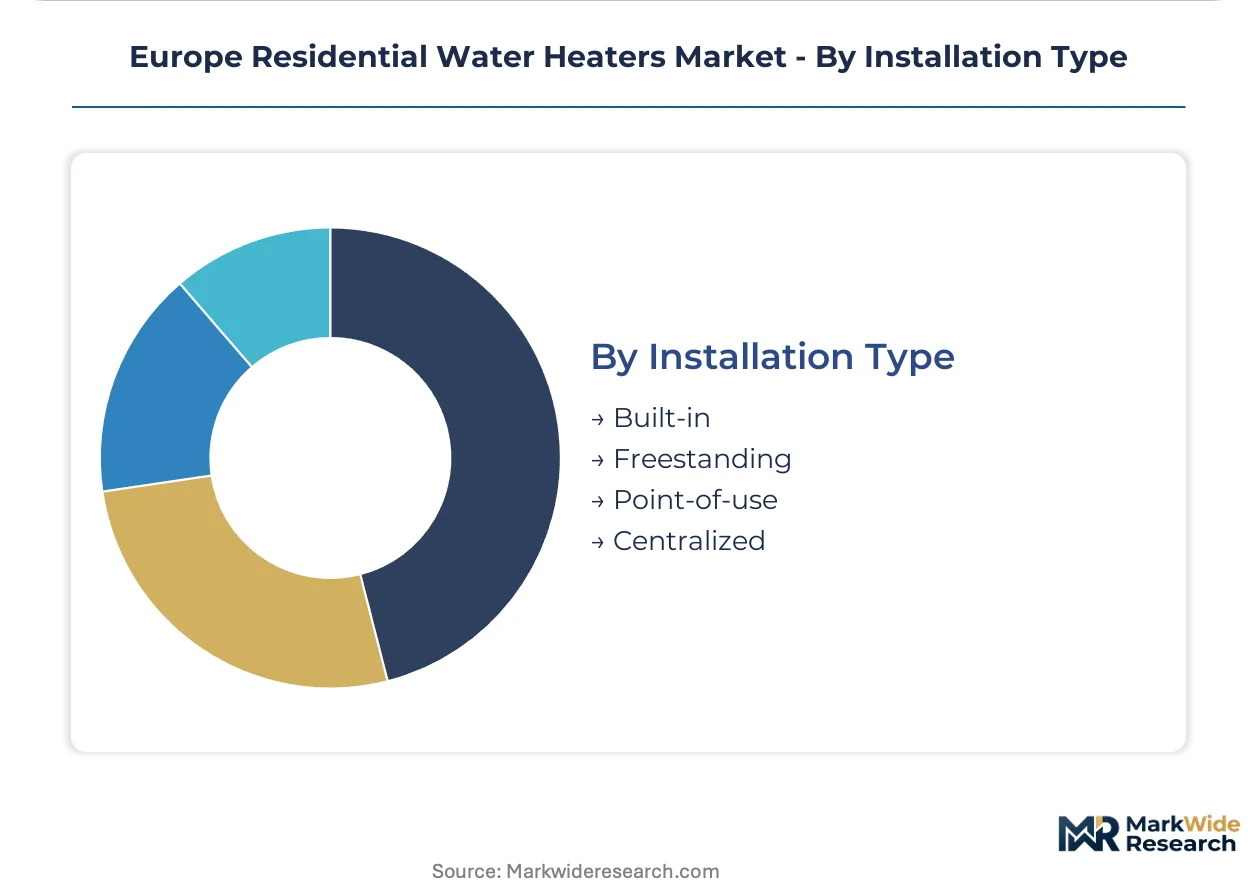
Installation Type:
Application context dictates mechanical room constraints and distribution architecture, with built-in systems requiring cabinet integration expertise while centralized plants demand hydraulic balancing capability.
- Freestanding:Conventional storage and heat pump units occupy dedicated mechanical rooms in detached homes and small multi-family buildings. German basement installations remain the default specification for replacement projects.
- Built-in:Cabinet-integrated systems address space constraints in urban apartments and kitchen renovations. French and Benelux markets specify these for aesthetic integration in open-plan living spaces.
- Point-of-use:Under-sink and wall-mounted electric units serve remote fixtures in large dwellings and commercial retrofits. Italian distributors stock these for bathroom renovation contractors seeking rapid installation turnaround.
- Centralized:District-scale and building-level plants serve multi-family developments with shared thermal distribution. Danish and Dutch housing associations procure these through performance-contracting models transferring operational risk to equipment providers.
Freestanding units dominate replacement demand. Centralized systems are where social housing procurement innovation and long-term service contracting create new revenue architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nord Stream pipeline infrastructure and Baltic grid interconnectors position Northern Europe as the primary corridor for electrified heating system deployment. Germany's Building Energy Act mandates accelerate replacement cycles across its single-family housing stock.
Germany
Retrofit contractors in North Rhine-Westphalia and Bavaria dominate replacement demand as boiler bans compress decision timelines. The Building Energy Act and F-Gas Regulation force refrigerant chemistry transitions across heat pump portfolios. Berlin-Brandenburg housing associations procure centralized systems through performance-contracting frameworks.
France
RE2020 environmental regulation drives heat pump specification in Île-de-France new construction. Social housing operators in Auvergne-Rhône-Alpes consolidate demand through framework agreements. Marseille and Lyon developers specify compact units for urban mechanical room constraints.
Poland
Warsaw and Kraków multi-family pipelines specify centralized heat pump systems at adoption rates exceeding Western European curves. National transpositions of EU Ecodesign Directive filter sub-80% efficiency gas storage from market access. Silesian construction merchant channels move high volumes through apartment renovation contractors.
Netherlands
Dutch housing associations lead performance-contracting procurement models transferring operational risk to equipment providers. The EU Green Deal's building renovation wave channels public financing toward thermal system upgrades. Randstad social housing operators consolidate specification authority through metered consumption service fees.
Italy
Electrical installers in Lombardy and Lazio specify tankless electric systems for 1970s-era buildings lacking mechanical room capacity. ErP Regulation labeling requirements filter inefficient units from distribution channels. Milan apartment renovation contractors favor rapid-installation point-of-use configurations.
Europe Residential Water Heaters Market Competitive Landscape
Concentration sits with diversified heating equipment conglomerates that leverage manufacturing scale across boiler replacement and heat pump transition cycles. German and Austrian manufacturers anchor premium heat pump segments through CO₂ transcritical technology leadership. Three strategic archetypes dominate: integrated HVAC conglomerates with control system bundling capability, compact heat pump specialists serving Nordic multi-family constraints, and construction merchant distributors optimizing for replacement part availability. M&A activity targets refrigerant handling certification networks, while portfolio diversification pushes manufacturers into long-term service contracting.
Among diversified European heating conglomerates, Robert Bosch GmbH and Vaillant Group exemplify integrated platform strategies spanning combustion and electrified thermal systems. NIBE Industrier AB occupies a specialist position within compact heat pump architectures sized for constrained mechanical environments. Ariston Holding N.V. and A.O. Smith Corporation represent transatlantic fabricators with distribution density across Southern European replacement markets. These entities anchor competitive dynamics as refrigerant phase-down deadlines compress product development cycles and social housing procurement shifts toward outcome-based contracting models.
| Leading Market Players |
|---|
| Ariston Holding N.V. |
| Robert Bosch GmbH (Bosch Thermotechnology) |
| Vaillant Group |
| Groupe Atlantic |
| Viessmann Werke GmbH & Co. KG |
| A.O. Smith Corporation |
| NIBE Industrier AB |
| Stiebel Eltron GmbH & Co. KG |
| BDR Thermea Group |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day compressor lead times from German and Japanese suppliers compress pricing power for heat pump water heater assemblers while amplifying volume-tier advantages for integrated conglomerates with captive component stocks. This inventory pressure stratifies the European market between premium CO₂ transcritical platforms commanding design premiums and commodity electric resistance units competing on replacement-part availability.
Pricing Analysis
Volume-discount tiering structures separate framework-contract social housing procurement from fragmented single-family replacement transactions. Three-tier pricing stratification across premium heat pump, standard hybrid, and economy electric resistance levels reflects certification grade and after-sales service bundling. Cost compression in mid-market gas storage segments intensifies as F-Gas Regulation deadlines force refrigerant transition R&D spending. Social housing operators in the Netherlands and Denmark exhibit lowest price sensitivity through performance-contracting models, while Polish apartment renovation contractors drive hardest bargain on standardized storage units.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability across Asia-Europe trade lanes, pressuring landed costs for copper coil and compressor imports. Manufacturing concentration clusters in Germany, Italy, and Poland, with German facilities anchoring premium heat pump assembly and Polish plants serving cost-optimized storage tank fabrication. Raw material dependencies center on copper pressure vessels, steel jacketing, and polyurethane foam insulation. Single-source vulnerability concentrates in propane and CO₂ compressor supply from German and Japanese component specialists. Distribution runs through HVAC specialist channels for heat pump systems and construction merchant networks for replacement storage units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Dutch and German social housing associations consolidate procurement through multi-year framework agreements, fragmenting specification authority away from individual installers and toward centralized technical committees.
For Market Incumbents: Consolidate refrigerant handling certification networks before F-Gas Regulation deadlines eliminate independent installer access to heat pump commissioning. Acquire Polish and Romanian construction merchant distributors to lock replacement storage volume channels. Vertical integration into CO₂ compressor sourcing reduces exposure to German-Japanese supply bottlenecks threatening margin stability.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Poland and Hungary accelerates market access for compact heat pump designs. White-space targets concentrate in Italian tankless electric retrofits and Portuguese solar-heat pump hybrid installations where incumbent coverage remains thin. Go-to-market positioning through electrical wholesaler relationships bypasses HVAC specialist channel saturation in Southern Europe.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates divesting non-core heating portfolios amid energy transition restructuring. Long-term viability favors specialists with CO₂ transcritical technology depth and service-contracting capability over pure hardware fabricators. Monitor German Building Energy Act enforcement intensity as inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition R&D | CO₂ and propane compressor architectures secure F-Gas Regulation compliance ahead of phase-down deadlines. |
| Performance-Contracting Expansion | Dutch housing association frameworks transfer operational risk from capital purchase to service fee structures. |
| Certification Network Acquisition | Refrigerant handling licenses in France and Spain address technician scarcity constraining heat pump deployment. |
| Compact Heat Pump Development | Nordic multi-family mechanical room constraints drive specification share in Warsaw and Kraków pipelines. |
| Solar Thermal Hybrid Integration | Mediterranean irradiance profiles reduce electrical load for Portuguese and Greek premium residential developments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Ecodesign Directive filings, ErP Regulation compliance databases, and national building energy act transpositions. Primary interviews engaged product managers at heating equipment manufacturers, procurement directors at Dutch and German housing associations, and HVAC installation contractors across Poland, France, and Italy. Secondary validation drew from F-Gas Regulation implementation reports, REPowerEU building renovation wave progress tracking, and customs data on copper and steel input flows. Bottom-up triangulation across product-type shipment estimates converged with top-down macroeconomic scenario modeling.
Segmentation dimensions modeled include product architecture, technology platform, end-user category, and installation type across the analysis window. The analytical framework incorporated heat pump adoption curves, gas boiler replacement mandates, and refrigerant chemistry transition timelines. CAGRs were derived from installed base turnover rates, new construction permit pipelines, and policy-driven retrofit acceleration scenarios. Forecast inputs weighted F-Gas Regulation phase-down schedules and national boiler ban timelines against electrical infrastructure upgrade capacity in Southern and Eastern Europe.
Underlying assumptions cover regulatory enforcement consistency, copper and steel price band stability, and heat pump technician training output, with deviation risk concentrated in refrigerant supply bottlenecks and electrical panel upgrade deferrals in older apartment stock. Recalibration cycles align with material shifts in EU Green Deal funding disbursements and national building energy act amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Electric Fireplace Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Smart Small Home Appliances Market