
 Germany Washing Machine Market | 2026-2036
Germany Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Washing Machine Market Analysis
Sensor-driven load detection is narrowing the efficiency gap between entry-level and premium drum systems. Bosch leverages in-house motor production to control inverter supply chains. Miele sustains its foothold in high-capacity commercial installations through extended service contracts. Samsung competes on connected-home integration, while BSH Hausgeräte anchors wholesale channels with modular platform designs.
A washing machine is an electromechanical appliance employing a rotating drum, water inlet valves, and a programmable control system to clean textiles through mechanical agitation and thermal cycles. Drum capacities typically range from 6kg to 12kg, with spin speeds exceeding 1,400 RPM in performance-tier models. Front-load configurations dominate German retail due to superior water efficiency and stackability in compact dwellings. Smart connectivity represents the fastest-growing technology segment, though inverter motor platforms command the deepest margin pools. Commercial end users in hotels and institutions generate higher per-unit revenue than household channels.
The EU Ecodesign Regulation and REACH compliance requirements shape material selection and water-recirculation system design for manufacturers distributing in Germany. The KBA does not regulate this sector, but the national implementation of EU energy labeling through BAFA influences consumer purchasing patterns. Stakeholders must monitor how pending EU right-to-repair legislation alters spare-part availability obligations and warranty cost structures.
Market Dynamics
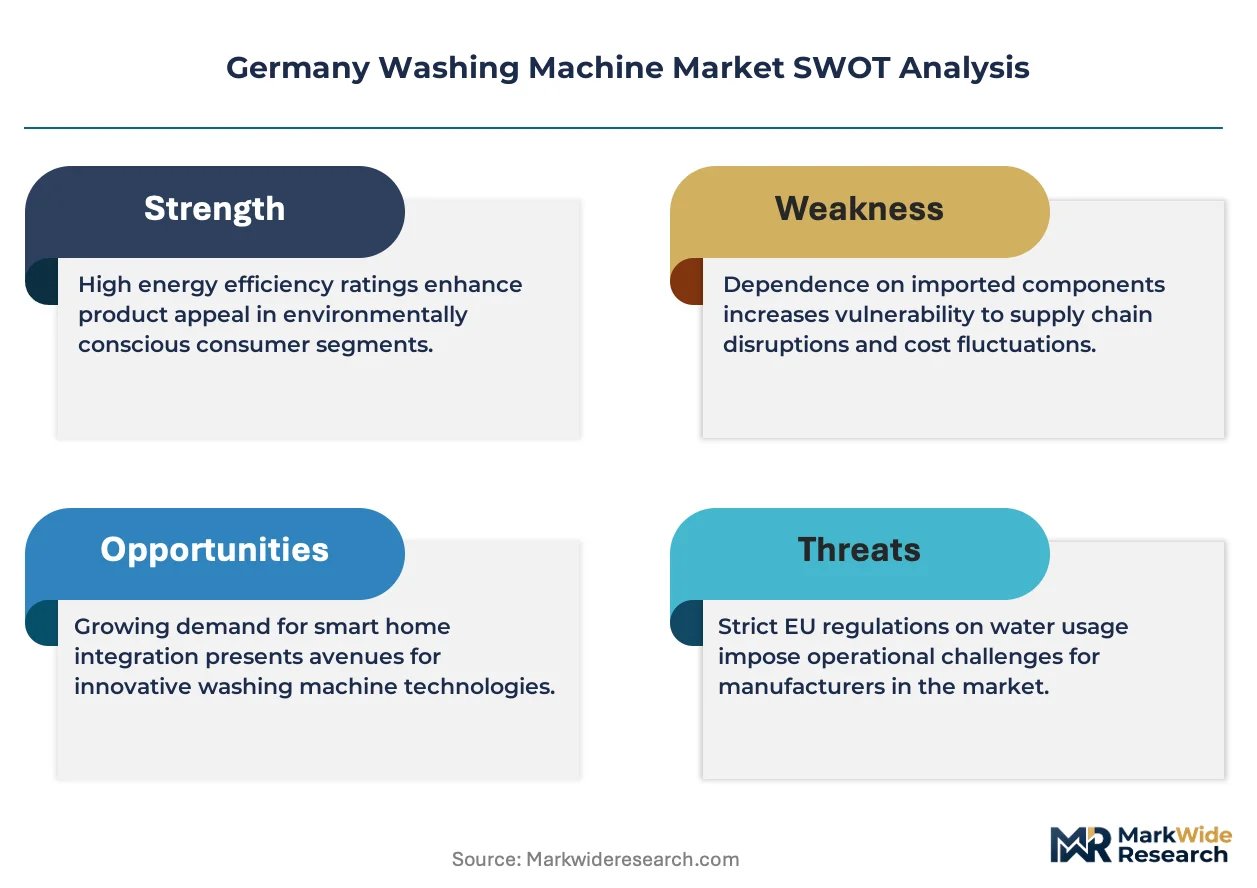
The EU Ecodesign Regulation is compressing replacement cycles while forcing simultaneous upgrades to inverter motor platforms and water-recirculation architectures across German manufacturing footprints.
Growth Catalysts
- Multi-family housing construction:Developers in North Rhine-Westphalia specify high-capacity, stackable front-load configurations as standard fit-outs, generating concentrated replacement pipelines.
- EU energy labeling alignment:BAFA-administered efficiency tiers steer consumer preference toward A-rated drum systems, accelerating trade-in of aging appliances.
- Smart connectivity integration:Wi-Fi-enabled load detection and remote cycle management are penetrating mid-tier price bands, expanding addressable household segments.
Market Restraints
- Copper and rare-earth magnet costs:Inverter motor production depends on neodymium supply concentrated in Chinese processing facilities, exposing margin structures to input volatility.
- REACH compliance complexity:Restrictions on specific polymer additives and surface coatings extend material qualification timelines for drum and seal components.
- Apartment dweller space constraints:Compact dwelling footprints in Berlin and Munich limit uptake of 10kg-plus capacity units regardless of efficiency gains.
Strategic Opportunities
- Commercial laundry services:Hotels in Bavaria and institutional facilities in Baden-Württemberg present underpenetrated demand for extended-service-contract arrangements.
- Right-to-repair preparation:Pending EU legislation mandating spare-part availability creates first-mover advantage for modular platform architectures with standardized component interfaces.
- Heat-pump drying convergence:Integration of closed-loop heat-pump technology into combination washer-dryer units addresses energy-conscious urban households.
Industry Challenges
- Embedded software certification:Smart appliance firmware requires documentation under EU Cybersecurity Act timelines, stretching engineering resources.
- Legacy inventory clearance:Retail channels face markdown pressure on pre-2023 stock lacking updated energy labels, complicating new product rollout pacing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Washing Machine Market |
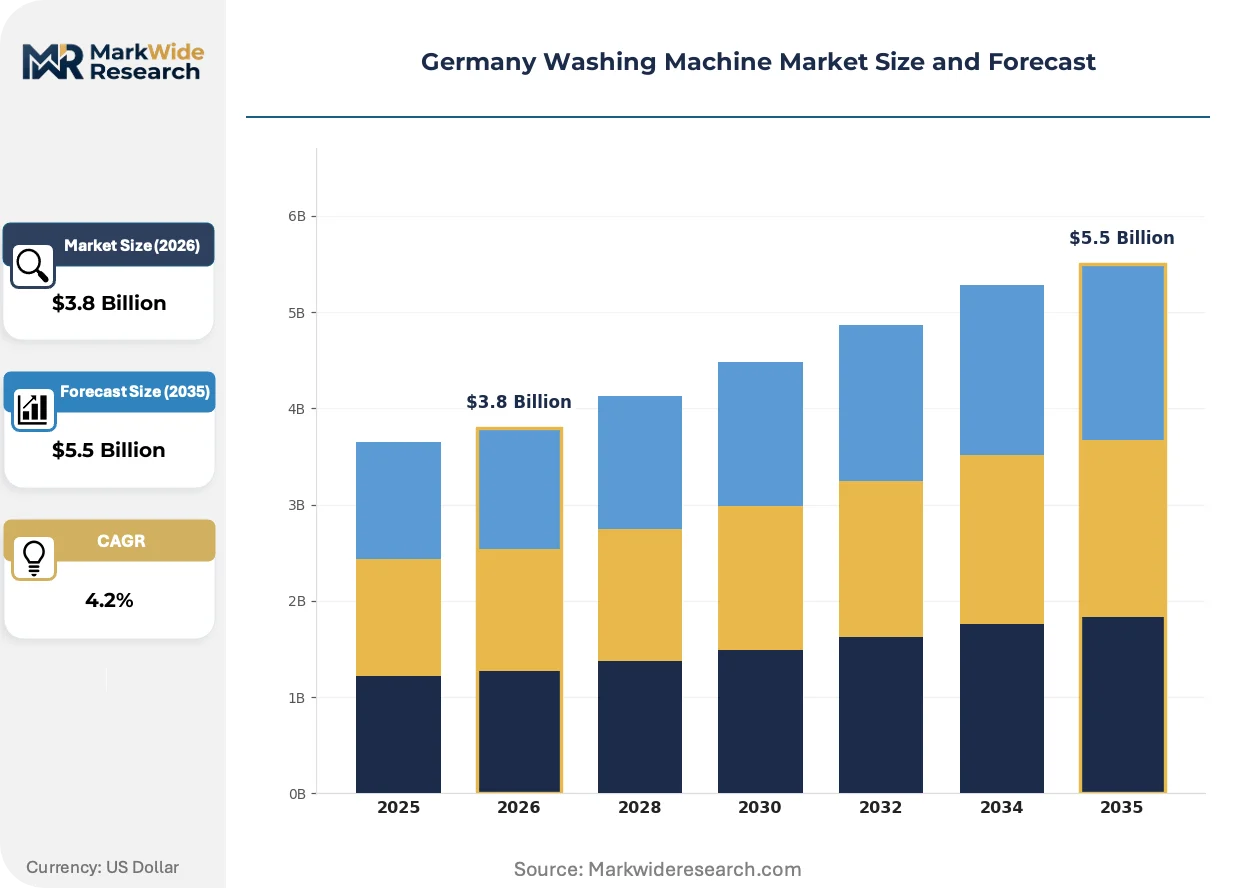
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-Load, Top-Load, Semi-Automatic, Fully Automatic Technology: Smart, Inverter, Conventional, Eco-Friendly End User: Households, Commercial, Institutions, Hotels Capacity: 6kg, 8kg, 10kg, 12kg |
| Companies Covered | Siemens, BSH Hausgeräte, Bosch, Samsung, LG Electronics, AEG, Bauknecht, Beko, Miele, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Washing Machine Market Emerging Trajectories
Sensor-driven automation and regulatory tightening are redefining competitive differentiation across drum system efficiency tiers and connected-home integration layers.
Direct-drive inverter motors eliminate belt-and-pulley transmission losses while enabling precision speed modulation. Residential buyers in urban centers are specifying these platforms for noise reduction in thin-walled apartments. Belt-driven asynchronous designs are rendering obsolete in mid-tier and above segments.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of drum seal coatings and gasket compounds. German manufacturers must validate alternative polymer formulations against 10-year durability benchmarks. Component suppliers in Baden-Württemberg are accelerating fluorine-free elastomer testing to maintain OEM qualification status.
Subscription-based maintenance bundles are displacing traditional warranty extensions among multi-unit property managers. Facility operators in Hamburg and Frankfurt are unbundling capital expenditure from service coverage, favoring per-cycle pricing. This procurement evolution concentrates buyer power with institutional channels while compressing retail margin capture.
Germany Washing Machine Market Segmentation
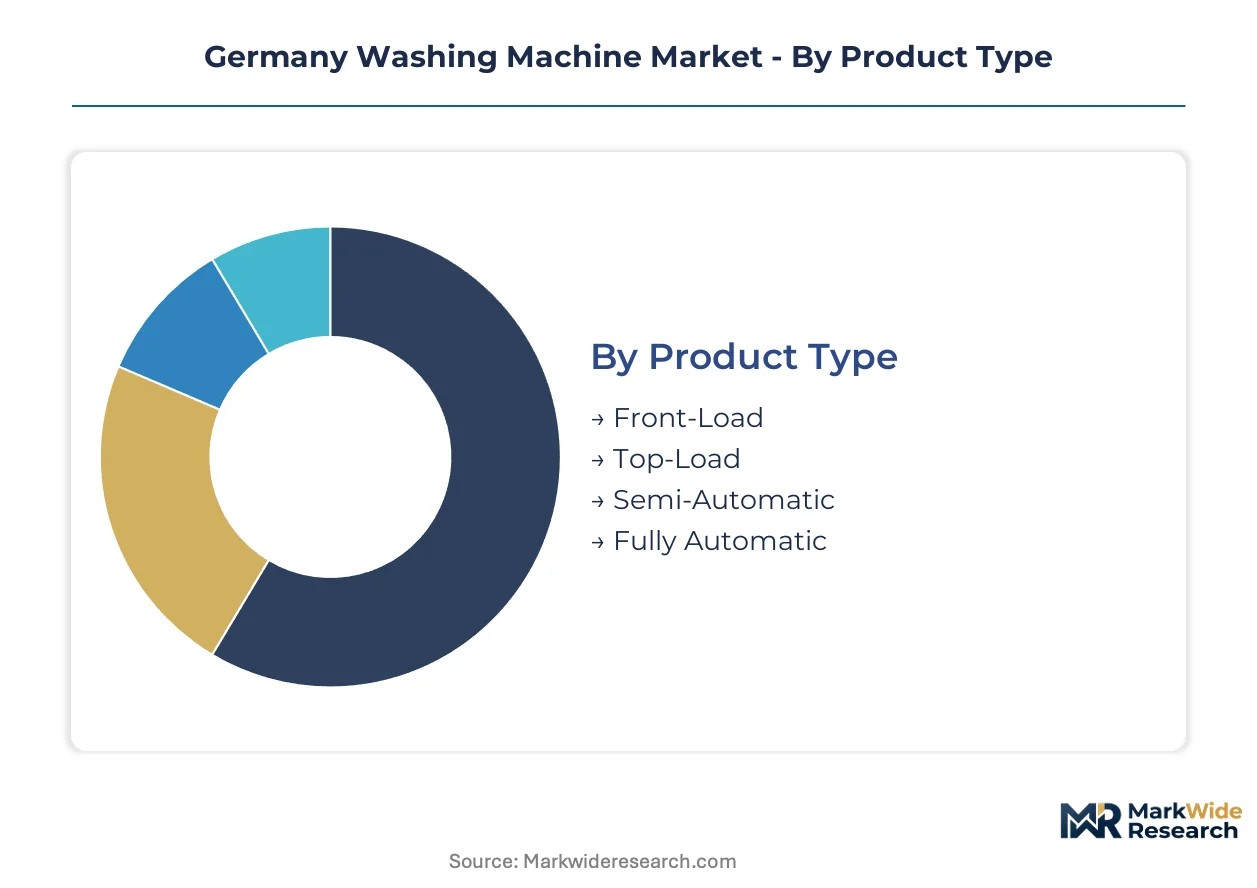
German washing machine procurement patterns diverge sharply across housing density, energy regulation exposure, and operational duty cycles. Manufacturers configure platform architectures around these fault lines to capture replacement pipelines and commercial service contracts.
Product Type:
Mature configurations dominate German retail, though emerging formats retain niche utility in specific dwelling types and price-sensitive channels.
- Front-Load:Horizontal-axis drum systems with superior water efficiency and stackability credentials. North Rhine-Westphalia multi-family developers specify these as standard fit-outs, driven by EU Ecodesign Regulation compliance requirements and space constraints in compact dwellings.
- Fully Automatic:Integrated water inlet, heating, and spin-dry sequences requiring minimal user intervention. Urban households in Berlin and Munich prioritize these platforms for noise reduction and program flexibility, though apartment footprints limit uptake of larger-capacity variants.
- Top-Load:Vertical-axis designs with faster cycle completion and reduced bending strain for users. Aging demographics in rural Bavaria sustain residual demand.
- Semi-Automatic:Segmented wash and spin tubs requiring manual water transfer. Price-sensitive single-person households in eastern Länder retain limited adoption.
Front-Load handles the majority of throughput; Fully Automatic is gaining share fastest among urban replacement cycles.
Technology:
Cost tier stratification separates premium motor platforms from baseline mechanical systems, with connectivity features penetrating mid-market price bands.
- Inverter:Direct-drive motor platforms eliminating belt transmission losses and enabling precision speed modulation. BSH Hausgeräte and Bosch leverage in-house production to control supply chains, while neodymium magnet costs from Chinese processing facilities expose margins to input volatility.
- Smart:Wi-Fi-enabled load detection, remote cycle management, and predictive maintenance alerts. Samsung competes aggressively on connected-home integration, penetrating mid-tier segments previously reserved for mechanical controls.
- Eco-Friendly:Heat-pump drying convergence and closed-loop water recirculation architectures. REACH compliance on fluorine-free seal coatings extends material qualification timelines for Baden-Württemberg component suppliers.
- Conventional:Belt-driven asynchronous motors with fixed-speed operation. Retail channels face markdown pressure on pre-2023 inventory lacking updated energy labels.
Inverter commands the deepest margin pools; Smart connectivity shows the steepest expansion trajectory as firmware requirements under the EU Cybersecurity Act reshape engineering priorities.
End User:
Application-based revenue concentration favors commercial channels with extended-service-contract potential over transactional household sales.
- Commercial:Hotels, laundromats, and institutional facilities with high-duty-cycle requirements. Miele sustains foothold through service bundling; Bavarian hotels and Baden-Württemberg institutions present underpenetrated demand for per-cycle pricing arrangements.
- Households:Single-family and multi-unit residential purchasers. BAFA-administered efficiency tiers steer preference toward A-rated drum systems, accelerating trade-in of aging appliances.
- Hotels:Dedicated hospitality procurement with brand-standard uniformity requirements. Facility operators in Hamburg and Frankfurt are unbundling capital expenditure from service coverage.
- Institutions:Hospitals, universities, and municipal facilities with tender-based acquisition. Procurement evolution concentrates buyer power with institutional channels.
Households handle the majority of throughput; Commercial is expanding most quickly as subscription-based maintenance bundles displace traditional warranty extensions.
Capacity:
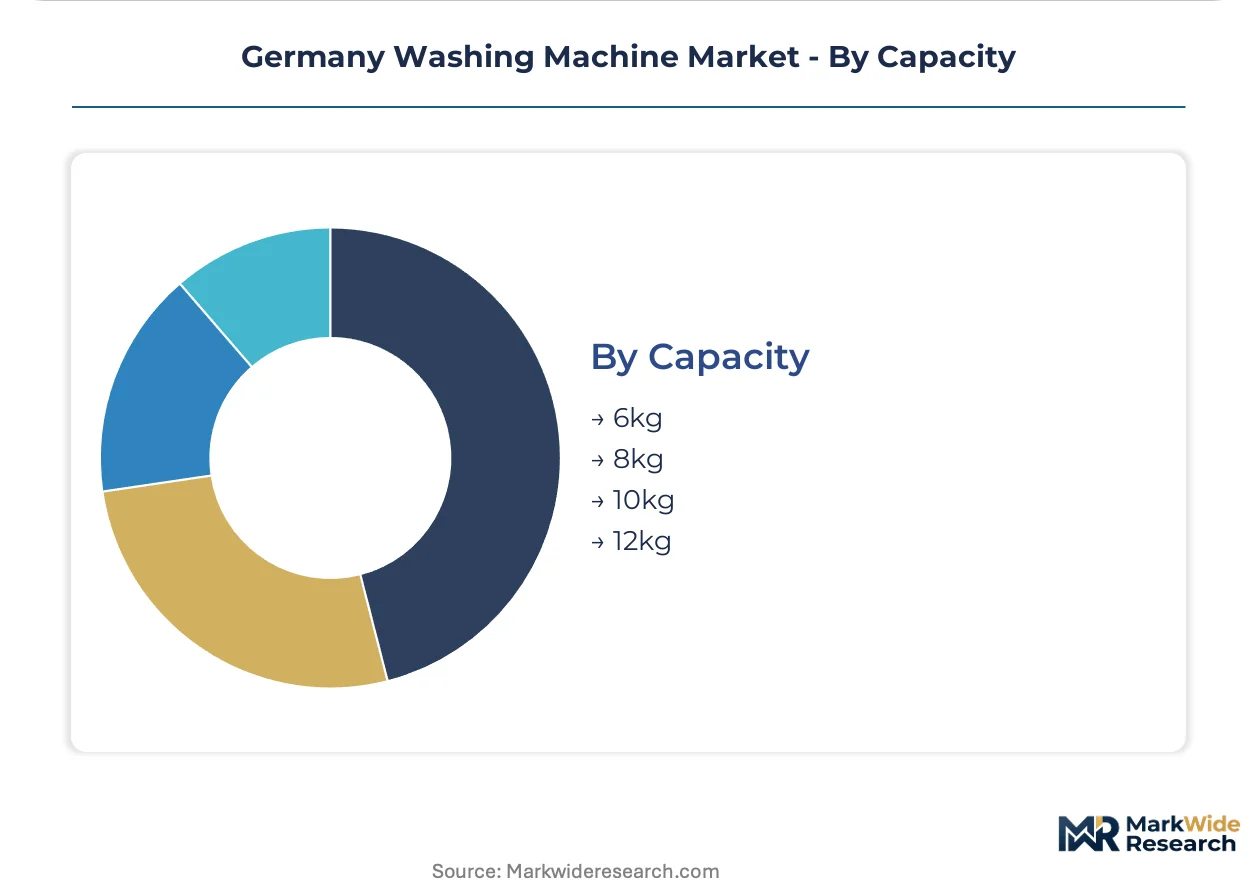
Volume-based segmentation reflects dwelling constraints and family size distribution across German urban centers.
- 8kg:Standard configuration for three-to-four-person households with moderate textile throughput. North Rhine-Westphalia developers specify this as baseline fit-out capacity.
- 6kg:Compact platforms for single-person and dual-income-no-kid households. Berlin and Munich apartment footprints sustain steady demand despite efficiency limitations.
- 10kg:Extended-family and small commercial applications. Space constraints in urban dwellings limit uptake regardless of efficiency gains.
- 12kg:High-capacity systems for commercial laundries and large households. Concentrated in suburban single-family zones with dedicated utility rooms.
8kg handles the majority of throughput; 10kg is climbing the fastest as multi-family developers upgrade baseline specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German washing machine production flows primarily toward neighboring European markets, with export corridors extending into France, the Netherlands, and Poland. Domestic absorption concentrates in urbanized western and southern Länder where multi-family housing density drives replacement cycles.
Bavaria
Hotel operators in Munich and Nuremberg sustain commercial-grade procurement with service-contract preferences. BAFA-administered efficiency tiers steer hospitality capital expenditure toward A-rated drum systems. Miele anchors high-capacity installations across Bavarian institutional facilities through extended maintenance bundling.
North Rhine-Westphalia
Multi-family developers in Cologne and Düsseldorf specify stackable front-load configurations as standard fit-outs. The EU Ecodesign Regulation mandates stricter water efficiency thresholds for new construction plumbing specifications. Component suppliers in the Ruhr industrial cluster accelerate inverter motor platform qualification for OEM integration.
Baden-Württemberg
REACH compliance complexity extends material qualification timelines for drum seal and gasket manufacturers. Stuttgart-area engineering firms validate fluorine-free elastomer formulations against durability benchmarks. BSH Hausgeräte leverages in-house motor production from regional manufacturing footprints to control supply chain exposure.
Berlin-Brandenburg
Compact dwelling footprints limit uptake of 10kg-plus capacity units regardless of efficiency gains. Apartment dwellers prioritize noise-reduction features in thin-walled residential stock. Samsung competes on connected-home integration for tech-forward households in the capital region.
Hamburg
Facility operators unbundle capital expenditure from service coverage, favoring per-cycle pricing arrangements. Commercial laundry services in the port city present underpenetrated demand for subscription-based maintenance bundles. Pending EU right-to-repair legislation concentrates spare-part availability planning among regional distributors.
Germany Washing Machine Market Vendor Landscape
On the supply side, the industry is moderately consolidated with tiered differentiation across motor platform control, connectivity integration, and service contract bundling. Established German engineering groups compete against Korean electronics conglomerates and Turkish value-oriented manufacturers. Two strategic archetypes dominate: vertically integrated motor producers capturing margin pools through captive inverter supply, and modular platform architects preparing for right-to-repair compliance. Competitive moves center on backward integration into rare-earth magnet sourcing and preemptive spare-part inventory positioning.
Among Germany-based engineering groups, BSH Hausgeräte and Miele exemplify divergent positioning strategies. BSH Hausgeräte anchors wholesale channels through modular platform designs with standardized component interfaces. Miele occupies the premium-service tier, sustaining foothold in commercial installations through extended contract arrangements. Samsung represents the Korean electronics archetype, competing on smart connectivity penetration into mid-market segments previously reserved for mechanical controls.
| Leading Market Players |
|---|
| Siemens |
| BSH Hausgeräte |
| Bosch |
| Samsung |
| LG Electronics |
| AEG |
| Bauknecht |
| Beko |
| Miele |
| Others |
Supply Flow & Price Mechanics
Ruhr industrial corridor freight costs from component suppliers to OEM assembly plants in North Rhine-Westphalia shape margin distribution across inverter motor tiers and downstream price bands for German washing machine distribution.
Pricing Analysis
The technology-generation pricing gap separates next-gen inverter platforms from conventional belt-driven systems and emerging smart-connected tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor efficiency certification and after-sales service bundling. Cost compression in entry-level segments is intensifying because retail channels face markdown pressure on pre-2023 inventory lacking updated BAFA energy labels. Commercial end users in hospitality and institutional channels demonstrate lowest price sensitivity due to per-cycle pricing arrangements, while single-person households in eastern Länder exhibit highest sensitivity.
Supply Chain Analysis
Upstream feedstock for neodymium rare-earth magnets concentrates in Chinese processing facilities, with secondary magnet fabrication anchored in Japan and Germany. Drum seal elastomers and fluorine-free gasket compounds draw from petrochemical suppliers in Belgium and the Netherlands. Single-source vulnerability in rare-earth magnet supply exposes inverter motor margins to commodity price volatility. Distribution runs through wholesale channels anchored by BSH Hausgeräte and specialized commercial laundry distributors serving hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany washing machine market represents high-growth disruption driven by EU right-to-repair legislation mandating modular platform architectures and spare-part availability obligations.
For Market Incumbents: Harden inverter motor supply chains through backward integration into rare-earth magnet sourcing or long-term offtake agreements with Chinese processors. Accelerate modular platform qualification to preempt right-to-repair compliance costs. Consolidate wholesale channel control before subscription-based maintenance bundles displace traditional warranty extensions among multi-unit property managers.
For New Entrants and Emerging Players: Pursue commercial laundry services in Bavarian hotels and Baden-Württemberg institutional facilities where per-cycle pricing arrangements remain underpenetrated. Target 8kg capacity segments in North Rhine-Westphalia multi-family construction as developers upgrade baseline specifications. Establish service-contract bundling capabilities to differentiate from transactional retail competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core appliance component divisions, particularly motor manufacturing and polymer seal suppliers. Five-to-ten year viability hinges on regulatory compliance positioning rather than volume scale. Monitor EU Cybersecurity Act firmware certification timelines as inflection indicator for engineering resource allocation across portfolio companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captures margin pools from Chinese processor concentration and stabilizes inverter motor cost structures. |
| Modular Platform Architecture Development | Positions manufacturers for EU right-to-repair spare-part availability mandates and reduces warranty exposure. |
| Subscription-Based Maintenance Bundling | Aligns revenue models with Hamburg and Frankfurt facility operators unbundling capital expenditure from service coverage. |
| Smart Connectivity Firmware Investment | Enables Samsung-style penetration of mid-tier segments previously reserved for mechanical control platforms. |
| Fluorine-Free Elastomer Qualification | Satisfies REACH compliance requirements for Baden-Württemberg drum seal manufacturers supplying OEM channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with product managers at BSH Hausgeräte and Miele, procurement directors at North Rhine-Westphalia multi-family developers, facility operators in Hamburg commercial laundries, and component engineers at Baden-Württemberg seal manufacturers. Secondary validation drew from BAFA energy labeling databases, EU Ecodesign Regulation implementation documents, REACH compliance filings with ECHA, and German customs trade statistics for washing machine component imports. Bottom-up unit shipment estimates across capacity tiers were triangulated against top-down value projections from wholesale channel revenue reporting.
Calibration against historical replacement cycle patterns and multi-family housing construction permits informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, motor technology tier, end-user channel, and drum capacity class. CAGRs were derived from regression analysis of efficiency regulation impacts on trade-in velocity and smart connectivity adoption curves. Industry-specific forecast inputs incorporated BAFA-administered energy label revision schedules and pending EU right-to-repair legislative timelines.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, neodymium magnet commodity prices, or euro-yuan exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology cost reduction curves. Quarterly review of multi-family housing permit data, REACH additive restriction updates, and inverter motor import volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Small Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Electrical Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
United States Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market