
 Americas Range Hood Market | 2026-2036
Americas Range Hood Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Range Hood Market Intelligence
Market Dynamics
Modular range hood configurations that separate blower units from canopy housings is hardening as the default specification for premium kitchen renovations. Whirlpool Corporation leverages its captive appliance distribution network to sustain bundled sales with cooking surfaces across North American home improvement channels. Samsung Electronics Co., Ltd. competes through connected-home integration, while Broan-NuTone, LLC anchors the replacement segment with broad contractor access.
Product Segmentation
Americas range hoods are mechanical ventilation appliances designed to capture, filter, and exhaust airborne grease, combustion products, smoke, heat, and steam from cooking surfaces, typically specified by airflow capacity measured in cubic feet per minute and noise levels rated in sones. Wall-mount and under-cabinet product types occupy the majority of residential volume, with island configurations commanding higher average prices due to ducting complexity and stainless steel dominating material specifications for durability and aesthetic compatibility. LED lighting and noise reduction features represent the fastest-growing feature attachments as builders respond to consumer preference for energy-efficient, quiet kitchen environments.
Regulatory Environment
The U.S. Department of Energy sets minimum efficiency standards for residential ventilation fans, while Health Canada and the Canadian Standards Association administer parallel certification requirements for cross-border product acceptance. The U.S. Environmental Protection Agency's ENERGY STAR program and California Title 24 building codes are tightening airflow efficiency thresholds, which forces manufacturers to redesign motor systems and filter geometries. Stakeholders must monitor evolving municipal electrification mandates and natural gas hookup restrictions, as these building code shifts directly alter the specification mix between ducted and recirculating ventilation architectures.
Market Dynamics
The U.S. Department of Energy's updated appliance efficiency standards are forcing motor and fan redesigns across North American manufacturing footprints, compressing margins for standardized product lines while rewarding modular, high-efficiency architectures.
Growth Catalysts
- Electrification mandates:Municipal natural gas hookup restrictions in California and New York are expanding specification demand for electric-compatible ventilation systems.
- Outdoor kitchen proliferation:Residential construction in Florida, Texas, and Arizona is accelerating demand for weather-resistant ducted hoods.
- Title 24 building codes:California's tightening airflow efficiency thresholds are pulling ENERGY STAR-certified products into baseline specification tiers.
Market Restraints
- Stainless steel price volatility:Raw material cost swings for 304-grade steel are compressing margin predictability for canopy fabricators.
- Supply concentration:Motor and blower assembly capacity clusters in Mexico and China, creating tariff and logistics exposure for North American OEMs.
- Installation complexity:Ducted system retrofit requirements in older housing stock limit replacement velocity in the northeastern United States.
Strategic Opportunities
- Underpenetrated Canadian market:Health Canada and CSA certification harmonization creates cross-border expansion paths for U.S. manufacturers with existing ENERGY STAR portfolios.
- Smart home convergence:Integration of range hoods with connected cooking surfaces and air quality sensors opens premium positioning in custom kitchen channels.
- IRA efficiency incentives:Federal tax credits for residential energy efficiency retrofits are subsidizing consumer upgrades to high-CFM, low-sones ventilation systems.
Industry Challenges
- Certification timeline compression:Simultaneous DOE rulemaking and state-level code updates are straining testing laboratory capacity and extending product launch cycles.
- Installation labor scarcity:Qualified HVAC technicians for ducted system commissioning are concentrated in metropolitan markets, limiting rural and exurban penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Range Hood Market |
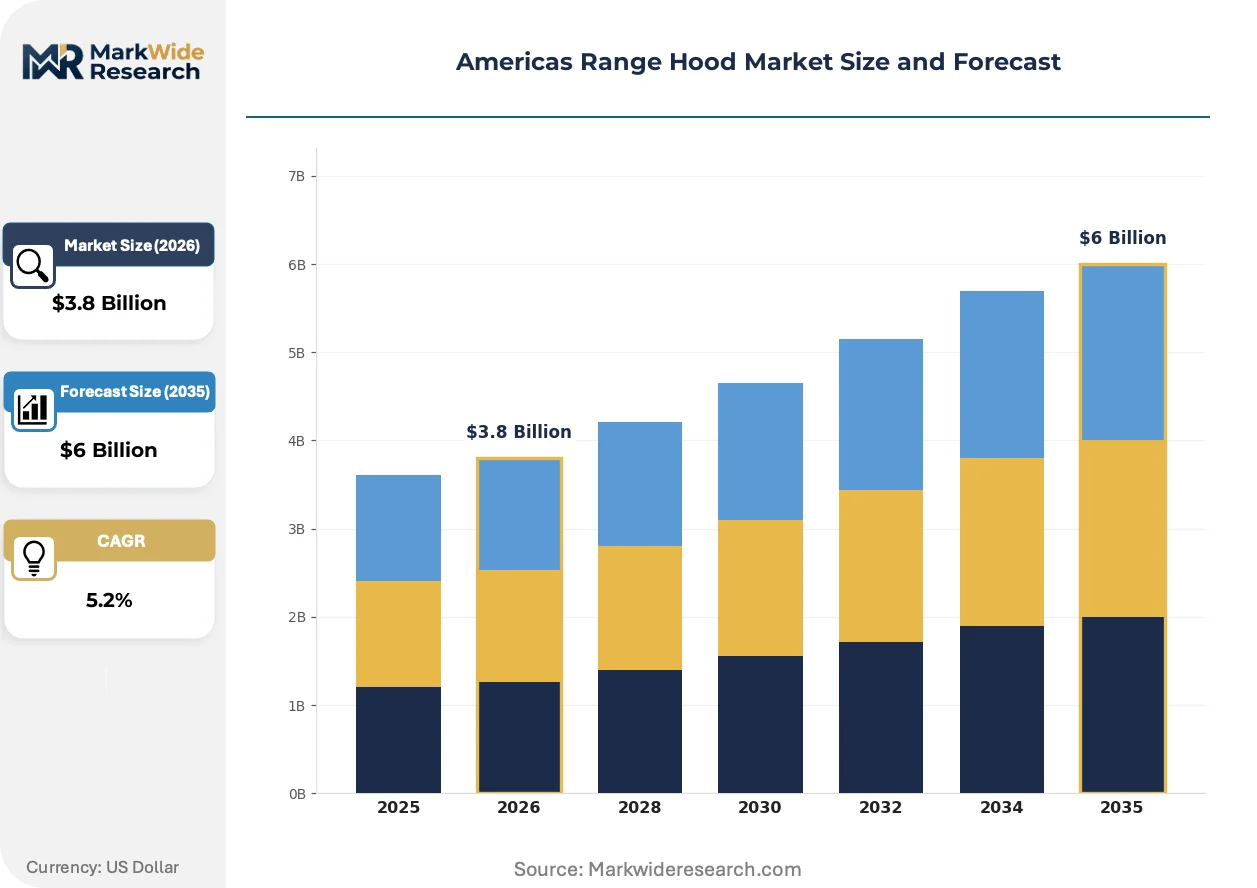
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mount, Under-Cabinet, Island, Ductless Material: Stainless Steel, Glass, Aluminum, Copper Feature: LED Lighting, Variable Speed, Noise Reduction, Touch Control Application: Residential, Commercial, Outdoor, Institutional |
| Companies Covered | Robert Bosch GmbH, Samsung Electronics Co., Ltd., Whirlpool Corporation, Zephyr Ventilation, LG Electronics Inc., Broan-NuTone, LLC, Electrolux AB, Faber S.p.A., GE Appliances, a Haier Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Range Hood Market Strategic Shifts & Innovations
Product architecture is fragmenting around three vectors: motor placement flexibility, sensing and automation integration, and material substitution for cost and weight reduction. Each vector carries distinct competitive implications for incumbents and entrants.
Remote blower technology is decentralizing the traditional range hood form factor by relocating motor units to attic or exterior wall positions. Premium kitchen designers in California and Texas are specifying these split-system configurations to reduce canopy noise and enable larger capture surfaces. This architecture is decentralizing supply chain relationships, as canopy fabricators now source blowers from specialized HVAC motor suppliers rather than integrated appliance divisions.
EPA ENERGY STAR Version 6.0 specifications for residential ventilation fans are tightening efficacy thresholds and introducing standby power limits. Manufacturers serving the U.S. market must redesign motor windings and control electronics to maintain certification eligibility. The southeastern United States, where cooling-dominated climates reduce heating penalty concerns, is seeing faster adoption of high-efficacy DC motor platforms than northern markets with greater makeup air cost sensitivity.
Builder procurement is consolidating around turnkey kitchen package specifications that bundle ventilation with cooking surfaces and refrigeration. National production homebuilders in Texas and Florida are shifting specification authority from local subcontractors to corporate purchasing departments, compressing vendor counts and privileging suppliers with multi-category portfolios. This concentration is most visible in the entry-level and first-move-up housing segments, where standardization overrides customization preferences.
Americas Range Hood Market Segmentation
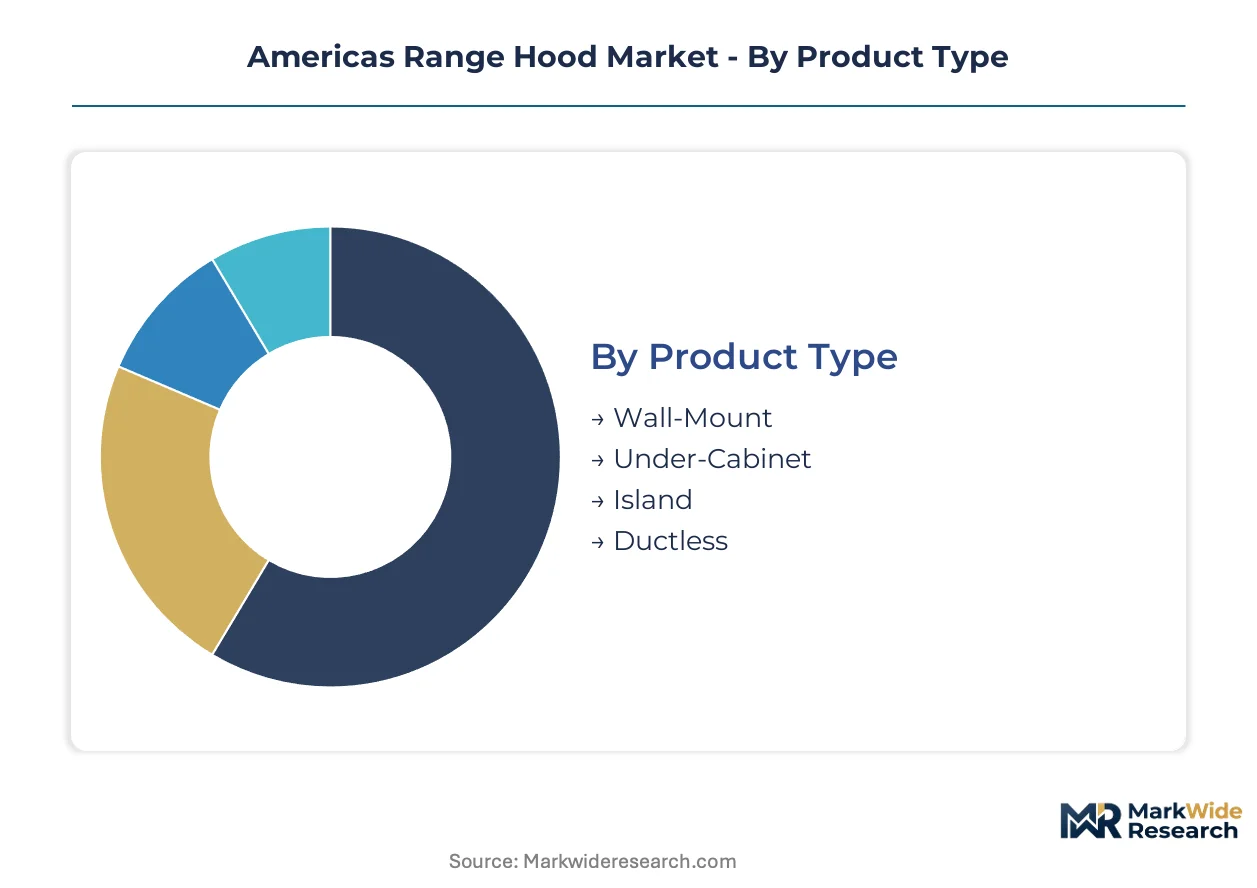
Americas range hood manufacturers configure product portfolios around kitchen architecture constraints, material durability requirements, and regional building code specifications. Segmentation discipline separates premium renovation demand from production builder specifications and identifies which feature attachments justify price premiums.
Product Type:
Customization intensity varies sharply across installation geometries, with island and wall-mount configurations demanding bespoke ducting solutions while under-cabinet units standardize around modular dimensions.
- Wall-Mount:Canopy designs affix directly to vertical wall surfaces above cooking ranges, typically specified in 30-inch and 36-inch widths to align with standard appliance footprints. Southeastern U.S. production homebuilders in Florida and Texas are standardizing wall-mount specifications across entire subdivisions, compressing SKU counts for regional distributors.
- Under-Cabinet:Compact hoods integrate beneath existing cabinetry, minimizing vertical clearance requirements and simplifying retrofit installations. Northeastern metropolitan markets with aging housing stock favor these configurations where duct routing through upper cabinets avoids structural modifications.
- Island:Ceiling-suspended canopies serve cooking surfaces without adjacent wall support, requiring concealed ducting through attic spaces or soffits. Premium kitchen renovations in California specify these for open-concept floor plans despite 40-60% higher installed costs.
- Ductless:Recirculating systems filter and return air to kitchens without exterior venting, mandated where municipal codes restrict penetrations in multi-family buildings. New York City and Chicago high-rise residential towers drive specification concentration.
Leading the category by volume: Under-Cabinet. Growing fastest: Island.
Material:
Cost tiers stratify around corrosion resistance, fabrication complexity, and aesthetic differentiation for visible kitchen surfaces.
- Stainless Steel:304-grade austenitic steel dominates residential specifications for oxidation resistance and compatibility with adjacent appliance finishes. Raw material price volatility from nickel supply fluctuations compresses margin predictability for canopy fabricators serving the replacement segment.
- Glass:Tempered glass canopies enable curved or planar aesthetic statements with integrated LED edge lighting. Contemporary kitchen designers in Miami and Los Angeles specify these for coastal properties where salt air accelerates metal corrosion.
- Aluminum:Lightweight extrusions reduce shipping costs and simplify ceiling-mount structural requirements for island configurations. Entry-level production builders in Texas and Arizona specify aluminum for cost-sensitive first-move-up housing segments.
- Copper:Antimicrobial surface properties and living-finish patina development command premium positioning in custom kitchen channels. Artisan fabricators in Colorado and Pacific Northwest markets serve renovation demand for distinctive visual signatures.
Stainless steel commands volume leadership. Glass surfaces are expanding most quickly in coastal metropolitan markets.
Feature:
Attachment rates for electronic and acoustic enhancements diverge between code-minimum builder specifications and consumer-driven renovation upgrades.
- LED Lighting:Solid-state illumination replaces halogen and incandescent sources, reducing energy consumption and heat generation at cooking surfaces. California Title 24 compliance mandates are accelerating attachment rates in new construction across the state.
- Variable Speed:Multi-stage motor control enables noise-acoustic tradeoffs during high-heat cooking versus low-speed continuous ventilation. ENERGY STAR Version 6.0 efficacy requirements favor electronically commutated motors with granular speed modulation.
- Noise Reduction:Sone rating improvements through remote blower placement and acoustic insulation address consumer complaints about kitchen conversation interference. Premium renovation specifications in Texas and Florida now standardize sub-5-sone operation at maximum CFM.
- Touch Control:Capacitive interfaces replace mechanical switches for cleanability and connected-home integration potential. Smart home convergence in custom California kitchens drives specification alongside WiFi-enabled cooking surfaces.
LED lighting leads feature attachment by unit volume. Noise reduction specifications are climbing fastest in premium renovation channels.
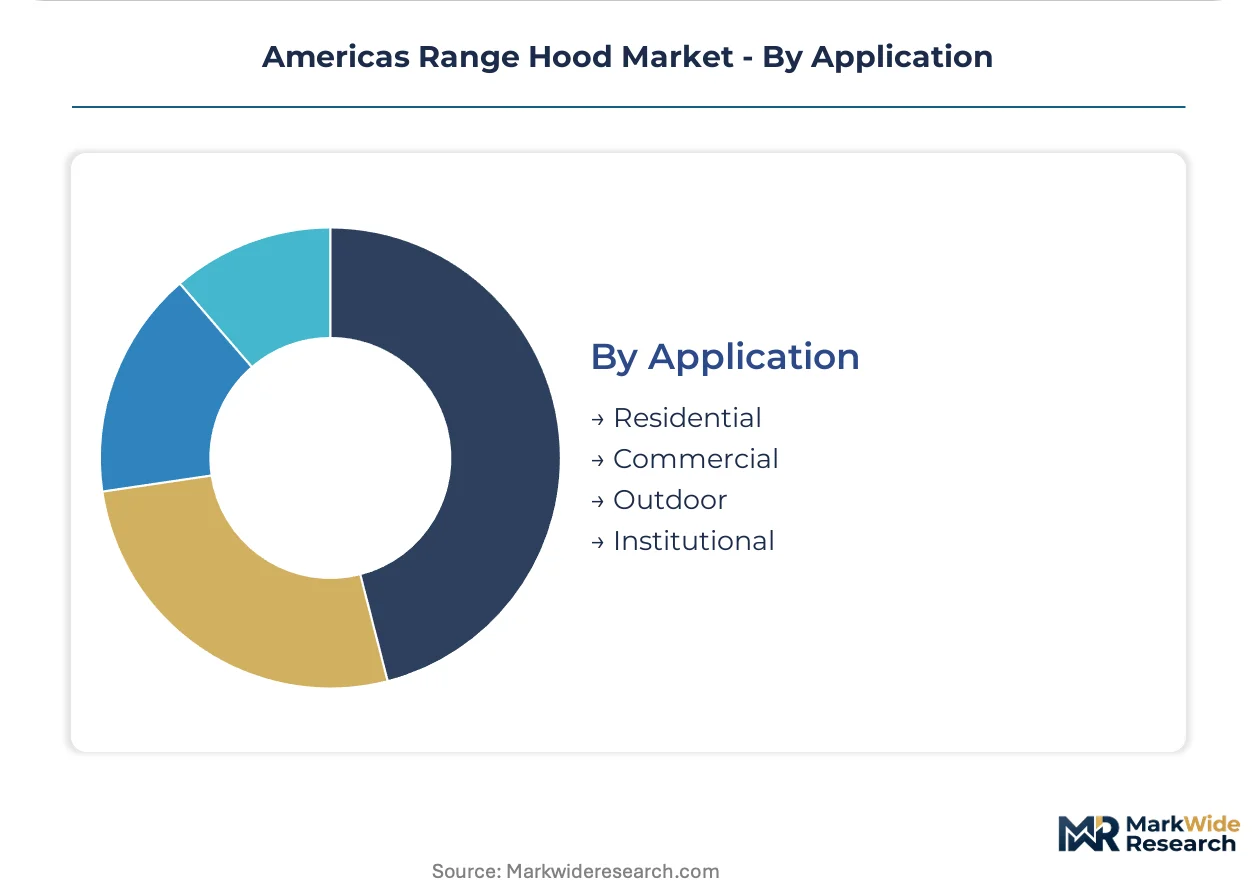
Application:
End-use concentration determines distribution channel requirements, with residential replacement demand flowing through home improvement retailers while commercial specifications route through foodservice equipment dealers.
- Residential:Single-family and multi-family dwellings account for the majority of unit volume, with replacement cycles accelerating as kitchen renovation activity expands. IRA efficiency incentives are subsidizing upgrades to high-CFM, low-sones systems in existing housing stock.
- Commercial:Restaurants, institutional cafeterias, and foodservice operations demand higher CFM ratings and fire suppression integration. Health department ventilation requirements in Florida and Texas drive mandatory replacement schedules for grease-laden exhaust systems.
- Outdoor:Weather-resistant ducted hoods serve exterior kitchen installations in climates with minimal freeze risk. Residential construction in Arizona and Nevada is expanding addressable base for marine-grade stainless specifications.
- Institutional:Schools, hospitals, and correctional facilities specify vandal-resistant controls and centralized monitoring capabilities. Federal procurement through GSA schedules concentrates volume for qualified suppliers with domestic manufacturing footprints.
Residential application dominates unit shipments. Outdoor configurations are gaining share fastest in Sun Belt construction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Mexico and China while consumption concentrates in the United States, creating cross-border supply dependencies that shape regional competitive dynamics. Tariff exposure and logistics costs are forcing North American OEMs to rebalance sourcing footprints. Regulatory divergence between national energy efficiency programs is fragmenting product specification requirements across the hemisphere.
United States
Residential kitchen renovation activity in the southeastern states is accelerating replacement cycles for ventilated cooking appliances. The Department of Energy's updated appliance efficiency standards are reshaping motor and fan specifications for domestic manufacturers. Atlanta and Dallas-Fort Worth metropolitan clusters are seeing concentrated demand from production homebuilders standardizing wall-mount configurations across entire subdivisions.
Canada
Health Canada and CSA certification harmonization creates cross-border expansion paths for U.S. manufacturers with existing ENERGY STAR portfolios. The country's national building code updates are tightening ventilation requirements for multi-family residential construction. Toronto and Vancouver metropolitan areas are driving specification demand for ductless recirculating systems in high-rise residential towers.
Mexico
Motor and blower assembly capacity concentrates in northern border states, creating tariff and logistics exposure for North American OEMs dependent on integrated supply chains. The Secretariat of Economy administers energy efficiency labeling requirements parallel to U.S. ENERGY STAR specifications. Monterrey and Tijuana industrial corridors are expanding manufacturing footprints to serve U.S. market demand with reduced cross-border transit times.
Brazil
Urban residential construction in São Paulo and Rio de Janeiro is expanding the addressable base for imported ventilation systems despite currency volatility challenges. ANVISA regulates product safety certification for electrical appliances entering the domestic market. Southeast regional distributors are consolidating procurement around Asian-origin products with competitive pricing for entry-level housing segments.
Americas Range Hood Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with appliance conglomerates leveraging captive distribution networks while ventilation specialists dominate premium renovation channels. The vendor base stratifies into three archetypes: multi-category appliance manufacturers with bundled sales capabilities, dedicated ventilation specialists with deep contractor relationships, and electronics conglomerates with connected-home integration platforms. Consolidation pressure is intensifying through strategic partnerships between canopy fabricators and specialized HVAC motor suppliers, alongside geographic expansion into underpenetrated Canadian markets.
Among diversified appliance conglomerates, Whirlpool Corporation and Samsung Electronics Co., Ltd. exemplify contrasting competitive approaches—Whirlpool leveraging its captive North American distribution network for bundled cooking surface sales, Samsung competing through connected-home integration platforms. Robert Bosch GmbH anchors the European-origin specialist tier with established ENERGY STAR certification portfolios. Broan-NuTone, LLC occupies a distinct position in the replacement segment through broad contractor access channels.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Samsung Electronics Co., Ltd. |
| Whirlpool Corporation |
| Zephyr Ventilation |
| LG Electronics Inc. |
| Broan-NuTone, LLC |
| Electrolux AB |
| Faber S.p.A. |
| GE Appliances, a Haier Company |
| Others |
Cost & Logistics Intelligence
London Metal Exchange nickel futures and 304-grade stainless steel spot indices cascade through canopy fabricator cost structures, compressing margin buffers for mid-tier suppliers while amplifying pricing power for vertically integrated manufacturers with captive metal sourcing.
Pricing Analysis
Margin tightening in the replacement segment reflects raw material volatility and concentrated buyer consolidation among national homebuilders. Three-tier pricing structure across premium, standard, and economy levels stratifies by motor efficiency certification and noise performance, with ENERGY STAR Version 6.0 compliance commanding tier separation. Pricing pressure stems from stainless steel cost swings and motor redesign requirements under DOE efficiency mandates. Production homebuilders in Texas and Florida exhibit highest price sensitivity, while custom kitchen renovation channels absorb premium positioning for remote blower architectures.
Supply Chain Analysis
Regional distribution centers in Atlanta, Dallas-Fort Worth, and Ontario hubs route finished goods through hub-and-spoke patterns serving contractor and retail channels. Motor and blower assembly capacity clusters in Mexico, China, and South Korea, with canopy fabrication concentrated in domestic U.S. and Canadian facilities. Raw material dependencies span 304-grade stainless steel, DC motor windings, and tempered glass substrates. Single-source vulnerability for specialized HVAC motor suppliers creates tariff exposure at the U.S.-Mexico border. Distribution runs through home improvement retailers for replacement demand and direct-to-builder programs for new construction specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized HVAC motor supplier capacity constraints prop pricing premiums for manufacturers with backward integration into blower production, creating a supply-constrained market structure favoring incumbent consolidation.
For Market Incumbents: Lock in captive motor supply through long-term offtake agreements with Monterrey and Tijuana assembly facilities. Expand ENERGY STAR certification portfolios ahead of California Title 24 code expansions to defend specification position against emerging connected-home entrants. For New Entrants and Emerging Players: Launch via direct-to-builder procurement channels targeting underpenetrated Canadian metropolitan markets with CSA-harmonized product lines. White-space concentration exists in ductless recirculating systems for New York and Chicago high-rise residential towers, with smart home integration as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors canopy fabricators with established contractor relationships and pending ENERGY STAR Version 6.0 certification. Long-term viability hinges on motor sourcing diversification and smart home platform compatibility. Watch ENERGY STAR specification adoption rates in southeastern U.S. production builder specifications as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive blower supply insulates margin compression from Mexico tariff exposure. |
| ENERGY STAR Version 6.0 Certification Investment | California Title 24 compliance pulls certified products into baseline specification tiers. |
| Smart Home Platform Integration | WiFi-enabled hoods command premium positioning in custom California kitchen channels. |
| Canadian Market Expansion | CSA harmonization creates cross-border paths for U.S. manufacturers with existing portfolios. |
| Remote Blower Architecture Development | Split-system configurations reduce canopy noise and enable larger capture surfaces in premium renovations. |
Research Approach
Department of Energy appliance efficiency filings, ENERGY STAR certification databases, and U.S. Census Bureau construction spending data formed the secondary backbone, supplemented by customs records tracking stainless steel and motor component trade flows. Primary interviews with HVAC contractor purchasing managers, kitchen designer specification consultants, production homebuilder procurement directors, and ventilation product R&D heads validated demand assumptions and pricing dynamics. Bottom-up unit shipment estimates triangulated against top-down construction spending allocation models.
Historical trendline analysis across residential renovation expenditure patterns and new housing completion rates informed baseline demand calibration. Segmentation modeling incorporated product type, material specification, feature attachment, and application end-use dimensions across the projection horizon. CAGRs derived from regression-weighted growth rate synthesis, with motor efficiency standard adoption curves and municipal electrification mandate propagation as industry-specific forecast inputs.
DOE rulemaking timeline delays, stainless steel price volatility spikes, and qualified HVAC technician labor scarcity are the dominant revision risks to shipment forecasts. Outputs reflect documented assumptions around regulatory compliance timelines and material cost stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Electric Household Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
India Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Household Refrigerators and Freezers Market