
 China Small Home Appliances Market | 2026-2036
China Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
China Small Home Appliances Market Outlook
Aftermarket service revenue is fragmenting across brand-certified networks and third-party repair platforms in China. Midea Group leverages its nationwide service infrastructure to capture recurring maintenance contracts. Supor anchors premium replacement-part sales through proprietary distribution. Haier competes by integrating subscription-based filter and accessory replenishment into its smart appliance ecosystem.
China small home appliances encompass compact electrically powered devices designed for domestic food preparation, beverage heating, and light culinary processing, typically operating at 220V with power ratings below 2,000 watts and constructed from food-grade stainless steel, borosilicate glass, or BPA-free polymer housings. These products serve primary commercial purposes across household meal preparation and commercial food service settings where space constraints and operational flexibility dominate procurement criteria. Rice cookers and electric kettles occupy the largest volume positions within the product type dimension, sustained by replacement-driven purchasing in tier-two and tier-three cities. Smart appliances within the technology dimension command expanding margin pools as MIIT interoperability standards and voice-control integration reshape consumer upgrade behavior. Online retailers dominate distribution channel growth, displacing hypermarket foot traffic through live-streaming commerce and same-day fulfillment networks.
GB standards issued by China's national standardization administration and MIIT smart-device certification requirements shape product design cycles and market access thresholds for domestic manufacturers. Energy-efficiency labeling mandates under the national green procurement program redirect consumer preference toward certified models. Stakeholders must monitor evolving interoperability protocols and provincial subsidy programs to align portfolio positioning with regulatory-driven replacement waves.
Market Dynamics
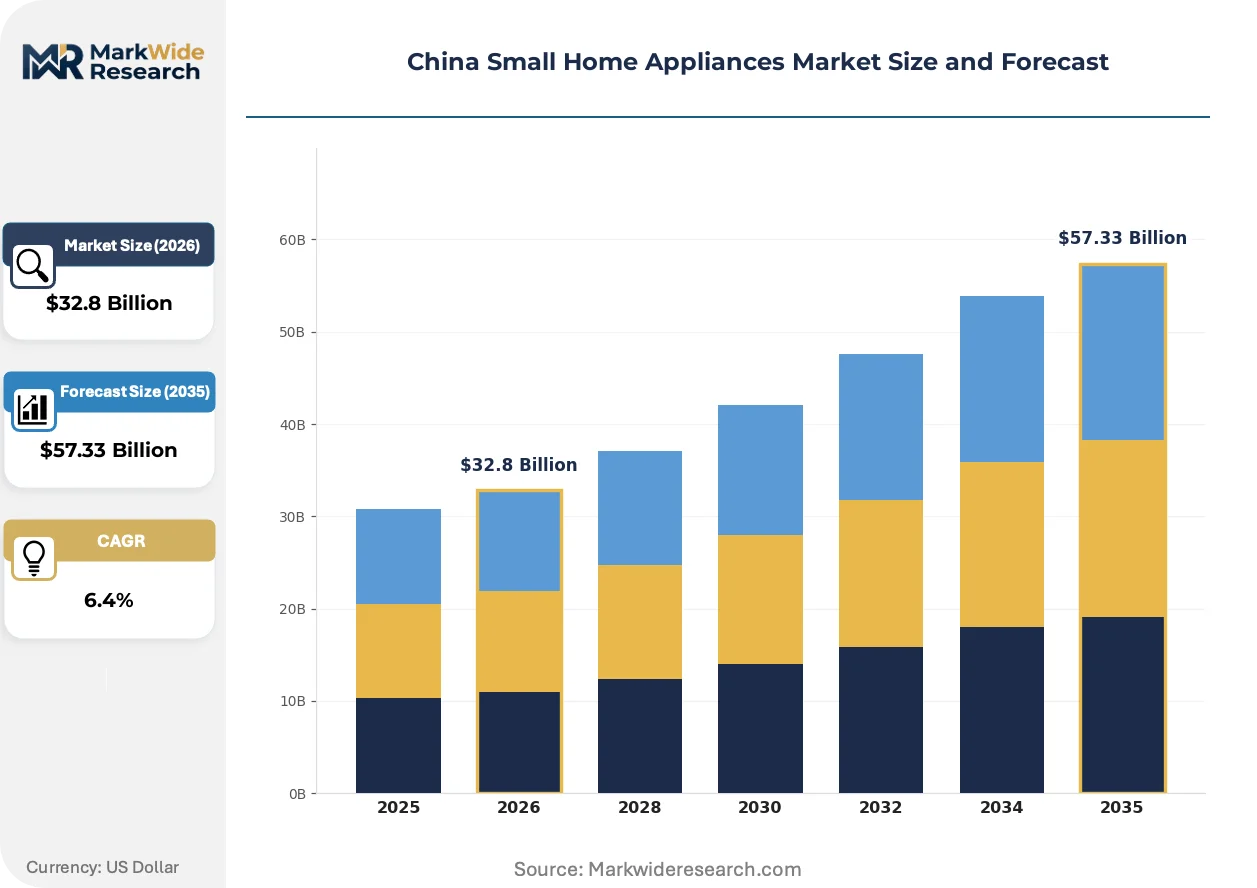
MIIT smart-home interoperability mandates and GB energy-efficiency standards are compressing product refresh cycles across China's small home appliances sector, forcing manufacturers to redesign control systems and thermal architectures ahead of regulatory deadlines.
Growth Catalysts
- GB Energy-Efficiency Labeling:National green procurement programs redirect consumer preference toward certified models, accelerating replacement purchases in tier-two and tier-three cities.
- Voice-Control Integration:Smart speaker ecosystems from Baidu, Alibaba, and Tencent are embedding appliance control into daily routines, expanding upgrade willingness among young urban households.
- Guangdong Manufacturing Clusters:Concentrated component supply and assembly capacity near Shenzhen and Foshan compress lead times and enable rapid prototype-to-production scaling.
Market Restraints
- Copper and Rare Earth Volatility:Heating element and motor winding costs fluctuate with commodity markets, squeezing margin predictability for mid-tier manufacturers.
- Single-Source Chip Dependency:Microcontroller supply concentrates among domestic semiconductor foundries, creating vulnerability to allocation constraints during demand spikes.
- Appliance Longevity:Durable mechanical designs in traditional rice cookers and kettles extend replacement intervals beyond the smart-upgrade cycle.
Strategic Opportunities
- Western Province Penetration:Sichuan and Shaanxi households remain underpenetrated for smart-connected devices, offering first-mover positioning before infrastructure saturation.
- Commercial Food Service:Compact appliance demand from cloud kitchens and boutique cafes in Chengdu and Hangzhou outpaces residential growth rates.
- Provincial Subsidy Programs:Municipal governments in Jiangsu and Zhejiang issue trade-in incentives for energy-efficient replacements, subsidizing consumer upgrade decisions.
Industry Challenges
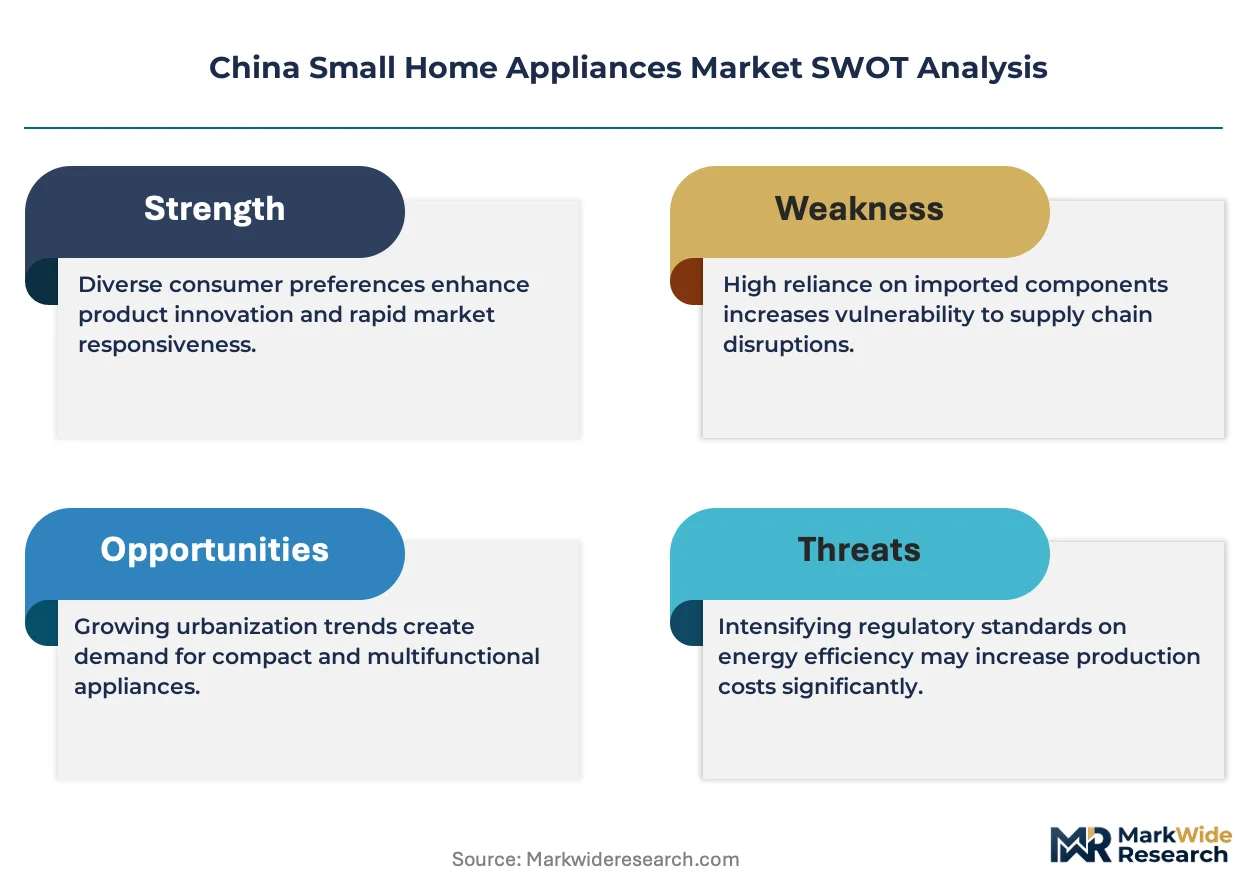
- Firmware Integration Complexity:MIIT certification requires seamless interoperability across competing smart-home protocols, extending development timelines.
- Aftermarket Service Scaling:Nationwide maintenance networks struggle to match the geographic dispersion of smart-enabled products, fragmenting customer retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Small Home Appliances Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toasters, Blenders, Electric Kettles, Rice Cookers End User: Households, Restaurants, Cafes, Catering Services Technology: Smart Appliances, Manual Appliances, Energy-efficient Devices, Multi-functional Units Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Supor, Galanz Group, Midea Group, Skyworth, TCL Corporation, Haier, Joyoung, Konka Group, Gree Electric Appliances Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Small Home Appliances Market Strategic Shifts
Control architectures and thermal management systems are converging around connected intelligence, with regulatory pressure and platform economics accelerating the obsolescence of electromechanical designs.
Induction heating technology is migrating from premium rice cookers into mid-range electric kettles and multi-function pots. Young professional households in Shanghai and Shenzhen are adopting these models at twice the rate of conventional resistive heating. The shift is compressing price premiums for precision temperature control, forcing legacy manufacturers to redesign core thermal platforms.
GB standards for standby power consumption and MIIT interoperability certification are tightening market access thresholds. Manufacturers must submit control firmware for protocol compliance testing before retail distribution. Small appliance categories with high smart-feature penetration face the steepest redesign costs and shortest certification windows.
Live-streaming commerce is displacing hypermarket foot traffic as the primary discovery channel for small appliance purchases. Influencer-hosted demonstrations on Douyin and Kuaishou generate same-day fulfillment demand, compressing traditional retail inventory cycles. This channel shift concentrates marketing spend among platform-native brands with direct factory relationships.
China Small Home Appliances Market Segmentation
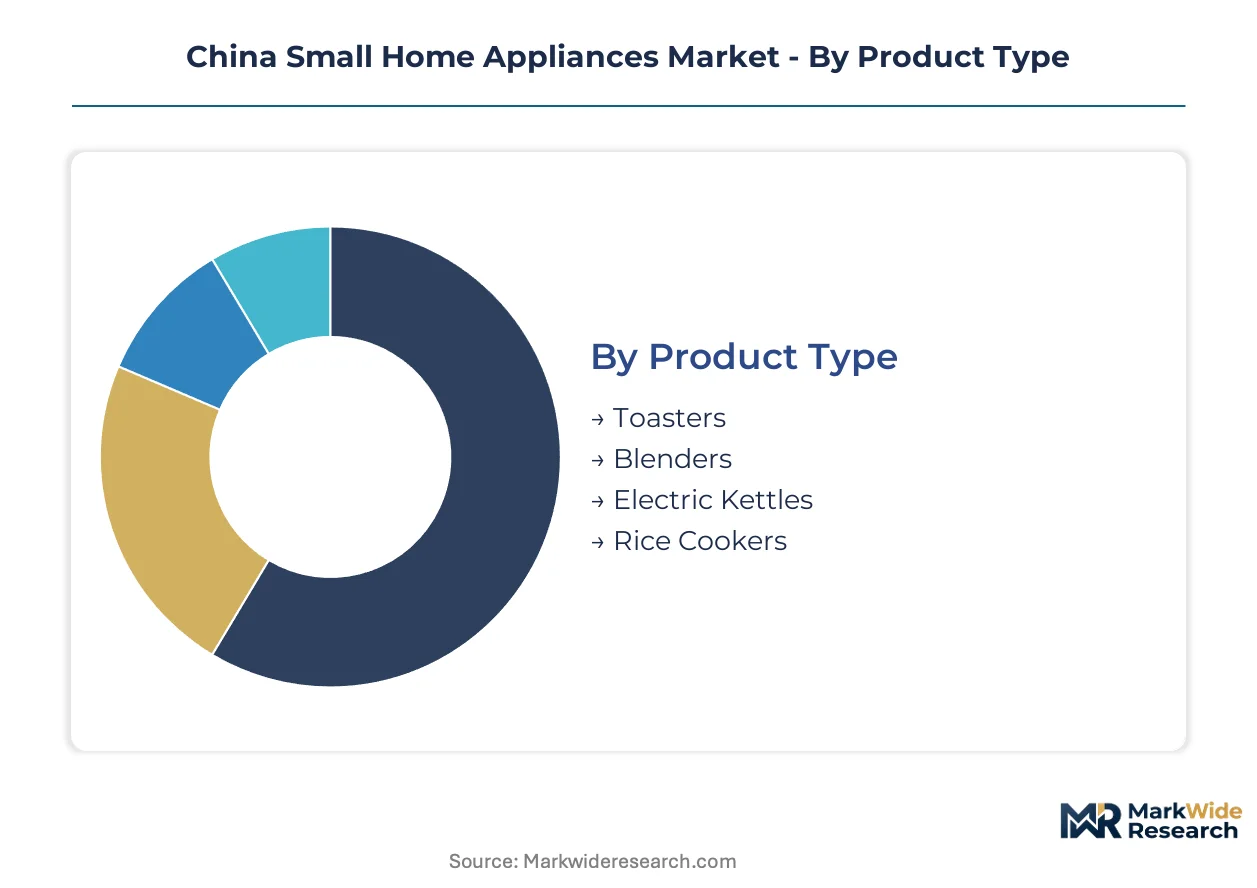
Segmentation reveals how China's small home appliances market fractures across cooking rituals, procurement channels, and digital maturity levels. Understanding these divides exposes where replacement cycles compress and where smart-premium pricing commands sustainable margins.
Product Type:
Cost tier stratification separates commodity replacement purchases from technology-forward upgrades in Chinese kitchens.
- Rice Cookers:These appliances incorporate fuzzy-logic microprocessors and induction heating coils for precision temperature curves. Demand clusters in tier-two and tier-three cities where replacement-driven purchasing dominates, accelerated by GB energy-efficiency labeling mandates that disqualify legacy resistive models.
- Electric Kettles:Borosilicate glass and 304 stainless steel housings with gooseneck spouts serve pour-over coffee enthusiasts. Shanghai and Shenzhen households are upgrading to variable-temperature models at twice the rate of conventional kettles, compressing price premiums for precision control.
- Blenders:High-torque brushless motors with food-grade Tritan vessels target smoothie preparation and nut-milk processing.
- Toasters:Compact two-slice and four-slice configurations with quartz heating elements serve breakfast preparation in space-constrained urban apartments.
Rice cookers hold installed capacity. Electric kettles are rotating up the share rankings.
End User:
Application context dictates durability specifications, batch capacity requirements, and connectivity feature penetration across Chinese consumption environments.
- Households:Domestic meal preparation drives volume through compact footprints and 220V single-phase operation. Young urban households in coastal provinces are integrating voice-controlled appliances into Baidu and Alibaba smart speaker ecosystems, expanding upgrade willingness.
- Restaurants:Commercial food service demands NSF-certified materials and continuous-duty thermal management. Cloud kitchens in Chengdu and Hangzhou are procuring compact multi-function pots at growth rates outpacing residential channels.
- Cafes:Boutique beverage preparation requires precision temperature stability and aesthetic counter presence.
- Catering Services:High-volume batch processing prioritizes rapid heat recovery and standardized output consistency.
Households anchor volume absorption. Restaurants are climbing the fastest as commercial kitchen automation accelerates.
Technology:
Customer type segmentation separates electromechanical simplicity from firmware-dependent interoperability in MIIT certification pathways.
- Smart Appliances:Wi-Fi-enabled control architectures with MIIT protocol compliance and voice-assistant integration. Young professional households are adopting these models at steep premiums, though firmware integration complexity extends development timelines and certification windows.
- Energy-efficient Devices:Standby power reduction and optimized thermal insulation meeting GB labeling thresholds. National green procurement programs redirect consumer preference toward certified models, subsidizing upgrade decisions through provincial trade-in incentives.
- Manual Appliances:Electromechanical controls without connectivity modules serving price-sensitive replacement demand.
- Multi-functional Units:Consolidated cooking platforms combining pressure cooking, air frying, and slow cooking in single footprints.
Manual appliances retain installed base depth. Smart appliances are gaining share fastest as interoperability mandates compress refresh cycles.
Distribution Channel:
Geography and logistics infrastructure determine where discovery happens and how fulfillment speed shapes purchase completion.
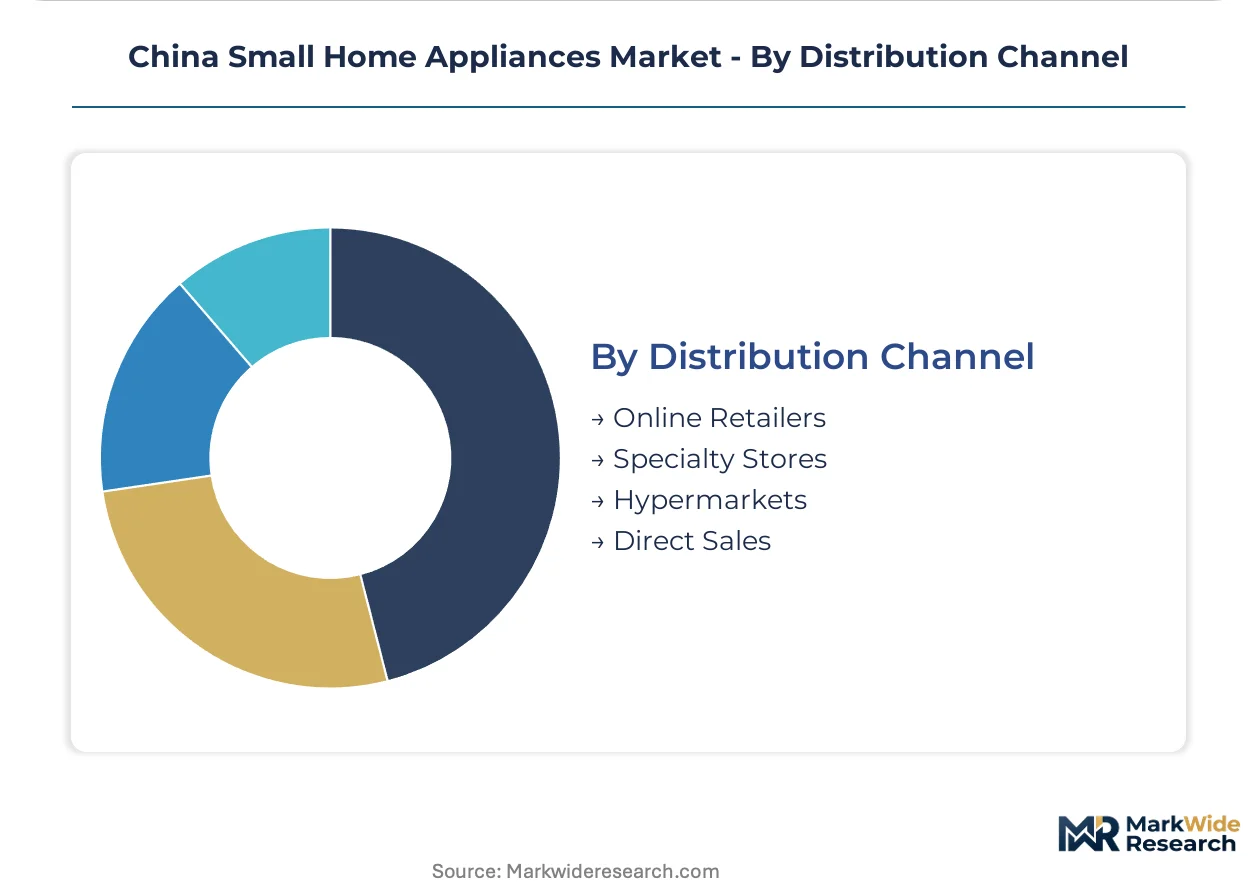
- Online Retailers:Douyin and Kuaishou live-streaming commerce with same-day fulfillment networks displacing traditional retail. Influencer-hosted demonstrations generate impulse demand, compressing inventory cycles for factory-direct brands with Guangdong manufacturing proximity.
- Hypermarkets:Big-box retail with physical inspection and immediate takeaway serving older demographics and emergency replacement needs.
- Specialty Stores:Curated premium positioning with demonstration kitchens and extended warranty attachments.
- Direct Sales:Manufacturer-controlled channels capturing full margin and customer relationship data.
Hypermarkets hold legacy foot traffic. Online retailers are rotating up the share rankings as live-streaming commerce captures discovery and fulfillment in unified journeys.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Chinese provinces. Coastal manufacturing clusters absorb premium smart-appliance upgrades while interior markets remain replacement-driven and cost-sensitive.
Yangtze River Delta
Shanghai and Jiangsu households drive smart-kettle and induction-cooker upgrades through live-streaming commerce channels. Jiangsu provincial subsidies under the national green procurement program subsidize energy-efficient replacements. Manufacturing concentrates in Suzhou and Ningbo where component suppliers cluster around induction-coil and microcontroller assembly.
Pearl River Delta
Shenzhen young professionals adopt voice-integrated appliances at steep premiums, compressing conventional product cycles. Guangdong provincial trade-in incentives accelerate GB-certified model turnover. Foshan anchors assembly capacity with same-day fulfillment networks reaching Guangzhou and Shenzhen within four hours.
Sichuan-Chongqing
Chengdu cloud kitchens and boutique cafes procure compact multi-function pots at growth rates outpacing residential channels. Chongqing municipal energy-efficiency labeling enforcement redirects procurement toward certified models. Local distributors in the twin-city corridor struggle to match coastal logistics speeds, fragmenting smart-appliance penetration.
Shandong Peninsula
Qingdao and Jinan households display moderate upgrade willingness for rice cookers with fuzzy-logic controls. Shandong provincial standards enforcement lags coastal provinces by 12-18 months, extending legacy product shelf life. Weihai hosts specialty stainless-steel component foundries serving premium kettle manufacturers.
Western China
Shaanxi and Gansu markets remain underpenetrated for Wi-Fi-enabled devices, with manual appliances dominating replacement purchases. Xi'an municipal infrastructure investment lags coastal smart-city deployments by several years. Local retailers in the interior rely on hypermarket foot traffic with limited live-streaming commerce integration.
China Small Home Appliances Market Competitive Environment
Diversified conglomerates and specialized appliance houses split the market along vertical-scope lines. The vendor base concentrates among five to eight dominant groups with tiered national distribution networks. Strategic archetypes span full-range diversified manufacturers, single-category specialists, and platform-integrated ecosystem players. Competitive moves center on backward integration into component supply and exclusive live-streaming commerce partnerships with Douyin and Kuaishou influencers.
Among diversified Chinese conglomerates, Midea Group and Haier occupy positions as ecosystem-integrated manufacturers with captive service networks. Supor represents the specialist archetype, anchoring premium replacement-part revenue through proprietary distribution control. These three exemplify how scale and vertical scope determine margin capture across GB-certified and smart-interoperable product tiers.
| Leading Market Players |
|---|
| Supor |
| Galanz Group |
| Midea Group |
| Skyworth |
| TCL Corporation |
| Haier |
| Joyoung |
| Konka Group |
| Gree Electric Appliances Inc |
| Others |
Value Chain & Pricing Dynamics
The Guangzhou-Shenzhen expressway freight corridor compresses logistics costs for Guangdong-based manufacturers while amplifying price differentiation between coastal smart-appliance exporters and inland manual-product distributors. This corridor's same-day delivery radius feeds live-streaming commerce velocity, tightening margin structures for brands without factory-direct fulfillment networks.
Pricing Analysis
Aftermarket service revenue tiers—spanning proprietary replacement parts, subscription-based filter replenishment, and extended maintenance contracts—drive lifetime value capture for ecosystem-integrated manufacturers. Three-tier pricing structure across premium smart-connected, standard energy-efficient, and economy manual levels stratifies the market, with MIIT certification costs and voice-control integration widening spreads between tiers. Cost compression in mid-range induction heating models is intensifying because legacy resistive-platform manufacturers must absorb redesign expenses to maintain retail placement. Young professional households in Shanghai and Shenzhen display lowest price sensitivity for voice-integrated appliances, while tier-three city replacement buyers anchor the economy tier.
Supply Chain Analysis
Supplier-financing facilities extended by Guangdong component foundries and Zhejiang induction-coil manufacturers compress working capital cycles for assembly plants. Manufacturing concentrates in China with critical microcontroller sourcing from domestic semiconductor foundries and heating-element materials drawing from Jiangxi rare-earth processors. Single-source chip dependency creates vulnerability to allocation constraints during live-streaming commerce demand spikes. Distribution runs through Douyin and Kuaishou live-streaming platforms with same-day fulfillment networks displacing hypermarket inventory cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in MIIT interoperability certification entrenchment, where compliance investment creates switching costs that lock in ecosystem-integrated incumbents.
For Market Incumbents: Insulate installed-base retention by deepening captive service infrastructure across western provinces before infrastructure saturation, while accelerating proprietary voice-assistant integration to preempt Baidu and Alibaba platform dependency. Threat from single-category specialists with factory-direct influencer partnerships demands backward integration into induction-coil supply to defend margin compression. For New Entrants and Emerging Players: Build out white-space positioning in Sichuan and Shaanxi cloud-kitchen commercial channels where smart-appliance penetration lags coastal saturation by several years. The most penetrable segment lies in compact multi-function pots for Chengdu boutique cafes, accessible through direct Douyin live-streaming partnerships bypassing legacy distributor markups. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with undermonetized small-appliance divisions lacking MIIT certification infrastructure. Long-term viability hinges on regulatory compliance scalability rather than manufacturing scale alone. Watch provincial subsidy program expansion into interior provinces as inflection signal for replacement-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Interoperability Certification Investment | GB standards and MIIT mandates compress product refresh cycles, forcing firmware redesign ahead of regulatory deadlines. |
| Live-Streaming Commerce Partnership | Douyin and Kuaishou influencer-hosted demonstrations displace hypermarket discovery with same-day fulfillment velocity. |
| Western Province Service Infrastructure Buildout | Sichuan and Shaanxi underpenetration offers first-mover positioning before logistics networks match coastal speeds. |
| Commercial Food Service Channel Expansion | Chengdu and Hangzhou cloud kitchens procure compact appliances at growth rates outpacing residential channels. |
| Energy-Efficiency Labeling Alignment | National green procurement programs redirect consumer preference toward GB-certified models with provincial trade-in subsidies. |
Study Parameters
The analysis maps rice cooker, electric kettle, and smart-connected appliance sub-sectors, each validated through manufacturing plant managers, live-streaming commerce platform category buyers, MIIT certification consultants, and aftermarket service network operators. Primary interview intelligence triangulates against customs export records, SAMR product registration databases, provincial subsidy program disclosures, and GB standards administration filings. Bottom-up unit economics from Guangdong and Zhejiang assembly clusters reconcile with top-down consumer expenditure surveys across coastal and interior provinces.
Assumption sets held MIIT certification timelines and copper commodity price bands fixed across the projection horizon, while voice-control adoption curves and provincial subsidy program coverage were varied. Segmentation dimensions modeled include product type, technology tier, distribution channel, and end-use application. CAGRs derive from replacement-cycle compression rates and smart-feature penetration slopes, with induction heating platform migration and live-streaming commerce channel share as primary forecast inputs.
Stress conditions across rare-earth price volatility, microcontroller allocation constraints, and western province logistics infrastructure buildout were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and consumer upgrade willingness. Macroeconomic deviation, accelerated MIIT protocol revision, or supply chain regionalization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Europe Laundry Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
UAE Major Home Appliances Market