
 India Home Appliances Market | 2026-2036
India Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
India Home Appliances Market Outlook
Modular kitchen appliance bundling is realigning how Indian households configure their cooking and cooling ecosystems. Samsung India leverages its integrated ecosystem strategy to cross-sell refrigerators with connected microwave ovens. LG Electronics India anchors its position through inverter compressor technology leadership across premium air conditioner lines. Whirlpool of India sustains manufacturing scale at its Pune and Faridabad plants to serve price-sensitive semi-urban buyers.
India home appliances comprise electromechanical devices designed for domestic tasks, typically operating on 230V/50Hz single-phase supply with Bureau of Energy Efficiency star ratings from 1 to 5 indicating power consumption efficiency. Refrigerators dominate volume shipments due to near-universal electrification and rising food preservation needs in tropical climates, though air conditioners represent the fastest-expanding margin pool as heat waves intensify and inverter technology penetrates middle-income households. Smart Technology features within the Feature segment are commanding premium pricing, while Compact Design variants are capturing space-constrained urban apartments in Mumbai and Bengaluru.
BIS mandates star-label compliance for refrigerators and air conditioners, while the PLI scheme for white goods manufacturing is reshaping supply chain localization requirements and tariff structures. FSSAI guidelines on food storage temperatures indirectly drive demand for precision-cooling refrigerator compartments. Stakeholders must monitor state-level electricity tariff reforms and DISCOM financial health, as subsidized power access in agricultural regions directly constrains rural appliance penetration timelines.
Market Dynamics
PLI scheme disbursements for white goods manufacturing are compressing component import dependence and rewiring supplier economics across Maharashtra and Tamil Nadu production corridors.
Growth Catalysts
- BIS star-label mandates:Mandatory energy-efficiency labeling for refrigerators and air conditioners forces technology upgrades across domestic manufacturers, accelerating inverter compressor adoption.
- Tier-II urbanization:Semi-urban households in Gujarat and Karnataka are upgrading from direct-cool to frost-free refrigeration systems as electrification reliability improves.
- Inverter technology maturation:Variable-speed compressor platforms reduce power consumption by 30-50% versus fixed-speed alternatives, expanding addressable middle-income demand in heat-stressed climates.
Market Restraints
- Copper-aluminum price volatility:Refrigeration coil and motor winding costs fluctuate with London Metal Exchange pricing, compressing gross margins for price-locked retail contracts.
- DISCOM financial stress:State electricity distribution companies in Uttar Pradesh and Bihar delay rural grid upgrades, capping appliance penetration in agricultural belts.
- Technical workforce scarcity:Certified inverter compressor repair technicians concentrate in Mumbai, Delhi, and Bengaluru, leaving tier-III service networks dependent on untrained third-party technicians.
Strategic Opportunities
- Modular kitchen bundling:Integrated refrigerator-microwave-dishwasher packages capture higher per-transaction value from new apartment buyers in Pune and Hyderabad.
- Smart appliance convergence:Wi-Fi-enabled inventory tracking and energy monitoring platforms differentiate premium lines for tech-forward households in Bengaluru.
- PLI localization incentives:Component manufacturing subsidies for compressors and heat exchangers attract capital expenditure toward Andhra Pradesh and Tamil Nadu industrial zones.
Industry Challenges
- Certification timeline compression:BIS laboratory capacity constraints delay star-rating approvals for new inverter models, extending product launch windows by 4-8 months.
- After-sales network fragmentation:Authorized service centers fail to cover tier-III towns, forcing reliance on independent repair shops that void warranty coverage.
- Legacy inventory clearance:Fixed-speed refrigerator stockpiles in distributor warehouses resist price reduction, blocking capital rotation toward inverter platform investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Home Appliances Market |
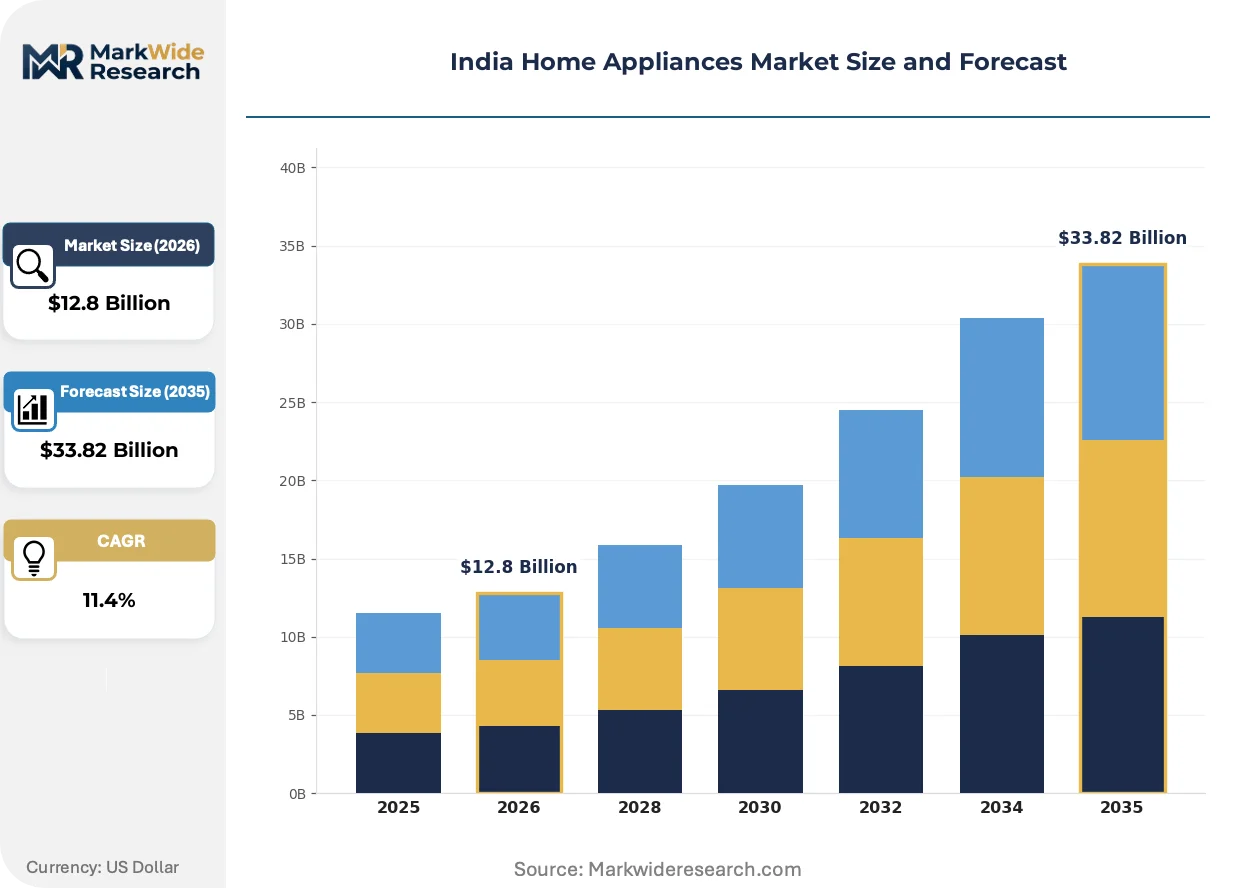
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners End User: Households, Small Businesses, Large Enterprises, Institutions Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale Feature: Energy Efficient, Smart Technology, User-Friendly, Compact Design |
| Companies Covered | Samsung India, LG Electronics India, Whirlpool of India, Godrej Appliances, Haier Appliances India, Voltas Ltd., IFB Industries Ltd., Havells India Ltd., Bajaj Electricals Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Home Appliances Market Strategic Shifts
Connected appliance ecosystems and precision-cooling architectures are redefining product roadmaps, while regulatory pressure on energy intensity accelerates hardware replacement cycles beyond traditional durability expectations.
Inverter compressor technology is automating temperature modulation in frost-free refrigerators, eliminating manual defrost cycles for urban households in Mumbai and Chennai. Middle-income buyers in tier-II cities adopt these platforms at replacement-driven pace, shifting volume share from direct-cool segments. This automation is compressing service revenue streams traditionally tied to mechanical failure repair.
BIS energy-rating mandates for air conditioners now require minimum 3-star compliance for commercial channel sales, disqualifying fixed-speed imports from Southeast Asian trading partners. Manufacturers respond by localizing inverter production at Faridabad and Pune facilities, redirecting capital from marketing to component vertical integration. The premium residential segment absorbs compliance costs through price escalation, while economy-tier buyers delay purchases or shift to secondary markets.
Appliance-as-a-service pilots emerge in Bengaluru and Hyderabad gated communities, unbundling upfront capital expenditure into monthly subscriptions covering hardware, maintenance, and electricity optimization. Young professional households in tech-sector employment clusters drive initial uptake, valuing flexibility over ownership. This model disrupts traditional distributor-retailer financing arrangements concentrated in Delhi-NCR and Maharashtra.
India Home Appliances Market Segmentation
Product configuration and feature differentiation across India's home appliances market determine manufacturing allocation and channel economics. Supply-side specialization concentrates in distinct regional clusters based on segment-specific technical requirements and certification complexity.
Product Type:
Component sourcing patterns and assembly line investments concentrate manufacturing capacity across Maharashtra, Gujarat, and Tamil Nadu production corridors.
- Refrigerators:Compressor-driven cooling systems operating on 230V/50Hz single-phase supply with Bureau of Energy Efficiency star ratings from 1 to 5. Demand clusters in tier-II and tier-III cities of Gujarat and Karnataka as electrification reliability improves and households upgrade from direct-cool to frost-free platforms.
- Air Conditioners:Inverter compressor technology reduces power consumption by 30-50% versus fixed-speed alternatives. Heat-stressed climates in Maharashtra and Delhi-NCR drive middle-income adoption as BIS mandates minimum 3-star compliance for commercial channel sales.
- Washing Machines:Fully automatic drum and top-load configurations address semi-urban laundry automation needs in Tamil Nadu and Andhra Pradesh.
- Microwaves:Countertop and built-in variants integrate with modular kitchen configurations in Pune and Hyderabad new apartment developments.
Refrigerators absorb the bulk of installed capacity; air conditioners are expanding most quickly.
End User:
Procurement scale and replacement frequency shape demand patterns across customer categories with distinct financing preferences and service expectations.
- Households:Individual consumers purchasing 1-3 units per transaction through retail channels, with replacement cycles accelerating as BIS energy-rating mandates obsolete legacy equipment. Urban households in tier-II cities drive frost-free refrigerator and inverter air conditioner upgrades.
- Small Businesses:Restaurants, retail shops, and clinics requiring commercial-grade refrigeration and cooling with higher duty cycles. Demand concentrates in Maharashtra and Gujarat commercial corridors where FSSAI food storage guidelines enforce precision-cooling compliance.
- Large Enterprises:Hospitality chains and corporate facilities procuring through centralized tenders with extended warranty and service-level requirements.
- Institutions:Educational facilities, healthcare centers, and government canteens with budget-constrained bulk procurement routed through tender processes.
Households command the dominant revenue share; small businesses are gaining share fastest.
Distribution Channel:
Inventory carrying costs and working capital requirements determine channel viability across geographic penetration targets and customer credit profiles.
- Online Retail:E-commerce platforms with EMI financing and exchange programs capture tech-forward buyers in Bengaluru and Mumbai. Logistics networks enable tier-III penetration where physical retail is sparse.
- Offline Retail:Branded exclusive stores and multi-brand outlets dominate in Delhi-NCR and Chennai, offering installation services and extended warranties. Working capital intensity limits expansion in semi-urban markets.
- Direct Sales:Manufacturer-led institutional and enterprise contracts with customized service agreements and bulk pricing structures.
- Wholesale:Distributor networks supplying independent retailers in Uttar Pradesh and Bihar agricultural belts, constrained by DISCOM financial stress delaying rural grid upgrades.
Offline retail maintains the largest transaction volume; online retail is climbing the fastest.
Feature:
Pricing stratification and certification requirements segment the market across performance tiers with distinct manufacturing complexity and margin profiles.
- Energy Efficient:BIS star-label compliance mandates inverter compressor adoption, disqualifying fixed-speed imports. Manufacturers localize production at Faridabad and Pune facilities to meet minimum 3-star requirements for commercial sales.
- Smart Technology:Wi-Fi-enabled inventory tracking, energy monitoring, and remote diagnostics differentiate premium lines. Tech-sector employment clusters in Bengaluru and Hyderabad drive initial uptake among young professional households.
- User-Friendly:Intuitive controls, regional language interfaces, and simplified maintenance protocols address semi-urban and first-time buyer segments in tier-II cities.
- Compact Design:Space-optimized dimensions for Mumbai and Bengaluru apartments where square footage constraints dictate appliance footprint limitations.
Energy efficient features dominate shipment volumes; smart technology commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production corridors concentrate in Maharashtra, Gujarat, and Tamil Nadu while consumption growth accelerates across tier-II and tier-III cities where electrification reliability has improved. The divergence between manufacturing scale and demand geography creates logistics optimization pressures for refrigerator and air conditioner distribution networks.
Maharashtra
Mumbai and Pune households drive frost-free refrigerator upgrades as modular kitchen installations expand in new apartment developments. BIS star-label mandates accelerate inverter air conditioner adoption across Mumbai's premium residential towers. The Chakan industrial belt near Pune hosts compressor manufacturing investments serving western India demand clusters.
Gujarat
Ahmedabad and Surat semi-urban buyers shift from direct-cool to frost-free refrigeration as grid stability improves in tier-II cities. The state's PLI scheme disbursements attract component localization for heat exchangers and motor assemblies. Mundra port facilities enable import substitution for refrigeration coil materials previously sourced through Southeast Asian trading routes.
Tamil Nadu
Chennai's heat-stressed climate sustains inverter air conditioner demand among middle-income households replacing fixed-speed units. FSSAI guidelines on commercial food storage temperatures drive precision-cooling refrigerator procurement in restaurant and retail channels. Sriperumbudur electronics manufacturing clusters expand assembly capacity for washing machine drum mechanisms.
Karnataka
Bengaluru tech-sector employment clusters generate premium demand for Wi-Fi-enabled smart appliances with energy monitoring capabilities. BIS laboratory capacity constraints in the region delay star-rating approvals for new inverter models by 4-8 months. Whitefield and Electronic City industrial zones attract component suppliers serving refrigerator compressor localization requirements.
Delhi-NCR
Heat wave intensity in Delhi accelerates air conditioner replacement cycles beyond traditional durability expectations. DISCOM financial stress in adjacent Uttar Pradesh agricultural belts caps rural appliance penetration despite grid availability. Faridabad manufacturing plants sustain washing machine production scale for price-sensitive buyers across northern India.
India Home Appliances Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across India's home appliances market. The vendor base organizes into three tiers: multinational subsidiaries with integrated ecosystem strategies, domestic conglomerates with diversified electrical goods portfolios, and regional specialists concentrating on single product categories. Consolidation pressures favor players with captive compressor manufacturing and established service networks. Strategic moves center on PLI-linked component localization and modular kitchen bundling partnerships with real estate developers.
Within the multinational subsidiary tier, Samsung India and LG Electronics India occupy positions defined by inverter technology platforms and connected appliance ecosystems. Whirlpool of India represents the focused specialist archetype with manufacturing concentration at Pune and Faridabad facilities. These three anchors exemplify divergent approaches to the same regulatory environment of BIS star-label mandates and PLI localization incentives.
| Leading Market Players |
|---|
| Samsung India |
| LG Electronics India |
| Whirlpool of India |
| Godrej Appliances |
| Haier Appliances India |
| Voltas Ltd. |
| IFB Industries Ltd. |
| Havells India Ltd. |
| Bajaj Electricals Ltd. |
| Others |
Value Chain & Pricing Dynamics
BIS star-label divergence between inverter-certified and fixed-speed platforms splits the India home appliances market into compliance-premium and clearance-economy tiers, with pricing power accumulating at manufacturers who localized compressor production ahead of PLI scheme deadlines while supply chains retool around Maharashtra and Tamil Nadu component corridors.
Pricing Analysis
Margin tightening in fixed-speed refrigerator tiers reflects distributor inventory clearance pressure as BIS mandates accelerate obsolescence. Three-tier pricing structure across premium, standard, and economy levels stratifies by compressor technology and star-rating certification, with inverter platforms commanding 25-40% premia over direct-cool alternatives. Price differentiation rests on energy efficiency grade and after-sales service bundling. Cost-down pressure on economy-tier manufacturers intensifies because copper-aluminum coil input volatility compresses gross margins on price-locked retail contracts. Small businesses in Gujarat commercial corridors exhibit highest price sensitivity, while premium residential buyers in Mumbai absorb compliance-driven escalation.
Supply Chain Analysis
Regional distribution centers in Pune, Chennai, and Faridabad anchor hub-and-spoke patterns serving tier-II and tier-III penetration targets. Manufacturing concentration centers on India, with compressor and heat exchanger component dependencies drawing from China and Southeast Asian trading partners. Raw material inputs hinge on London Metal Exchange-priced copper and aluminum for refrigeration coils, plus imported inverter control modules. Single-source vulnerability in certified compressor supply creates structural risk as BIS laboratory capacity constraints delay star-rating approvals. Distribution runs through branded exclusive stores and multi-brand outlets in Delhi-NCR and Chennai, with e-commerce platforms capturing tech-forward buyers in Bengaluru.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's home appliances market operates as a supply-constrained environment where BIS certification bottlenecks and PLI localization timelines prop pricing power for early movers who secured compressor manufacturing capacity.
For Market Incumbents: Cement defensive positioning through captive inverter compressor production at Pune and Faridabad facilities, insulating margin structures from copper-aluminum price volatility. Deepen channel control in tier-II cities before emerging regional specialists capture modular kitchen bundling partnerships with real estate developers. Prioritize certification investment to compress BIS star-rating approval timelines that currently extend product launch windows. For New Entrants and Emerging Players: Smart appliance convergence with Wi-Fi-enabled energy monitoring offers a technology-first wedge into Bengaluru and Hyderabad tech-sector employment clusters where young professional households value flexibility over ownership. Target tier-III towns in Karnataka and Tamil Nadu where authorized service center coverage gaps force reliance on independent repair shops. Pursue appliance-as-a-service pilots in gated communities to bypass traditional distributor-retailer financing arrangements. For Investors and Strategic Acquirers: Re-rating potential sits with component manufacturers possessing PLI-linked localization credentials given disbursement acceleration through Maharashtra and Tamil Nadu industrial zones. Long-term viability over a 5-10 year window favors targets with captive heat exchanger production and established tier-III service networks. Monitor DISCOM financial health in Uttar Pradesh and Bihar as the signal to watch for rural appliance penetration inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Localization | PLI scheme disbursements for white goods manufacturing compress import dependence across Maharashtra production corridors. |
| Modular Kitchen Bundling Partnership | Integrated refrigerator-microwave packages capture higher per-transaction value from Pune and Hyderabad apartment buyers. |
| Smart Appliance Platform Launch | Wi-Fi-enabled inventory tracking differentiates premium lines for Bengaluru tech-sector households. |
| Tier-III Service Network Expansion | Authorized coverage gaps in Karnataka and Tamil Nadu force reliance on untrained third-party technicians. |
| BIS Certification Fast-Track Investment | Laboratory capacity constraints delay star-rating approvals by 4-8 months, extending launch windows. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this India home appliances market analysis. Primary interviews with product development executives at white goods manufacturers, BIS certification laboratory directors, DISCOM planning officers in Maharashtra and Uttar Pradesh, and category buyers at multi-brand retail chains combined with secondary validation from Bureau of Energy Efficiency star-rating databases, PLI scheme disbursement records, and FSSAI food storage guidelines. Bottom-up shipment modeling and top-down consumption estimation triangulated volume and value outputs.
Granularity-level modeling operated at product type, end user, distribution channel, and feature dimensions across the analysis window. Refrigerator and air conditioner segments incorporated compressor technology tier, star-rating certification, and regional electrification reliability as industry-specific forecast inputs. CAGRs derived from replacement cycle acceleration patterns tied to BIS mandate implementation and tier-II urbanization trajectories in Gujarat and Karnataka.
Several conditions sit outside the modeled scope, including state-level electricity tariff reform timing, copper-aluminum commodity price trajectories, and DISCOM financial restructuring outcomes. Forecasts reflect documented assumptions regarding PLI localization timelines and BIS laboratory capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Japan Home Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Germany Household Side by Side Refrigerator Market