
 Israel Home Appliances Market | 2026-2036
Israel Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Home Appliances Market Foresight
Young urban professionals is redrawing demand patterns across Israel's home appliances sector, pulling volume toward connected, space-efficient formats suited for compact city apartments. Electra Consumer Products leverages its domestic manufacturing footprint and distribution depth to anchor share in refrigeration and climate control. Haier Electronics Group Co. Ltd. competes through aggressive smart-home integration and direct-to-consumer digital channels. Samsung Electronics differentiates by bundling appliance sales with its broader ecosystem of screens and mobile devices.
Israel home appliances encompass electrically powered devices designed for domestic tasks including food preservation, cleaning, cooking, and climate management, typically operating on 220-240V at 50Hz with energy efficiency ratings governed by mandatory labeling schemes. Refrigerators command the largest product-type value pool due to universal household penetration and replacement-driven purchase cycles, while smart appliances within the technology dimension capture expanding margin as IoT connectivity shifts from premium novelty toward baseline consumer expectation. The residential customer type dominates absolute volume, though builders represent a concentrated procurement channel for new construction in Israel's high-density coastal developments.
The Israel Standards Institution (SII) certifies electrical safety and electromagnetic compatibility for all imported and domestically manufactured appliances, while the Ministry of Energy enforces tiered efficiency labeling that effectively bars entry of low-efficiency models. The Ministry of Environmental Protection advances extended producer responsibility frameworks for appliance recycling and refrigerant recovery, tightening compliance costs for manufacturers. Stakeholders must monitor how forthcoming amendments to energy performance standards reshape product development timelines and import sourcing strategies.
Market Dynamics
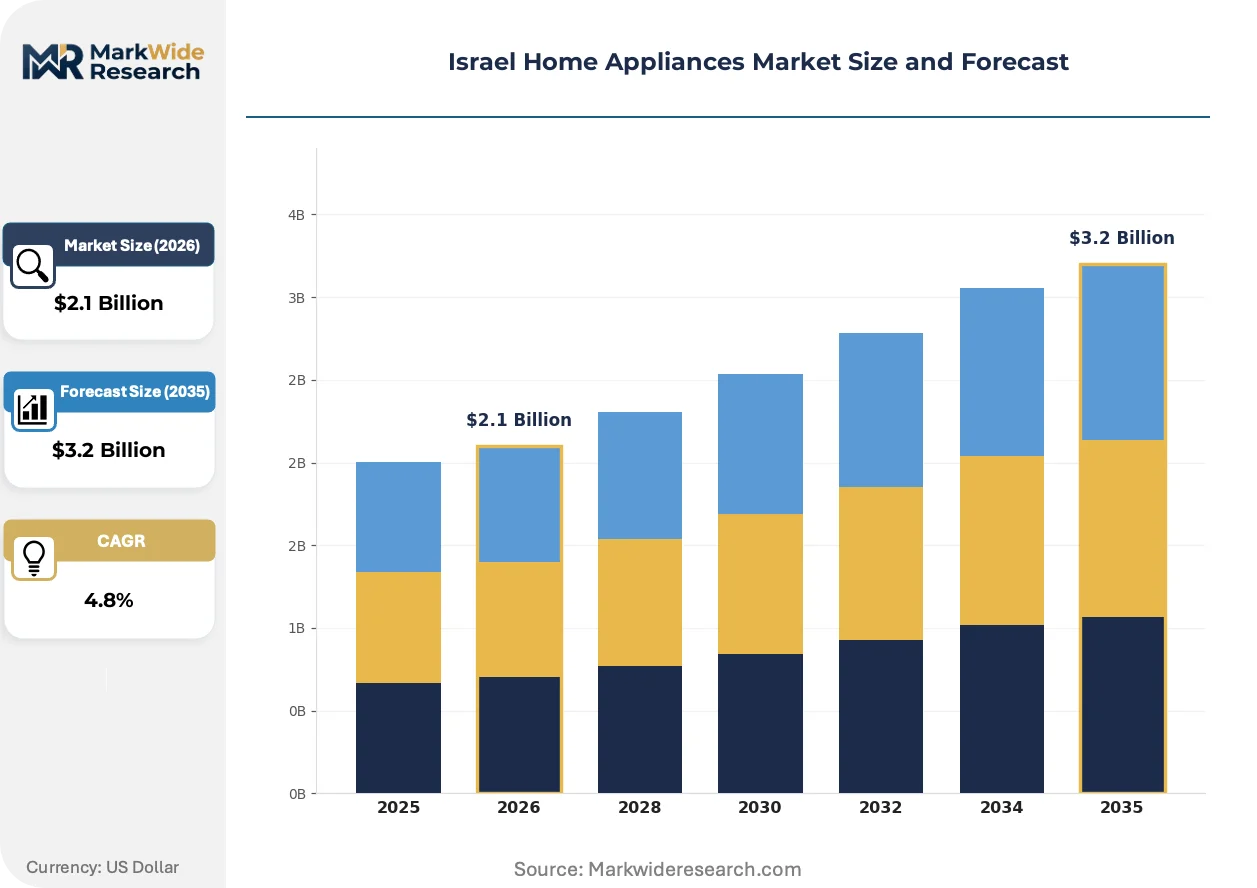
Energy efficiency mandates from the Ministry of Energy are compressing replacement cycles across Israel's appliance installed base, forcing manufacturers to accelerate R&D timelines while retailers clear older inventory tiers. This regulatory pressure intersects with urban densification patterns in Tel Aviv and Jerusalem, where compact-format smart appliances command premium positioning.
Growth Catalysts
- Smart home integration:IoT-enabled kitchen ecosystems allow remote monitoring and predictive maintenance, appealing to tech-forward households in coastal metropolitan clusters.
- Ministry of Energy labeling tiers:Mandatory efficiency grades create visible differentiation at point-of-sale, steering consumer preference toward higher-rated models and accelerating trade-ins.
- High-density residential construction:New apartment developments in Tel Aviv and Haifa incorporate built-in appliance specifications, generating concentrated builder procurement volumes.
Market Restraints
- Import dependency for compressors:Core refrigeration components originate from concentrated East Asian supplier bases, exposing margins to shipping cost volatility and currency fluctuation.
- Copper and steel input costs:Raw material price swings directly impact manufacturing economics for domestic producers lacking long-term hedging arrangements.
- Extended producer responsibility compliance:Ministry of Environmental Protection recycling mandates impose collection infrastructure costs that smaller importers struggle to absorb.
Strategic Opportunities
- Water-scarce climate adaptation:Drought-resistant washing machine designs with sub-50-liter cycles address regional environmental stress and align with national conservation campaigns.
- Direct-to-consumer digital channels:Bypassing traditional retail markups allows manufacturers to capture margin while offering subscription-based maintenance bundles.
- Kosher kitchen automation:Sabbath-mode connectivity and dairy-meat separation protocols open specialized positioning within Israel's observant household segment.
Industry Challenges
- Electromagnetic compatibility certification:SII testing protocols for smart appliance RF emissions extend product launch timelines by four to six months versus non-connected equivalents.
- Legacy electrical infrastructure:Older residential buildings in Jerusalem's historic districts lack circuit capacity for high-draw induction ranges, complicating product-market fit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Home Appliances Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Microwaves Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Conventional Customer Type: Residential, Commercial, Builders, Retailers End User: Homeowners, Renters, Hospitality Sector, Institutions |
| Companies Covered | Electra Consumer Products, Tadiran Holdings, Haier Electronics Group Co. Ltd., LG Electronics, Samsung Electronics, Whirlpool Corporation, Electrolux AB, Panasonic Corporation, BSH Home Appliances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Home Appliances Market Shifts & Advancements
Connectivity architectures are fragmenting appliance value propositions away from standalone hardware toward integrated service platforms. This shift demands new competencies in software maintenance, data security, and over-the-air update infrastructure.
Edge-computing refrigeration controls are fragmenting the traditional appliance-manufacturer relationship with consumers. Compressor modulation algorithms now process temperature and humidity data locally, reducing cloud dependency for Israeli households with intermittent connectivity. Young urban buyers in Tel Aviv prioritize these autonomous systems. The technology is fragmenting brand loyalty as performance becomes tied to firmware sophistication rather than mechanical reliability alone.
Ministry of Energy amendments to standby power regulations are forcing redesigns across the import portfolio. The new thresholds, effective pending final publication, will disqualify several mid-range dishwasher and laundry models currently stocked by major retailers. Importers are advancing compliance certification ahead of formal enforcement to avoid stranded inventory.
Rental and subscription models are displacing outright purchase for major appliances among Jerusalem's student and young professional population. Monthly fee structures bundle maintenance, eventual upgrade rights, and energy cost guarantees. This behavioral shift concentrates procurement decisions with property management platforms rather than individual consumers, altering manufacturer sales force deployment toward B2B relationship management.
Israel Home Appliances Market Segmentation
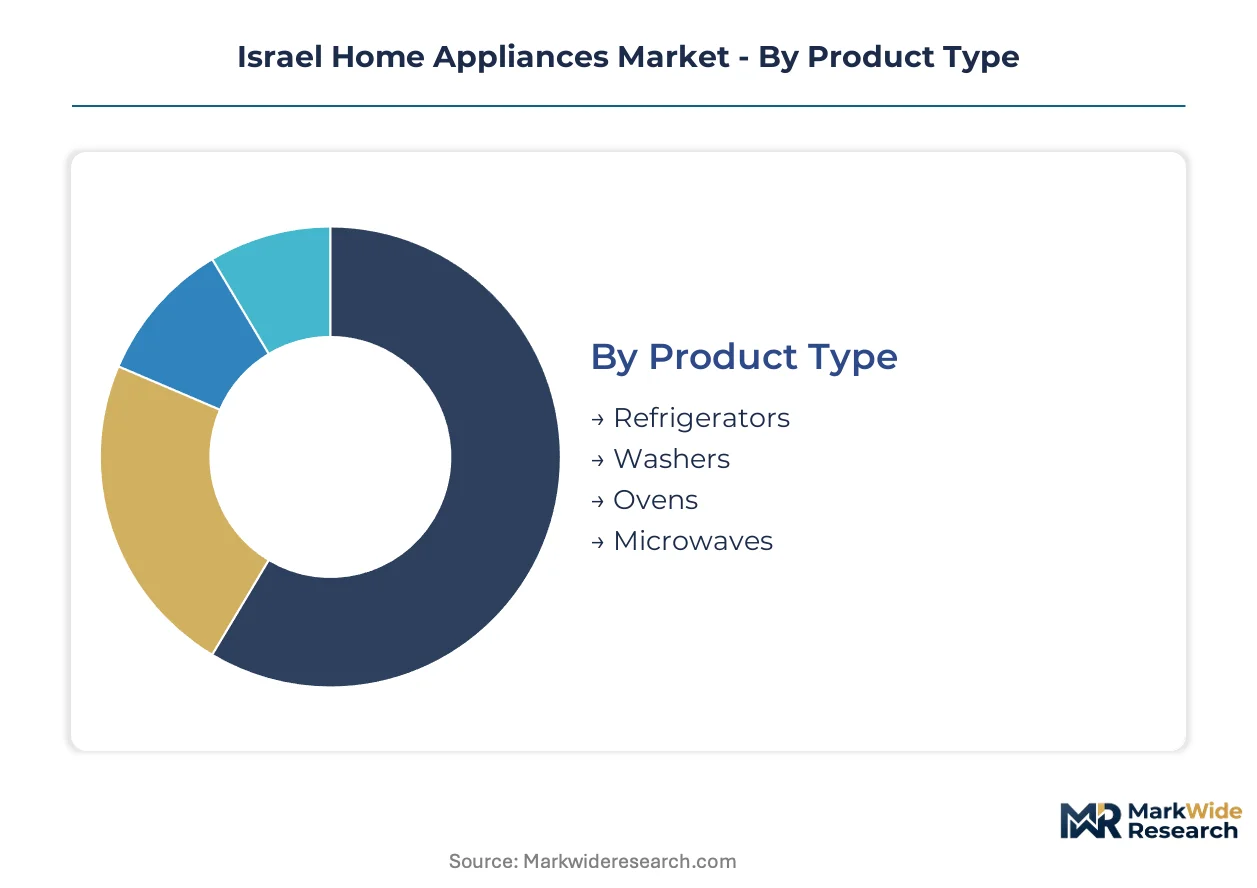
Segmentation reveals how regulatory pressure and urban living patterns concentrate demand across distinct appliance categories in Israel. Understanding these divisions exposes where substitution threats from adjacent technologies reshape competitive dynamics.
Product Type:
Refrigerators face the strongest substitution pressure as cooling technology fragments across portable units, drawer formats, and built-in wine preservation systems that displace traditional single-door configurations.
- Refrigerators:Compression-based cooling systems with variable-speed inverter compressors dominate Israeli households. Demand concentrates among residential homeowners in Tel Aviv's high-rise developments where space constraints favor counter-depth and French-door configurations over traditional top-freezer designs.
- Washers:Front-loading drum systems with heat-pump drying integration command premium positioning. Jerusalem's rental market and young professional clusters drive concentrated procurement through property management platforms offering subscription-based laundry services.
- Ovens:Convection and pyrolytic self-cleaning configurations address kosher kitchen requirements for dairy-meat separation. Builder specifications in Haifa's coastal developments increasingly mandate built-in formats over freestanding alternatives.
- Microwaves:Inverter-powered compact units with sensor-based defrost algorithms serve secondary cooking roles. Hospitality sector procurement in Eilat's tourism corridor generates concentrated volume for commercial-grade durability specifications.
Refrigerators anchors the volume base while Washers gains share at the steepest rate.
Technology:
Cost tier stratification separates premium-connected systems from baseline replacements, with mid-range positioning eroding as efficiency mandates force feature upgrades.
- Smart Appliances:Wi-Fi-enabled units with app-based remote control and usage analytics. Tel Aviv's tech-forward households drive adoption where predictive maintenance alerts and energy monitoring justify price premiums over conventional alternatives.
- Energy-Efficient:Compressor and motor designs meeting Ministry of Energy tier-A labeling thresholds. Regulatory compliance deadlines accelerate replacement cycles across Israel's installed base as older stock faces import restrictions.
- IoT-Enabled:Cloud-connected ecosystems integrating with broader home automation platforms. Young urban professionals in coastal metropolitan clusters prioritize these systems despite SII electromagnetic compatibility certification delays extending launch timelines.
- Conventional:Non-connected mechanical systems with basic electromechanical controls. Price-sensitive segments in peripheral development towns and older Jerusalem neighborhoods sustain residual demand despite efficiency labeling disadvantages.
Energy-Efficient dominates absolute volume while Smart Appliances expands most quickly as connectivity shifts from premium novelty toward baseline expectation.
Customer Type:
Volume concentration among residential purchasers contrasts with margin capture in builder channel procurement for new construction specifications.
- Residential:Individual household purchasers selecting appliances for existing homes or renovations. Replacement-driven demand in established neighborhoods generates steady volume with high price sensitivity to efficiency rating visibility.
- Commercial:Restaurants, catering facilities, and institutional kitchens requiring durability-rated equipment. Kosher certification requirements and high-cycle usage patterns create specialized procurement criteria distinct from residential specifications.
- Builders:Property developers specifying built-in appliances for new apartment deliveries. High-density coastal developments in Tel Aviv and Haifa generate concentrated procurement volumes with standardized efficiency tier requirements.
- Retailers:Inventory procurement for multi-brand showroom and e-commerce fulfillment operations. Extended producer responsibility compliance costs from Ministry of Environmental Protection mandates disadvantage smaller importers in this channel.
Residential anchors the volume base while Builders gains share at the steepest rate as high-density construction accelerates.
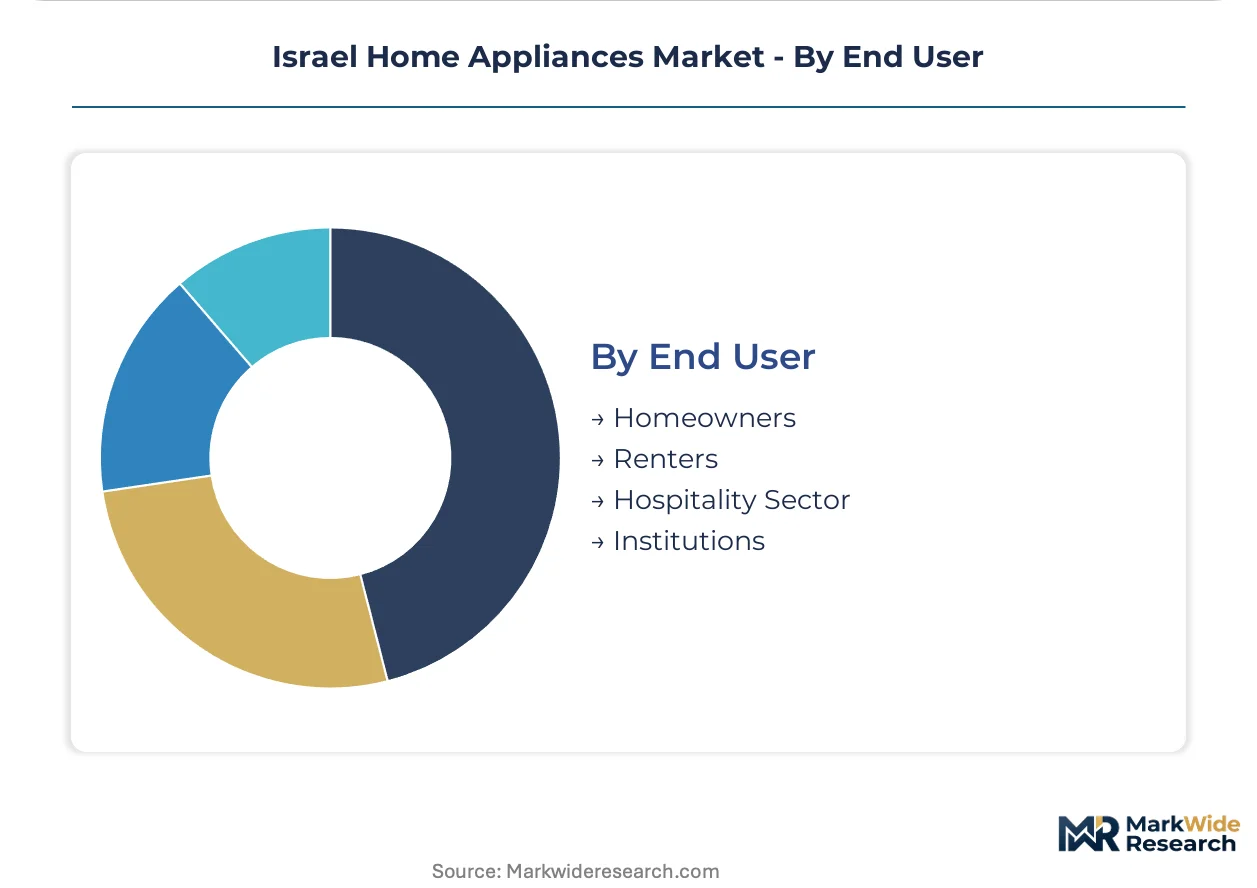
End User:
Application-based segmentation reveals divergent durability and connectivity requirements across ownership and institutional contexts.
- Homeowners:Long-horizon purchasers prioritizing reliability and warranty coverage. Energy efficiency labeling influences replacement timing as Ministry of Energy tiers create visible upgrade incentives at point-of-sale.
- Renters:Price-sensitive users dependent on landlord-provided or subscription-accessed appliances. Jerusalem's student population and young professional clusters drive rental model adoption with bundled maintenance and upgrade rights.
- Hospitality Sector:Hotels and serviced apartments requiring commercial-grade durability with aesthetic consistency. Eilat and Dead Sea tourism corridors generate concentrated demand for corrosion-resistant finishes and high-cycle compressor specifications.
- Institutions:Schools, hospitals, and government facilities with centralized procurement and extended replacement cycles. National tender processes prioritize efficiency tier compliance and local service network coverage over feature sophistication.
Homeowners anchors the volume base while Renters gains share at the steepest rate as subscription models displace outright purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young urban professionals in Tel Aviv and Jerusalem drive replacement cycles toward connected, space-efficient formats suited for compact apartments. Ministry of Energy labeling mandates accelerate trade-ins across all sub-regions. High-density coastal construction concentrates builder procurement volumes.
Tel Aviv Metropolitan Area
Tech-sector households prioritize IoT-enabled kitchen ecosystems with predictive maintenance capabilities. Ministry of Energy tier-A efficiency thresholds steer point-of-sale decisions toward inverter-compressor refrigeration. Ramat Gan and Givatayim high-rises generate concentrated demand for counter-depth French-door configurations.
Jerusalem
Observant household segments seek Sabbath-mode connectivity and dairy-meat separation protocols in oven specifications. Israel Standards Institution electromagnetic compatibility certification extends launch timelines for smart appliance imports. Student and young professional clusters in central neighborhoods drive subscription-based rental model adoption.
Haifa and Northern Coastal District
High-density residential developments incorporate built-in appliance specifications for new apartment deliveries. Ministry of Environmental Protection extended producer responsibility frameworks tighten compliance costs for importers. Builder procurement concentrates in Kiryat Yam and Hadera corridor projects.
Beer Sheva and Southern District
Peripheral development towns sustain residual demand for conventional mechanical systems with basic electromechanical controls. National tender processes for institutional procurement prioritize efficiency tier compliance over feature sophistication. Soroka Medical Center and Ben-Gurion University generate concentrated institutional volume.
Eilat and Southern Arava
Tourism corridor hotels and serviced apartments require commercial-grade durability with corrosion-resistant finishes. Hospitality sector procurement prioritizes high-cycle compressor specifications for continuous operation. Dead Sea resort properties generate concentrated demand for climate-adapted refrigeration.
Israel Home Appliances Market Competitive Landscape
Player mix skews toward diversified multinational electronics conglomerates with established distribution infrastructure. Market structure consolidates around manufacturers with domestic assembly presence or direct-to-consumer digital channels. Three archetypes dominate: vertically integrated conglomerates leveraging ecosystem bundling, regional specialists with kosher certification expertise, and scale-driven importers optimizing for efficiency-tier compliance. Competitive moves center on strategic partnerships with property management platforms and portfolio diversification into subscription-based service models.
Among Israel-based specialists, Electra Consumer Products and Tadiran Holdings anchor positions through domestic manufacturing footprints and distribution depth. Haier Electronics Group Co. Ltd. represents the scale-driven import archetype, competing through aggressive smart-home integration. Samsung Electronics and LG Electronics exemplify diversified conglomerate positioning, bundling appliance sales with broader mobile and screen ecosystems. Whirlpool Corporation, Electrolux AB, and BSH Home Appliances occupy mid-tier volume positions, while Panasonic Corporation targets premium connectivity segments.
| Leading Market Players |
|---|
| Electra Consumer Products |
| Tadiran Holdings |
| Haier Electronics Group Co. Ltd. |
| LG Electronics |
| Samsung Electronics |
| Whirlpool Corporation |
| Electrolux AB |
| Panasonic Corporation |
| BSH Home Appliances |
| Others |
Supply & Pricing Matrix
Compressor manufacturing scale economies in China and South Korea anchor cost structures across Israel's refrigeration segment, concentrating supply-side leverage among East Asian producers while compressing price floors for domestic assemblers lacking captive component sources. This concentration forces Israeli distributors to absorb currency volatility through inventory hedging or pass through costs to tier-A efficiency models where Ministry of Energy labeling insulates margin.
Pricing Analysis
Cost-plus contracts with copper and steel indexation dominate procurement between Israeli retailers and East Asian manufacturers, embedding raw material volatility directly into landed cost structures. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi-enabled smart refrigerators from basic inverter models and entry-level mechanical units. Pricing pressure stems from Ministry of Energy efficiency mandates disqualifying mid-range inventory ahead of regulatory deadlines. Builders in Tel Aviv's high-density corridor exhibit lowest price sensitivity due to standardized specification requirements, while peripheral development towns drive volume at economy tiers.
Supply Chain Analysis
China and South Korea anchor compressor and inverter module production for Israel-bound refrigeration systems, with Taiwan supplying control board assemblies and sensor components. Raw material dependencies center on copper windings, rare-earth permanent magnets, and cold-rolled steel sheet. Single-source vulnerability concentrates in variable-speed compressor technology where two suppliers control patent-protected designs. Distribution runs through Haifa port consolidation followed by bonded warehousing for duty-deferred inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's home appliances market sits in cyclical recovery driven by Ministry of Energy replacement mandates forcing trade-in waves across the installed base. Regulatory compression of replacement cycles creates predictable demand pulses for manufacturers positioned at tier-A efficiency thresholds.
For Market Incumbents: Consolidate distributor relationships in Jerusalem and Haifa corridors to preempt subscription-model platforms from capturing procurement decisions. Deepen backward integration into compressor servicing networks to offset import dependency risks. Electra Consumer Products and Tadiran Holdings should lock builder specifications through multi-year efficiency-tier compliance guarantees before regulatory amendments tighten.
For New Entrants and Emerging Players: Sabbath-mode connectivity gaps in Jerusalem's observant household segment offer white-space positioning where incumbents under-serve kosher kitchen automation requirements. Water-scarce climate adaptation for sub-50-liter washing cycles targets Beer Sheva and Southern District municipalities running conservation campaigns. Direct-to-consumer digital channels bypassing traditional retail markups provide the most penetrable go-to-market angle for subscription-based maintenance bundles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with firmware-over-air capabilities and SII electromagnetic compatibility certification infrastructure already deployed. Long-term viability hinges on software maintenance competencies rather than mechanical manufacturing scale. Acquisition targets should demonstrate established property management platform relationships in Tel Aviv's rental market. The signal to watch is Ministry of Energy standby power regulation final publication timing, which will strand non-compliant inventory and accelerate consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Kosher Kitchen Automation Development | Sabbath-mode protocols capture Jerusalem's observant household premium segment. |
| Direct-to-Consumer Digital Channel Launch | Subscription bundles bypass retail markups in Tel Aviv young professional clusters. |
| Water-Scarce Climate Product Adaptation | Sub-50-liter cycles align with Ministry of Environmental Protection conservation mandates. |
| Extended Producer Responsibility Infrastructure | Collection networks satisfy Ministry of Environmental Protection compliance for importer survival. |
| Edge-Computing Refrigeration Controls | Autonomous firmware reduces cloud dependency for Israeli intermittent connectivity households. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with appliance category managers, SII certification engineers, Ministry of Energy policy officers, and property management platform procurement leads; and secondary validation through Israel Central Bureau of Statistics household expenditure surveys, Ministry of Environmental Protection extended producer responsibility filings, customs import manifests for HS 8418 refrigeration equipment, and retailer point-of-sale efficiency-tier tracking data. Bottom-up unit economics triangulated against top-down sectoral expenditure flows.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, technology tier, customer channel, and metropolitan sub-region. CAGRs derived from replacement-cycle timing, regulatory compliance deadlines, and construction permit flows for high-density residential developments. Specific inputs included Ministry of Energy labeling amendment implementation schedules and compressor import cost indices.
Underlying assumptions cover regulatory enforcement consistency and construction permit velocity, with deviation risk concentrated in electromagnetic compatibility certification delays and copper price volatility. Recalibration cycles align with material shifts in Ministry of Energy efficiency thresholds and standby power regulation final publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Japan Small Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Egypt Home Appliances Market