
 United States Household Refrigerators Market | 2026-2036
United States Household Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
United States Household Refrigerators Market Analytics
Direct-to-consumer online channels is rewriting how major brands reach replacement buyers in the United States Household Refrigerators Market. Whirlpool Corporation leverages its dealer network to sustain service-touch advantages in rural markets. Samsung Electronics competes through smart-home ecosystem integration that anchors kitchen connectivity strategies. LG Electronics differentiates via inverter compressor technology leadership that extends energy performance claims.
Household refrigerators are electrically powered appliances maintaining temperatures between 35°F and 38°F in refrigerated compartments and 0°F in freezer sections through vapor-compression cycles using refrigerants, insulated cabinets, and automated defrost systems for residential food preservation. French Door configurations command margin pools as kitchen renovation spending shifts toward premium aesthetics and flexible storage. Smart Refrigerators represent the fastest-growing technology segment as WiFi-enabled inventory management and energy optimization reshape buyer expectations. Compact units face maturity pressures from urban density limits and counter-depth alternatives.
DOE appliance standards, EPA SNAP refrigerant rules, and state energy codes in California and New York shape product design mandates and market access thresholds for manufacturers selling into the United States. FTC EnergyGuide labeling requirements influence consumer comparison behavior and retailer merchandising priorities. Stakeholders must monitor refrigerant phase-down timelines and state-level electrification incentives that will determine next-generation platform investments.
Market Dynamics
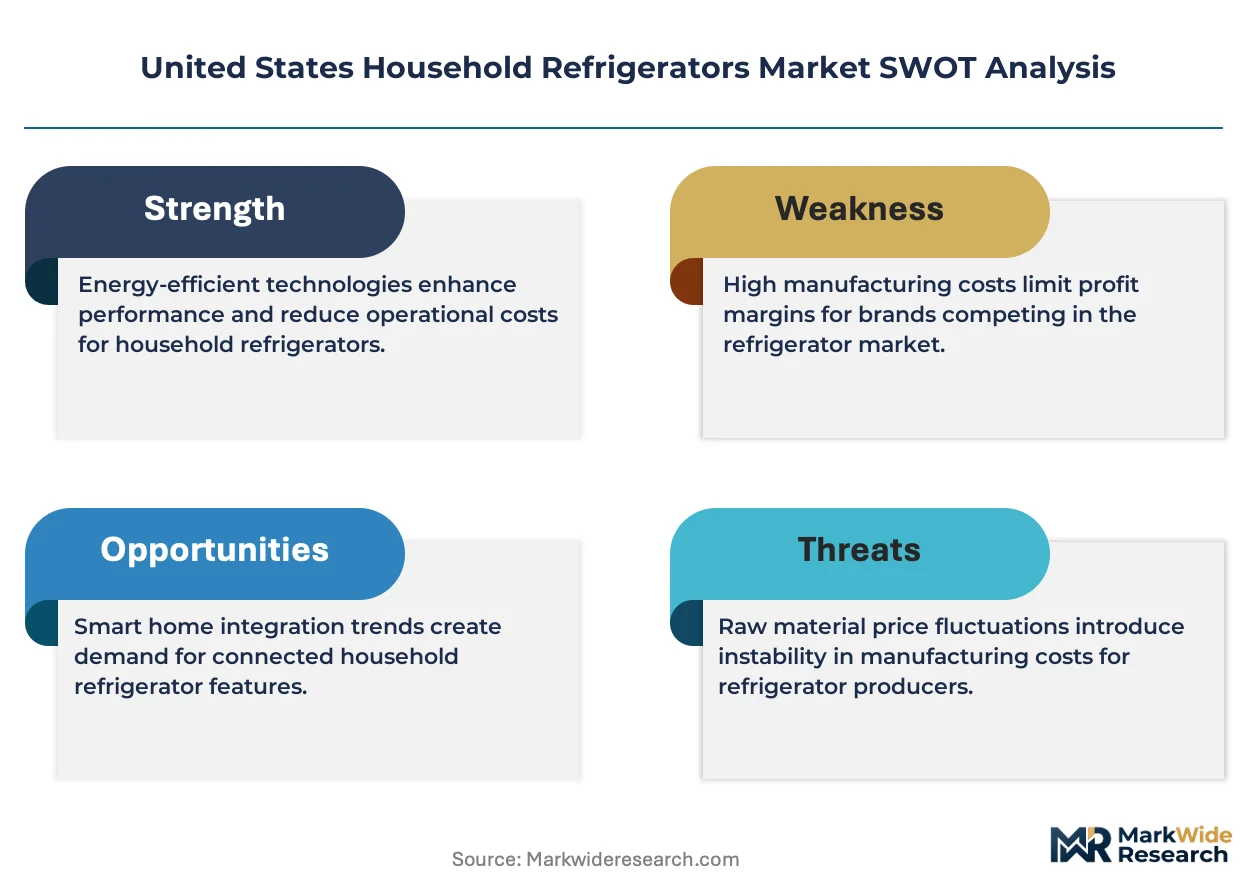
The United States Household Refrigerators Market is experiencing structural pressure from DOE appliance efficiency standards that mandate compressor technology transitions and insulation material upgrades, forcing manufacturers to redesign thermal management systems while maintaining price accessibility for replacement buyers.
Growth Catalysts
- Single-Family Residential Construction:Housing formation in Sun Belt states including Texas and Florida is accelerating replacement cycles for full-size kitchen appliances as new inventory absorbs first-time buyers.
- IRA Electrification Incentives:Federal tax credits for energy-efficient appliance purchases are compressing payback periods for inverter compressor upgrades and smart-home integration features.
- Smart-Home Ecosystem Integration:WiFi-enabled inventory management and automated energy optimization are creating specification pull-through from kitchen renovation contractors targeting premium aesthetic upgrades.
Market Restraints
- Refrigerant Supply Concentration:EPA SNAP rules phasing down hydrofluorocarbons are compressing qualified supplier bases for next-generation low-GWP alternatives, creating input cost volatility.
- Copper and Steel Input Volatility:Compressor manufacturing and cabinet fabrication face margin pressure from commodity price swings in electrical steel and copper tubing.
- Technical Limitation in Retrofit Compatibility:Smart refrigerator connectivity protocols lack standardization across home automation platforms, creating integration friction for replacement buyers with legacy systems.
Strategic Opportunities
- Counter-Depth Category Expansion:Urban density constraints in California and New York metro corridors are displacing compact units with full-featured counter-depth alternatives commanding premium positioning.
- State-Level Electrification Mandates:California Title 24 building codes and New York energy efficiency incentives are creating regulatory tailwinds for heat pump water heater adjacent appliance upgrades.
- Direct-to-Consumer Channel Innovation:Online configuration tools and virtual kitchen design services are compressing traditional dealer intermediation in replacement purchase journeys.
Industry Challenges
- Compressor Engineering Talent Scarcity:Inverter drive electronics and variable-speed motor control expertise is concentrating among a limited pool of electromechanical design specialists.
- FTC EnergyGuide Certification Timelines:Testing protocol updates for revised efficiency metrics are extending product launch windows and compressing competitive response speeds.
- Legacy Defrost System Integration:Automated adaptive defrost algorithms require firmware compatibility with decades-old installed base electrical architectures, complicating platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Household Refrigerators Market |
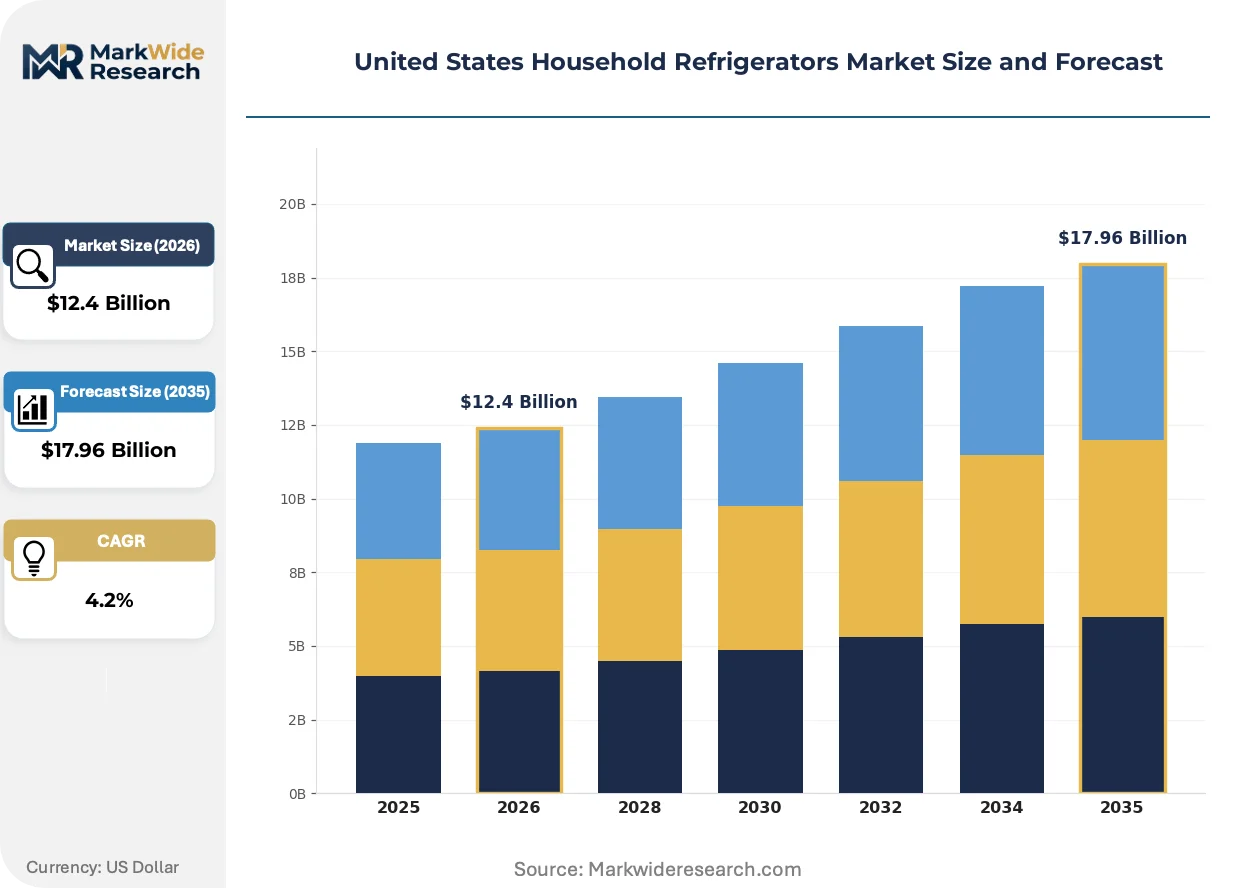
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $17.96 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Freezer, Bottom-Freezer, Side-by-Side, French Door Size: Compact, Standard, Large Capacity, Custom Fit Technology: Frost Free, Manual Defrost, Energy Efficient, Smart Refrigerators End User: Residential, Restaurants, Cafes, Grocery Stores |
| Companies Covered | Whirlpool Corporation, GE Appliances, LG Electronics, Samsung Electronics, Electrolux, Haier Group, Frigidaire, Robert Bosch GmbH, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Household Refrigerators Market Evolving Landscape
Refrigeration technology is converging with home energy management systems, creating new specification criteria that prioritize grid-responsive operation and predictive maintenance over traditional capacity and finish attributes.
Inverter compressor technology with variable-speed drive electronics is rendering obsolete fixed-speed reciprocating compressors in mid-tier and premium segments. Kitchen renovation contractors are specifying inverter platforms for energy performance claims that satisfy California Title 24 compliance documentation. This technology transition is compressing margins for manufacturers dependent on legacy compressor supply chains while rewarding vertical control over motor and drive electronics production.
DOE amended appliance efficiency standards are mandating 15% energy use reductions for refrigerator-freezers through 2029. Manufacturers are responding with vacuum-insulated panel adoption and enhanced door seal geometries that complicate assembly automation. The standard revision most affects top-freezer configurations in the replacement market, where price sensitivity constrains technology absorption rates.
Replacement buyers are unbundling delivery and installation services from product purchases, treating white-glove handling as separately negotiable. Big-box retailers and direct-to-consumer platforms are disintermediating traditional dealer networks that historically captured service-touch margins. This pattern concentrates in Sun Belt states where housing turnover rates support independent contractor ecosystems for appliance installation and haul-away.
United States Household Refrigerators Market Segmentation
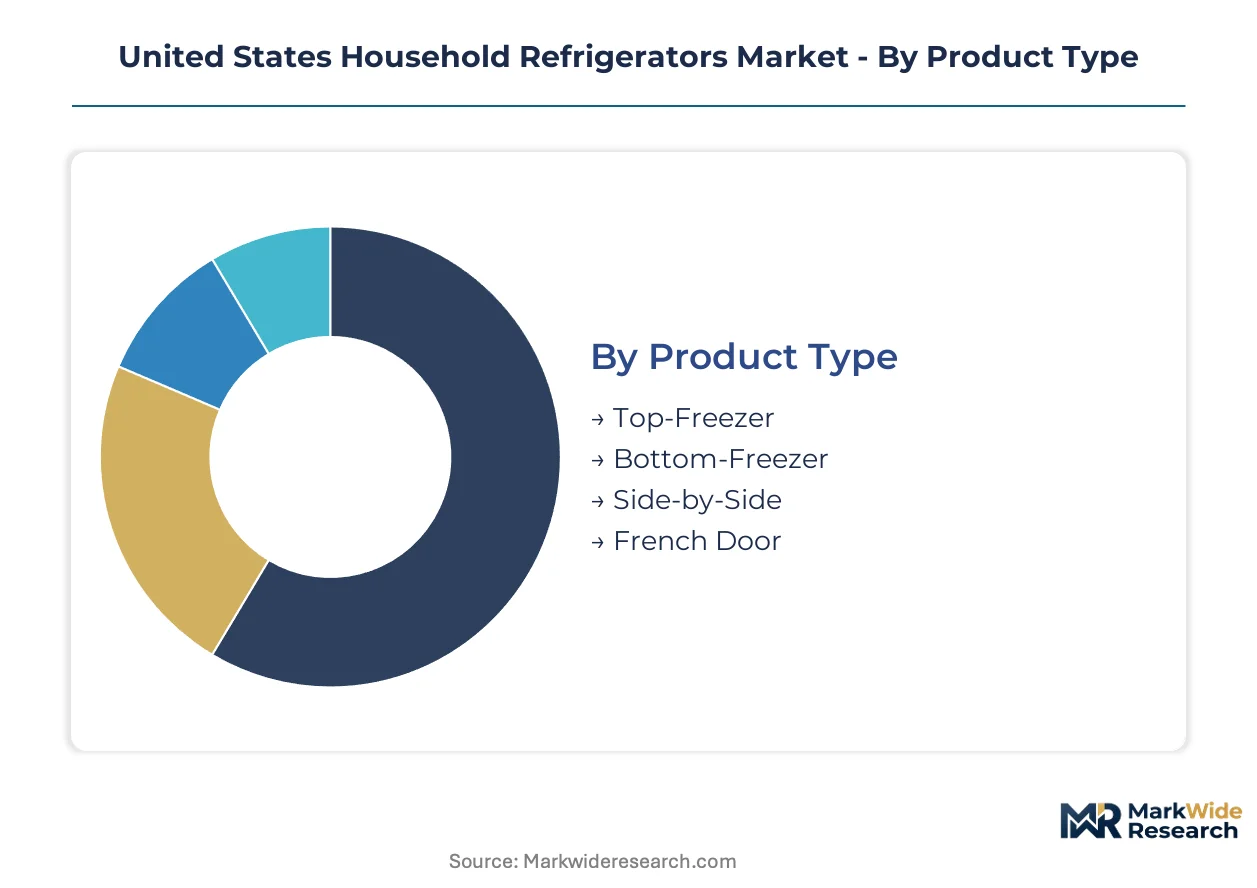
Segmentation in the United States household refrigerators market reveals distinct replacement cycles and technology adoption curves. Product configuration and end-use application determine margin pools and channel strategy for manufacturers competing across replacement and new construction demand.
Product Type:
Top-freezer units turn over fastest in rental housing and secondary kitchens, while French door configurations command extended replacement cycles tied to kitchen renovation timelines.
- French Door:Dual-door refrigeration compartments with bottom-mount freezer drawers optimize kitchen workflow and storage flexibility. Texas and Florida kitchen renovation contractors specify these units for premium aesthetic upgrades in single-family new construction.
- Side-by-Side:Vertical split configurations with parallel refrigerator and freezer compartments suit narrow kitchen footprints. Demand concentrates in California urban infill projects where space constraints limit swing-door clearance.
- Bottom-Freezer:Eye-level refrigeration with pull-out freezer drawer improves accessibility for aging-in-place households. Adoption lags in price-sensitive replacement segments.
- Top-Freezer:Traditional configuration with cost-optimized manufacturing and established service networks. Dominates rental property and secondary residence installations.
Top-freezer dominates installed base. French door is where expansion concentrates.
Size:
Cost tier alignment separates commodity replacement from premium kitchen specification, with counter-depth alternatives displacing compact units in urban density corridors.
- Standard:Full-depth cabinets between 30 and 36 inches wide serve the mass-market replacement cycle. Inventory availability and delivery speed determine retailer competitiveness in Sun Belt states.
- Large Capacity:Extended-width configurations above 36 inches target multi-generational households and entertainment-focused kitchens. California and Texas housing formation absorbs volume in new construction channels.
- Custom Fit:Panel-ready and built-in specifications integrate with cabinetry for luxury kitchen renovations. Architect and designer specification drives margin capture.
- Compact:Under-counter and dormitory-scale units face displacement from counter-depth alternatives in secondary kitchen applications. Maturity pressures constrain growth.
Standard size commands volume. Custom fit captures margin expansion.
Technology:
Application-driven technology adoption separates grid-responsive premium platforms from baseline replacement units, with regulatory pressure accelerating compressor transitions.
- Smart Refrigerators:WiFi-enabled inventory management, energy optimization algorithms, and voice assistant integration reshape buyer expectations. DOE efficiency standards and IRA incentives compress payback periods for connected platforms in California and New York markets.
- Energy Efficient:Inverter compressor technology with variable-speed drive electronics satisfies Title 24 compliance documentation. Kitchen renovation contractors specify these for energy performance claims.
- Frost Free:Automated defrost systems with adaptive algorithms maintain consistent temperatures without manual intervention. Dominates mid-tier and premium segments.
- Manual Defrost:Simplified refrigeration systems with periodic maintenance requirements persist in garage and utility applications. Price positioning sustains niche demand.
Frost free dominates installed base. Smart refrigerators are climbing the fastest.
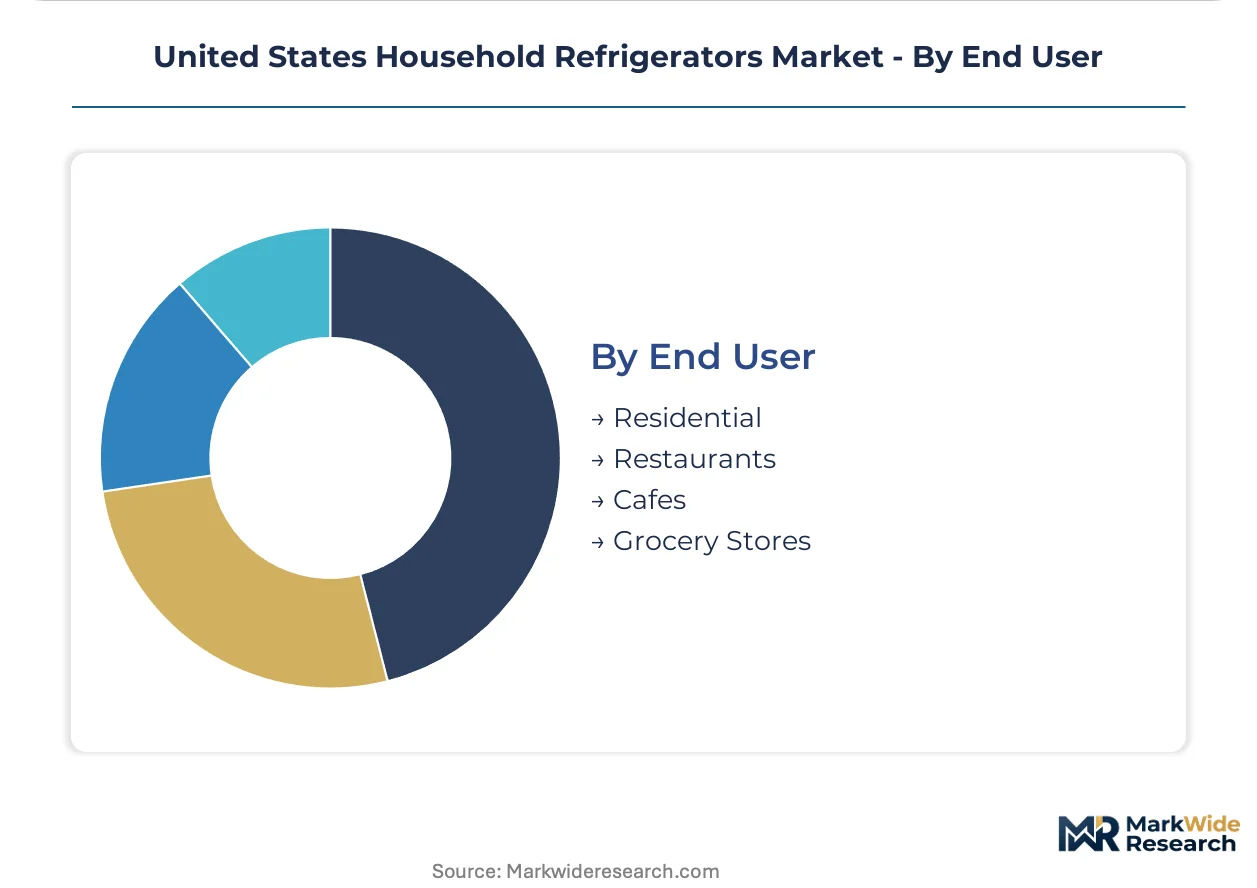
End User:
Customer type determines service-touch requirements, warranty terms, and channel configuration, with residential replacement exhibiting distinct procurement patterns from commercial foodservice.
- Residential:Single-family and multi-family households drive replacement cycles tied to housing turnover and kitchen renovation spending. Direct-to-consumer channels and big-box retailers capture volume in Sun Belt states.
- Restaurants:Commercial kitchen specifications demand NSF certification and rapid temperature recovery under door-opening loads. Equipment dealers maintain service-touch advantages.
- Grocery Stores:Convenience retail and small-format food retail require display merchandising integration and energy monitoring capabilities. Utility rebate programs influence procurement.
- Cafes:Limited-menu foodservice operations prioritize under-counter refrigeration and beverage display integration. Compact and custom fit sizes align with space constraints.
Residential dominates installed base. Grocery stores represent emerging specification pull-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Sun Belt housing corridors where new construction absorbs premium configurations, while legacy manufacturing regions face compressed margins on replacement volume. Texas and Florida command specification premiums for French door and smart-enabled units. California's regulatory density accelerates technology transitions faster than national adoption curves.
Texas
Single-family residential construction in Dallas-Fort Worth and Houston metroplexes drives replacement cycle acceleration for full-size kitchen appliances. DOE appliance efficiency standards and state-level energy codes compress payback periods for inverter compressor upgrades. San Antonio and Austin housing formation outpaces national averages, pulling smart-home integration features into mid-tier specifications.
Florida
Hurricane-resistant construction codes and elevated humidity requirements shape insulation material selection and compressor durability specifications. Miami and Tampa kitchen renovation contractors specify French door configurations for premium aesthetic upgrades in coastal new construction. Florida building energy codes align with federal IRA electrification incentives for energy-efficient appliance procurement.
California
Title 24 building energy standards mandate heat pump compatibility and grid-responsive operation for residential appliances. Los Angeles and San Francisco metro corridors exhibit fastest smart refrigerator adoption as WiFi-enabled inventory management satisfies renovation contractor specification requirements. California Energy Commission efficiency regulations accelerate vacuum-insulated panel transitions ahead of federal compliance deadlines.
New York
Urban density constraints in New York City and surrounding metro areas displace compact units with counter-depth alternatives commanding premium positioning. State-level electrification incentives and utility rebate programs influence procurement patterns for multi-family housing developers. Buffalo and Rochester industrial corridors maintain legacy manufacturing infrastructure for standard-size replacement volume.
Illinois
Midwest distribution hub concentration in Chicago supports inventory availability and delivery speed for mass-market replacement cycles. Illinois energy efficiency programs complement federal tax credits for inverter compressor technology adoption. Suburban Chicago housing turnover sustains dealer network service-touch advantages in segments resistant to direct-to-consumer channel migration.
United States Household Refrigerators Market Competitive Landscape
Diversified appliance conglomerates and electronics specialists split the market across technology-led and distribution-led competitive vectors. The vendor base concentrates among vertically integrated manufacturers controlling compressor production and brand portfolios spanning multiple price tiers. Two strategic archetypes dominate: ecosystem integrators leveraging smart-home platform connectivity, and efficiency specialists commanding inverter drive electronics expertise. Competitive moves center on direct-to-consumer channel buildout and state-level regulatory pre-positioning for electrification incentive capture.
Among diversified appliance manufacturers, Whirlpool Corporation and GE Appliances exemplify scale-driven archetypes with established dealer networks and service infrastructure. LG Electronics and Samsung Electronics represent technology-forward specialists originating from Korean electronics conglomerates, occupying positions defined by inverter compressor and smart-home ecosystem capabilities. Haier Group anchors Chinese multinational participation through appliance portfolio breadth. Robert Bosch GmbH and Panasonic Corporation illustrate diversified industrial conglomerates with appliance segments sitting within broader technology and engineering portfolios. Electrolux and Frigidaire maintain European-rooted positions in North American replacement markets through brand heritage and retail channel relationships.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| GE Appliances |
| LG Electronics |
| Samsung Electronics |
| Electrolux |
| Haier Group |
| Frigidaire |
| Robert Bosch GmbH |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Chicago distribution hub concentration anchors inventory positioning for mass-market replacement cycles, compressing delivery premiums in Midwest corridors while amplifying price leverage for manufacturers controlling compressor production in-house.
Pricing Analysis
Configured-to-order panel-ready and built-in specifications command 40-60% premiums over standard-size transactional units, with price differentiation driven by architect specification pull-through and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels faces compression from direct-to-consumer channel disintermediation that strips white-glove margins from dealer networks. Cost volatility in copper tubing and electrical steel inputs is intensifying margin pressure on mid-tier inverter compressor platforms. Rental property managers and secondary residence owners exhibit highest price sensitivity, while kitchen renovation contractors in Texas and Florida absorb premium positioning for aesthetic upgrades.
Supply Chain Analysis
Electrical steel and copper tubing feedstock sourcing concentrates in China, South Korea, and domestic US foundries, with compressor manufacturing drawing from Japanese and Korean motor control expertise. Vacuum-insulated panel production rests on Korean and European supplier bases for core materials. Single-source vulnerability in low-GWP refrigerant alternatives under EPA SNAP phase-down timelines creates qualification bottlenecks for next-generation platform launches. Distribution runs through big-box retail consolidation in Sun Belt states and direct-to-consumer fulfillment centers displacing traditional dealer intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Household Refrigerators Market functions as a defensive-moat arena where regulatory entrenchment around DOE efficiency standards and EPA refrigerant rules creates substantial compliance barriers for unqualified entrants.
For Market Incumbents: Build switching-cost moats through proprietary smart-home ecosystem integration that locks replacement buyers into platform-specific connectivity protocols. Deepen captive supply of inverter drive electronics to offset commodity volatility in copper and steel inputs. Compress response windows to FTC EnergyGuide certification timeline changes through pre-positioned testing infrastructure. For New Entrants and Emerging Players: Pursue white-space capture in counter-depth category expansion within California and New York urban density corridors where full-featured alternatives displace compact units. Target state-level electrification incentive stacking in California Title 24 compliance documentation services for renovation contractors. Anchor go-to-market through virtual kitchen design tools that bypass established dealer network gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive compressor production and smart-home platform assets over pure-brand marketers. Long-term viability hinges on regulatory pre-positioning for refrigerant transitions and inverter technology absorption curves. Acquisition screening should prioritize electromechanical design specialist teams with variable-speed motor control expertise. Monitor EPA SNAP implementation pace and state electrification incentive renewal as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Technology Licensing | Accelerates compliance with DOE 2029 efficiency mandates while capturing IRA tax credit pass-through. |
| Direct-to-Consumer Channel Buildout | Disintermediates dealer networks in Sun Belt replacement markets through virtual configuration tools. |
| Smart-Home Platform Integration | Locks replacement buyers into ecosystem-specific connectivity protocols that raise switching costs. |
| Vacuum-Insulated Panel Supply Agreement | Secures thermal performance materials ahead of California Title 24 accelerated compliance deadlines. |
| State-Level Regulatory Pre-Positioning | Captures electrification incentive stacking in California and New York procurement specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with kitchen renovation contractors, big-box retail category buyers, appliance dealer network managers, and compressor engineering specialists. Secondary validation drew from DOE appliance efficiency standard filings, EPA SNAP regulatory dockets, California Energy Commission Title 24 documentation, and customs records for electrical steel and copper tubing imports. Bottom-up unit shipment modeling and top-down value reconciliation triangulated market sizing across product configuration, technology tier, and regional demand clusters.
Calibration against historical efficiency standard implementation curves and housing formation data in Texas, Florida, and California anchored projection parameters across the analysis window. Segmentation modeling incorporated product type, size tier, technology platform, and end-use application dimensions with regional regulatory cluster overlays. CAGRs derived from replacement cycle velocity analysis and new construction absorption rates in Sun Belt corridors, cross-referenced with IRA incentive impact assumptions and refrigerant transition timelines.
Macroeconomic conditions sit as an overlay; deviation in single-family residential construction permits, mortgage rate trajectories, or copper futures pricing would shift the trajectory. Forecasts reflect documented assumptions around DOE standard enforcement timing and state electrification program continuity. Quarterly review of housing starts data, refrigerant qualification approvals, and smart-home platform adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Refrigerator Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market