
 Side-By-Side Smart Refrigerator Market | 2026-2036
Side-By-Side Smart Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Side-By-Side Smart Refrigerator Market Insights
REACH compliance in Europe is pivoting the cost-of-entry calculus for manufacturers sourcing refrigerants and insulation foams. Samsung Electronics leverages its vertical integration in display and semiconductor supply chains to control smart interface costs. LG Electronics anchors its position through in-house compressor technology and deep R&D investment in energy-efficient cooling systems. Whirlpool Corporation differentiates via brand strength in North American retail channels and sustained manufacturing scale across multiple continents.
A side-by-side smart refrigerator denotes a full-height refrigeration appliance with vertically split compartments—fresh food on one side, freezer on the other—equipped with internet connectivity, embedded sensors, and digital interfaces for inventory tracking, energy optimization, and remote diagnostics. These units typically employ variable-speed inverter compressors, multi-zone climate control, and low-global-warming-potential refrigerants to meet commercial and residential cooling requirements with precision. The French Door product configuration commands the strongest margin pool as consumers prioritize aesthetic integration and flexible storage geometry. Wi-Fi Enabled technology leads volume penetration due to its foundational role in app-based monitoring and over-the-air firmware updates, while Voice Control represents the fastest-expanding interface layer as natural-language processing migrates from smart speakers to kitchen appliances.
The EPA regulates refrigerant transitions under SNAP rules, the EU enforces F-Gas Regulation phase-down schedules, and China's MEE imposes dual carbon goals that shape compressor efficiency mandates across manufacturing bases. These frameworks collectively elevate R&D spend thresholds and disqualify non-compliant suppliers from tender participation in regulated jurisdictions. Stakeholders must monitor refrigerant chemistry transitions and energy-label recalibrations as the primary variables that will determine which product portfolios retain market access.
Market Dynamics
Variable-speed inverter compressors are compressing energy consumption benchmarks while F-Gas Regulation phase-down schedules in Europe force refrigerant chemistry transitions across manufacturing footprints.
Growth Catalysts
- Residential smart home integration:Connected kitchen ecosystems in the United States, China, and Germany pull demand as consumers synchronize appliances with centralized home automation platforms.
- EPA SNAP refrigerant rules:The United States mandates low-global-warming-potential alternatives, creating compliance-driven replacement cycles among existing installed bases.
- Wi-Fi Enabled technology penetration:App-based inventory tracking and remote diagnostics expand addressable demand among tech-forward households seeking operational transparency.
Market Restraints
- Copper and steel input volatility:Compressor housing and heat exchanger materials face commodity price swings that compress margin predictability for OEMs.
- Display panel supply concentration:Semiconductor and TFT-LCD sourcing clusters in East Asian foundries, exposing manufacturers to single-region disruption risk.
- Voice Control integration complexity:Natural-language processing engines require sustained software engineering investment that smaller appliance brands cannot sustain internally.
Strategic Opportunities
- India residential electrification:Rising middle-class appliance penetration in Tier-2 and Tier-3 cities creates first-mover positioning for connected refrigerator portfolios.
- EU Green Deal appliance subsidies:Member state rebate programs for A+++ energy-rated products accelerate premium segment conversion in Germany, France, and Italy.
- AI-driven predictive maintenance:Sensor fusion between temperature telemetry and compressor vibration analytics enables subscription service revenue models.
Industry Challenges
- Refrigerant certification timelines:ECHA REACH compliance documentation for new foam formulations extends product development cycles by 12-18 months.
- Cross-platform software fragmentation:Proprietary smart home protocols from Amazon Alexa, Google Home, and Apple HomeKit force multi-certification engineering overhead.
- Field service technician training:Connected diagnostics and inverter compressor repair require upskilling legacy appliance maintenance networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side-By-Side Smart Refrigerator Market |
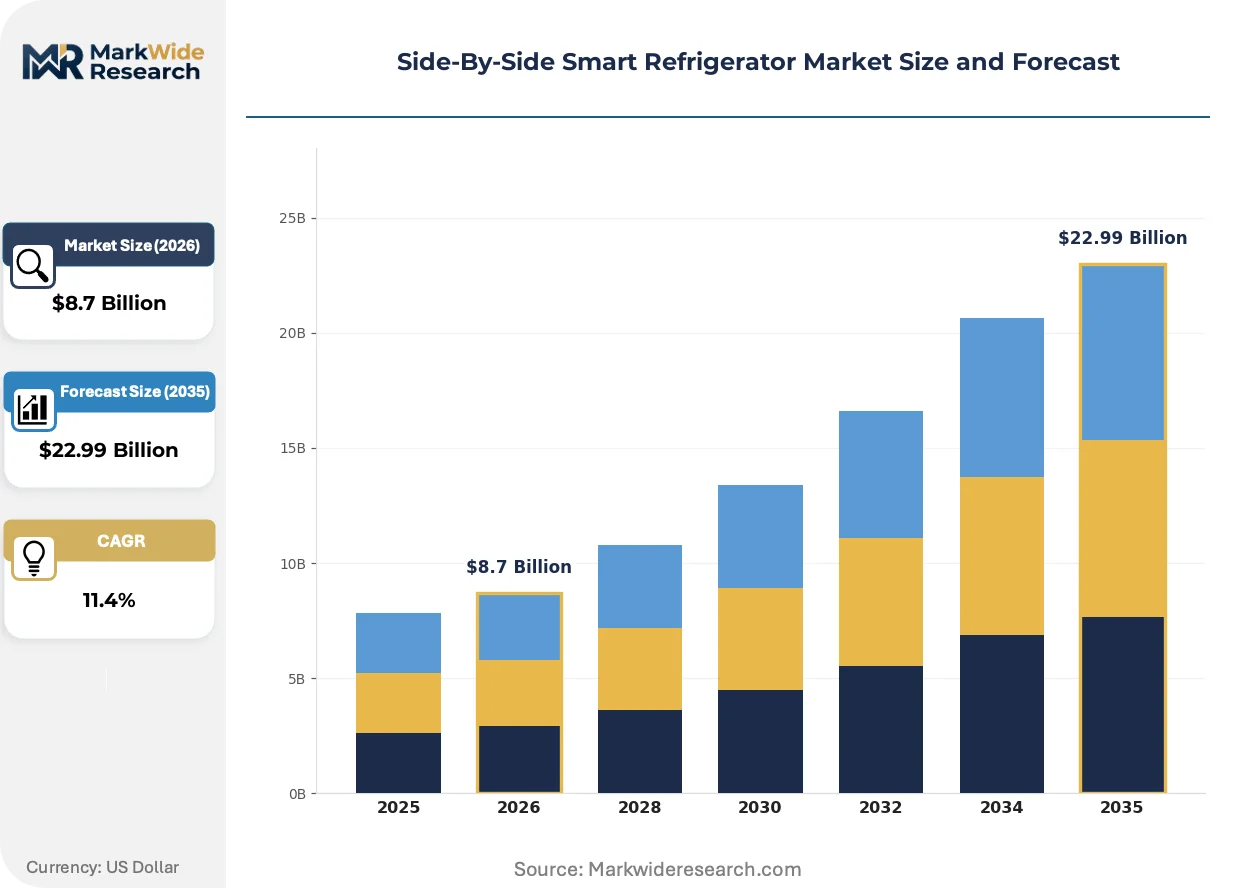
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Star, French Door, Built-In, Counter Depth Technology: Wi-Fi Enabled, Touchscreen Display, Smart Sensors, Voice Control End User: Households, Restaurants, Hotels, Catering Services Distribution Channel: Online Retail, Specialty Stores, Appliance Showrooms, Warehouses |
| Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Haier Group Corporation, Electrolux AB, GE Appliances, Hisense Co. Ltd, Midea Group, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side-By-Side Smart Refrigerator Market Trends and Innovations
Digital interface layers are migrating from novelty features to core purchase criteria as buyers prioritize seamless ecosystem integration over standalone hardware specifications.
Multi-zone climate control is consolidating fresh-food preservation precision. Premium residential buyers in Germany and the United States specify independent humidity and temperature zones for produce, meat, and dairy compartments. This capability compresses differentiation timelines for manufacturers lacking variable-speed compressor architectures.
China's MEE dual carbon goals are tightening compressor efficiency mandates. The policy framework elevates minimum performance coefficients for cooling appliances manufactured or imported into the country. Domestic Chinese brands and multinational OEMs with Chinese production bases must redesign motor and insulation systems to retain market access.
Subscription-based filter and consumable replenishment is displacing transactional aftermarket sales. Smart inventory sensors trigger automatic water filter and ice maker cartridge shipments before depletion. This model concentrates in United States retail channels where Amazon Dash Replenishment and proprietary OEM services capture recurring revenue from installed bases.
Side-By-Side Smart Refrigerator Market Segmentation
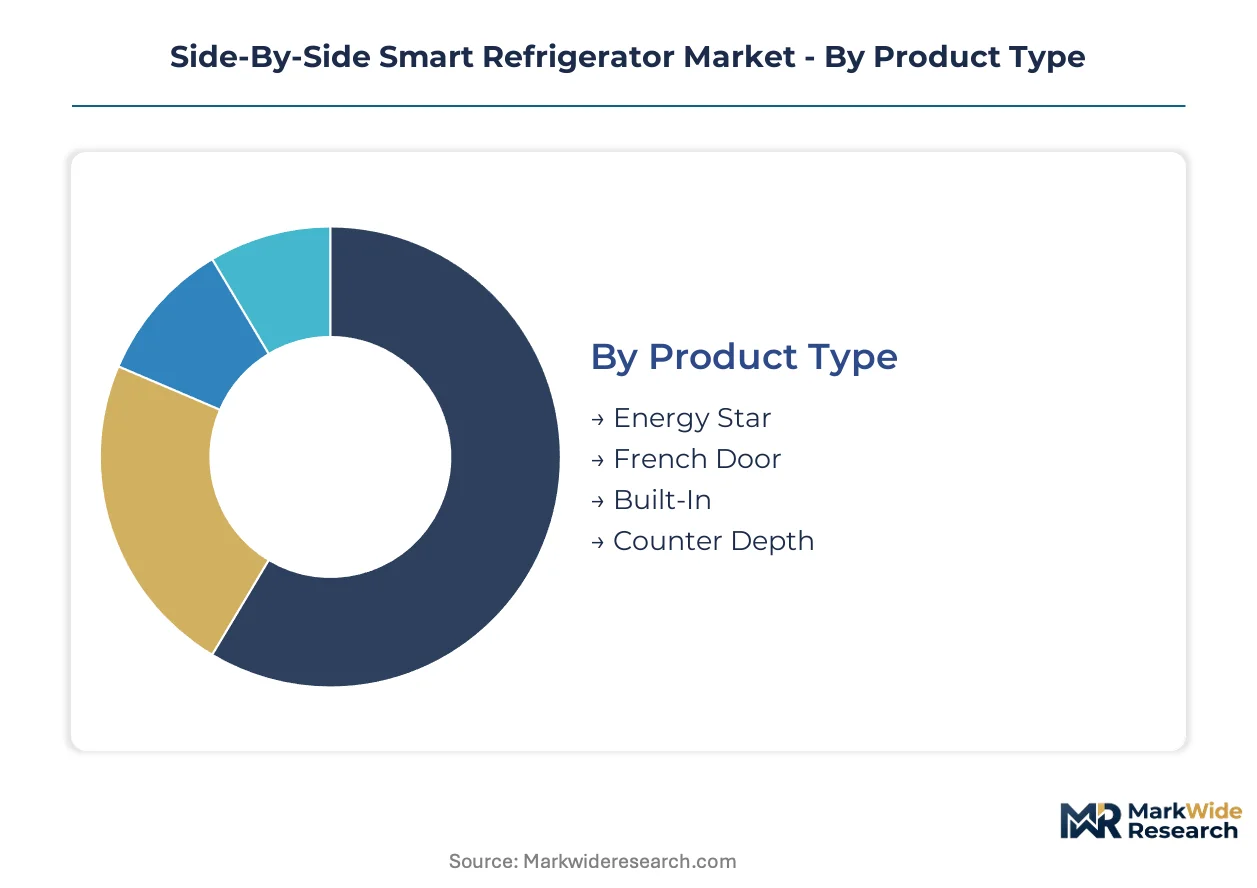
Segmentation in the side-by-side smart refrigerator market reveals distinct performance tiers across product architecture, interface technology, and procurement channels. Manufacturers align R&D budgets and distribution investments against these fault lines to capture premium margins or volume scale.
Product Type:
Standalone refrigeration units dominate residential installations, while built-in configurations embed within custom kitchen cabinetry for luxury segments.
- French Door:Vertically split fresh food compartments with bottom-mount freezer drawers maximize storage flexibility. Demand concentrates in the United States and Germany where kitchen renovation cycles and aesthetic integration priorities drive specification. This configuration commands the strongest margin pool due to premium positioning and complex hinge engineering.
- Energy Star:Certified units meet EPA efficiency thresholds through variable-speed compressors and advanced insulation. Procurement clusters in California and New York where state-level rebate programs and utility incentives accelerate replacement cycles. Regulatory pressure tightens minimum efficiency coefficients annually.
- Built-In:Cabinet-depth units with panel-ready exteriors integrate seamlessly with surrounding millwork.
- Counter Depth:Shallower profiles align with standard countertop dimensions for space-constrained kitchens.
French Door leads volumes today; Energy Star is gaining share fastest.
Technology:
Interface layers range from passive connectivity modules to active voice-controlled systems, with cost and engineering complexity scaling accordingly.
- Wi-Fi Enabled:Foundational connectivity enables remote temperature monitoring, energy tracking, and over-the-air firmware updates. Penetration runs deepest in tech-forward United States households and Chinese urban centers where smartphone ecosystem integration drives purchase decisions. This layer serves as the baseline for all subsequent smart feature stacking.
- Voice Control:Natural-language processing engines from Amazon Alexa and Google Home migrate from smart speakers to appliance interfaces. Adoption accelerates fastest in Germany and the United States where hands-free operation during food preparation commands premium pricing. Engineering investment requirements disadvantage smaller OEMs lacking software development scale.
- Touchscreen Display:Embedded TFT-LCD panels deliver inventory visualization, recipe suggestions, and calendar integration.
- Smart Sensors:Temperature, humidity, and door-open telemetry enable predictive maintenance algorithms and automated climate adjustment.
Wi-Fi Enabled dominates installed base; Voice Control climbs the fastest.
End User:
Residential procurement patterns diverge sharply from commercial foodservice requirements in capacity, connectivity, and service expectations.
- Households:Residential buyers prioritize ecosystem integration, energy labeling, and finish aesthetics over raw cooling capacity. Demand clusters most intensely in the United States, China, and Germany where smart home infrastructure investment and premium appliance penetration run deepest. Connected kitchen synchronization with centralized automation platforms drives replacement timing.
- Restaurants:Commercial kitchens require NSF-certified construction, rapid temperature recovery, and remote monitoring for HACCP compliance.
- Hotels:In-room minibars and suite kitchenettes specify compact footprints with silent operation and minimal energy draw.
- Catering Services:Mobile and event-based operations demand portable units with generator-compatible power systems and ruggedized construction.
Households anchor volume today; Restaurants show steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture, brand positioning, and post-sale service attachment rates for manufacturers.
- Online Retail:Amazon and direct-to-consumer platforms capture price-sensitive buyers and subscription filter replenishment attach. Penetration concentrates in the United States where Dash Replenishment integration and financing options reduce purchase friction. Logistics networks enable white-glove delivery and installation coordination.
- Specialty Stores:Independent dealers provide consultative selling, custom panel matching, and local service relationships.
- Appliance Showrooms:Manufacturer-flagship and multi-brand galleries emphasize tactile experience and premium finish comparison.
- Warehouses:Costco and similar clubs move high-volume SKUs with extended warranties and bundled installation packages.
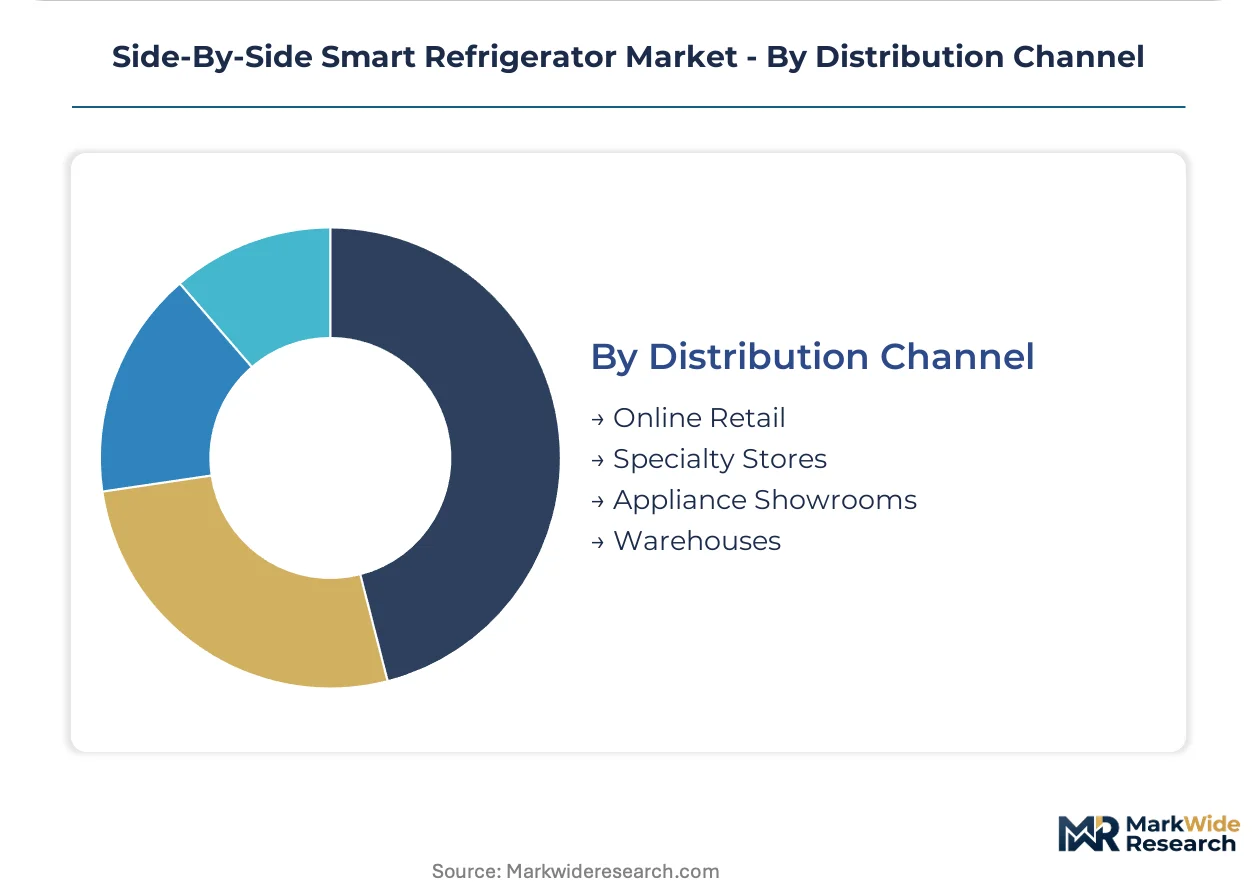
Online Retail leads transaction growth; Specialty Stores retain margin advantage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in appliance electronics concentrate in South Korea, Germany, and China's coastal manufacturing belts, anchoring R&D investment and smart feature development.
United States
Residential smart home integration and kitchen renovation cycles drive replacement demand in California and Texas. The EPA enforces SNAP refrigerant phase-down rules that compel low-global-warming-potential transitions. Appliance manufacturing clusters in the Midwest, where Ohio and Michigan facilities retrofit compressor lines for energy-efficiency compliance.
Germany
Premium appliance penetration and aesthetic kitchen integration prioritize French Door configurations in Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation mandates refrigerant chemistry transitions with binding phase-down schedules. Berlin-Brandenburg hosts R&D centers where manufacturers test multi-zone climate control systems for EU energy-label compliance.
China
Urban middle-class expansion and connected home platform adoption accelerate smart refrigerator uptake in Shanghai and Beijing. The MEE imposes dual carbon goals that tighten minimum compressor efficiency coefficients. The Yangtze River Delta manufacturing corridor dominates inverter compressor production and TFT-LCD panel sourcing for digital interfaces.
India
Rising electrification in Tier-2 and Tier-3 cities creates first-mover opportunities for connected appliance portfolios in Maharashtra and Gujarat. BIS certification requirements and energy-labeling standards elevate product entry thresholds. The Delhi-NCR corridor attracts distribution investment as online retail penetration expands beyond metro centers.
Japan
Space-constrained urban households and aging demographics favor compact, sensor-rich refrigeration in Tokyo and Osaka. METI efficiency standards and JIS certification frameworks shape product specification. The Kansai region maintains precision manufacturing clusters for variable-speed compressor components and smart sensor modules.
Side-By-Side Smart Refrigerator Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive semiconductor and display supply chains. Market concentration reflects scale advantages in smart interface development and compressor technology. Three archetypes dominate: vertically integrated Korean-Japanese electronics groups, North American brand houses with retail channel depth, and Chinese appliance conglomerates with cost-engineering scale. Competitive moves center on refrigerant compliance certification and voice-control platform partnerships.
Among Korean electronics groups, Samsung Electronics and LG Electronics exemplify the vertically integrated archetype through captive control over display and semiconductor inputs. Whirlpool Corporation anchors the North American brand-house position with manufacturing scale across multiple continents. Haier Group Corporation represents Chinese engineering-scale competitiveness in connected appliance platforms. These three companies occupy distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Whirlpool Corporation |
| Haier Group Corporation |
| Electrolux AB |
| GE Appliances |
| Hisense Co. Ltd |
| Midea Group |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
EPA SNAP refrigerant mandates and EU F-Gas phase-down schedules are forcing manufacturers to absorb compliance costs or pass them through, compressing margin pools for non-integrated OEMs while rewarding suppliers with captive compressor and foam formulation capabilities.
Pricing Analysis
Service bundling separates hardware from recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy-label grade and smart feature depth. Cost compression in the economy tier is intensifying because commodity steel and copper volatility feeds into compressor housing expenses. Mass-market retailers exhibit highest price sensitivity, while luxury kitchen renovators prioritize finish aesthetics over unit economics.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China anchor hub-and-spoke fulfillment patterns for finished goods. Inverter compressor production draws from South Korea, China, and Japan, while TFT-LCD panel sourcing rests on Taiwanese and Chinese foundries. Single-source vulnerability in semiconductor substrates exposes manufacturers to geopolitical disruption. Distribution runs through direct-to-consumer platforms and specialty dealer networks with white-glove installation coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as residential smart home penetration deepens replacement cycles and pulls premium upgrade demand through connected kitchen ecosystems.
For Market Incumbents: Anticipate refrigerant chemistry transitions by securing ECHA REACH certification pipelines early, compressing product development timelines for compliant foam formulations. Deepen backward integration into inverter compressor manufacturing to defend margin position against commodity input volatility. Voice-control platform fragmentation from Amazon Alexa, Google Home, and Apple HomeKit threatens ecosystem lock-in advantages. For New Entrants and Emerging Players: Launch via online retail platforms with subscription filter replenishment attach to capture recurring revenue without legacy service network overhead. India's Tier-2 and Tier-3 cities present the most penetrable geography as electrification expands middle-class appliance adoption. Target Wi-Fi Enabled baseline configurations to avoid engineering investment in natural-language processing engines. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated electronics conglomerates with captive display and semiconductor supply chains. The five-to-ten-year viability window favors manufacturers controlling smart interface costs internally. Monitor refrigerant certification timelines as the primary inflection signal for portfolio access risk in regulated jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Compliance Certification | ECHA REACH documentation for low-GWP foam formulations secures EU market access ahead of F-Gas phase-down deadlines. |
| Voice Control Platform Partnership | Integration with Amazon Alexa or Google Home ecosystems differentiates premium interfaces for hands-free kitchen operation. |
| Inverter Compressor Backward Integration | In-house production of variable-speed motors reduces exposure to commodity steel and copper price volatility. |
| Subscription Service Launch | Automatic filter replenishment via Amazon Dash Replenishment captures recurring revenue from installed bases in United States retail. |
| India Distribution Expansion | Delhi-NCR corridor investment positions portfolios for rising electrification in Maharashtra and Gujarat Tier-2 cities. |
Research Methodology
Multiple input streams — executive interviews with appliance OEM product managers, procurement directors at compressor suppliers, and smart home platform engineers — were reconciled against customs trade data, EPA SNAP regulatory filings, and EU energy-label compliance databases. Secondary validation drew from SEC 10-K disclosures, BIS certification records, and MEE efficiency standard publications. Bottom-up unit shipment modeling and top-down macroeconomic scaling were triangulated to anchor volume estimates.
Data-stream reconciliation across product type, interface technology, end-user segment, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical replacement cycles and regulatory compliance deadlines. Smart sensor penetration rates and voice-control adoption curves served as industry-specific forecast inputs alongside compressor efficiency coefficient trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt refrigerant chemistry bans or semiconductor supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Appliance Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Russia Home Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
Refrigerator Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market