
 Laundry Appliances Market | 2026-2036
Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Laundry Appliances Market Outlook
Heat-pump drying technology is reconfiguring energy consumption profiles across the industry. Miele leverages its European engineering base to sustain premium positioning in heat-pump systems. Samsung anchors its competitive stance through connected-home ecosystems that integrate laundry cycles with broader appliance networks. Whirlpool dominates North American replacement demand through extensive service infrastructure and dealer relationships.
Laundry appliances encompass electromechanical systems designed for fabric cleaning and drying, typically operating through programmable cycles with temperature ranges from cold wash at 20°C to sanitize modes exceeding 60°C, utilizing drum rotation, water agitation, and forced-air or condensation-based moisture extraction for residential and commercial textile maintenance. Front-load washing systems command the largest installed base due to superior water efficiency and gentler mechanical action on fabrics, while smart appliances represent the fastest-expanding technology segment as connectivity enables remote diagnostics, cycle optimization, and utility demand-response integration. The commercial end-user category concentrates margin pools in vended laundry and on-premise hospitality operations where equipment utilization rates justify premium pricing for durability and service contracts.
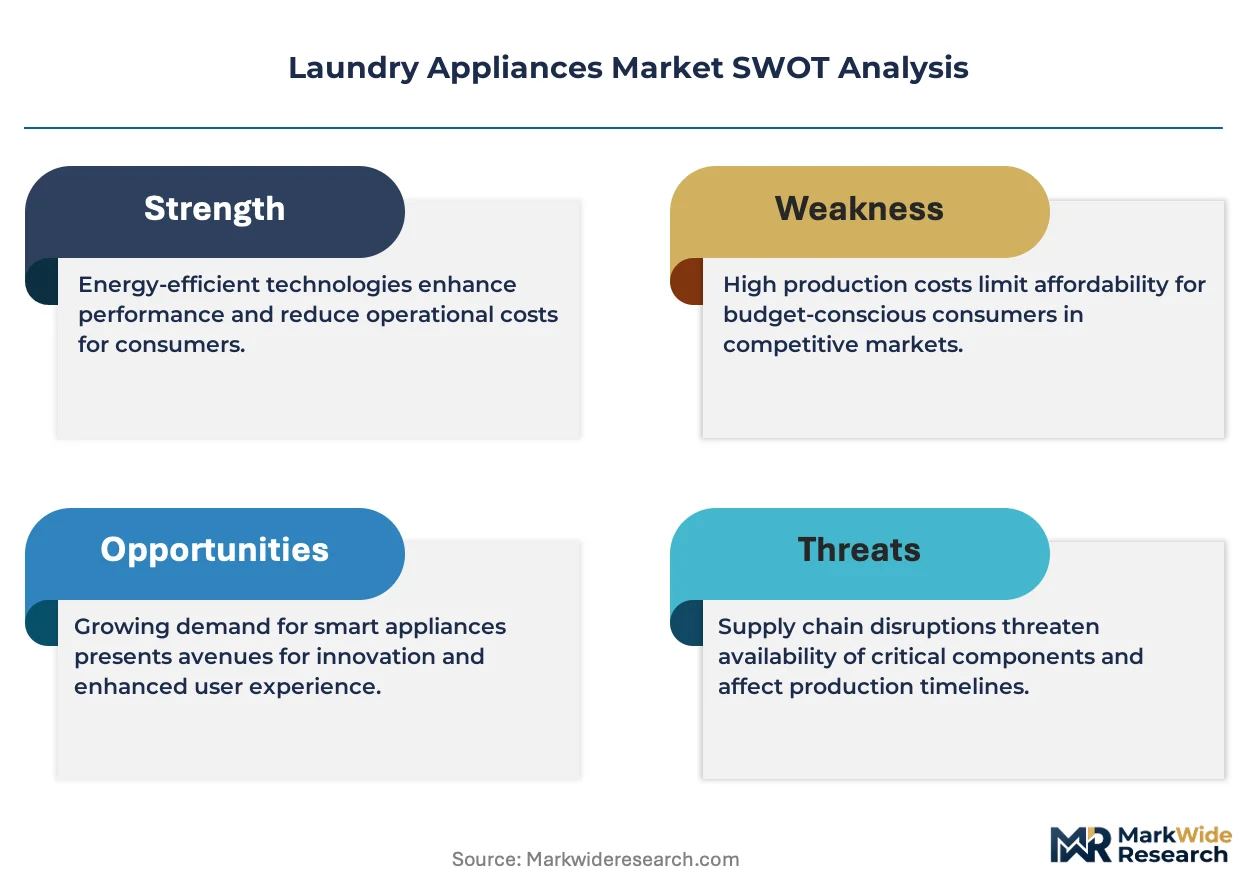
The U.S. Department of Energy sets minimum efficiency standards that manufacturers must meet for market access, while the EPA's ENERGY STAR certification creates a voluntary tier that shapes consumer preference and retailer assortment decisions. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant choices and energy consumption limits for appliances sold across member states. Stakeholders must monitor how tightening efficiency mandates interact with material cost inflation and consumer willingness to absorb price premiums for certified products.
Market Dynamics
Heat-pump drying systems are compressing energy consumption benchmarks while forcing manufacturers to retool compressor supply chains and refrigerant portfolios. The U.S. Department of Energy's efficiency thresholds are accelerating obsolescence of conventional vented dryers.
Growth Catalysts
- Appliance efficiency mandates:The U.S. Department of Energy's tightening water and electricity thresholds are pulling forward replacement cycles in North American multi-housing units.
- Urban apartment density:China's compact washer-dryer combo demand concentrates in tier-one cities where floor space constraints dominate purchase decisions.
- Heat-pump technology maturation:European engineering advances in closed-loop drying systems are reducing unit costs and expanding addressable markets beyond premium tiers.
Market Restraints
- Refrigerant supply concentration:EU F-Gas Regulation constraints on hydrofluorocarbon availability are tightening compressor input costs for heat-pump dryer manufacturers.
- Steel and copper volatility:Drum assemblies and motor windings face raw material price swings that compress margin predictability at volume tiers.
- Technical service infrastructure:Heat-pump system complexity requires specialized technician training that lags behind installation growth in secondary markets.
Strategic Opportunities
- India urbanization wave:Penetration rates below 15 percent in semi-urban households create white space for compact, low-water-consumption systems.
- Demand-response integration:Utility-sponsored load-shifting programs are creating revenue streams for connected-appliance ecosystems that automate cycle timing.
- Commercial vended laundry expansion:On-premise hospitality and student housing operators are consolidating equipment procurement around service-contract bundled offerings.
Industry Challenges
- Certification timeline compression:EPA ENERGY STAR and EU Ecodesign recertification cycles are accelerating, straining product development bandwidth.
- Legacy control system integration:Smart appliance connectivity protocols must interoperate with existing building management systems in commercial installations.
- Field technician skill gaps:Heat-pump refrigeration loop diagnostics and sealed-system repair capabilities remain scarce outside major metropolitan service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laundry Appliances Market |
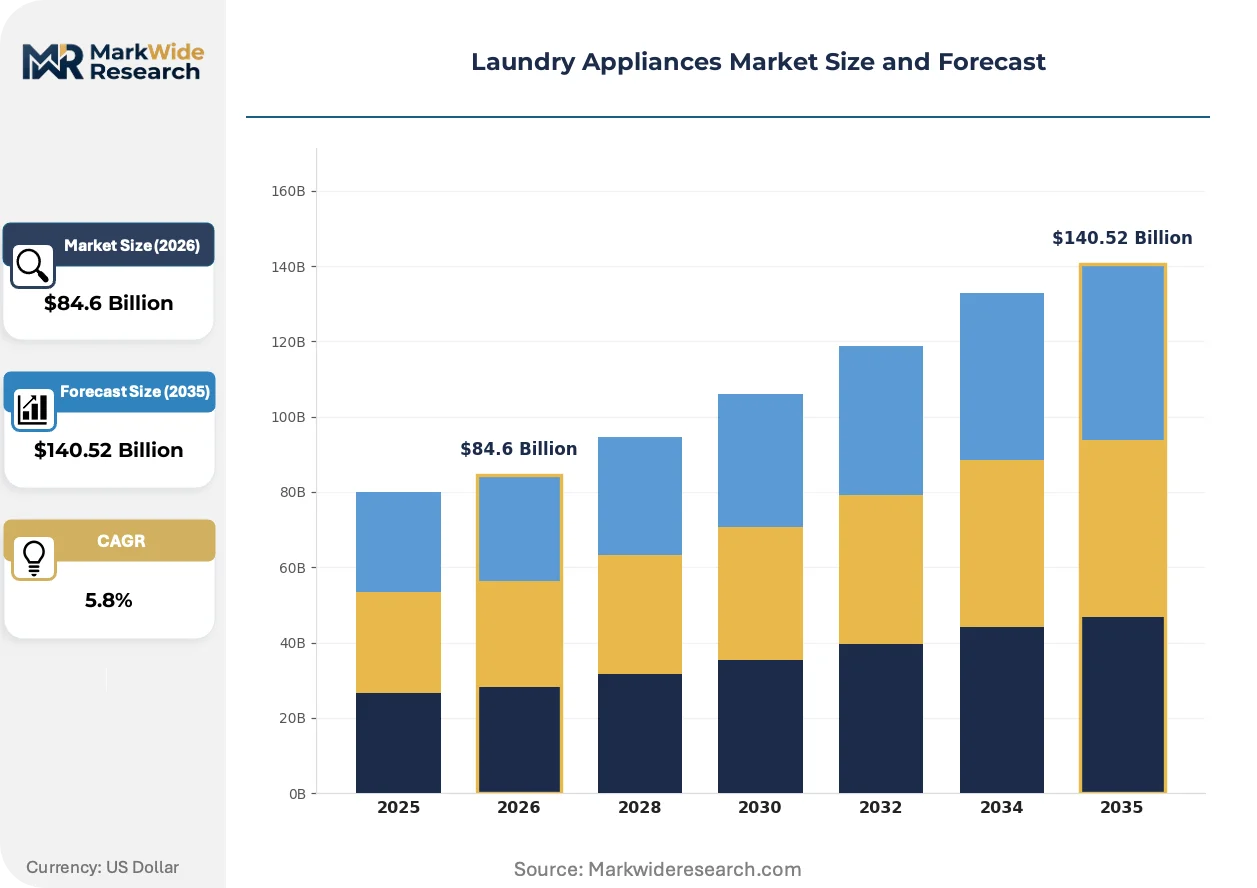
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Portable Washers Technology: Smart Appliances, Inverter Technology, Top Load, Front Load End User: Residential, Commercial, Hospitality, Laundromats Capacity: Compact, Standard, Large, Extra Large |
| Companies Covered | GE, Miele, LG, Maytag, Speed Queen, Whirlpool, Bosch, Electrolux, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laundry Appliances Market Strategic Shifts
Sensor-driven load detection and automated detergent dosing are reconfiguring how manufacturers differentiate hardware beyond capacity and spin speed. Connectivity infrastructure is becoming the primary battleground for recurring revenue attachment.
Intelligent fabric recognition systems are digitizing cycle selection through weight sensors, conductivity probes, and optical spectrum analysis that automatically map textiles to optimal mechanical action and thermal profiles. Multi-housing property managers and premium residential buyers are adopting these systems fastest where labor cost reduction justifies upfront premiums. The technology is digitizing service models by enabling predictive maintenance alerts and remote diagnostic resolution that reduce truck-roll dependency.
The EU F-Gas Regulation is phasing down hydrofluorocarbon quotas through 2030, forcing manufacturers to qualify alternative refrigerants with lower global warming potential for heat-pump dryer compressors. This transition is compressing supplier qualification timelines and accelerating R&D spending on propane and carbon dioxide loop architectures. Heat-pump dryer portfolios destined for European markets are bearing the steepest compliance cost increments and earliest redesign deadlines.
Subscription-based detergent and fabric care provisioning is displacing traditional retail replenishment for connected-appliance owners who accept automated reordering tied to usage telemetry. Direct-to-consumer channels and manufacturer-owned apps are capturing recurring revenue streams that retailers previously intermediated. This pattern concentrates in North American and Western European urban markets where delivery infrastructure and credit-card-on-file penetration enable frictionless replenishment.
Laundry Appliances Market Segmentation
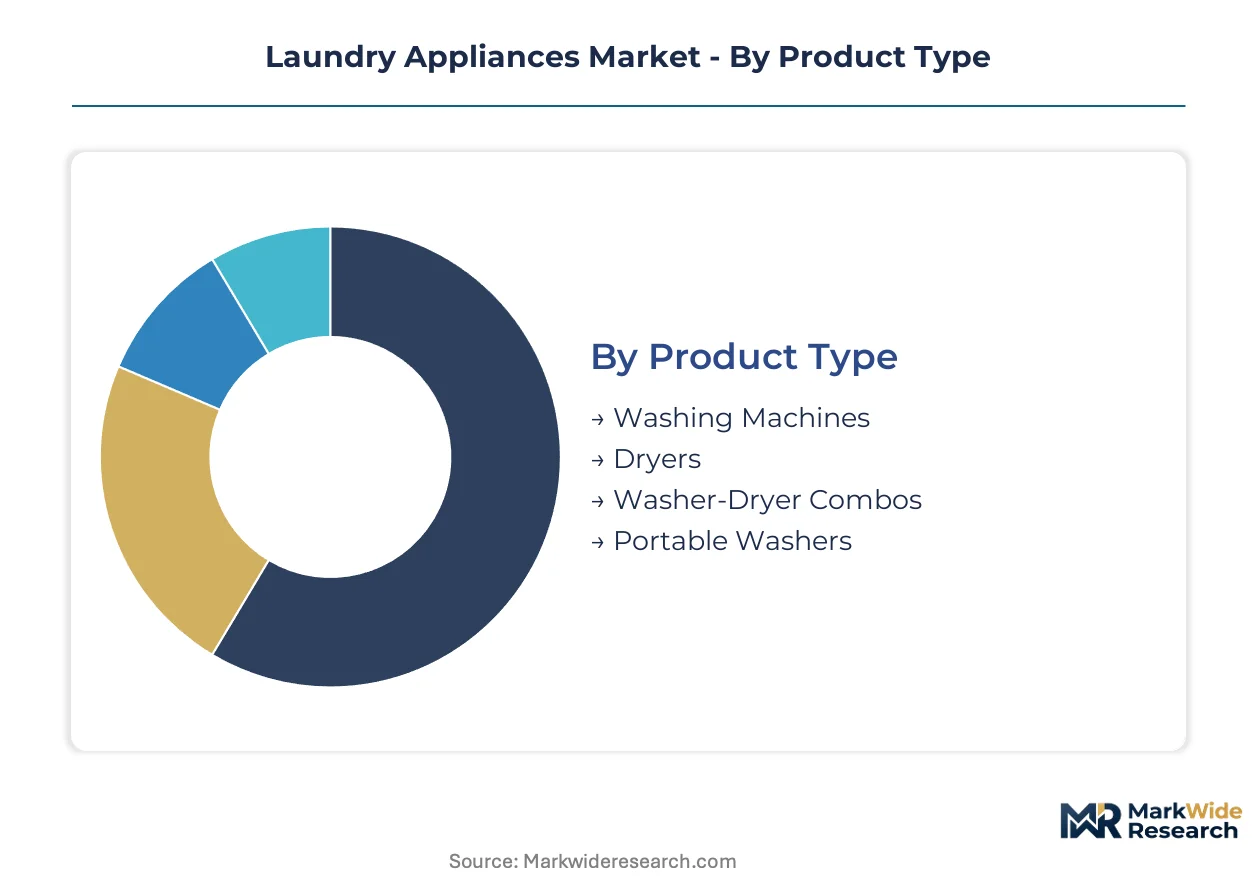
Segmentation in laundry appliances reveals distinct replacement cycles and margin profiles across hardware configurations. Cycle frequency varies from annual commercial refresh schedules to decade-long residential replacement patterns, reshaping inventory and service investment priorities.
Product Type:
Washing machines turn over fastest in commercial settings where daily utilization accelerates mechanical wear, while portable washers exhibit the longest replacement intervals due to intermittent residential use.
- Washing Machines:Electromechanical systems utilizing drum rotation and water agitation across programmable temperature profiles from cold wash to sanitize modes. Demand concentrates in China's tier-one cities where urban apartment density drives front-load preference for water efficiency.
- Dryers:Forced-air or condensation-based moisture extraction systems operating through heated airflow or closed-loop refrigeration. North American multi-housing complexes are pulling forward replacement cycles as DOE efficiency thresholds render conventional vented units obsolete.
- Washer-Dryer Combos:Integrated single-unit systems combining wash and dry functions through sequential programming.
- Portable Washers:Compact, mobile units designed for space-constrained environments with manual water connection requirements.
Washing machines anchor the volume base while washer-dryer combos gain share at the steepest rate.
Technology:
Cost tier stratification separates premium heat-pump and connected systems from standard inverter configurations, with entry-level top-load units dominating emerging market penetration plays.
- Smart Appliances:Connected systems enabling remote diagnostics, cycle optimization, and utility demand-response integration through IoT protocols. North American utility-sponsored load-shifting programs are creating recurring revenue streams for ecosystem operators.
- Inverter Technology:Variable-speed motor drives reducing energy consumption through load-adaptive drum rotation. European markets under Ecodesign Directive constraints show concentrated adoption where electricity tariffs justify upfront premiums.
- Top Load:Vertical-axis washing systems with agitator or impeller mechanisms.
- Front Load:Horizontal-axis drum systems with tumble wash action and superior water efficiency.
Front load systems anchor the volume base while smart appliances expand most quickly.
End User:
Application-specific utilization rates create divergent durability requirements, with commercial operators prioritizing service-contract bundled procurement over residential discretionary replacement.
- Residential:Individual household installations spanning single-family homes and multi-housing units. China's urban apartment density concentrates demand for compact, low-water-consumption configurations.
- Commercial:On-premise operations in hospitality, healthcare, and institutional settings where equipment utilization rates justify premium pricing for durability.
- Hospitality:Hotel and resort on-premise laundry operations with high-throughput requirements.
- Laundromats:Vended self-service facilities with coin or card-operated payment systems.
Residential installations anchor the volume base while commercial applications climb the fastest.
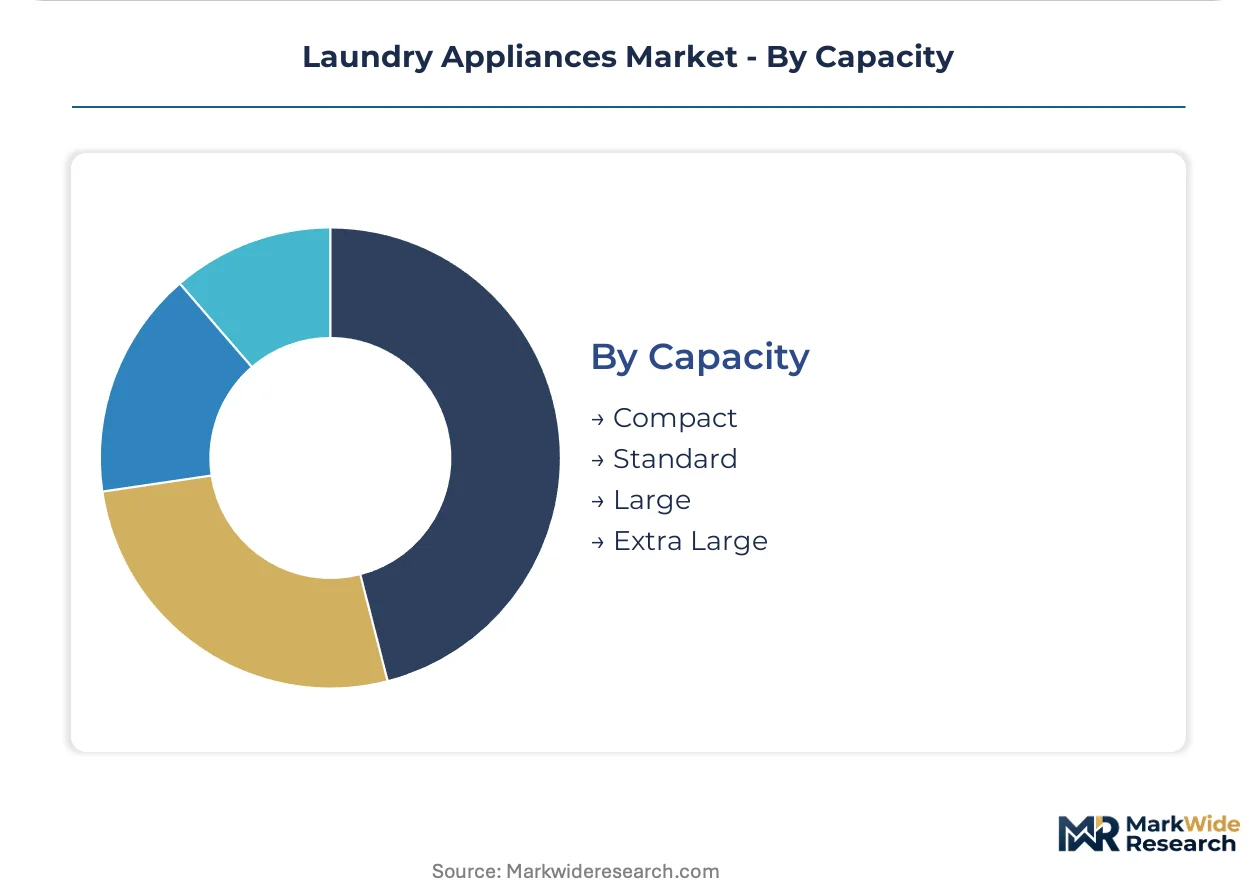
Capacity:
Customer type segmentation separates property managers procuring standardized fleets from individual buyers selecting capacity based on household composition and floor space constraints.
- Compact:Units under 2.5 cubic feet designed for urban apartments and space-constrained installations. European cities with strict building codes show concentrated adoption where utility closet dimensions dictate selection.
- Standard:Mid-range capacity systems serving typical family household requirements.
- Large:Expanded drum capacity for high-volume residential or light commercial use.
- Extra Large:Industrial-scale systems for commercial vended laundry and hospitality operations.
Standard capacity anchors the volume base while compact systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-housing developers and urban apartment buyers concentrate demand across distinct national markets, each shaped by local efficiency mandates and space constraints.
United States
Property managers in multi-housing complexes drive replacement cycles as DOE efficiency thresholds phase out conventional vented dryers. The EPA's ENERGY STAR certification shapes retailer assortment decisions and consumer preference hierarchies. Installation growth concentrates in Texas and Florida metro corridors where new construction permits for rental units exceed national averages.
Germany
EU Ecodesign Directive constraints and F-Gas Regulation refrigerant quotas accelerate heat-pump dryer adoption among efficiency-conscious households. The country's national energy regulator enforces strict electricity consumption labeling that elevates premium-tier sales. Manufacturing and R&D clusters in North Rhine-Westphalia supply compressor technologies for closed-loop drying systems across European markets.
China
Urban apartment density in tier-one cities drives compact washer-dryer combo preference where floor space constraints dominate purchase decisions. The Ministry of Ecology and Environment's dual carbon goals tighten industrial efficiency standards for appliance manufacturing. Shanghai and Beijing metropolitan areas show concentrated adoption of connected-home ecosystems that integrate laundry cycles with broader appliance networks.
India
Semi-urban households with penetration rates below 15 percent create white space for low-water-consumption front-load systems. The Bureau of Indian Standards mandates efficiency labeling that shapes mid-tier purchasing decisions. Maharashtra and Gujarat industrial corridors host assembly operations targeting compact configurations for space-constrained urban apartments.
Japan
Metropolitan Tokyo and Osaka households prioritize space-efficient heat-pump and washer-dryer combo installations. METI appliance efficiency standards exceed regional baselines and compress replacement intervals for older vented systems. Nagoya manufacturing clusters supply precision motor and inverter technologies for premium-tier Asian markets.
Laundry Appliances Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered price bands defined by efficiency certification and connectivity integration. The structure consolidates around scale-driven manufacturers with extensive service infrastructure and premium engineering specialists with heat-pump expertise. Three archetypes dominate: ecosystem integrators bundling laundry into smart-home platforms, efficiency specialists commanding refrigerant and compressor competencies, and volume manufacturers capturing replacement demand through dealer networks. Competitive moves center on M&A for connectivity assets and vertical integration into compressor supply chains.
Within the ecosystem integrator tier, Samsung and LG exemplify positioning through connected-home platforms that automate cycle timing and utility demand-response. Miele occupies a position among European engineering specialists leveraging heat-pump competencies for premium-tier differentiation. Whirlpool anchors the North American replacement channel through service infrastructure density.
| Leading Market Players |
|---|
| GE |
| Miele |
| LG |
| Maytag |
| Speed Queen |
| Whirlpool |
| Bosch |
| Electrolux |
| Samsung |
| Others |
Value Chain & Pricing Dynamics
North Rhine-Westphalia's compressor manufacturing clusters anchor European heat-pump dryer supply, translating engineering scarcity into pricing power for premium-tier manufacturers while volume players face margin compression from steel and copper volatility.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate component sourcing agreements between drum assembly suppliers and finished-goods manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates heat-pump certified systems from inverter-motor configurations and entry-level top-load units. Pricing pressure stems from EU F-Gas Regulation compliance costs accelerating R&D spending on alternative refrigerant architectures. Property managers procuring multi-housing fleets exhibit highest price sensitivity, while hospitality operators prioritize service-contract bundled offerings over unit economics.
Supply Chain Analysis
Export-control regimes limiting refrigerant technology transfers constrain compressor supply diversification beyond established European and East Asian sources. Manufacturing concentration centers on China, Germany, and South Korea for precision motor and inverter component production. Raw material dependencies span electrical steel for stator laminations, copper for motor windings, and specialized polymers for drum seals. Single-source vulnerability concentrates in heat-pump refrigeration loop components where qualified supplier pools remain narrow. Distribution runs through dealer networks in North America and appliance retail chains in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as heat-pump technology maturation pulls replacement demand forward ahead of regulatory obsolescence deadlines for conventional vented systems.
For Market Incumbents: Harden service infrastructure density against emerging connected-appliance specialists threatening dealer-channel control. Prioritize backward integration into compressor supply chains to secure refrigerant-qualified component flows under tightening EU F-Gas quotas. Defensive patent positioning around closed-loop drying architectures limits entrant replication speed.
For New Entrants and Emerging Players: India's sub-15 percent household penetration offers white-space capture for compact front-load configurations tailored to water-scarce semi-urban markets. Tier-one Chinese cities present secondary entry points through connected-home ecosystem partnerships bypassing established brand loyalty. Direct-to-consumer detergent subscription models enable recurring revenue attachment without retail slotting investments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected-appliance ecosystem operators with automated replenishment and demand-response utility contracts. Long-term viability favors targets with captive heat-pump engineering competencies and ENERGY STAR certification pipelines. Monitor EPA efficiency threshold announcements as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Accelerates refrigerant-compliant product portfolios for EU Ecodesign Directive markets. |
| Connected-Home Platform Integration | Captures utility demand-response revenue streams through automated cycle timing. |
| Backward Integration into Compressors | Secures supply continuity under EU F-Gas Regulation quota constraints. |
| Direct-to-Consumer Subscription Launch | Displaces retail detergent replenishment with telemetry-driven automated reordering. |
| Commercial Service-Contract Bundling | Locks hospitality procurement decisions around multi-year equipment and maintenance packages. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with appliance manufacturing executives, compressor supplier technical directors, multi-housing property managers, and commercial laundry operators; alongside secondary validation through U.S. Department of Energy efficiency filings, EPA ENERGY STAR certification databases, EU Ecodesign Directive compliance registers, and customs trade records for steel and copper component flows. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology tier, end-user category, and capacity segmentation.
Forecast inputs incorporated replacement cycle dynamics under tightening efficiency mandates, urbanization-driven compact system adoption patterns, and heat-pump technology cost curves. Segmentation dimensions modeled include product configuration, connectivity integration level, end-user utilization intensity, and regional regulatory cluster. CAGRs derived from installed base turnover rates and penetration expansion trajectories rather than extrapolated trend lines. Refrigerant transition timelines and utility demand-response program rollouts shaped regional growth differentials.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or acquisition moves by ecosystem integrators would shift competitive dynamics and pricing trajectories. Material shifts in EPA efficiency threshold timing or EU F-Gas Regulation enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Water Heater Market
Appliances
UAE Dishwasher Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Clothing Iron Market
Appliances
Sanitary Towel Machine Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Automatic Dishwasher Market
Appliances
Smart Massage Appliances Market
Appliances
Conveyor Dishwasher Market
Appliances
Bhutan and Nepal White Goods Market
Appliances
Garments Steamer Market
Appliances
Under Counter Dishwasher Market
Appliances
Portable Dishwasher Market
Appliances
Dishwasher Market
Appliances
Industrial Gas Stove Market
Appliances
Global Electric Water Heaters Market