
 Portable Dehumidifier Market | 2026-2036
Portable Dehumidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Dehumidifier Market Analytics
Demand among residential property managers and restoration contractors is consolidating toward multi-unit procurement programs. Honeywell leverages its distribution network to supply large facility operators with standardized fleet deployments. Frigidaire anchors the mass retail channel through big-box partnerships and private-label manufacturing scale. Danby competes in the compact segment with specialized units designed for recreational vehicles and marine applications.
A portable dehumidifier extracts moisture from ambient air using either compressor-driven refrigeration cycles or desiccant rotor absorption, typically achieving extraction rates from 10 to 70 pints per day depending on capacity class and operating conditions. The device protects building materials, electronics inventory, and occupant health by maintaining relative humidity below 60 percent in enclosed spaces. Refrigerant technology dominates the residential application segment due to superior energy efficiency at moderate temperatures, while desiccant systems command premium positioning in cold-climate industrial settings where coil frosting degrades compressor performance. Compact and mini product types are capturing margin pools from aging urban housing stock with limited storage space.
The US Department of Energy sets minimum energy factor requirements under federal appliance standards, while the EPA administers ENERGY STAR certification thresholds that shape consumer purchasing decisions and retailer assortment policies. California's Title 20 appliance regulations impose stricter standby power limits than federal baselines, effectively creating a dual-compliance landscape for national manufacturers. Stakeholders must monitor evolving refrigerant phase-down schedules under the American Innovation and Manufacturing Act, as transition timelines toward low-global-warming-potential alternatives will reshape compressor supply chains and product redesign cycles.
Market Dynamics
Refrigerant phase-down mandates under the American Innovation and Manufacturing Act are forcing compressor redesigns and supply chain reconfigurations across the portable dehumidifier industry. Manufacturers must retool production lines while maintaining energy efficiency compliance.
Growth Catalysts
- EPA ENERGY STAR thresholds:Stricter certification requirements are pulling consumer demand toward higher-efficiency refrigerant-based systems and expanding retail assortment of qualified models.
- Basement moisture control:Residential homeowners in flood-prone southeastern US states are deploying compact units as standard humidity management infrastructure.
- Desiccant rotor absorption:Cold-climate industrial facilities are adopting this technology where coil frosting degrades compressor performance, opening premium positioning opportunities.
Market Restraints
- Refrigerant input cost volatility:Transition timelines toward low-global-warming-potential alternatives are compressing margins and complicating inventory planning for compressor suppliers.
- Supply concentration risk:Compressor manufacturing clusters in East Asia create vulnerability to logistics disruptions and trade policy friction.
- Technical limitation:Desiccant systems carry higher energy consumption per pint extracted, constraining adoption in residential segments sensitive to operating cost.
Strategic Opportunities
- Recreational vehicle applications:Specialized compact units designed for mobile environments represent underpenetrated demand among marine and RV owners.
- California Title 20 regulations:Stricter standby power limits than federal baselines create a dual-compliance landscape favoring manufacturers with advanced power management capabilities.
- Restoration contractor procurement:Multi-unit fleet deployment programs are consolidating demand among property managers and disaster recovery services.
Industry Challenges
- Thermodynamics engineering talent:Scarcity of specialists in refrigerant system design and desiccant rotor optimization is elongating product development cycles.
- Certification timeline compression:Simultaneous DOE efficiency standards and EPA refrigerant phase-down schedules are forcing parallel compliance pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Dehumidifier Market |
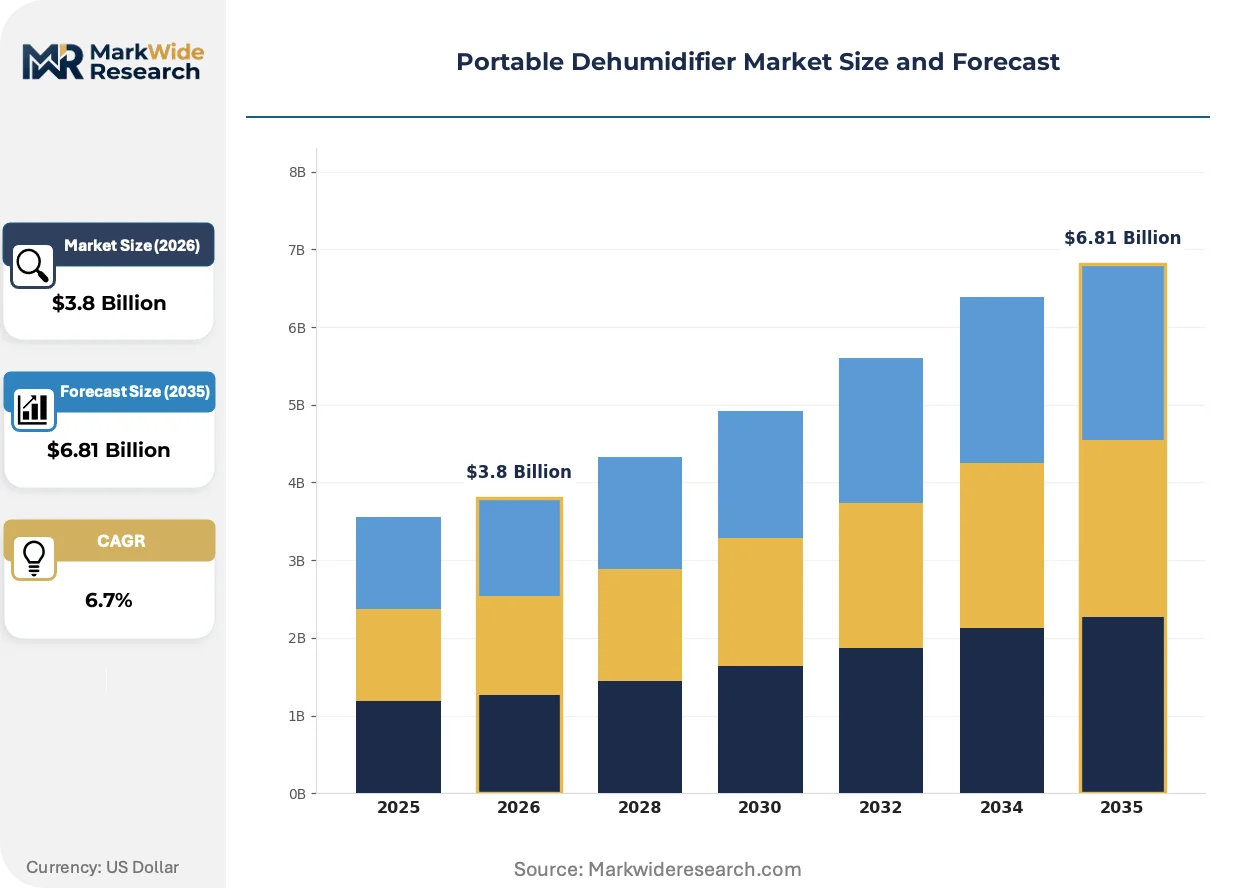
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Mini, Standard, High Capacity Technology: Desiccant, Refrigerant, Thermoelectric, Hybrid Application: Residential, Commercial, Industrial, Automotive End User: Homeowners, Businesses, Contractors, Facility Managers |
| Companies Covered | Whynter, Frigidaire, Aprilaire, Keystone, Danby, Honeywell, Ivation, Friedrich, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Dehumidifier Market Evolving Landscape
Smart humidity sensing and connected control systems are rewriting how portable dehumidifiers interact with building management infrastructure. These advances are compressing the gap between consumer appliances and integrated environmental systems.
Variable-speed compressor technology is rewriting energy consumption profiles across the residential segment. Property managers in multifamily housing are specifying these units for common-area moisture control. The technology is compressing operating cost differentials between entry-level and mid-tier product classes.
The EPA's refrigerant management regulations under Section 608 are tightening handling and disposal requirements for hydrofluorocarbon-based systems. Service contractors must now maintain specialized recovery equipment and technician certifications. The industrial cold-storage segment is accelerating desiccant system evaluation to sidestep compliance complexity.
Facility operators are unbundling after-sales service from equipment procurement, contracting directly with regional HVAC service networks rather than manufacturer-authorized dealers. Big-box retailers are responding with private-label units designed for third-party serviceability. This pattern is most visible in the southeastern United States where replacement cycles align with hurricane season recovery timelines.
Portable Dehumidifier Market Segmentation
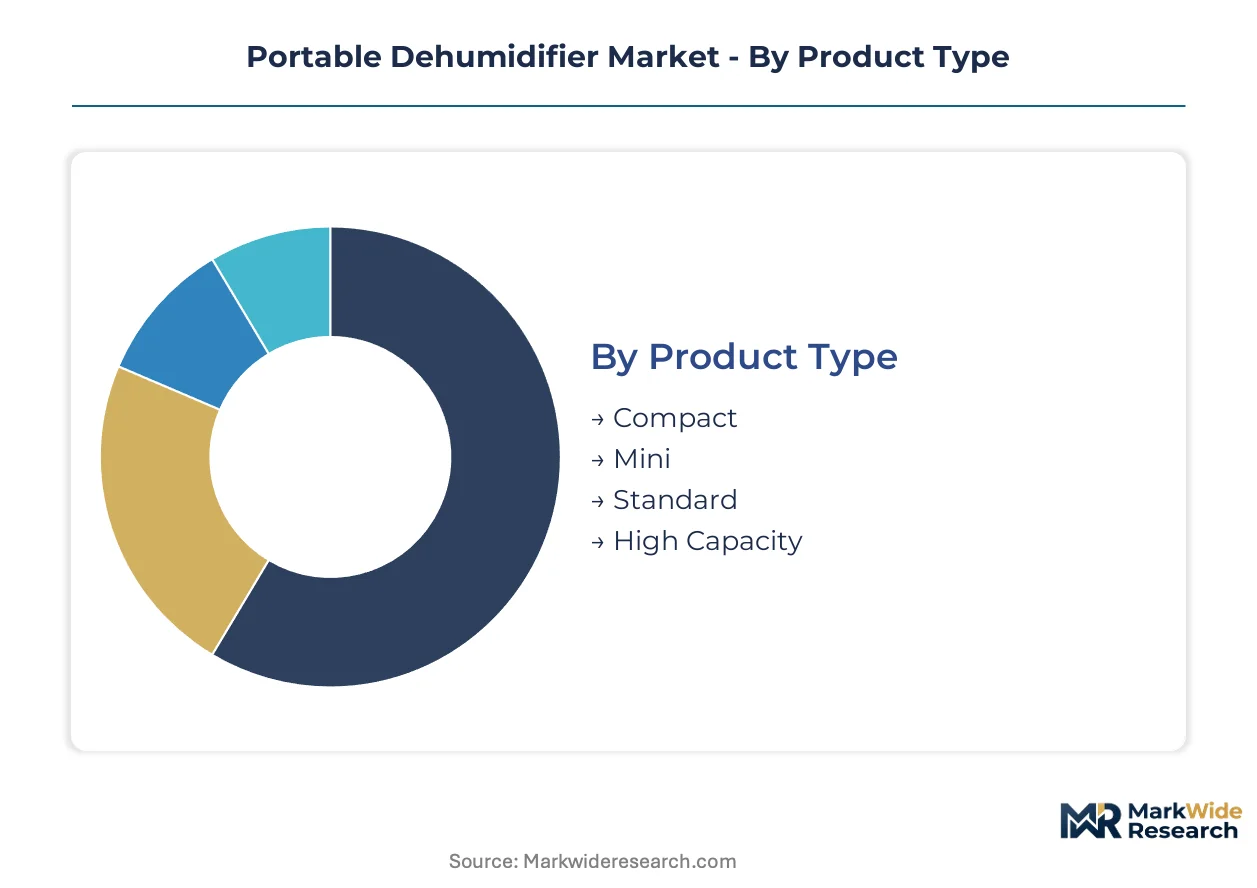
Portable dehumidifier procurement patterns diverge sharply between standalone residential purchases and integrated building management deployments. Understanding these integration depths enables manufacturers to align product specifications with channel requirements and service expectations.
Product Type:
Standalone units dominate residential basements and temporary moisture events, while embedded compact designs integrate into recreational vehicles and marine vessels requiring permanent installation.
- Compact:Units under 20 pints daily extraction deploy in recreational vehicles and marine cabins where space constraints and vibration tolerance override raw capacity. RV owners in hurricane-prone southeastern states specify these for seasonal humidity control during storage cycles.
- Mini:Ultra-portable designs below 10 pints target closet spaces, gun safes, and small bathrooms in aging urban housing stock with limited storage. These command premium positioning through whisper-quiet operation below 40 decibels.
- Standard:Mid-range 30-50 pint units serve as the workhorse for residential basement moisture management across flood-prone regions.
- High Capacity:70+ pint extraction rates address commercial restoration projects and industrial facility maintenance requirements.
Standard units lead volumes today; compact designs are gaining share fastest.
Technology:
Cost tier stratification separates premium desiccant positioning from mass-market refrigerant dominance, with thermoelectric and hybrid options occupying niche efficiency-conscious segments.
- Desiccant:Silica gel or zeolite rotor systems absorb moisture without compressor cycling, enabling effective operation below 65°F where refrigerant coils frost. Cold-storage facilities and unheated warehouses specify these despite 30-50% higher energy consumption per pint extracted.
- Refrigerant:Compressor-driven vapor compression cycles achieve superior energy factors at moderate temperatures, satisfying EPA ENERGY STAR thresholds that shape big-box retailer assortment policies. The technology anchors residential segment economics through established supply chains and technician familiarity.
- Thermoelectric:Peltier-effect cooling eliminates moving parts for silent operation in bedrooms and home offices where noise tolerance is minimal.
- Hybrid:Dual-mode systems switch between refrigerant and desiccant operation based on ambient temperature, optimizing efficiency across seasonal variation.
Refrigerant systems anchor current revenue; hybrid configurations show steepest expansion trajectory.
Application:
Volume concentration clusters in residential replacement cycles, while margin expansion concentrates in commercial and industrial segments with specialized performance requirements.
- Residential:Basement moisture control and post-flood recovery drive replacement purchases concentrated in southeastern states with high humidity baselines and hurricane seasonality. Property managers specify standardized fleet deployments across multifamily portfolios.
- Commercial:Retail inventory protection, hotel humidity management, and office building moisture control create recurring procurement from facility operators unbundling service from equipment purchase.
- Industrial:Manufacturing process control, pharmaceutical storage, and electronics assembly environments demand precision humidity maintenance with continuous-duty ratings.
- Automotive:Classic car storage and commercial fleet maintenance facilities deploy specialized units to prevent corrosion and electrical system degradation.
Residential applications dominate unit volumes; industrial specifications deliver highest margin per unit.
End User:
Customer type determines procurement channel and service expectations, from big-box retail self-service to contractor fleet programs with direct manufacturer relationships.
- Homeowners:Individual purchasers prioritize ENERGY STAR certification visibility, noise ratings, and caster mobility for seasonal repositioning. These buyers concentrate in southeastern states with established humidity awareness.
- Businesses:Commercial entities including retail chains and hospitality operators specify through HVAC service contractors rather than direct purchase, favoring units designed for third-party maintainability.
- Contractors:Restoration and disaster recovery services procure multi-unit fleets through standardized programs, demanding ruggedized construction and rapid deployment logistics.
- Facility Managers:Institutional operators in healthcare, education, and government sectors integrate dehumidification into building automation systems, requiring communication protocols and centralized monitoring compatibility.
Homeowner purchases generate highest unit volumes; contractor fleet programs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for portable dehumidifiers outpaces Canadian procurement by roughly four-to-one in unit volumes, though both markets face tightening federal efficiency mandates. Southeast Asian manufacturing clusters now supply compressor components to both North American and European assembly plants.
United States
Basement moisture control in flood-prone southeastern states drives replacement cycles synchronized with hurricane season recovery. EPA ENERGY STAR certification thresholds shape big-box retailer assortment policies nationwide. Dallas-Fort Worth logistics hubs coordinate distribution to restoration contractor fleets across Texas, Louisiana, and Florida.
Canada
Cold-climate industrial facilities in Ontario and Quebec specify desiccant systems where refrigerant coil frosting degrades performance. Health Canada's appliance efficiency regulations align with federal standards while maintaining distinct standby power testing protocols. Toronto-area HVAC service networks unbundle after-sales support from equipment procurement for commercial clients.
Germany
Industrial humidity control in pharmaceutical storage and electronics assembly sustains precision-specification demand. EU F-Gas Regulation phase-down schedules accelerate refrigerant transition timelines for compressor redesign cycles. Bavaria-based manufacturing clusters specialize in desiccant rotor optimization for cold-storage applications.
China
Domestic production of compressor components concentrates in Yangtze River Delta industrial zones serving export assembly plants. MIIT appliance efficiency standards and GB national standards create dual compliance pathways for manufacturers targeting both domestic and overseas markets. Shenzhen electronics assemblers integrate compact dehumidification modules into recreational vehicle and marine OEM supply chains.
Japan
Compact unit demand from aging urban housing stock with limited storage space sustains mini-segment innovation. METI energy conservation standards and JIS certification requirements maintain stringent efficiency benchmarks. Osaka-Kobe industrial corridors manufacture precision desiccant rotors for cold-climate industrial specifications.
Portable Dehumidifier Market Competitive Landscape
United States-based producers anchor the mass retail tier; German and Japanese specialists hold premium positioning in industrial cold-climate applications. The vendor base separates into three functional tiers: diversified appliance conglomerates with national distribution networks, regional fabricators serving contractor fleet programs, and compact-specialist manufacturers targeting recreational vehicle and marine OEM channels. Two dominant competitive moves define current positioning: strategic partnerships between compressor suppliers and finished goods assemblers to secure refrigerant transition timelines, and geographic expansion of service networks to capture unbundled after-sales revenue from facility operators.
Among North American diversified manufacturers, Honeywell International Inc., Frigidaire, and Danby Products Limited exemplify distinct strategic archetypes. Honeywell represents the integrated building systems approach, leveraging distribution infrastructure to supply standardized fleet deployments for multi-site facility operators. Frigidaire occupies the mass retail anchor position through big-box channel density and private-label manufacturing scale. Danby sits within the compact-specialist tier, with product configurations designed for recreational vehicle and marine cabin installations where space constraints and vibration tolerance override raw extraction capacity.
| Leading Market Players |
|---|
| Whynter |
| Frigidaire |
| Aprilaire |
| Keystone |
| Danby |
| Honeywell |
| Ivation |
| Friedrich |
| GE Appliances |
| Others |
Value Network & Pricing Analysis
Multi-unit procurement programs from restoration contractors and property managers are compressing order quantities into standardized fleet deployments, forcing manufacturers to absorb volume discounts while retooling for refrigerant compliance. This demand consolidation reshapes margin structures across compressor suppliers and finished goods assemblers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for compressor components. Three-tier pricing structure across premium ENERGY STAR-certified, standard residential, and economy private-label tiers separates manufacturers by certification investment and brand positioning. Price differentiation hinges on EPA ENERGY STAR compliance and standby power performance under California Title 20. Pricing pressure stems from refrigerant transition costs under the American Innovation and Manufacturing Act. Residential homeowners in southeastern states show highest price sensitivity; industrial cold-storage operators demonstrate lowest sensitivity due to frost-avoidance requirements.
Supply Chain Analysis
Thermodynamics engineering talent shortages in East Asian manufacturing zones are elongating compressor redesign cycles. Component production concentrates in China, South Korea, and Japan. Finished assembly draws from aluminum heat exchangers, copper refrigerant lines, and desiccant rotor materials. Single-source vulnerability pervades compressor manufacturing clusters subject to logistics disruptions. Distribution runs through Dallas-Fort Worth logistics hubs coordinating contractor fleet deployment across Texas, Louisiana, and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable dehumidifier market compounds steadily as climate-driven humidity management becomes standard infrastructure across flood-prone housing stock.
For Market Incumbents: Hedge refrigerant transition exposure by securing dual-source compressor supply agreements before American Innovation and Manufacturing Act phase-down deadlines compress availability. Deepen backward integration into desiccant rotor production to capture premium positioning in cold-climate industrial segments where coil frosting threatens refrigerant performance. Fortify ENERGY STAR certification pipelines to maintain big-box retail assortment priority. For New Entrants and Emerging Players: Enter via recreational vehicle and marine cabin applications where Danby's specialized compact designs have validated demand but supply gaps persist among OEM channels. Target underpenetrated restoration contractor fleet programs in hurricane-corridor states with ruggedized construction and rapid-deployment logistics. Pursue direct relationships with regional HVAC service networks rather than manufacturer-authorized dealer structures. For Investors and Strategic Acquirers: Asymmetric upside sits with compact-specialist manufacturers possessing recreational vehicle OEM relationships and desiccant rotor optimization capabilities. Long-term viability centers on regulatory compliance agility across refrigerant phase-down schedules and efficiency standard evolution. Monitor EPA refrigerant management regulations under Section 608 for handling and disposal requirement intensification signals.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Compliance | American Innovation and Manufacturing Act timelines force parallel compressor redesign and supply chain reconfiguration investments. |
| Desiccant Rotor Capacity Expansion | Cold-storage facilities accelerate adoption where EPA Section 608 complexity disadvantages hydrofluorocarbon-based refrigerant systems. |
| Smart Humidity Sensing Integration | Connected control systems compress the gap between consumer appliances and building automation infrastructure for facility managers. |
| Service Network Unbundling | Third-party HVAC contractor relationships replace manufacturer-authorized dealer structures in southeastern replacement cycles. |
| Recreational Vehicle OEM Partnership | Specialized compact units for marine and RV cabins access validated demand with limited incumbent penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged compressor manufacturing executives, big-box retail category buyers, restoration contractor procurement managers, and HVAC service network operators. Secondary validation incorporated EPA ENERGY STAR certification databases, DOE appliance efficiency standards filings, customs trade records for compressor component flows, and SEC 10-K disclosures from diversified appliance manufacturers. Bottom-up unit shipment modeling and top-down market value triangulation anchored volume estimates.
Historical reference periods established baseline growth trajectories against which projection assumptions were stress-tested across the analysis window. Segmentation dimensions modeled include product type, technology configuration, application depth, and end-user procurement channel. CAGRs were derived from fitted trend analysis adjusted for regulatory inflection points. Refrigerant phase-down schedules under the American Innovation and Manufacturing Act and ENERGY STAR threshold evolution served as primary forecast inputs.
The model holds under steady regulatory implementation timelines; deviation in refrigerant transition pace or efficiency standard acceleration would shift manufacturer investment priorities and margin structures. Practitioners should monitor EPA Section 608 enforcement intensity and California Title 20 standby power test protocol amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Russia Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
UK Household Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Canada Laundry Appliances Market