
 Oman Home Appliances Market | 2026-2036
Oman Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Home Appliances Market Analytics
Buyer concentration across Oman's residential segment is rebalancing as expatriate professionals in Muscat and Salalah drive fragmented demand for premium kitchen appliances. Samsung Electronics leverages its smart home ecosystem to anchor digital connectivity preferences among urban households. LG Electronics competes through specialized inverter compressor technology in refrigeration lines suited to Gulf climate conditions. Haier sustains cost positioning in washing machines through regional manufacturing scale and localized distribution partnerships.
Home appliances encompass electrically powered mechanical devices designed for domestic tasks, typically operating at 220-240V/50Hz with insulated enclosures rated for ambient temperatures exceeding 45 degrees Celsius in Gulf applications; their primary commercial purpose centers on reducing household labor time and preserving food safety in high-temperature environments. Refrigerators dominate value pools as the most replacement-intensive category across Omani households, while Energy Star and A+ Rating segments capture margin premiums from efficiency-conscious buyers in new villa developments. Online Retail channels are expanding fastest among younger demographics in metropolitan areas, though Specialty Stores retain decisive influence through in-person demonstration and installation services.
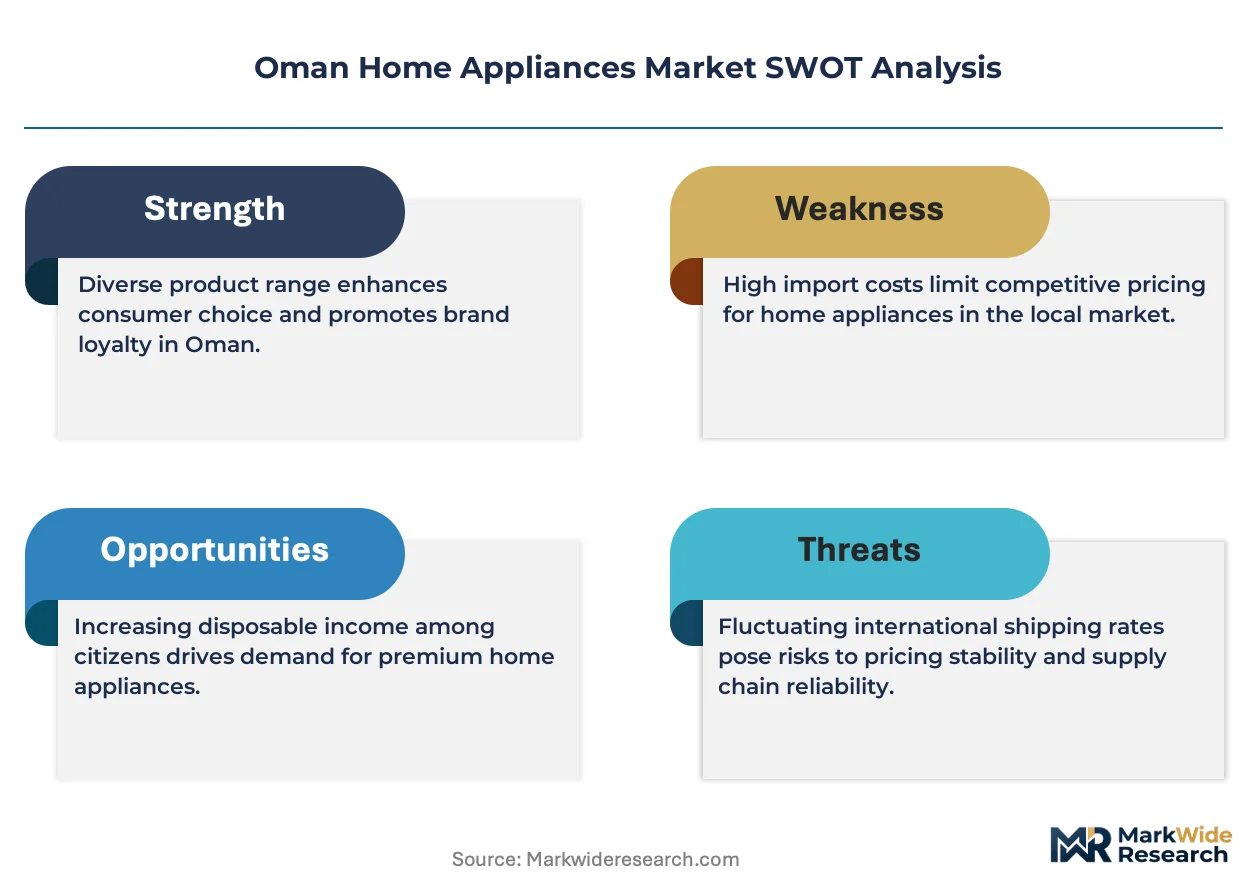
Oman's National Energy Strategy and the Gulf Standards Organization (GSO) efficiency labeling requirements shape product eligibility and import compliance for cooling appliances entering Port Sultan Qaboos. The country's Ministry of Commerce, Industry and Investment Promotion enforces conformity assessment procedures that filter substandard electronics from retail circulation. Stakeholders must monitor evolving mandatory efficiency tiers and local content incentives as Oman deepens industrial diversification beyond hydrocarbon dependence.
Market Dynamics
Oman's National Energy Strategy is compressing replacement cycles for cooling appliances as efficiency mandates disqualify older import stock from Port Sultan Qaboos entry. Villa developers in Muscat now specify inverter compressor systems to meet GSO labeling thresholds, redirecting procurement toward certified suppliers.
Growth Catalysts
- Al Batinah hospitality construction:New hotel developments along the coast require commercial-grade refrigeration and laundry equipment, creating concentrated demand for high-capacity appliances with desert-climate ratings.
- GSO efficiency labeling expansion:Mandatory tier upgrades for cooling appliances are filtering substandard imports and elevating certified product penetration in retail channels.
- Smart connectivity protocols:Wi-Fi enabled kitchen systems are gaining traction among expatriate professionals in Muscat and Salalah, linking appliance purchases to home automation ecosystems.
Market Restraints
- Copper and refrigerant input volatility:Compressor manufacturing costs fluctuate with commodity markets, compressing margins for mid-tier refrigeration suppliers serving price-sensitive segments.
- Port Sultan Qaboos concentration:Single-entry point dependency creates customs clearance bottlenecks during peak import seasons, delaying inventory replenishment for retailers.
- Technical service scarcity:Qualified inverter compressor technicians remain concentrated in Muscat, leaving interior governorates underserved for complex repairs.
Strategic Opportunities
- Dhofar Governorate underpenetration:Salalah's secondary urban status relative to Muscat leaves room for specialized distribution partnerships targeting coastal humidity-rated appliances.
- Online retail channel expansion:Younger demographics in metropolitan areas are migrating toward e-commerce platforms for appliance research and purchase, bypassing traditional specialty store dependence.
- Solar-compatible appliance development:Oman's renewable energy diversification creates white space for DC-powered refrigeration systems aligned with residential solar installations.
Industry Challenges
- Conformity assessment timelines:Ministry of Commerce certification procedures for new product lines extend market entry lead times, disadvantaging suppliers with rapid refresh cycles.
- Installation skill fragmentation:Smart-connected system deployment requires cross-trained technicians capable of both appliance setup and home network integration, a capability gap in the current workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Home Appliances Market |
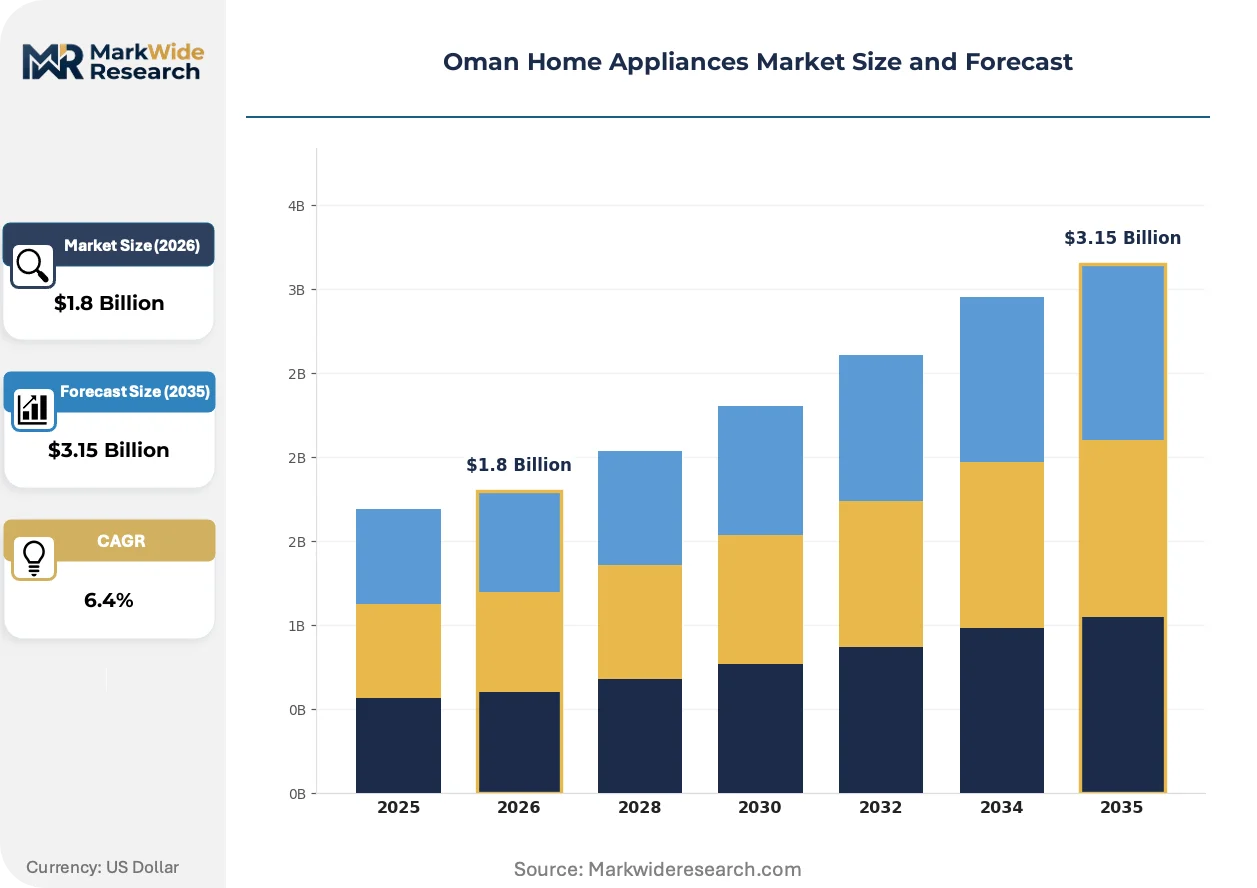
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers Energy Efficiency: Energy Star, A+ Rating, A++ Rating, Conventional Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales End User: Residential, Commercial, Hospitality, Institutions |
| Companies Covered | Whirlpool Corporation, Panasonic Corporation, Samsung Electronics, Electrolux, Hitachi, LG Electronics, Bosch, Haier, Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Home Appliances Market Evolving Landscape
Connectivity architectures are rewiring how Omani households interact with domestic equipment. Three developments are compressing traditional purchase and usage patterns.
Inverter-driven compressor technology is decentralizing cooling system design across residential applications. Variable-speed motors adjust output to ambient thermal loads rather than cycling on-off, reducing energy draw during peak summer demand. Urban villa buyers in Muscat are specifying these systems at accelerating rates, fragmenting the market away from conventional fixed-speed units toward modulated performance tiers.
Gulf Standards Organization efficiency mandates are tightening eligibility criteria for refrigeration imports through Port Sultan Qaboos. The labeling scheme now requires documented power consumption testing at 45-degree Celsius ambient conditions, disqualifying products rated only for temperate climates. Retailers are responding by consolidating supplier relationships around manufacturers with established Gulf certification portfolios.
Specialty store influence is eroding as demonstration and installation services unbundle from purchase transactions. Younger buyers in metropolitan areas research specifications online before engaging contractors separately for delivery and setup. This pattern is most visible in Muscat, where digital-native professionals prioritize price transparency over in-person sales consultation for standard appliance categories.
Oman Home Appliances Market Segmentation
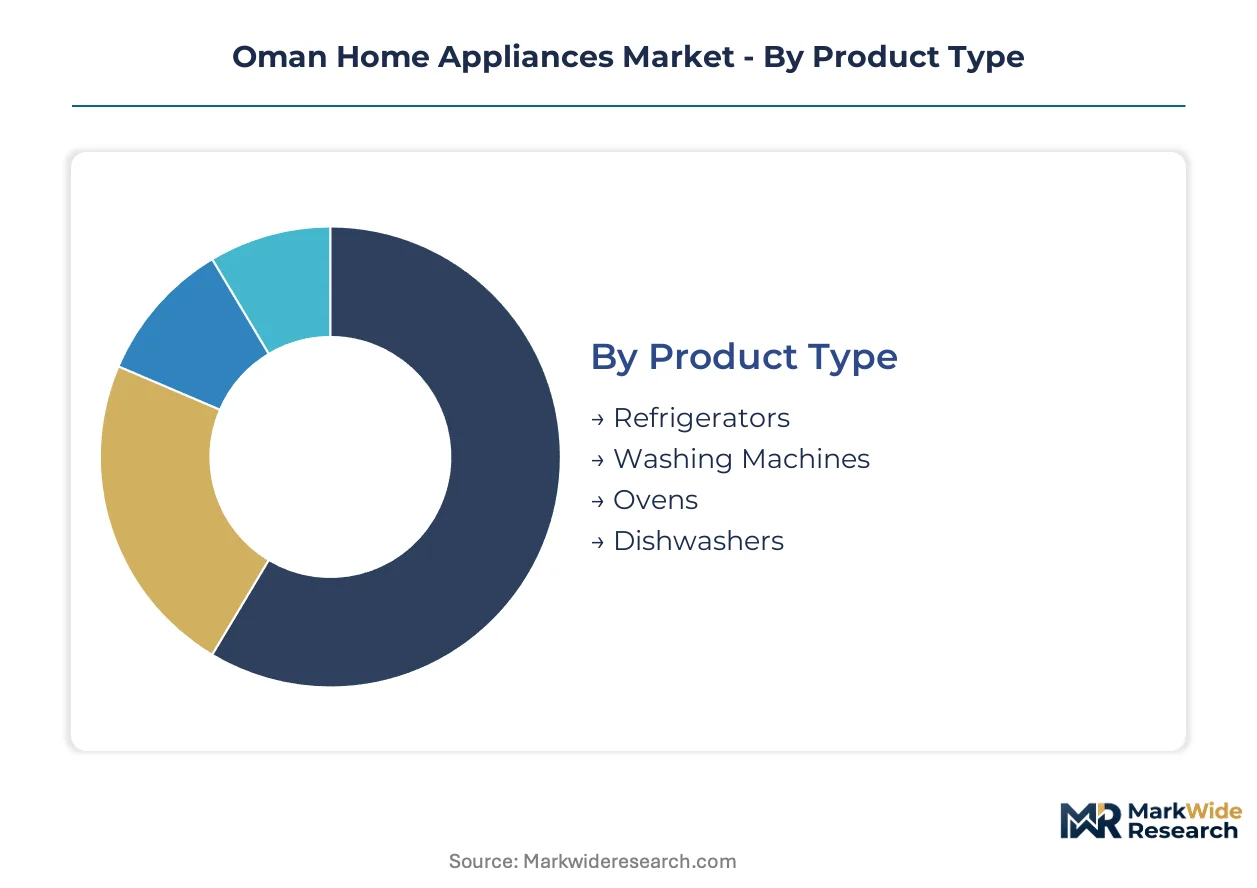
Segmentation in Oman's home appliances market reveals how efficiency mandates, distribution infrastructure, and end-user requirements fragment procurement patterns across the Sultanate. Buyers in Muscat and Salalah prioritize different performance tiers than hospitality developers along Al Batinah, while GSO certification filters reshape channel strategies.
Product Type:
Replacement urgency and climate adaptation drive purchasing decisions, with thermal performance under Gulf conditions separating premium from commodity selections.
- Refrigerators:Inverter compressor systems with variable-speed motors modulate cooling output against 45-degree Celsius ambient loads. Villa developers in Muscat specify these units to meet National Energy Strategy mandates, displacing fixed-speed imports at Port Sultan Qaboos.
- Washing Machines:Front-loading designs with humidity-resistant electronics address Salalah's coastal conditions. Regional manufacturing scale through localized distribution partnerships sustains cost positioning for mid-tier residential buyers.
- Ovens:Built-in convection systems with Gulf-rated insulation target new villa construction in metropolitan areas.
- Dishwashers:Compact countertop units dominate expatriate apartment installations where kitchen footprint constraints limit full-size integration.
Volume sits with refrigerators; growth tilts toward washing machines.
Energy Efficiency:
Margin structure follows certification tier, with GSO labeling thresholds creating discrete price-performance bands that reshape supplier eligibility.
- Energy Star:Imported units meeting international testing protocols command premiums from efficiency-conscious buyers in new Muscat developments. GSO alignment requirements at Port Sultan Qaboos restrict uncertified competitor access.
- A+ Rating:European-standard efficiency tiers attract villa owners seeking electricity cost containment during peak summer cooling loads. Procurement concentrates through specialty stores offering installation bundling.
- A++ Rating:Ultra-efficient compressors with documented 45-degree Celsius testing appeal to sustainability-focused commercial buyers.
- Conventional:Fixed-speed legacy stock persists in price-sensitive interior governorates where replacement cycles lag metropolitan adoption curves.
Revenue concentrates in Energy Star and A+ tiers; steepest expansion trajectory belongs to A++ Rating as commercial procurement standards tighten.
Distribution Channel:
Service unbundling is fragmenting traditional purchase patterns, with demonstration and installation separating from transaction completion across buyer demographics.
- Online Retail:E-commerce platforms capture younger metropolitan professionals prioritizing price transparency over in-person consultation. Research-to-purchase migration accelerates in Muscat and Salalah for standard appliance categories.
- Specialty Stores:In-person demonstration and installation bundling retains decisive influence for complex connected systems requiring network integration. Qualified technician concentration in Muscat reinforces geographic channel concentration.
- Hypermarkets:Mass retail formats serve impulse replacement demand and entry-level price segments in suburban catchment areas.
- Direct Sales:Project-based procurement for Al Batinah hospitality developments bypasses retail infrastructure through manufacturer-contractor relationships.
Transaction volume remains with specialty stores; channel share gains fastest in online retail.
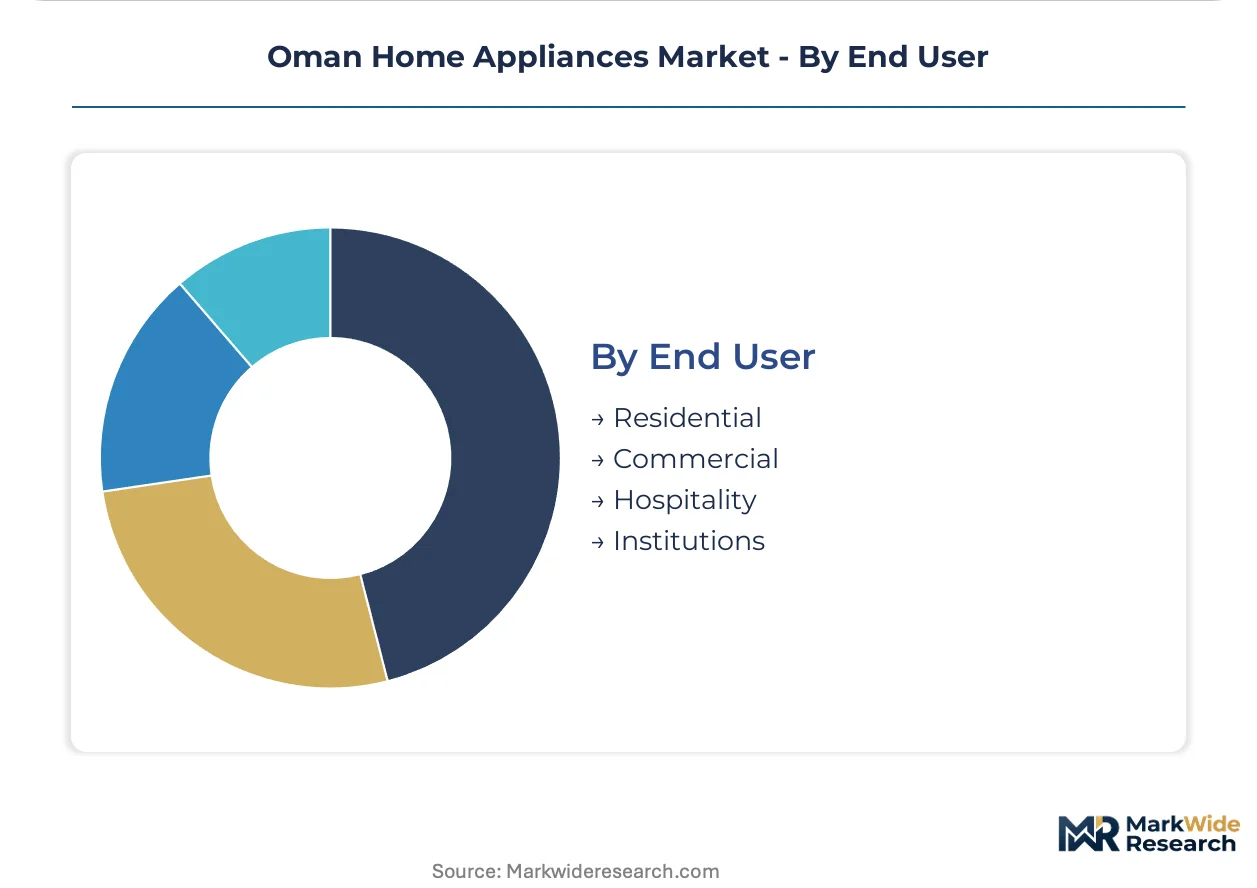
End User:
Application scale and climate rating requirements segment procurement specifications, with commercial durability standards diverging sharply from residential replacement patterns.
- Residential:Expatriate professionals in Muscat and Salalah drive fragmented demand for smart-connected kitchen systems. Wi-Fi enabled appliances link to home automation ecosystems, compressing replacement cycles for digitally integrated households.
- Commercial:High-capacity refrigeration and laundry equipment with desert-climate ratings serve Al Batinah hotel developments. Concentrated procurement volumes reward suppliers with established Gulf certification portfolios.
- Hospitality:Restaurant and food-service operators require commercial-grade durability under continuous-use thermal stress.
- Institutions:Government and educational facilities procure through centralized tender processes with extended warranty requirements.
Unit volume concentrates in residential; value expansion tilts toward commercial hospitality procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Muscat and Salalah, where expatriate professionals and villa developments drive premium appliance procurement. Interior governorates lag metropolitan adoption curves due to technical service scarcity and distribution gaps.
Muscat Governorate
New villa construction in Al Mouj and Madinat Sultan Qaboos specifies inverter compressor refrigeration systems. The Ministry of Commerce enforces GSO efficiency labeling at Port Sultan Qaboos, filtering substandard imports. Smart-connected kitchen systems from Samsung Electronics and LG Electronics dominate showroom floors in Qurum commercial district.
Dhofar Governorate
Salalah's coastal humidity drives demand for washing machines with corrosion-resistant electronics. The National Energy Strategy mandates efficiency tiers that redirect procurement toward certified suppliers. Distribution partnerships target underpenetrated residential zones beyond the city center with localized service networks.
Al Batinah South Governorate
Hotel developments along the coast generate concentrated commercial demand for high-capacity refrigeration and laundry equipment. The Ministry of Commerce conformity assessment procedures extend lead times for new product entry. Procurement flows through direct manufacturer-contractor relationships bypassing retail infrastructure.
Al Dakhiliyah Governorate
Nizwa and interior cities exhibit replacement cycles that lag Muscat by several years due to price sensitivity. GSO labeling requirements apply uniformly but enforcement intensity varies with customs capacity. Haier sustains cost positioning through regional manufacturing scale serving mid-tier residential segments.
Al Sharqiyah South Governorate
Sur and coastal towns balance residential demand with hospitality sector requirements from emerging tourism infrastructure. Technical service scarcity for inverter compressor repairs limits premium product penetration. Online retail channels expand fastest among younger demographics seeking price transparency over specialty store consultation.
Oman Home Appliances Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart connectivity integration and solar-compatible system development. The market structures around three tiers: global electronics conglomerates with Gulf certification portfolios, regional manufacturing specialists with cost-optimized distribution, and premium appliance fabricators targeting villa construction specifications. Competitive positioning depends on GSO compliance speed, installation service bundling, and inverter compressor technology access. M&A activity concentrates on distribution network consolidation; strategic partnerships link manufacturers to hospitality developers for project-based procurement.
Among Korea-based electronics conglomerates, Samsung Electronics and LG Electronics anchor the premium-tier vector through smart home ecosystem integration and specialized compressor technology. Haier, a China-based Co., Ltd., occupies the scale-driven end with regional manufacturing advantages and localized distribution partnerships serving price-sensitive interior governorates. These three exemplify how geographic origin and corporate structure map to distinct competitive archetypes in a market filtered by Port Sultan Qaboos entry requirements and National Energy Strategy compliance mandates.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Panasonic Corporation |
| Samsung Electronics |
| Electrolux |
| Hitachi |
| LG Electronics |
| Bosch |
| Haier |
| Philips |
| Others |
Value Network & Pricing Analysis
Captive compressor manufacturing in South Korea and China anchors both supply security and pricing power for premium refrigeration tiers entering Port Sultan Qaboos. This upstream control allows certified suppliers to buffer commodity volatility while extracting margins from GSO-mandated efficiency upgrades.
Pricing Analysis
Volume concentrates in mid-tier fixed-speed units while margins accrue to inverter compressor systems with documented 45-degree Celsius testing. Price differentiation separates GSO-certified imports from uncertified legacy stock blocked at Port Sultan Qaboos. Pricing pressure stems from copper and refrigerant input volatility compressing returns for non-integrated suppliers. Residential buyers in interior governorates exhibit highest price sensitivity; villa developers in Muscat prioritize efficiency ratings over unit cost.
Supply Chain Analysis
Compressor supply rests on South Korean and Chinese specialty motor manufacturers with Gulf certification portfolios. Copper winding stock and refrigerant gases constitute critical input dependencies. Single-entry vulnerability through Port Sultan Qaboos creates customs clearance bottlenecks during peak import seasons. Distribution runs through specialty store networks in Muscat for complex systems, with online platforms capturing standard appliance transactions in metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's home appliance sector sits in a technology-transition phase as inverter-driven compressor systems displace fixed-speed legacy units under National Energy Strategy mandates.
For Market Incumbents: Extend GSO certification coverage to new product lines faster than Ministry of Commerce assessment timelines to lock out rapid-refresh competitors. Deepen captive compressor supply through backward integration into South Korean motor manufacturing. Channel control through installation service bundling defends against online retail unbundling. For New Entrants and Emerging Players: E-commerce platform partnerships open underpenetrated residential zones in Salalah and interior governorates where specialty store density remains thin. Target Dhofar Governorate humidity-rated washing machine demand with localized distribution partnerships. Solar-compatible DC refrigeration development addresses renewable energy diversification white space. For Investors and Strategic Acquirers: Exit pathways concentrate in distribution network consolidation plays serving Al Batinah hospitality project pipelines. Long-term viability favors suppliers with established Gulf certification portfolios and inverter technology access. Watch GSO efficiency tier acceleration as inflection signal for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| GSO Certification Acceleration | Speeds Port Sultan Qaboos entry before efficiency mandates disqualify legacy stock. |
| Specialty Store Network Expansion | Captures installation-bundled demand for smart-connected kitchen systems in Muscat. |
| Inverter Compressor Technology Licensing | Secures variable-speed motor supply for 45-degree Celsius rated product lines. |
| Online Retail Channel Development | Targets younger metropolitan buyers prioritizing price transparency over demonstration. |
| Solar-Compatible Product Development | Aligns with Oman renewable energy diversification beyond hydrocarbon dependence. |
Research Methodology
Independent corroboration across appliance procurement managers at Al Batinah hotel developers, inverter compressor service technicians in Muscat, and Ministry of Commerce conformity assessment officers underwrites the qualitative findings. Primary interviews with specialty store operators, online retail platform category heads, and villa construction project managers combined with secondary validation from Gulf Standards Organization labeling databases, Port Sultan Qaboos customs entry records, and National Energy Strategy documentation. Bottom-up demand modeling triangulates against top-down market sizing.
Comparable-period anchoring to historical replacement cycles and efficiency mandate implementation phases structured the projection horizon. Segmentation dimensions span product type, energy efficiency tier, distribution channel, and end-user application with governorates as geographic clusters. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate GSO labeling expansion schedules and hospitality construction pipeline tracking.
The model holds under stable GSO enforcement intensity and copper price bands; deviation in refrigerant gas supply disruptions or customs capacity constraints at Port Sultan Qaboos would shift volume timing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
India Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Household Appliance Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Australia Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
Kuwait Home Appliances Market