
 United Kingdom Small Home Appliances Market | 2026-2036
United Kingdom Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Small Home Appliances Market Analytics
The UK's Ecodesign for Energy-Related Products Regulations is consolidating procurement standards across retail channels, compelling manufacturers to redesign motor and heating assemblies. Dyson leverages proprietary digital motor technology to sustain premium positioning in vacuum and air-treatment categories. Morphy Richards anchors mid-market kitchen electrics through established supermarket and online distribution. BSH Home Appliances Ltd differentiates via built-in compatibility and German engineering credentials that resonate with UK kitchen-fitters.
United Kingdom Small Home Appliances encompass portable electric devices for food preparation, beverage brewing, cleaning, and climate control, typically operating below 2,500 watts and designed for countertop or handheld domestic use. These products employ universal or brushless DC motors, thermostatic heating elements, and ABS or stainless-steel housings to deliver convenience functions in space-constrained residential settings. Coffee makers and blenders within the product type dimension lead current revenue pools, reflecting sustained café-at-home behaviour and smoothie preparation trends. The technology dimension shows smart appliances and IoT-enabled units capturing disproportionate growth attention, though energy-efficient conventional models still dominate absolute unit sales through mass-market channels.
The UK's Office for Product Safety and Standards enforces electrical equipment safety regulations that mandate CE or UKCA marking, directly shaping product testing budgets and time-to-market for importers. The Competition and Markets Authority monitors environmental claims, constraining how brands communicate sustainability attributes to consumers. Stakeholders must track evolving interoperability standards between smart appliances and domestic energy management platforms, as grid-responsive functionality becomes a decisive purchase criterion.
Market Dynamics
The UK's Ecodesign for Energy-Related Products Regulations is compressing motor wattage ceilings across vacuum, heating, and food preparation categories, forcing redesigns of universal motor architectures and thermostatic control systems.
Growth Catalysts
- Urban rental density:London and Manchester rental households favor compact, multi-functional kitchen devices that minimize countertop footprint and storage requirements.
- UKCA marking harmonization:The Office for Product Safety and Standards streamlines compliance pathways for domestic and imported electrical equipment, reducing retesting burdens for certified manufacturers.
- Smart home interoperability:Grid-responsive functionality is integrating with domestic energy management platforms, creating pull-through demand for connected small appliances.
Market Restraints
- Copper and rare-earth magnet costs:Brushless DC motor production faces input price volatility from concentrated Chinese rare-earth processing and Chilean copper supply.
- Testing budget inflation:UKCA and CE dual certification requirements expand product validation timelines and laboratory expenditure for importers serving UK channels.
- Manual appliance substitution:Premium-priced electric devices compete with lower-cost manual alternatives in cost-conscious household segments.
Strategic Opportunities
- Scotland and Northern England penetration:Metropolitan corridors outside Greater London show underdeveloped retail distribution for premium small appliance brands.
- Refurbishment channel development:Online platforms and supermarket partnerships for certified pre-owned units address circular economy preferences and price-sensitive demand.
- IoT-enabled predictive maintenance:Sensor-integrated kettles, coffee makers, and vacuum units enable subscription-based filter and component replacement revenue streams.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for smart appliance connectivity outpaces UK graduate pipeline capacity, inflating recruitment costs.
- Legacy platform integration friction:Grid-responsive appliances face interoperability testing delays against fragmented domestic energy management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Small Home Appliances Market |
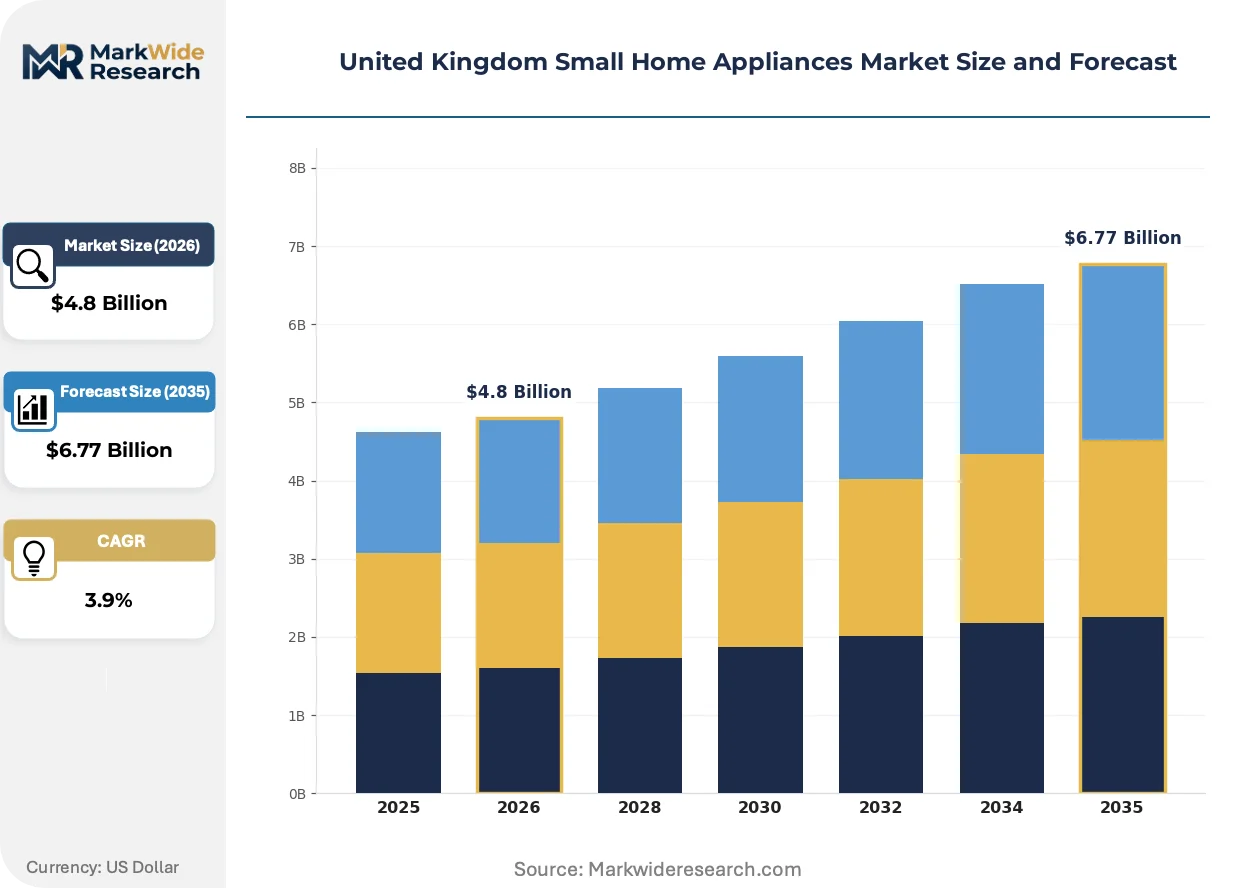
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixers, Toasters, Coffee Makers, Blenders Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Conventional End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Dyson, Morphy Richards, BSH Home Appliances Ltd, De’Longhi, KitchenAid, Philips, Black & Decker, Electrolux, Russell Hobbs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Small Home Appliances Market Evolving Landscape
Digital motor control, regulatory energy efficiency mandates, and rental-lifestyle product formats are restructuring competitive positioning across UK small appliance categories.
Brushless DC motor technology is integrating digital control algorithms that optimize power draw against load conditions. Premium vacuum and air-treatment manufacturers adopt these systems to meet Ecodesign wattage ceilings while sustaining suction performance. This architecture is compressing the cost-performance gap between conventional universal motors and electronically commutated alternatives.
The UK's Ecodesign for Energy-Related Products Regulations mandates minimum efficiency indices for standby and active modes. Manufacturers redesign heating element insulation and motor winding configurations to comply. Vacuum and climate-control categories face the steepest redesign requirements, with testing houses reporting extended validation queues for 2024-2025 product cycles.
Rental-optimized product formats emphasize collapsible storage dimensions and multi-function consolidation. Urban households in London and Manchester prioritize appliances that serve multiple preparation functions within single countertop footprints. Retail buyers at major supermarket chains now specify dimensional constraints and cord-storage features as standard procurement criteria.
United Kingdom Small Home Appliances Market Segmentation
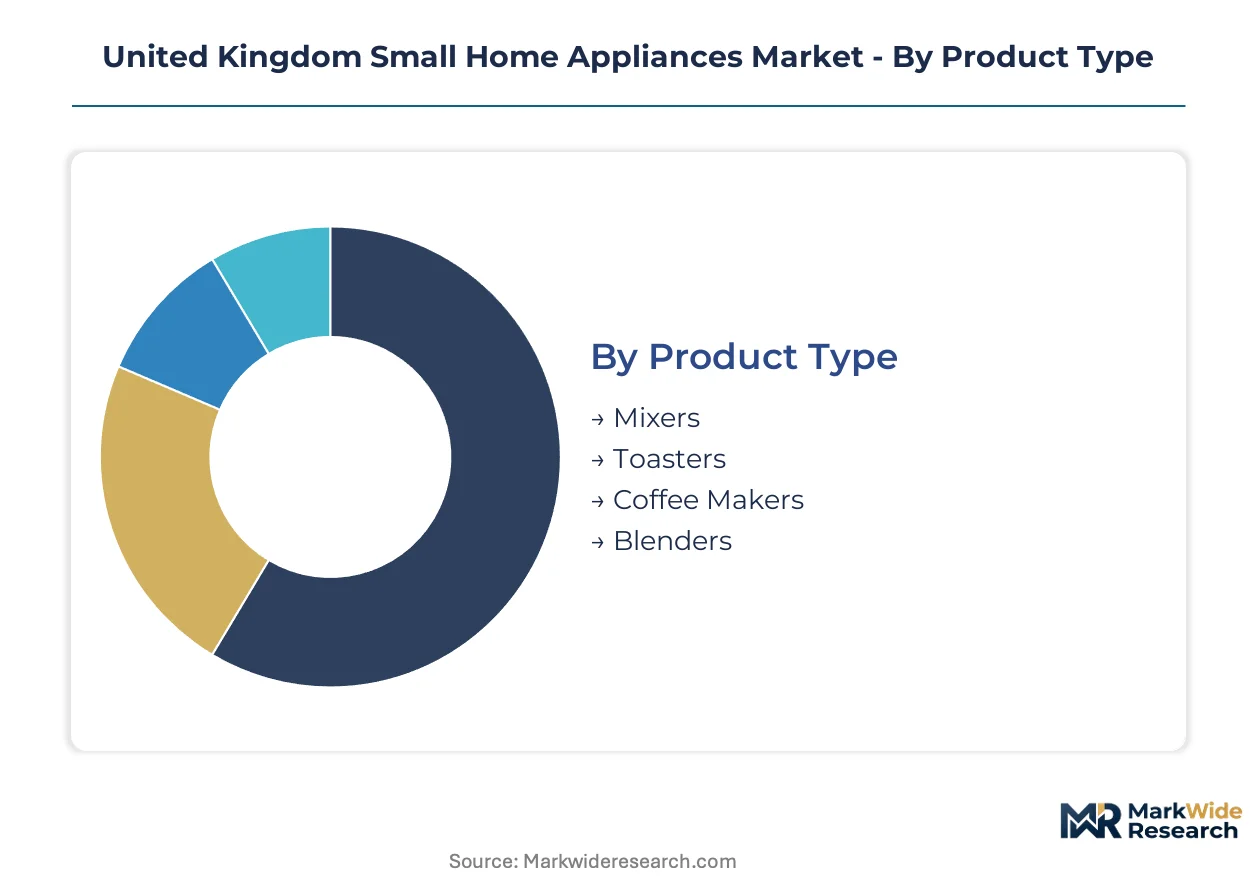
United Kingdom Small Home Appliances segmentation reveals how rental-lifestyle constraints, Ecodesign compliance costs, and channel consolidation reshape procurement patterns across distinct buyer profiles. Each dimension carries specific implications for motor specification, connectivity architecture, and retail placement strategy.
Product Type:
Countertop footprint and preparation versatility drive purchase decisions in space-constrained urban kitchens.
- Coffee Makers:Espresso and pod-based systems dominate premium placement in Greater London retail. Café-at-home behaviour sustains demand for milk-frothing integration and programmable brewing in Manchester and Birmingham rental corridors.
- Blenders:High-torque brushless motor units capture smoothie-preparation demand. Nutrient-extraction marketing and collapsible jug designs concentrate sales in England's metropolitan fitness-oriented households.
- Mixers:Planetary-action stand mixers with bowl-lift mechanisms serve baking enthusiasts. Compact hand-mixer variants address storage limitations in smaller urban dwellings.
- Toasters:Long-slot and bagel-function models lead replacement cycles. Crumb-access design and cool-wall housing influence supermarket buyer specifications.
Coffee makers lead on scale; blenders lead on momentum.
Technology:
Energy efficiency mandates and connectivity premiums create tiered pricing architecture across motor and control system specifications.
- Energy-Efficient:Ecodesign-compliant heating elements and electronically commutated motors reduce active-mode consumption. These configurations dominate absolute unit sales through mass-market channels as regulatory minimums harden.
- Smart Appliances:Wi-Fi-enabled control interfaces and app-based recipe integration attract tech-forward households. Grid-responsive scheduling functionality aligns with domestic energy platform expansion in the South East.
- IoT-Enabled:Sensor-integrated units with predictive maintenance capabilities enable subscription filter replacement. Firmware update infrastructure and cloud connectivity inflate bill-of-materials costs.
- Conventional:Basic electromechanical controls and universal motor architectures serve price-sensitive segments. These units face margin compression as efficiency regulations mandate redesign investment.
Energy-efficient models lead on scale; smart appliances lead on momentum.
End User:
Usage intensity and durability requirements differentiate procurement specifications across domestic and commercial contexts.
- Residential:Single-household and multi-occupancy rental units drive volume concentration. Aesthetic coordination with fitted kitchens influences premium purchase decisions in owner-occupied properties.
- Commercial:Cafes and co-working spaces demand commercial-grade duty cycles and rapid-recovery heating systems. These buyers prioritize warranty terms and service network density over initial purchase price.
- Hospitality:Hotel breakfast service and in-room placement require compact footprints and simplified user interfaces. Procurement runs through specialist hospitality supply contracts rather than retail channels.
- Retail:Demonstration unit purchases and staff break-room provisioning generate intermittent bulk orders. Seasonal peaks align with pre-Christmas inventory builds.
Residential leads on scale; commercial leads on momentum.
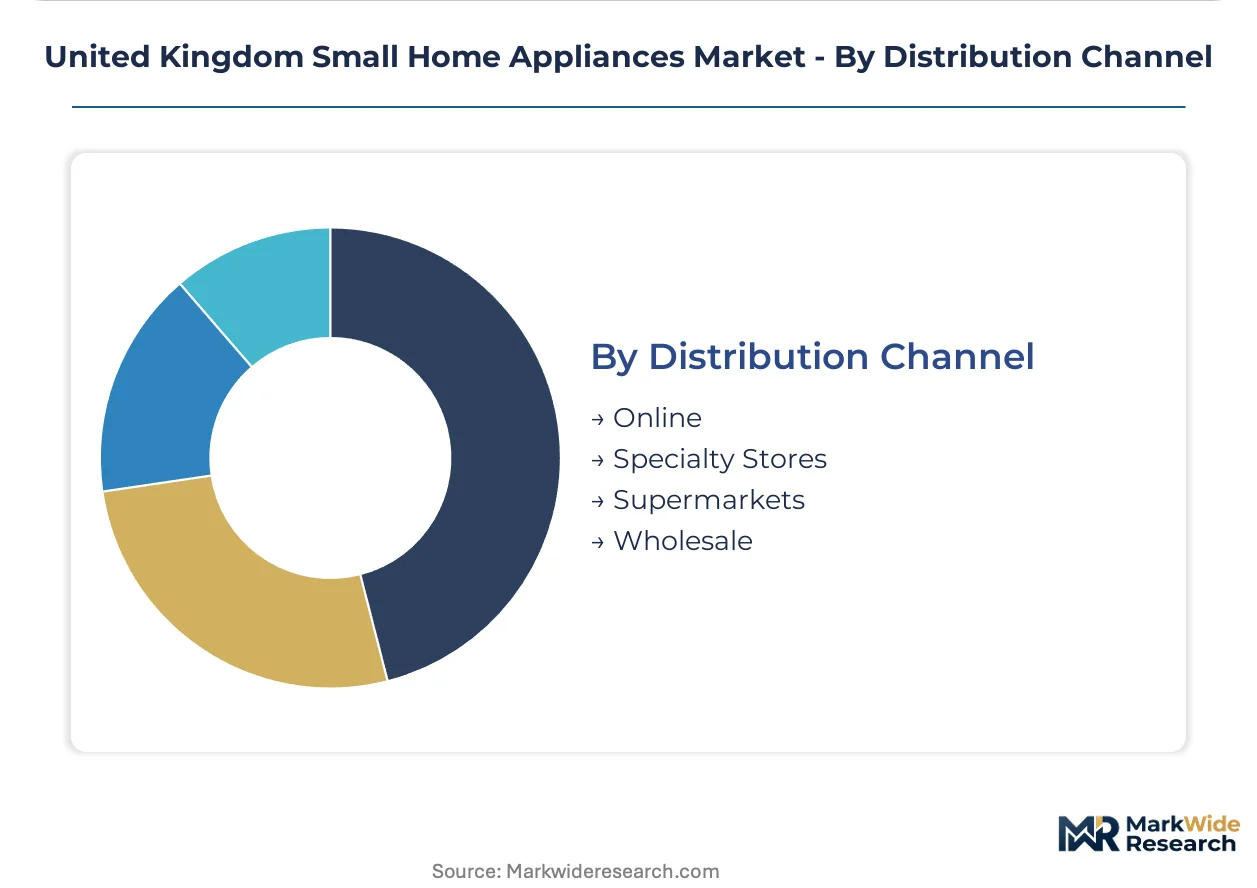
Distribution Channel:
Channel selection determines compliance burden exposure, return logistics complexity, and brand positioning latitude.
- Online:Direct-to-consumer and marketplace platforms capture comparison-shopping behaviour. Review aggregation and subscription replenishment models concentrate in this channel.
- Supermarkets:Grocery retail buyers specify dimensional constraints and impulse-display compatibility. Own-label sourcing agreements compress branded manufacturer margins.
- Specialty Stores:Kitchenware independents and department store concessions enable tactile evaluation and staff consultation. Premium positioning and extended warranties justify higher price points.
- Wholesale:Trade-only distribution serves builder-merchant and contract-furnishing channels. Volume pricing and project-tender participation define competitive dynamics.
Supermarkets lead on scale; online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's small home appliances industry traces its commercial lineage to post-war electrification of British households, with manufacturing clusters consolidating first in the English Midlands before spreading to Scotland and Wales through the 1960s and 1970s.
London and the South East
Rental density in Greater London and commuter belt counties concentrates demand for collapsible, multi-functional kitchen devices with minimal countertop footprints. The Office for Product Safety and Standards enforces UKCA marking requirements that streamline compliance for domestic manufacturers. Retail distribution in the M25 corridor accounts for disproportionate volume in premium coffee makers and smart-enabled appliances.
Midlands
Engineering heritage in Birmingham and Coventry sustains component supply chains for motor winding and thermostatic control manufacturing. The region's technical workforce supports testing laboratory capacity for Ecodesign compliance validation. Wolverhampton and Stoke-on-Trent host specialist metal-forming facilities serving housing and heating element production.
North England
Manchester and Leeds rental markets mirror London's space-constrained appliance preferences with stronger price sensitivity. Northern Powerhouse investment programs channel infrastructure funding toward logistics hubs that reduce distribution costs to Scottish markets. Sheffield retains specialized steel supply relationships for premium housing materials.
Scotland
Edinburgh and Glasgow metropolitan areas show underdeveloped retail penetration for premium small appliance brands relative to comparable English cities. Scottish Government energy efficiency schemes create procurement pull for Ecodesign-compliant heating and climate-control devices. Aberdeen's compact housing stock favors space-optimized appliance formats.
Wales
South Wales manufacturing corridors near Newport and Cardiff maintain assembly operations for mid-market kitchen electrics targeting English supermarket channels. Welsh Government innovation funding supports motor efficiency research at Cardiff University engineering departments. Rural North Wales households demonstrate higher manual appliance substitution rates than urban centers.
United Kingdom Small Home Appliances Market Competitive Landscape
Premium-margin players sit above commodity-margin players across motor technology and connectivity architecture dimensions. The vendor base organizes into three tiers: proprietary technology specialists, mid-market brand licensors, and volume-driven private-label suppliers. Two strategic archetypes dominate: vertically integrated motor manufacturers and brand-asset licensors outsourcing production. Competitive moves concentrate on portfolio diversification into adjacent climate-control categories and geographic expansion through refurbished goods platforms.
Among UK-anchored specialists, Dyson and Morphy Richards exemplify contrasting archetypes. Dyson occupies a position defined by captive digital motor technology and premium pricing authority. Morphy Richards sits within the mid-market tier, leveraging established supermarket and online distribution relationships. BSH Home Appliances Ltd represents the multinational engineering-credentials archetype, competing through built-in compatibility and installer-channel relationships.
| Leading Market Players |
|---|
| Dyson |
| Morphy Richards |
| BSH Home Appliances Ltd |
| De’Longhi |
| KitchenAid |
| Philips |
| Black & Decker |
| Electrolux |
| Russell Hobbs |
| Others |
Value Network & Pricing Analysis
UKCA marking harmonization for electrical equipment imports compresses supplier qualification timelines and forces manufacturers to absorb dual-certification laboratory costs, which then transmit into tiered pricing stratification across premium, standard, and economy product tiers.
Pricing Analysis
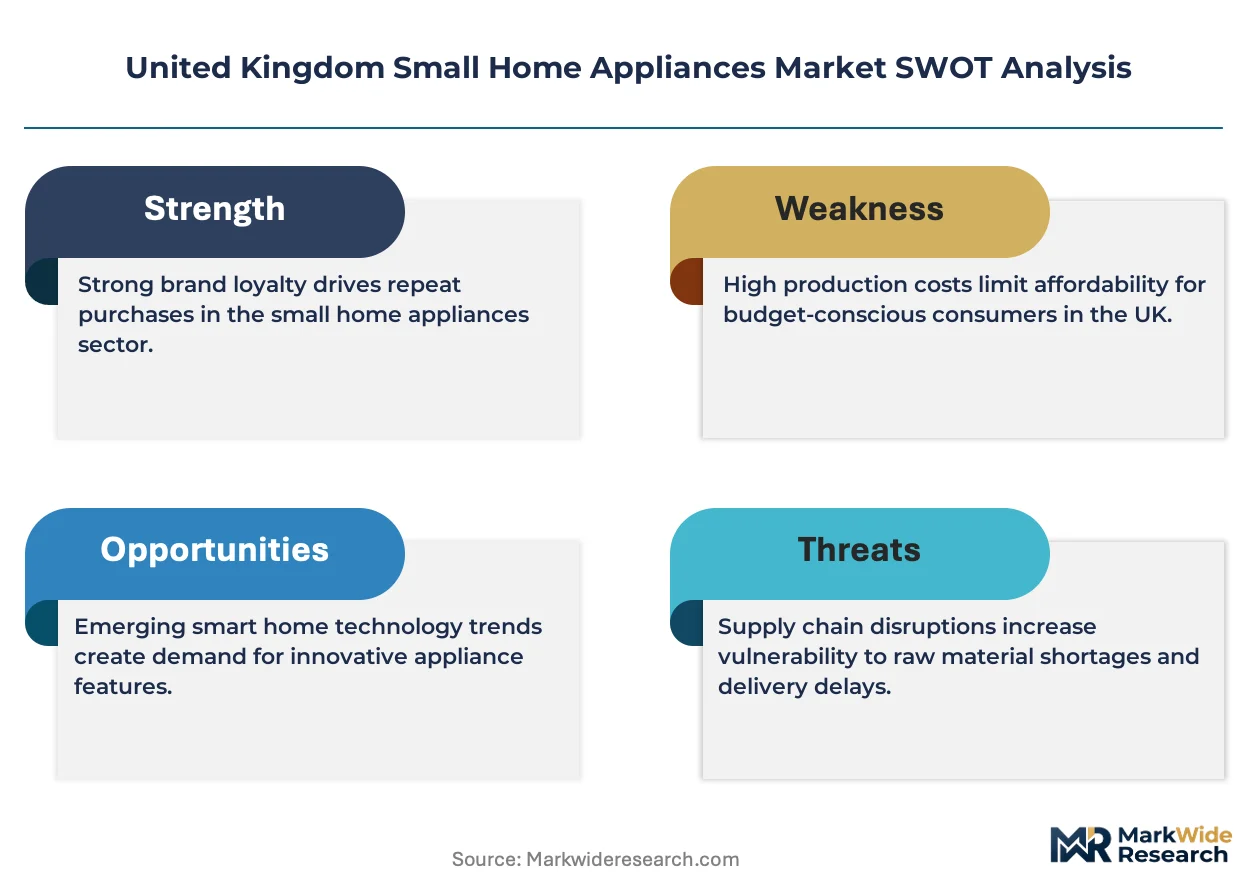
Three-tier pricing structure across premium, standard, and economy levels dominates UK small home appliances, with price differentiation driven by motor technology tier and smart connectivity certification. Cost compression in the economy tier is intensifying because Ecodesign regulations mandate universal motor redesigns. Supermarket buyers exhibit the highest price sensitivity, while specialty store purchasers prioritize engineering credentials over initial outlay.
Supply Chain Analysis
Dual-sourcing requirements from major UK retailers mandate brushless DC motor qualification across at least two Asian manufacturing bases, typically drawing from China and Vietnam for winding assemblies. Rare-earth magnet supply rests on concentrated Chinese processing capacity, creating single-source vulnerability for premium motor tiers. Distribution runs through supermarket central warehouses and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK small home appliances market functions as a stable compounder, with rental household formation in metropolitan corridors providing durable replacement-cycle demand.
For Market Incumbents: Lock in proprietary motor technology through backward integration into digital control firmware development, defending against emerging smart-home platform entrants. Prioritize UKCA certification investment to maintain supermarket shelf access as compliance timelines compress. For New Entrants and Emerging Players: Direct-to-consumer subscription models offer the most penetrable route for sensor-integrated appliances with filter replenishment revenue. Target Scotland's underdeveloped premium retail corridors through Edinburgh and Glasgow digital marketing spend. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-market brand licensors possessing established supermarket relationships but lacking smart-home connectivity infrastructure. Watch for inflection when grid-responsive functionality becomes mandatory in domestic energy platform specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Wi-Fi-enabled appliances align with Octopus Energy and OVO grid-responsive scheduling requirements. |
| Refurbishment Channel Development | Certified pre-owned units capture circular economy preferences in Manchester rental corridors. |
| Brushless DC Motor Backward Integration | In-house digital motor production reduces rare-earth magnet cost volatility exposure. |
| Scotland Retail Distribution Expansion | Glasgow and Edinburgh show underdeveloped penetration for premium appliance brands. |
| Ecodesign Compliance Pre-Investment | Early UKCA marking completion secures supermarket buyer procurement slots ahead of regulatory deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with supermarket category buyers, motor winding plant engineers, domestic energy platform product managers, and Ecodesign testing laboratory directors with secondary validation against UK Office for National Statistics household formation data, Office for Product Safety and Standards enforcement notices, and Companies House import filings. Bottom-up segment sizing and top-down macroeconomic anchoring provided triangulation checks.
Segment-weighting approaches distributed volume and value projections across product type, technology tier, end-user intensity, and distribution channel dimensions over the projection horizon. CAGRs derived from historical replacement-cycle patterns, rental household growth trajectories, and regulatory compliance cost pass-through assumptions. Smart appliance adoption curves and brushless DC motor cost reduction trajectories served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for grid-responsive IoT integration would alter the outlook if interoperability standards fragment across domestic energy platforms. Deviation in UKCA marking enforcement intensity or rare-earth export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
White Goods Market
Home Appliances
Range Hood Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
France Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Europe White Goods Market