
 Germany Home Appliances Market | 2026-2036
Germany Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Home Appliances Market Foresight
The EU Green Deal is decoupling energy-intensive appliance production from carbon-heavy supply chains across German manufacturing. BSH Hausgeräte GmbH leverages its captive Bavarian production network to sustain domestic assembly scale. Miele & Cie KG anchors premium positioning through specialized craftsmanship in Gütersloh. Robert Bosch GmbH competes on connected-device R&D intensity out of Stuttgart engineering centers.
Germany home appliances encompass electrically powered domestic equipment engineered to IEC 60335 safety standards, with power ratings from 200W to 3kW depending on appliance class, designed for food preservation, textile care, cooking, and surface cleaning in residential and light-commercial environments. Refrigerators and washing machines occupy the largest installed base, though connected devices and smart appliances are capturing disproportionate margin pools as households prioritize remote monitoring and predictive maintenance capabilities. Energy-efficient technology segments face accelerated replacement cycles driven by Ecodesign labeling mandates and rising electricity tariffs.
KBA vehicle-electrification spillovers and REACH chemical compliance requirements shape material selection for polymer housings and refrigerant gases, while BSI and VDE certification gates market access for electrical safety and electromagnetic compatibility. The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants, forcing compressor redesigns across refrigerator and freezer portfolios. Stakeholders must monitor Brussels policy velocity against German manufacturer adaptation timelines to calibrate inventory and R&D commitments.
Market Dynamics
The EU F-Gas Regulation is forcing compressor redesigns across German refrigerator portfolios, while Ecodesign labeling mandates accelerate replacement cycles in energy-intensive appliance categories. Southern metropolitan clusters around Munich and Stuttgart concentrate demand pull.
Growth Catalysts
- Ecodesign Labeling Mandates:The EU Ecodesign Directive tightens minimum efficiency thresholds for washing machines and refrigeration equipment. Urban apartment households in Berlin and Hamburg respond with accelerated replacement purchasing.
- REACH Chemical Compliance:Stricter polymer housing standards under ECHA guidelines are filtering subscale component suppliers. German manufacturers with captive material testing capabilities capture specification-setting authority.
- Urban Apartment Density:Compact appliance form factors gain traction in Frankfurt and Cologne rental markets. Space-constrained households prioritize multi-function cooking and cleaning equipment.
Market Restraints
- Refrigerant Input Volatility:Hydrofluorocarbon phase-down schedules under EU F-Gas Regulation compress compressor engineering timelines. Alternative refrigerant R&D absorbs disproportionate technical resources.
- Bavarian Production Concentration:Final assembly gravity centers on southern German industrial zones. Logistics costs escalate for distribution to northern and eastern federal states.
- Electronics Substitution Pressure:Connected-device ecosystems from adjacent consumer electronics categories encroach on standalone appliance control interfaces. Smart home platforms displace proprietary manufacturer apps.
Strategic Opportunities
- Predictive Maintenance Convergence:Sensor-embedded washing machines and dishwashers are integrating machine learning for failure anticipation. Service revenue models unbundle from hardware sales.
- EU Green Deal Tailwinds:Carbon-border adjustment mechanisms favor domestic European assembly over Asian import competition. German captive production networks qualify for green procurement preferences.
- Rural Household Underpenetration:Eastern German states including Saxony and Brandenburg exhibit lower connected-appliance penetration. Direct-to-installer channels bypass traditional retail concentration.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for IEC 60335-compliant connected devices competes with automotive electrification hiring. Stuttgart engineering clusters face KBA vehicle-sector wage pressure.
- VDE Certification Timelines:Electromagnetic compatibility testing queues extend for novel inverter motor designs. Product launch windows compress against seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Home Appliances Market |
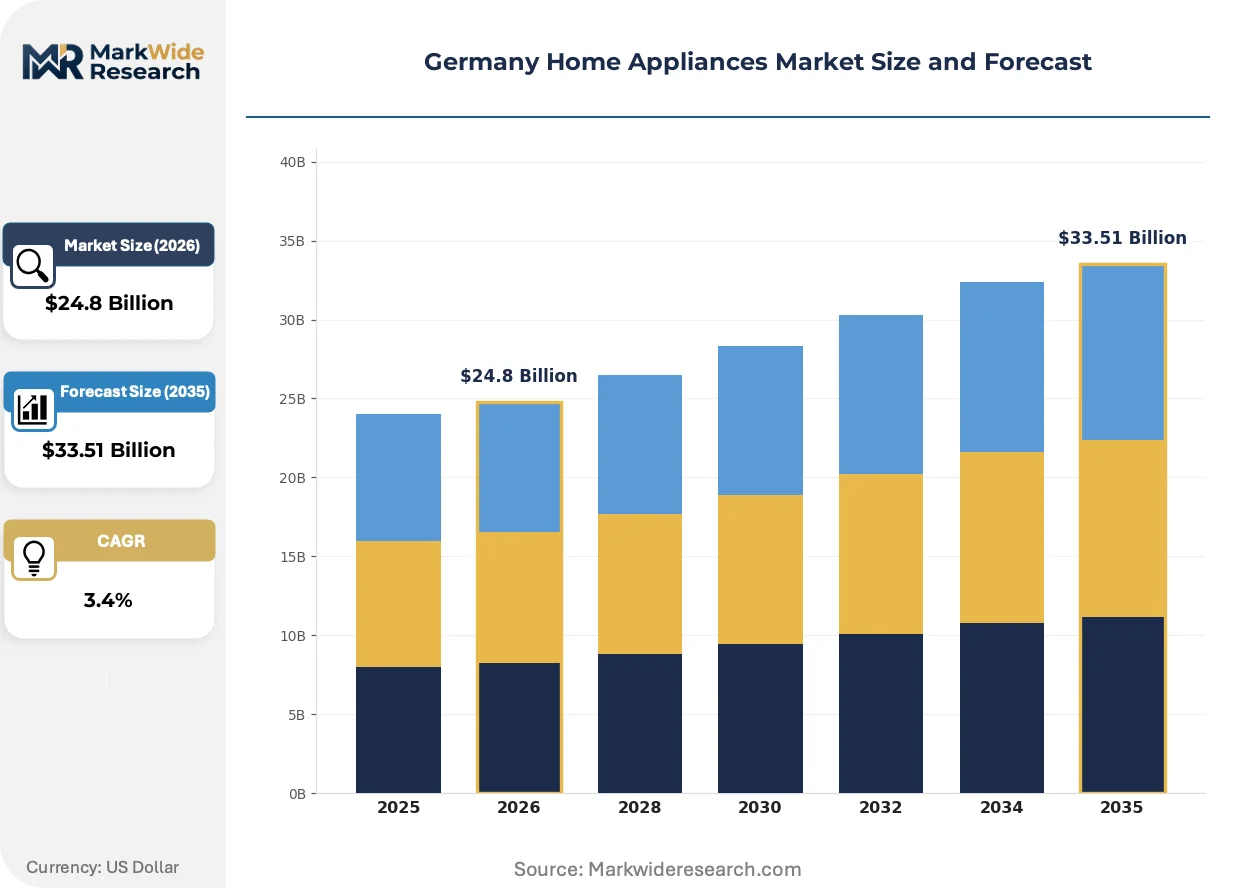
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $33.51 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers Technology: Smart Appliances, Energy-Efficient, Traditional, Connected Devices End User: Households, Apartments, Commercial Spaces, Rental Properties Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Electrolux AB, LG Electronics, BSH Hausgeräte GmbH, Liebherr Hausgeräte, Samsung Electronics, Miele & Cie KG, Whirlpool Corporation, Haier Group, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Home Appliances Market Shifts & Advancements
Sensor fusion and edge computing are rewriting control architectures across German appliance engineering centers. Regulatory chemistry mandates and shifting procurement patterns complete the transformation triangle.
Inverter-driven heat pump dryers are integrating variable-speed compressor technology with humidity-optimized cycle algorithms. Premium segment buyers in Baden-Württemberg adopt these systems at twice the national average. The technology is integrating moisture-sensing precision that halves energy consumption versus conventional resistive heating.
The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants with GWP thresholds tightening through 2030. Compressor manufacturers must validate alternative refrigerant chemistries under accelerated timelines. Refrigeration portfolios face complete platform redesigns, with mid-size freezer categories experiencing the most severe engineering resource strain.
Apartment households are consolidating vendor relationships through bundled kitchen renovation contracts. Traditional electronics retail loses specification influence to kitchen studio channels and direct manufacturer portals. This concentration is most pronounced in Munich and Stuttgart metropolitan zones where new-build residential completions remain elevated.
Germany Home Appliances Market Segmentation
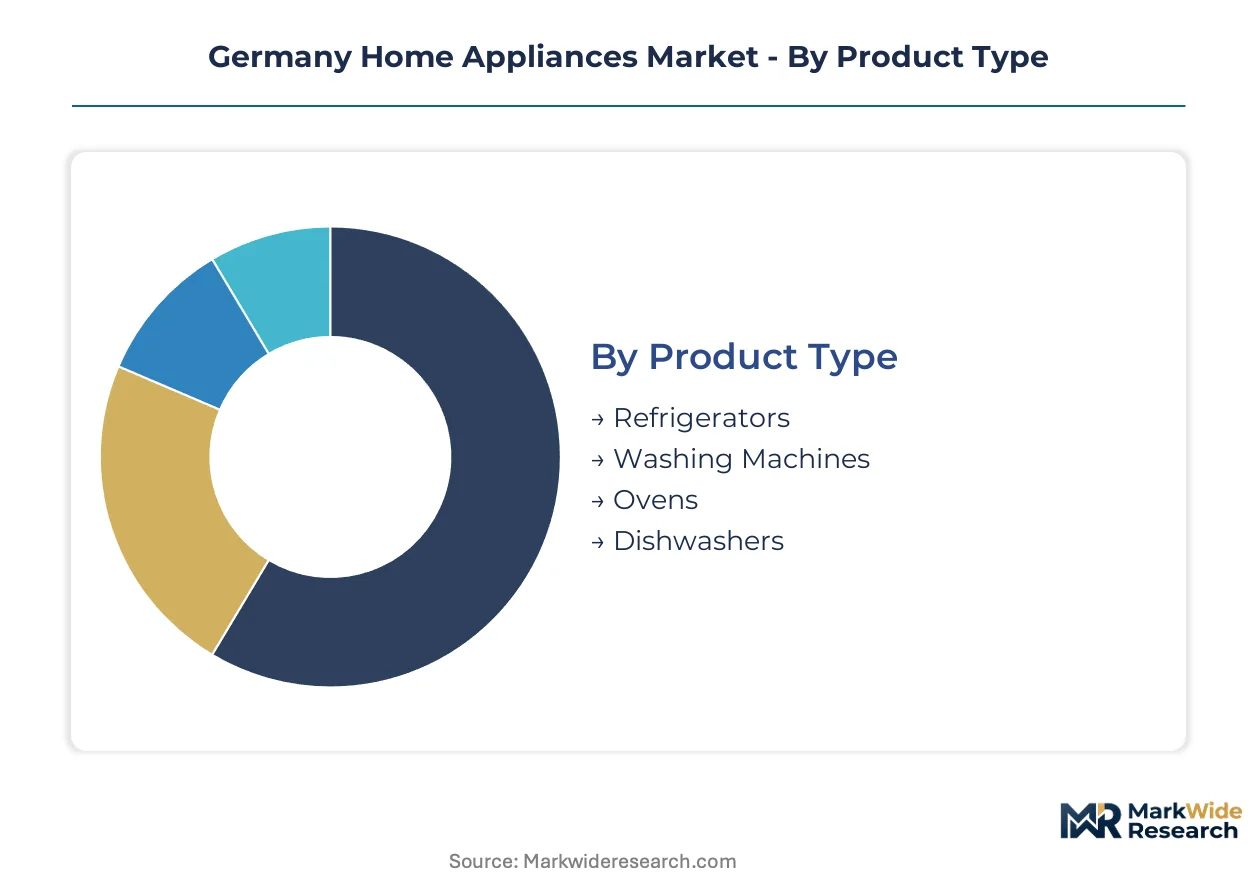
German appliance manufacturers calibrate production lines around distinct product architectures and technology tiers. Segmentation discipline separates high-margin connected portfolios from commodity replacement cycles.
Product Type:
Supply concentration tilts toward refrigeration and laundry platforms where Bavarian engineering centers maintain captive compressor and motor production.
- Refrigerators:Compression-based cooling systems span single-door through side-by-side configurations. Munich and Stuttgart apartment renovations drive demand for counter-depth and integrated panel-ready units. EU F-Gas Regulation refrigerant mandates force complete platform redesigns across the category.
- Washing Machines:Front-loading drum systems dominate with inverter motor drives replacing universal motors. Urban rental markets in Berlin and Hamburg prioritize energy-labeled A+++ units to offset rising electricity tariffs. Ecodesign labeling accelerates replacement purchasing among cost-conscious households.
- Ovens:Convection and pyrolytic self-cleaning variants serve kitchen studio channels.
- Dishwashers:Slimline 45cm formats gain share in space-constrained Frankfurt apartments.
Refrigerators absorb the bulk of installed capacity; dishwashers are expanding most quickly.
Technology:
Cost tier stratification separates premium sensor-embedded systems from baseline mechanical controls.
- Smart Appliances:WiFi-enabled units with cloud-connected diagnostics and remote cycle management. Baden-Württemberg households adopt these systems at elevated rates. Predictive maintenance algorithms unbundle service revenue from hardware margins.
- Energy-Efficient:Heat pump dryers and inverter-driven compressors halve consumption versus resistive heating. Southern metropolitan clusters respond to Ecodesign mandates with accelerated replacement cycles.
- Traditional:Electromechanical controls without connectivity modules serve price-sensitive segments.
- Connected Devices:Matter protocol compatibility enables cross-brand smart home integration.
Energy-efficient platforms absorb the bulk of installed capacity; smart appliances represent the fastest-growing trajectory.
End User:
Application context determines form factor specifications and channel access patterns.
- Households:Owner-occupied single-family homes prioritize full-size appliances with extended warranty terms. Rural Saxony and Brandenburg markets exhibit lower connected-device penetration.
- Apartments:Space-constrained units in Cologne and Frankfurt rental markets demand compact multi-function equipment. Kitchen studio channels bypass traditional electronics retail for specification influence.
- Commercial Spaces:Light-duty food service and hospitality operations require certified durability ratings.
- Rental Properties:Landlord procurement favors standardized SKUs with service network coverage.
Households absorb the bulk of installed capacity; apartments are climbing the fastest.
Distribution Channel:
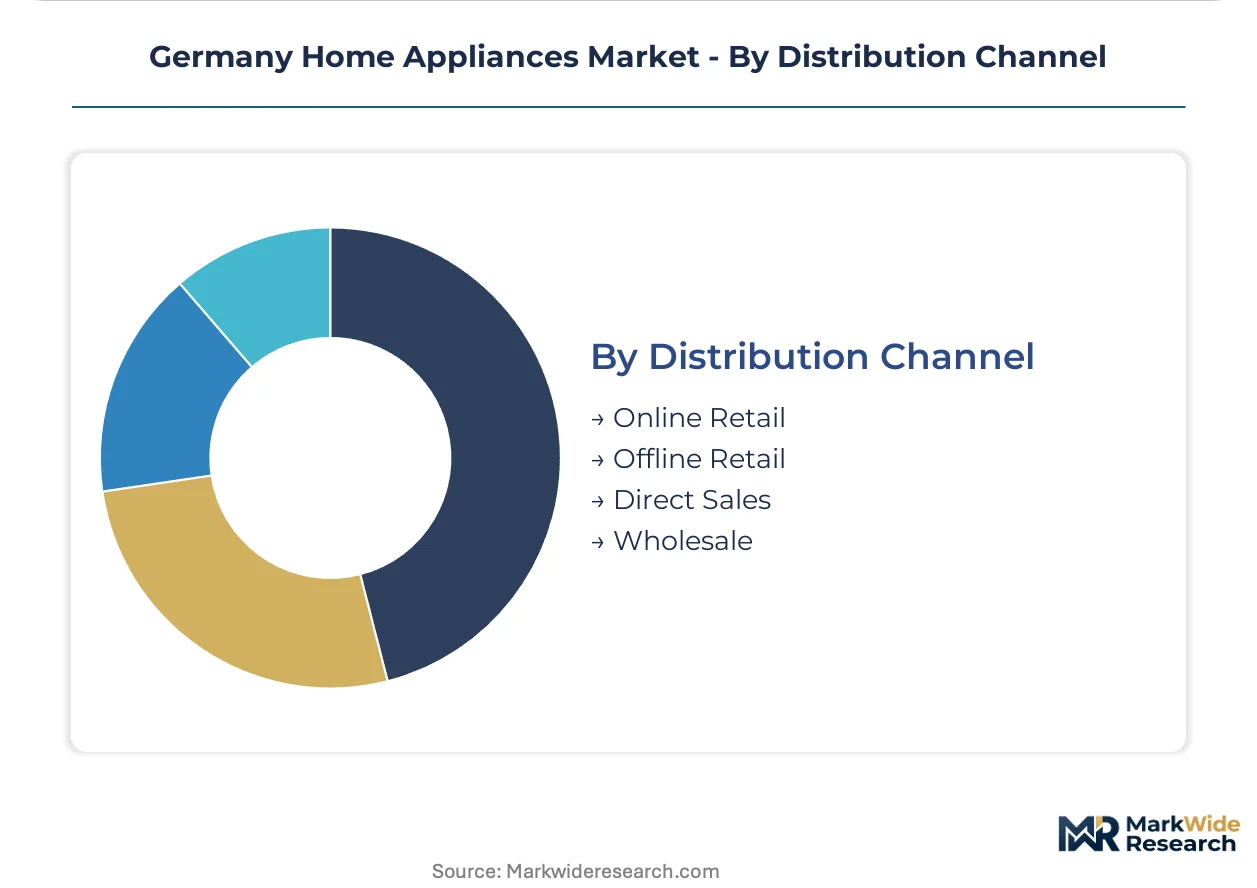
Volume flows reshape around direct manufacturer portals and installer-mediated specification.
- Online Retail:Manufacturer-owned storefronts and marketplace platforms capture replacement purchasing. Berlin and Hamburg urban demographics favor digital channels for research and transaction completion.
- Offline Retail:Electronics specialty stores lose share to kitchen studio networks in Munich and Stuttgart new-build corridors.
- Direct Sales:Builder and developer relationships secure pre-installation commitments.
- Wholesale:Installer and maintenance contractor networks serve eastern German states with limited retail density.
Offline retail absorbs the bulk of installed capacity; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German appliance production concentrates in southern industrial zones while consumption spreads across federal states with distinct urban-rural patterns. Manufacturing scale in Bavaria and Baden-Württemberg outpaces northern demand density.
Bavaria
Munich metropolitan renovations drive integrated panel-ready refrigerator demand. The EU F-Gas Regulation forces compressor redesigns through Bavarian engineering centers. Ingolstadt and Nuremberg industrial corridors anchor captive production networks for domestic assembly scale.
Baden-Württemberg
Stuttgart engineering clusters generate connected-device R&D intensity for predictive maintenance algorithms. KBA vehicle-electrification spillovers compete for embedded systems talent. Premium heat pump dryer adoption in Freiburg and Karlsruhe runs twice the national average.
North Rhine-Westphalia
Cologne and Düsseldorf rental markets prioritize compact multi-function cooking equipment. Ecodesign labeling mandates accelerate washing machine replacement among electricity tariff-sensitive households. The Ruhr industrial legacy supports polymer housing component supply.
Berlin-Brandenburg
Urban apartment density in Berlin favors slimline dishwasher formats and space-constrained laundry solutions. Eastern Brandenburg exhibits lower connected-appliance penetration versus western federal states. Direct-to-installer channels bypass traditional retail concentration in rural zones.
Hesse
Frankfurt financial sector salaries support premium smart appliance adoption in owner-occupied units. REACH chemical compliance requirements filter subscale polymer suppliers through Rhine-Main logistics hubs. Kitchen studio channels capture specification influence from electronics retail.
Germany Home Appliances Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive component production. Market concentration reflects high capital requirements for IEC 60335-compliant manufacturing and VDE certification barriers. Three archetypes dominate: vertically integrated domestic manufacturers, Korean-Japanese electronics multinationals with scale advantages, and premium craftsmanship specialists. Capacity expansion and predictive maintenance service unbundling represent the dominant competitive moves.
Among Germany-based manufacturers, BSH Hausgeräte GmbH and Miele & Cie KG exemplify contrasting strategic positions. BSH occupies a scale-driven role leveraging Bavarian production networks for domestic assembly compliance with EU Green Deal procurement preferences. Miele anchors the premium craftsmanship archetype through specialized engineering traditions. Robert Bosch GmbH represents the diversified conglomerate model, competing on connected-device R&D intensity from Stuttgart engineering centers.
| Leading Market Players |
|---|
| Electrolux AB |
| LG Electronics |
| BSH Hausgeräte GmbH |
| Liebherr Hausgeräte |
| Samsung Electronics |
| Miele & Cie KG |
| Whirlpool Corporation |
| Haier Group |
| Robert Bosch GmbH |
| Others |
Supply & Pricing Matrix
Family-owned engineering conglomerates anchor German appliance manufacturing, translating captive Bavarian production networks into pricing discipline that resists Asian import undercutting. Their ownership structure insulates margin targets from quarterly earnings pressure, reinforcing long-term investment in EU Green Deal compliance that smaller competitors cannot match.
Pricing Analysis
Margin tightening in mid-tier segments traces to Ecodesign labeling mandates that accelerate replacement cycles among electricity tariff-sensitive households. Three-tier pricing structure across premium, standard, and economy levels separates Miele craftsmanship positioning from BSH scale economics and Korean-Japanese volume plays. Price differentiation hinges on VDE certification grade and after-sales service bundling. Berlin apartment renters exhibit highest price sensitivity; Baden-Württemberg owner-occupiers show least.
Supply Chain Analysis
Freight cost escalation from Bavarian production gravity to eastern federal states compresses distributor margins in Saxony and Brandenburg. Component sourcing draws from China for electronics modules, Italy for design-intensive finishes, and Poland for polymer housings. Single-source vulnerability concentrates in inverter motor controllers sourced from Taiwanese semiconductor fabricators. Distribution runs through kitchen studio channels in southern metropolitan clusters and direct-to-installer networks in rural zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Home Appliances Market functions as a cost-of-compliance story where EU F-Gas Regulation refrigerant phase-downs erect engineering barriers that filter subscale competitors and reward captive R&D investment.
For Market Incumbents: Lock in specification-setting authority through accelerated compressor platform redesigns that absorb F-Gas compliance costs competitors cannot shoulder. Deepen backward integration into refrigerant chemistry validation and predictive maintenance algorithm development to unbundle service revenue from hardware margins before Korean-Japanese electronics multinationals close the connectivity gap. For New Entrants and Emerging Players: Begin with eastern German rural household segments where connected-appliance penetration lags western federal states by substantial margins. Kitchen studio channel partnerships in Cologne and Frankfurt rental markets offer specification influence bypassing established retail concentration. Direct-to-installer logistics models address service network gaps that incumbent distribution infrastructure underserves. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with partial VDE certification pipelines and stranded inventory in transitional refrigerant categories. Long-term viability across the analysis window rests on EU Green Deal procurement preference qualification and captive southern German production scale. The signal to watch is Brussels policy velocity against German engineering center adaptation timelines for inventory and R&D commitment calibration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Redesign | F-Gas Regulation compliance secures EU market access against Asian import competition. |
| Predictive Maintenance Service Unbundling | Sensor-embedded washing machines generate recurring revenue beyond hardware sale margins. |
| Kitchen Studio Channel Expansion | Munich and Stuttgart new-build corridors concentrate specification influence away from electronics retail. |
| Backward Integration into Compressor Production | Captive Bavarian engineering centers control refrigerant validation timelines and cost structures. |
| Eastern German Installer Network Buildout | Direct-to-installer models penetrate Saxony and Brandenburg markets with limited retail density. |
Research Methodology
Independent corroboration across appliance manufacturer engineering directors, kitchen studio specification consultants, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork engaged plant managers at Bavarian production facilities, procurement leads at polymer housing suppliers, and aftermarket service heads covering eastern German federal states. Secondary validation drew from EU F-Gas Regulation implementation reports, VDE certification queue disclosures, and customs records tracking refrigerant component imports. Bottom-up SKU-level shipment analysis triangulates against top-down federal state consumption estimates.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product architecture, technology tier, end-use context, and distribution channel. CAGRs derive from replacement cycle acceleration curves tied to Ecodesign mandate phase-ins and electricity tariff elasticity assumptions. Industry-specific forecast inputs incorporate KBA vehicle-electrification talent competition effects on embedded systems hiring costs and REACH chemical compliance timeline uncertainties.
Underlying measurement precision varies by segment; smart appliance and connected device categories carry tighter precision than traditional electromechanical equipment due to more consolidated vendor reporting. Forecasts reflect assumptions around Brussels regulatory implementation velocity and German manufacturer adaptation capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Egypt Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Europe Laundry Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
India Major Home Appliances Market