
 China Laundry Appliances Market | 2026-2036
China Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
China Laundry Appliances Market Outlook
Buyer concentration among property developers and rental housing operators is shifting as China's urban housing stock modernizes, pulling procurement toward bulk contracts for standardized laundry solutions. Haier Group leverages its domestic manufacturing scale to anchor supply agreements with major residential developers. GD Midea Holding Co Ltd competes through deep distribution networks spanning third and fourth-tier cities. Hisense Group specializes in compact front-load systems engineered for high-rise apartment footprints.
China laundry appliances encompass electrically powered machines for washing, drying, and combined fabric care, typically operating at 220V/50Hz with drum capacities ranging from six to twelve kilograms and water consumption ratings governed by national efficiency tiers. The primary commercial purpose centers on automating textile cleaning across households, hospitality operations, and industrial linen processing. Washing machines dominate installed base volumes while smart appliances capture expanding margin pools through IoT connectivity and usage-based service models. Energy-efficient models face accelerating pull from utility rebate programs and property manager ESG procurement criteria.
MIIT enforces GB standards covering energy consumption, water efficiency, and electromagnetic compatibility for all domestically sold laundry equipment. SAMR administers mandatory energy labeling that directly shapes consumer purchase decisions and manufacturer product line priorities. China's dual carbon goals pressure producers to redesign compressor and heating systems for lower greenhouse gas intensity. Stakeholders must monitor regulatory tightening on refrigerants and water discharge standards that could obsolete current dryer thermal pump architectures.
Market Dynamics
China's dual carbon goals are compressing product development cycles as MIIT tightens GB energy-efficiency tiers and water-consumption standards, forcing manufacturers to redesign thermal systems and compressor architectures ahead of regulatory deadlines.
Growth Catalysts
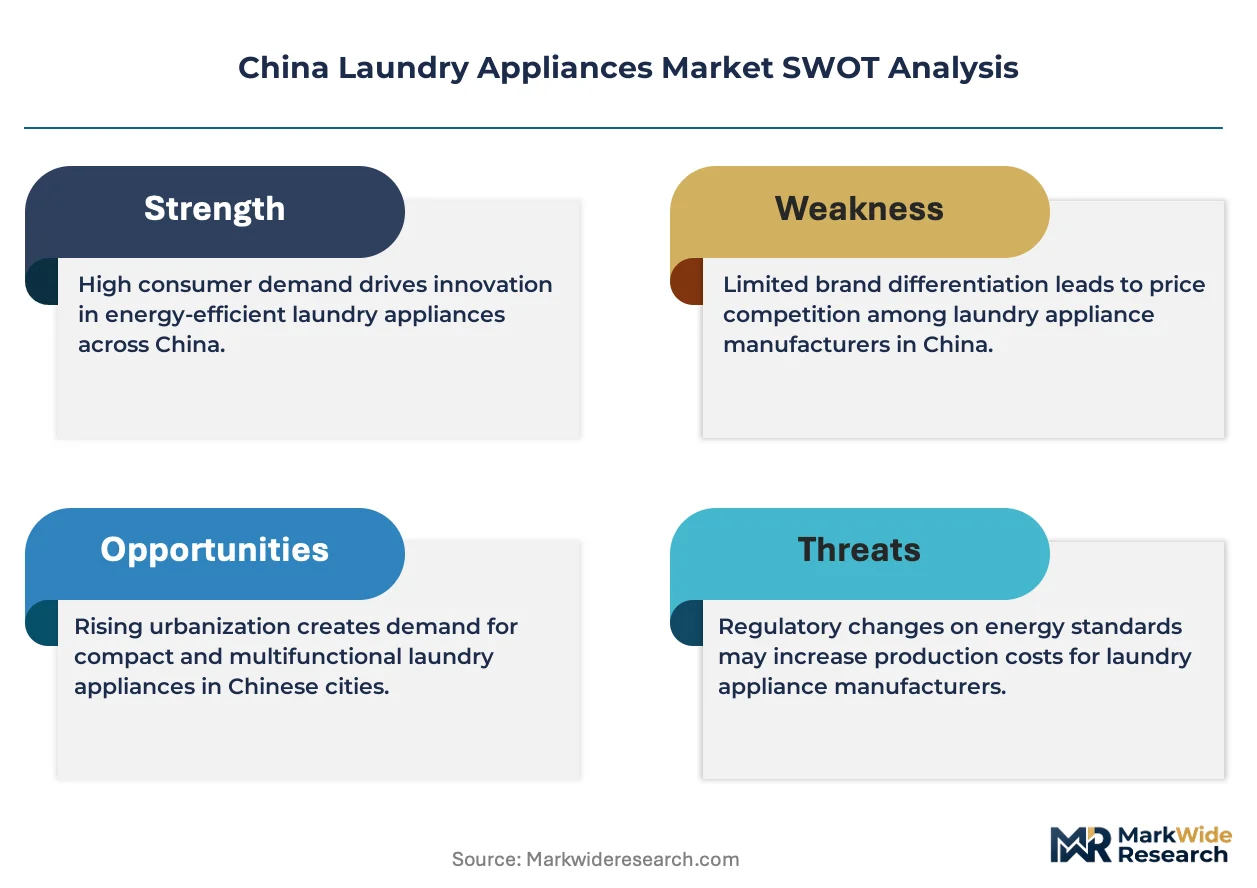
- Urban residential densification:High-rise construction in Shanghai, Beijing, and Shenzhen accelerates demand for compact washer-dryer combos that fit standardized apartment footprints.
- MIIT water-efficiency mandates:Updated GB standards for water labeling pull replacement demand toward machines with tier-one efficiency ratings.
- Smart appliance ecosystems:IoT connectivity integration enables usage-based service revenue streams and remote diagnostics for property managers.
Market Restraints
- Copper and steel input volatility:Raw material price swings compress margin buffers for drum and motor assembly production.
- Refrigerant supply concentration:Thermal pump dryer architectures depend on constrained imports of low-GWP refrigerants subject to MEE discharge scrutiny.
- Technical ceiling on heat-pump efficiency:Current compressor designs approach thermodynamic limits without breakthrough materials.
Strategic Opportunities
- Third and fourth-tier city penetration:Underpenetrated inland provinces offer volume expansion as distribution networks deepen.
- Rental housing operator procurement:Bulk service contracts for standardized laundry fleets replace fragmented retail purchasing.
- SAMR ESG labeling convergence:Mandatory energy labeling alignment with property manager sustainability criteria creates premium positioning.
Industry Challenges
- Embedded software talent scarcity:Firmware engineering for IoT-enabled machines outpaces domestic training pipeline output.
- GB certification timeline compression:Accelerated standard revisions force parallel product redesigns before current generation payback.
- Legacy apartment electrical infrastructure:220V circuit limitations in older buildings constrain high-capacity machine deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Laundry Appliances Market |
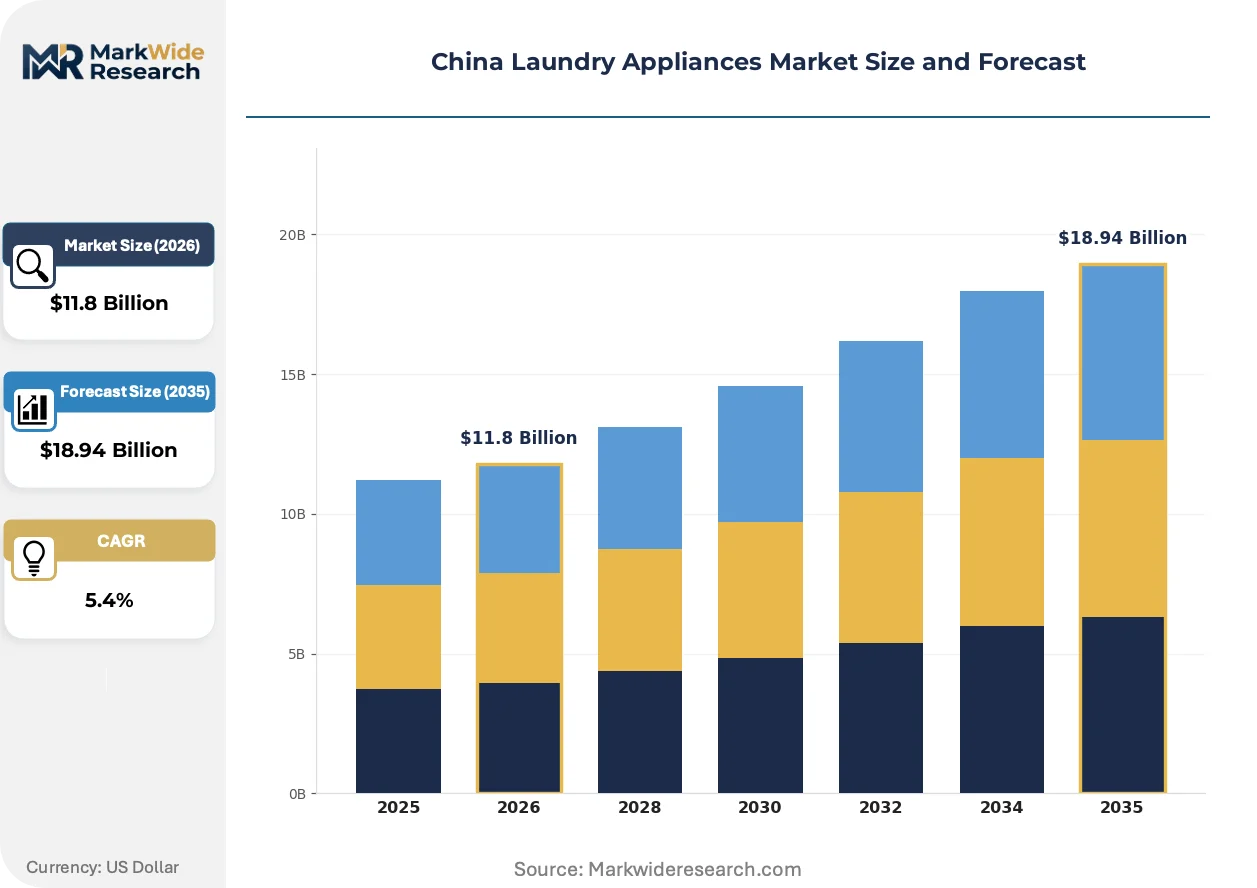
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Specialty Appliances End User: Residential, Commercial, Industrial, Laundromats Technology: Front-Load, Top-Load, Smart Appliances, Energy-Efficient Models Distribution Channel: Online Retail, Offline Stores, Distributors, Direct Sales |
| Companies Covered | GD Midea Holding Co Ltd, Haier Group, Whirlpool, Samsung Electronics, LG Electronics, Electrolux, Panasonic Corp, Bosch, Hisense Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Laundry Appliances Market Strategic Shifts
Heat-pump thermal technology is rewriting efficiency benchmarks while regulatory pressure on water and carbon intensity forces simultaneous hardware and software innovation across the supply base.
Heat-pump dryer systems with coefficient-of-performance ratings above three are rewriting energy consumption norms for fabric drying. Property developers in Guangdong and Jiangsu provinces specify these systems for new high-rise projects. The technology is compressing operating cost differentials that previously favored gas-vented alternatives.
MIIT's phased implementation of stricter GB 12021.4 energy-consumption limits is forcing compressor redesigns and control-system upgrades. Manufacturers must submit revised test data to SAMR certification bodies before existing product lines face market withdrawal. Front-load platforms above eight-kilogram capacity face the steepest compliance cost escalation.
Leasing and subscription-based access models are displacing outright purchase in urban rental housing segments. Operators like Vanke and Longfor bundle laundry appliances into monthly service fees rather than capitalizing hardware. This shift concentrates most visibly in Shanghai and Hangzhou where tenant turnover favors flexibility over ownership.
China Laundry Appliances Market Segmentation
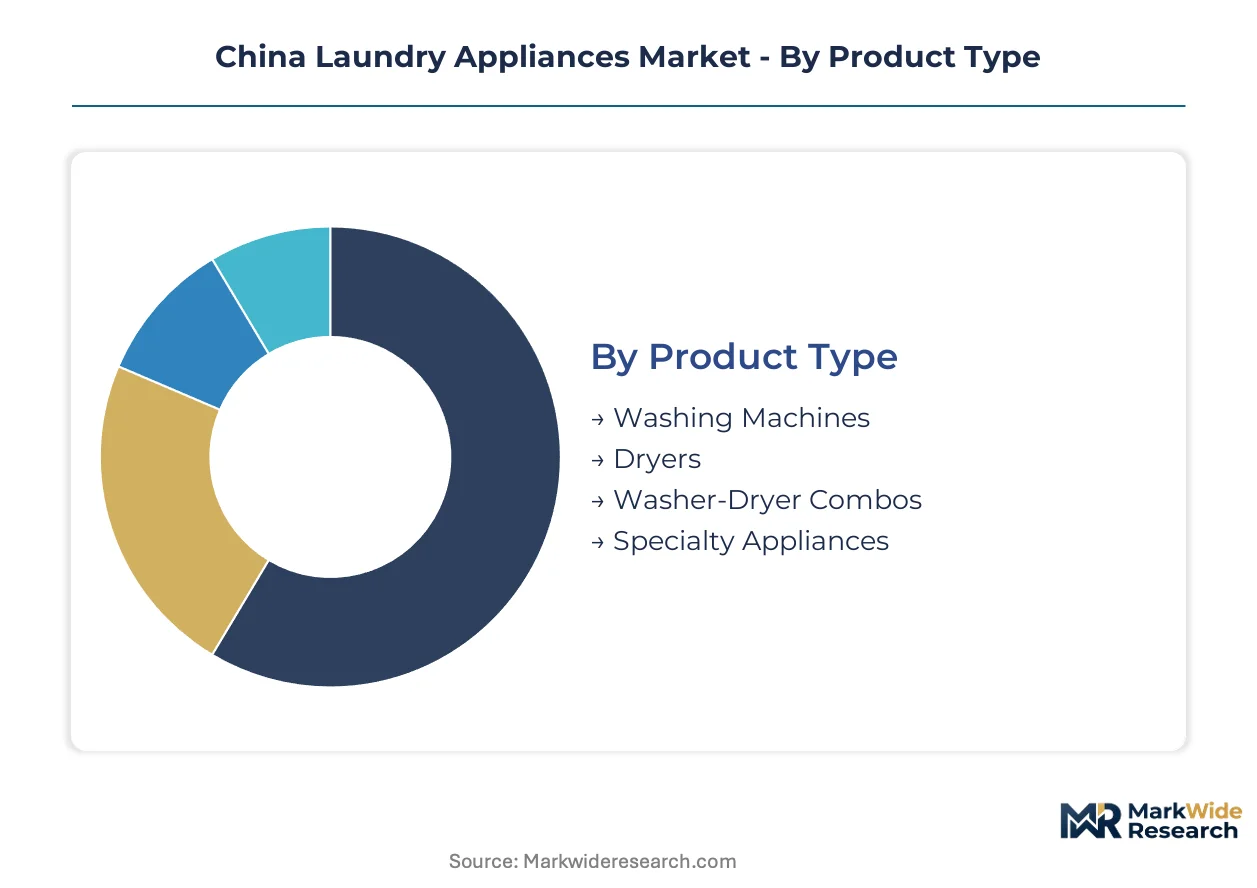
Segmentation in China's laundry appliances market reveals how regulatory pressure and urban density reshape procurement patterns across buyer categories. MIIT's tiered efficiency standards and SAMR labeling requirements create divergent compliance burdens that manufacturers must navigate through targeted product architectures.
Product Type:
Standardization dominates high-volume washing machines while washer-dryer combos command premium customization for space-constrained installations.
- Washing Machines:Drum capacities from six to twelve kilograms operate at 220V/50Hz with water consumption ratings governed by national efficiency tiers. Demand concentrates in tier-one cities including Shanghai and Beijing where replacement cycles accelerate under MIIT's updated GB standards for water labeling.
- Washer-Dryer Combos:Integrated units combine washing and drying functions within single footprints engineered for high-rise apartment constraints. Property developers in Shenzhen and Guangdong specify these systems for new residential complexes where space optimization overrides separate appliance preferences.
- Dryers:Standalone thermal pump and vented configurations serve households with dedicated utility spaces. Heat-pump architectures with coefficient-of-performance ratings above three face refrigerant supply constraints under MEE discharge scrutiny.
- Specialty Appliances:Compact units and fabric care systems address niche applications including delicate garment processing.
Leading the category by volume: Washing Machines. Expanding most quickly: Washer-Dryer Combos.
End User:
Cost tier stratification separates capital-light residential purchasers from bulk-procurement rental operators seeking standardized fleet solutions.
- Residential:Individual households drive replacement demand through retail channels with purchase decisions shaped by SAMR energy labeling visibility. Tier-one city consumers prioritize smart connectivity features that enable remote diagnostics.
- Commercial:Hotels and hospitality operations require high-duty-cycle machines with rapid throughput capabilities. Procurement concentrates through distributor networks serving Guangdong and Jiangsu province clusters.
- Industrial:Large-scale linen processing facilities demand specialized equipment with continuous-operation ratings.
- Laundromats:Self-service operations favor durable coin-operated or card-payment systems with minimal attendant requirements.
Residential buyers dominate unit volumes. Rental housing operators represent the steepest expansion trajectory as Vanke and Longfor bundle appliances into subscription service models.
Technology:
Application requirements split the market between water-efficient front-load platforms and convenience-oriented top-load alternatives.
- Front-Load:Horizontal drum orientation enables water-efficient operation with tumble-action cleaning mechanics. Platforms above eight-kilogram capacity face steepest compliance cost escalation under MIIT's phased GB 12021.4 implementation.
- Smart Appliances:IoT-enabled machines integrate firmware for usage-based service revenue and predictive maintenance alerts. Embedded software talent scarcity constrains domestic development pipeline output for these systems.
- Top-Load:Vertical axis designs maintain preference in older buildings with 220V circuit limitations that constrain high-capacity front-load deployment.
- Energy-Efficient Models:Tier-one rated machines qualify for utility rebate programs and property manager ESG procurement criteria.
Front-Load systems anchor installed base volumes. Smart Appliances gain share fastest through property developer specification for new high-rise projects.
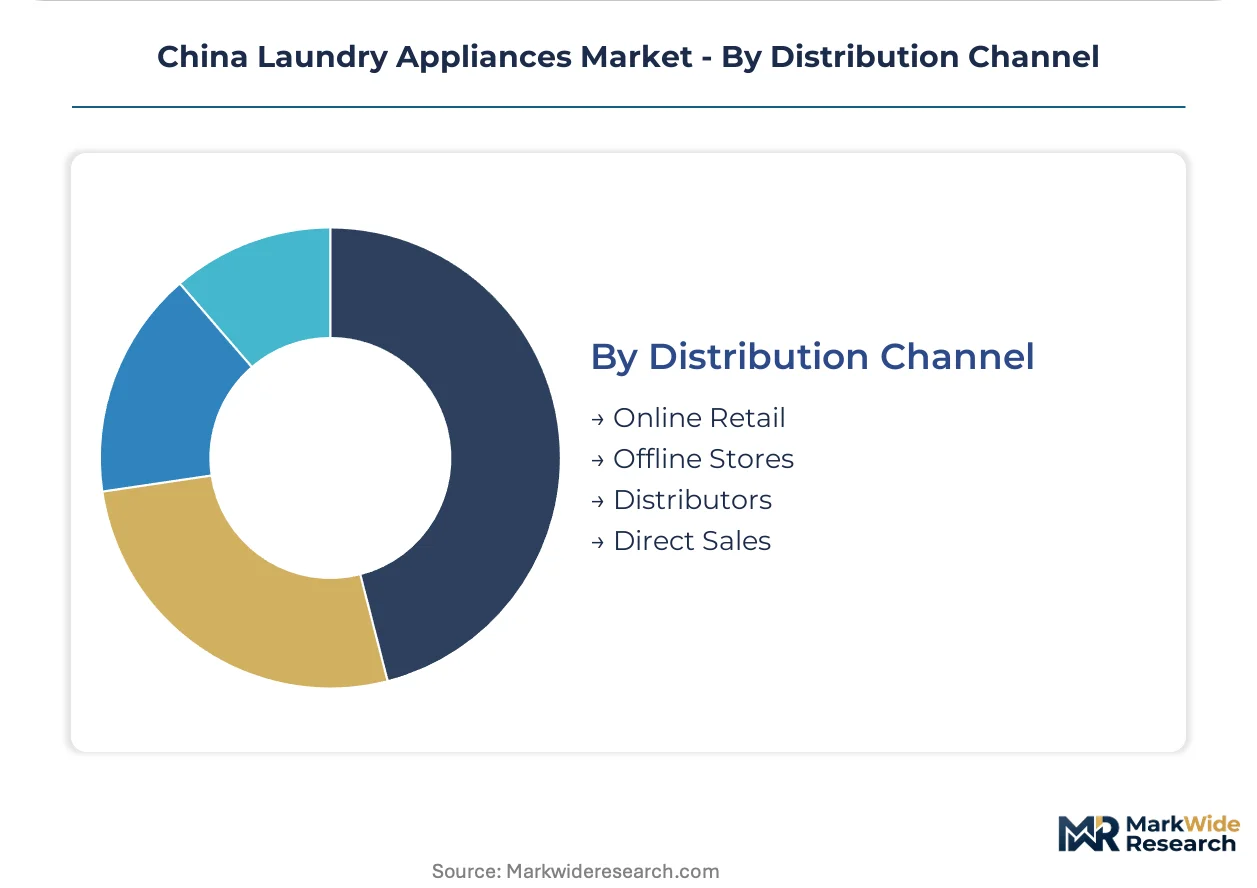
Distribution Channel:
Customer type fragmentation pulls procurement toward direct sales for bulk contracts while individual buyers fragment across omnichannel touchpoints.
- Online Retail:E-commerce platforms capture growing share of replacement purchases with SAMR labeling information prominently displayed. Third and fourth-tier city penetration deepens as logistics networks extend inland.
- Offline Stores:Physical showrooms enable tactile evaluation of drum capacity and noise specifications. Haier Group and GD Midea Holding Co Ltd anchor presence through branded retail networks.
- Distributors:Regional wholesalers serve commercial and industrial accounts with installation and service bundling.
- Direct Sales:Bulk contracts with property developers and rental housing operators bypass retail markup through manufacturer-direct negotiation.
Offline Stores maintain volume leadership. Direct Sales channels climb fastest as standardized fleet procurement displaces fragmented retail purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's laundry appliances demand concentrates in coastal urban corridors where high-rise residential construction and MIIT efficiency mandates converge. Provincial-level procurement patterns diverge sharply between mature tier-one markets and inland expansion zones.
Yangtze River Delta
Shanghai anchors replacement demand as property developers specify heat-pump washer-dryer combos for new luxury residential towers. SAMR energy labeling enforcement accelerates turnover of pre-2018 washing machine stock. Suzhou and Hangzhou manufacturing clusters supply compact front-load platforms engineered for 90-square-meter apartment footprints.
Pearl River Delta
Shenzhen and Guangzhou drive premium smart appliance adoption through rental housing operator procurement at Vanke and Longfor. MIIT's phased GB 12021.4 implementation forces compressor redesigns for export-oriented factories in Dongguan. Local distribution networks penetrate third-tier satellite cities across Guangdong province.
Beijing-Tianjin-Hebei
Dual carbon goals pressure municipal governments to mandate tier-one water efficiency ratings in public housing retrofits. SAMR certification bottlenecks delay product launches for manufacturers without established Beijing testing relationships. Tianjin port logistics advantage supports inbound refrigerant supply for thermal pump dryer assembly.
Sichuan-Chongqing
Western inland expansion targets underpenetrated urban populations in Chengdu and Chongqing with standardized six-kilogram drum platforms. Provincial utility rebate programs pull demand toward MIIT-certified energy-efficient models. Local electrical infrastructure limitations in legacy residential blocks constrain high-capacity front-load deployment.
Shandong Peninsula
Qingdao-based manufacturing anchors domestic supply chains for drum and motor components serving national distribution networks. Shandong province's industrial base supports captive steel and copper sourcing for cost-competitive assembly. Jinan municipal procurement specifications increasingly mirror SAMR ESG labeling criteria for rental housing fleets.
China Laundry Appliances Market Competitive Environment
Chinese producers anchor volume-tier supply; Korean and European specialists hold premium positioning through thermal pump technology licensing. The vendor base stratifies across three tiers: integrated conglomerates with captive component manufacturing, mid-scale specialists focused on compact urban formats, and import-reliant premium brands serving high-end retail channels. Dominant competitive moves include backward integration into compressor production and direct sales negotiations with property developers bypassing traditional distributor markups.
Within the integrated conglomerate tier, Haier Group and GD Midea Holding Co Ltd exemplify scale-driven market presence through manufacturing breadth and distribution depth. Hisense Group occupies a specialist position in compact front-load systems. These three anchors demonstrate how domestic players leverage proximity to MIIT regulatory processes and SAMR certification timelines against multinational competitors facing extended compliance cycles.
| Leading Market Players |
|---|
| GD Midea Holding Co Ltd |
| Haier Group |
| Whirlpool |
| Samsung Electronics |
| LG Electronics |
| Electrolux |
| Panasonic Corp |
| Bosch |
| Hisense Group |
| Others |
Value Chain & Pricing Dynamics
Captive compressor manufacturing among Haier Group and GD Midea Holding Co Ltd anchors both supply security and pricing power against multinational rivals facing extended SAMR certification cycles. This backward integration into thermal system production shields domestic leaders from refrigerant cost volatility while compressing margin buffers for import-reliant premium brands.
Pricing Analysis
Volume-tier washing machines trade on thin per-unit margins while washer-dryer combos capture premium positioning through space-constrained engineering. Three-tier pricing structure across premium, standard, and economy levels separates SAMR tier-one certified models from baseline efficiency ratings. Cost compression in entry-level segments is intensifying because copper and steel input volatility erodes drum assembly profitability. Rental housing operators exhibit lowest price sensitivity due to subscription bundling, whereas third-tier city retail channels remain highly elastic.
Supply Chain Analysis
Reverse-logistics networks for end-of-life machine recovery remain underdeveloped, constraining circular material flows for steel drum reclamation. Component sourcing concentrates in China, South Korea, and Japan for compressor motors and control systems. Thermal pump architectures draw from constrained refrigerant imports subject to MEE discharge scrutiny. Single-source vulnerability in low-GWP refrigerant supply creates procurement risk for dryer assembly lines. Distribution runs through manufacturer-direct negotiations with property developers alongside traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with captive component production and MIIT regulatory proximity, as accelerated GB standard revisions force weaker players into compliance cost distress.
For Market Incumbents: Cement supply agreements with Vanke and Longfor through standardized fleet specifications that lock out fragmented competitors. Deepen captive compressor manufacturing to offset refrigerant import exposure. MIIT's phased GB 12021.4 implementation threatens product line obsolescence for manufacturers without parallel redesign capacity. For New Entrants and Emerging Players: SAMR's mandatory energy labeling convergence with property manager ESG criteria in China opens a window for premium smart appliance positioning against legacy volume players. Target rental housing operator procurement in Hangzhou and Suzhou where subscription models displace retail fragmentation. Lead with IoT-enabled predictive maintenance as the differentiated service layer. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated conglomerates seeking compact front-load engineering capabilities and MIIT certification relationships. Long-term viability favors targets with established SAMR testing partnerships and thermal pump R&D pipelines. Monitor refrigerant supply license approvals as the inflection signal for dryer segment profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive thermal system production shields margins from refrigerant cost volatility and import constraints. |
| Direct Sales Negotiations with Property Developers | Bulk fleet procurement bypasses retail markup concentration and locks in multi-year service contracts. |
| Smart Appliance Platform Development | IoT firmware enables usage-based revenue streams and predictive maintenance alerts for rental operators. |
| GB 12021.4 Compliance Pre-Certification | Early SAMR submission secures market access before accelerated standard withdrawals take effect. |
| Third-Tier City Distribution Network Expansion | Logistics depth in Sichuan and Shandong provinces captures underpenetrated replacement demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with appliance manufacturing executives, property development procurement managers, MIIT certification consultants, and rental housing fleet operators. SAMR energy labeling databases, MIIT GB standard revision notices, and China Customs import records provided validation anchors. Bottom-up demand modeling from regional construction permits and replacement cycle data triangulated against top-down manufacturer shipment disclosures.
Granularity-level modeling deployed product-type splits across washing machines, washer-dryer combos, and thermal pump dryers; technology tiers separating front-load, top-load, and smart-connected platforms; and channel segmentation between direct developer sales and retail distribution. CAGRs were derived from regression analysis against urban residential construction permits and MIIT efficiency mandate implementation schedules. Heat-pump adoption curves and refrigerant supply constraints shaped dryer segment projections.
The model assumes a particular technology adoption path; alternative pathways for thermal pump efficiency breakthroughs would alter the outlook for compressor redesign investment cycles. Forecasts reflect assumptions around MIIT regulatory timeline adherence and rental housing operator procurement concentration. Practitioners should monitor SAMR certification bottleneck reports and low-GWP refrigerant import license approvals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
United States Major Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Range Hood Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
Built-In Hobs Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Merchandizing Refrigerators Market