
 United Arab Emirates Floor Covering Market | 2026-2036
United Arab Emirates Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Floor Covering Market Analytics
Hospitality sector procurement is restructuring the United Arab Emirates floor covering landscape as hotel and resort developers specify premium hard surfaces over traditional broadloom. RAK Ceramics leverages its Ras Al Khaimah manufacturing base to anchor supply for mega-project timelines across the emirates. Floorworld LLC competes through specialized project execution capabilities in the commercial fit-out segment. Al Khaleej Ceramics Co LLC sustains its position via deep distribution control across northern emirate construction channels.
Floor covering encompasses finished surface materials installed over structural subfloors to provide wear resistance, acoustic performance, and aesthetic finish in built environments. Technical specifications span PEI abrasion ratings for ceramic tiles, wear-layer thickness measured in mils for vinyl products, and density ratings above 50 ounces per square yard for commercial-grade carpets. Tiles dominate value capture in the product type dimension due to thermal resilience suited to Gulf climates and preference across institutional buyers. Carpets retain share in hospitality guest rooms and executive office settings where acoustic dampening and underfoot comfort carry premium weight. The click-lock installation category grows fastest as dry-laid systems reduce skilled-labor dependency and accelerate project completion cycles.
MOHAP mandates fire-resistance classifications for interior finishes in healthcare and hospitality buildings, while Dubai Municipality enforces green building standards that restrict formaldehyde emissions in laminate and engineered wood products. The Emirates Authority for Standardization and Metrology (ESMA) administers UAE-specific conformity schemes that govern product labeling and performance claims for imported floor coverings. Stakeholders must monitor evolving procurement criteria from master developers as sustainability-linked financing instruments increasingly tie contractor selection to material traceability and embodied carbon documentation.
Market Dynamics
Hospitality procurement restructuring around large-format porcelain and engineered surfaces is compressing traditional broadloom timelines and rewiring supplier qualification criteria across the emirates.
Growth Catalysts
- Dubai Municipality green building regulations:Tightening VOC emission thresholds for interior finishes are mandating low-formaldehyde laminate and engineered wood products in new commercial developments.
- Healthcare facility expansion:MOHAP fire-resistance classifications for interior finishes are driving specification of PEI-rated ceramic tiles in hospital and clinic construction.
- Click-lock installation systems:Dry-laid flooring methods are reducing skilled-labor dependency and accelerating project completion cycles in high-volume residential towers.
Market Restraints
- Raw material import concentration:Ceramic tile production depends on clays and frits sourced from specific overseas quarries, exposing margins to shipping cost volatility.
- Skilled installer scarcity:Traditional mortar-set tile work requires certified craftsmen whose training pipelines lag behind project ramp rates.
- Substitution pressure from polished concrete:Industrial and logistics facilities are specifying seamless concrete finishes that eliminate material cost and installation layers entirely.
Strategic Opportunities
- Abu Dhabi cultural district pipeline:Museum and performing arts venues are specifying acoustic-engineered flooring systems with integrated underlayment for performance halls.
- ESMA conformity scheme expansion:Enhanced product labeling and performance claim verification is creating first-mover advantage for documented supply chain transparency.
- Digital specification platforms:BIM-integrated material libraries are enabling direct architect-to-manufacturer engagement that bypasses traditional distributor markup layers.
Industry Challenges
- Certification timeline compression:ESMA testing protocols and MOHAP fire-rating approvals are extending product launch lead times for imported flooring systems.
- Legacy inventory obsolescence:Stocked broadloom and vinyl sheet goods face write-down pressure as project specifications pivot to hard surfaces with shorter design cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Floor Covering Market |
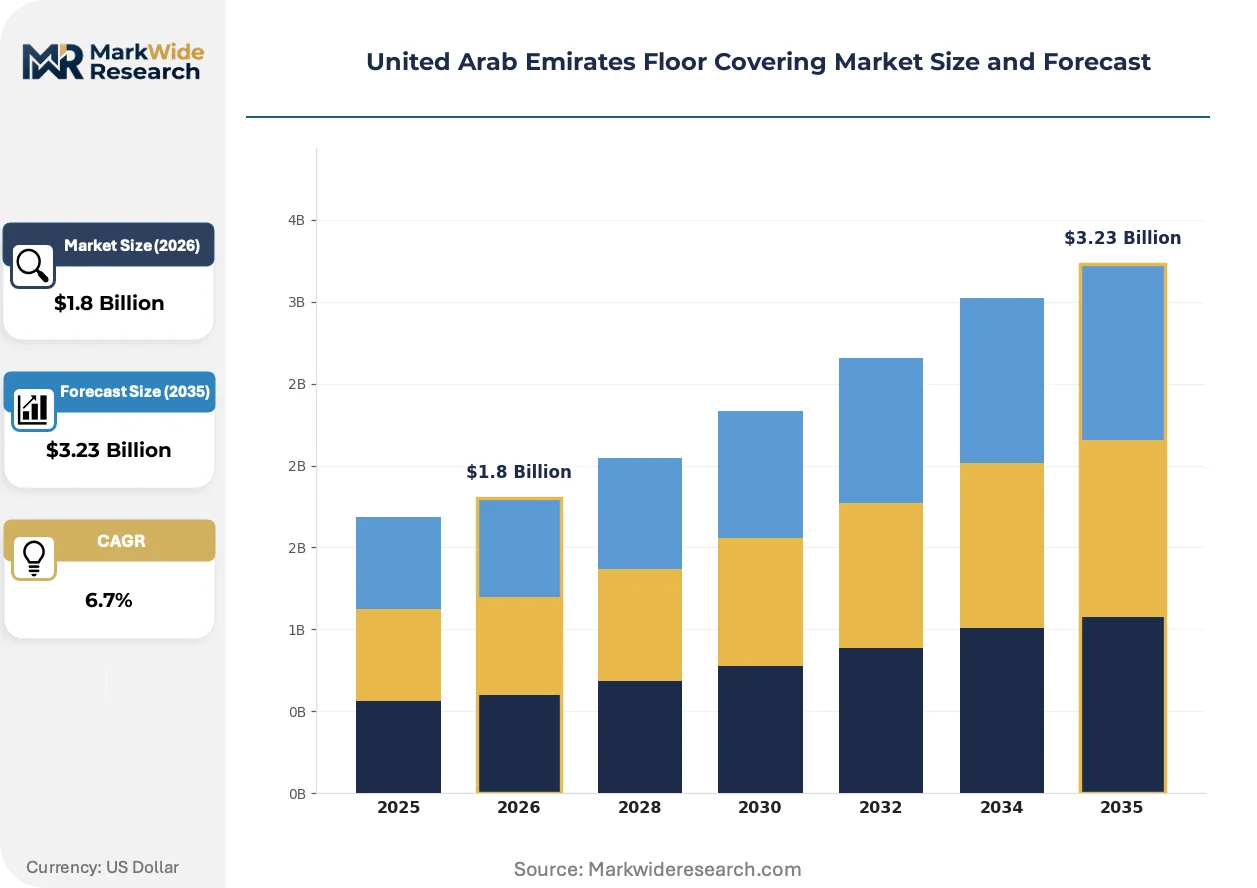
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Tiles, Laminates, Vinyl Installation Type: Glue-Down, Click-Lock, Staple, Loose-Lay Material: Wool, Synthetic Fibers, Hardwood, Bamboo End User: Commercial, Residential, Industrial, Hospitality |
| Companies Covered | RAK Ceramics, Carpet Land, AB Gustaf Kahr, Emirates Ceramic, Terrazzo, Floorworld LLC, Al Khaleej Ceramics Co LLC, TOLI Corporation, Carpetland LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Floor Covering Market Evolving Landscape
Material science advances and digital specification tools are compressing traditional procurement cycles while embedding performance documentation deeper into product selection workflows.
Large-format thin porcelain slabs are converging with digital printing technology to deliver stone-mimicking surfaces at reduced weight and installation cost. Hospitality developers across Dubai's commercial corridor are specifying these panels for lobby and amenity spaces where seamless aesthetics and thermal resilience matter. This convergence is compressing demand for natural stone imports while elevating local manufacturing value capture.
MOHAP building safety codes now mandate fire-resistance testing for all interior finishes in healthcare and hospitality occupancies. The industrial consequence is a bifurcation between certified product lines and general inventory that cannot access institutional procurement channels. Healthcare vertical buyers are responding by consolidating vendor lists to suppliers with pre-approved testing documentation.
Architect specification behavior is migrating from physical sample libraries to cloud-based material databases with embedded carbon accounting. Engineering consultancies in Abu Dhabi's cultural district are disqualifying products without embodied carbon documentation from shortlists. This shift is most visible in trophy projects where sustainability-linked financing instruments tie contractor selection to material traceability.
United Arab Emirates Floor Covering Market Segmentation
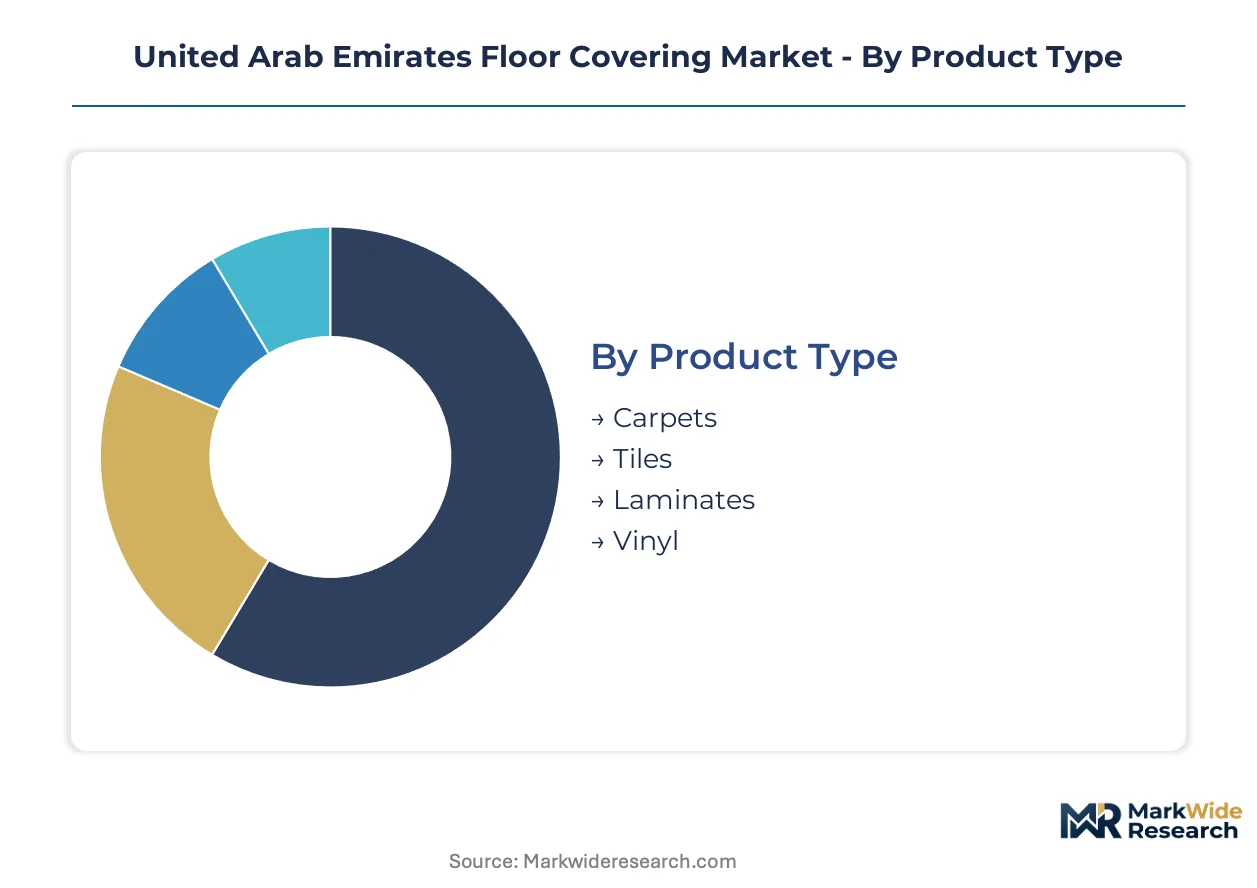
Segmentation in the UAE floor covering market reveals how procurement criteria diverge across institutional buyers, installation methods, and climate-specific material performance. Understanding these splits exposes where specification power concentrates and where supplier margins compress.
Product Type:
Integration depth varies sharply: tiles function as standalone structural finishes, while carpets and resilient flooring require integrated underlayment systems to meet performance specs.
- Tiles:Ceramic and porcelain compositions deliver PEI abrasion ratings above 4, suited to high-traffic commercial corridors. Dubai's hospitality developers specify large-format thin porcelain for lobby seamlessness, though thermal mass demands precise substrate preparation in Gulf climates.
- Carpets:Broadloom and modular tile systems incorporate primary and secondary backing layers with density ratings above 50 ounces per square yard for commercial grades. Abu Dhabi's cultural district venues prioritize acoustic-engineered broadloom for performance halls, compressing demand for standard hospitality guest room installations.
- Laminates:HDF core boards with aluminum oxide wear layers satisfy residential cost constraints but face MOHAP formaldehyde emission scrutiny in institutional channels.
- Vinyl:LVT and sheet goods with 20-mil wear layers dominate healthcare retrofits where moisture resistance and rapid installation matter.
Tiles lead volumes today; vinyl is gaining share fastest through healthcare and education retrofits.
Installation Type:
Cost tier separation runs deepest here: dry-laid systems reduce skilled labor dependency while adhesive methods lock in premium pricing for certified installer networks.
- Glue-Down:Full-spread adhesive application for sheet vinyl and broadloom delivers maximum dimensional stability in high-moisture environments. Dubai Municipality specifications mandate this method for healthcare sterile zones, though curing timelines extend project schedules.
- Click-Lock:Mechanical joining systems for LVT and laminate planks enable floating installations without subfloor penetration. Residential tower developers across Sharjah and Ajman specify click-lock to accelerate unit turnover and reduce skilled craftsman dependency.
- Staple:Traditional carpet attachment to wooden tack strips persists in villa residential segments where concrete substrate prevalence limits applicability.
- Loose-Lay:Friction-based vinyl systems with fiberglass backing allow rapid deployment and reconfiguration, favored in temporary exhibition and event spaces.
Click-Lock is climbing the fastest as dry-laid methods displace mortar-set timelines in volume residential.
Material:
Supply concentration determines margin structure: wool and hardwood depend on concentrated import channels, while synthetic fibers and bamboo offer localized sourcing alternatives.
- Wool:Natural fiber carpets with inherent flame resistance and acoustic absorption command premium positioning in luxury hospitality and executive office segments.
- Synthetic Fibers:Nylon and polypropylene formulations dominate commercial carpet tile production through solution-dyed colorfastness and stain resistance, capturing institutional procurement at standard tier pricing.
- Hardwood:Engineered oak and teak products face Dubai Municipality green building restrictions on tropical hardwood sourcing, compressing specification to FSC-certified alternatives.
- Bamboo:Rapid-renewable grass-based flooring with hardness ratings exceeding northern hardwoods attracts sustainability-linked financing projects requiring embodied carbon documentation.
Synthetic fibers anchor volume throughput; bamboo shows steepest expansion trajectory on sustainability credential requirements.
End User:
Customer type segmentation maps directly to specification authority concentration: master developers control commercial and hospitality procurement, while fragmented residential buyers prioritize cost and speed.
- Commercial:Office and retail fit-outs specify hard surfaces for durability and maintenance efficiency, with Dubai International Financial Centre towers driving large-format porcelain demand.
- Residential:Villa and apartment segments split between click-lock laminates for investor-grade units and engineered hardwood for owner-occupied premium developments.
- Industrial:Logistics and manufacturing facilities increasingly specify polished concrete or epoxy systems that eliminate material layers entirely, pressuring traditional flooring suppliers.
- Hospitality:Hotel and resort developers restructure procurement around large-format porcelain for public areas and acoustic-engineered carpet for guest rooms, with MOHAP fire-resistance classifications filtering vendor qualification.
Commercial dominates value capture; hospitality is expanding most quickly on mega-project pipeline density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's commercial corridor anchors the emirates' floor covering demand through hospitality mega-projects and financial district expansions. Abu Dhabi's cultural district pipeline and Sharjah's residential tower density create complementary consumption nodes. MOHAP building safety codes and Dubai Municipality green building regulations govern specification standards across all emirates.
Dubai
Hospitality procurement restructuring concentrates in Dubai's commercial corridor where hotel developers specify large-format porcelain for lobby and amenity spaces. Dubai Municipality enforces green building standards that restrict formaldehyde emissions in laminate and engineered wood products. Dubai International Financial Centre towers drive specification of PEI-rated ceramic tiles for high-traffic commercial corridors.
Abu Dhabi
Museum and performing arts venues in the cultural district specify acoustic-engineered flooring systems with integrated underlayment for performance halls. MOHAP mandates fire-resistance classifications for interior finishes in healthcare facility expansions across the emirate. Saadiyat Island and Al Maryah Island developments concentrate premium hard surface procurement for trophy projects.
Sharjah
Residential tower developers specify click-lock LVT and laminate systems to accelerate unit turnover and reduce skilled craftsman dependency. The emirate's cost-sensitive construction market favors dry-laid installation methods over traditional mortar-set timelines. Industrial zones in Hamriyah and Al Sajaa specify polished concrete for logistics facilities, eliminating material layers entirely.
Ras Al Khaimah
RAK Ceramics leverages its Ras Al Khaimah manufacturing base to anchor supply for mega-project timelines across all emirates. The emirate's industrial free zones attract ceramic tile production through proximity to raw material import channels. Northern emirate distribution networks radiate from Ras Al Khaimah to serve Ajman, Umm Al Quwain, and Fujairah construction markets.
Ajman and Northern Emirates
Affordable residential segments in Ajman, Umm Al Quwain, and Fujairah prioritize cost-optimized vinyl sheet goods and entry-grade laminates. Al Khaleej Ceramics Co LLC sustains distribution control across these northern emirate construction channels. Infrastructure investment lags behind Dubai and Abu Dhabi, compressing specification tiers toward standard-grade materials.
United Arab Emirates Floor Covering Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers restructure product mixes around hard surface growth and compress broadloom exposure. The vendor base spans integrated ceramic manufacturers, specialized flooring distributors, and regional project execution specialists. Three archetypes anchor competitive positioning: manufacturing-integrated players with captive production, distribution-heavy operators with deep channel control, and project-centric specialists with fit-out execution capabilities. M&A activity and capacity expansion in large-format porcelain represent the dominant competitive moves.
Within the manufacturing-integrated tier, RAK Ceramics exemplifies production-scale supply anchoring for mega-project timelines. Among distribution-focused operators, Floorworld LLC and Al Khaleej Ceramics Co LLC occupy positions emphasizing channel depth and project execution capabilities respectively. These three companies represent the structural segmentation between production gravity, distribution control, and specialized service delivery that characterizes the emirates' competitive terrain.
| Leading Market Players |
|---|
| RAK Ceramics |
| Carpet Land |
| AB Gustaf Kahr |
| Emirates Ceramic |
| Terrazzo |
| Floorworld LLC |
| Al Khaleej Ceramics Co LLC |
| TOLI Corporation |
| Carpetland LLC |
| Others |
Value Network & Pricing Analysis
Clay and frit import costs from Italian and Spanish quarries cascade through ceramic tile pricing tiers, compressing margins at the standard-grade level while premium large-format porcelain commands project-specific premiums from Dubai hospitality developers.
Pricing Analysis
Distributor markup layers separate manufacturer ex-factory pricing from installed project costs, with project-based contract structures dominating mega-developer procurement. Price differentiation stems from ESMA certification status and volume scale, with MOHAP fire-rated products capturing premium positioning over general inventory. Cost compression in entry-grade laminates intensifies as Sharjah residential developers prioritize click-lock speed over material specifications. Specifier buyers in Abu Dhabi's cultural district exhibit lowest price sensitivity, while northern emirate residential contractors drive hardest bargain terms.
Supply Chain Analysis
Refurbishment flows remain minimal as worn ceramic and porcelain tiles lack economically viable reprocessing pathways, diverting end-of-life material to construction debris streams rather than circular recovery. Raw material sourcing draws from Italy, Spain, and India for ceramic frits and clays, while synthetic fiber carpet production hinges on petrochemical feedstocks from Saudi and Qatari suppliers. Single-source vulnerability concentrates in specialized PEI-rated glaze formulations from European producers. Distribution runs through Ras Al Khaimah manufacturing hubs radiating to emirate-level project sites via contractor-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in large-format porcelain as hospitality procurement shifts toward hard surfaces, while click-lock installation methods reduce labor cost exposure in volume residential segments.
For Market Incumbents: Acquire ceramic pressing and digital printing capacity to anchor supply security for Dubai mega-project timelines. Consolidate distributor relationships in northern emirates before Al Khaleej Ceramics extends channel lock-in. Counter polished concrete substitution threat by embedding performance warranties into project specifications. For New Entrants and Emerging Players: Begin with acoustic-engineered flooring systems targeting Abu Dhabi museum and performing arts venues where specification authority concentrates with engineering consultancies. Exploit ESMA conformity scheme gaps by building pre-certified product documentation ahead of incumbent legacy inventory transitions. Pursue architect-direct engagement through BIM-integrated material libraries that bypass established distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale advantages intersect with sustainability-linked financing requirements that demand embodied carbon documentation. Five-to-ten year viability favors integrated producers with captive raw material processing over pure distribution plays. Target acquisition archetype: mid-cap ceramic manufacturers with PEI-rated product lines and established MOHAP testing relationships. Monitor ESMA protocol expansion timelines as inflection signal for certification-premium capture windows.| Strategic Initiative | Industry Significance |
|---|---|
| Large-Format Porcelain Capacity Expansion | RAK Ceramics and integrated producers capture hospitality procurement restructuring toward seamless lobby surfaces. |
| ESMA Certification Pre-Investment | First-mover documentation advantage opens institutional procurement channels closed to general inventory competitors. |
| Backward Integration into Digital Printing | In-house stone-mimicking surface production reduces import dependency and compresses design-to-delivery cycles. |
| BIM-Integrated Specification Platform Launch | Direct architect engagement bypasses Floorworld LLC distributor markup layers in commercial fit-out segments. |
| Acoustic-Engineered System Development | Abu Dhabi cultural district venues specify integrated underlayment for performance hall sound isolation requirements. |
Research Methodology
Bottom-up project pipeline modeling reconciled against top-down import customs tracking forms the analytical core of this study. Primary interviews with hospitality procurement directors, healthcare facility planners, ceramic plant operations managers, and commercial contractor estimators combined with secondary validation against Dubai Municipality building permit databases, ESMA conformity registration records, and MOHAP fire-rating certification lists. Trade flow analysis from UAE customs authorities and Ras Al Khaimah free zone production statistics anchored supply-side calibration.
Historical trendline analysis across ceramic tile, carpet, and resilient flooring demand patterns informed projection frameworks over the analysis window. Segmentation dimensions modeled include product type, installation method, material composition, and end-user vertical with regional emirate splits. CAGRs derived from fitted growth curves applied to project-based contract values and unit installation volumes. Climate-specific performance requirements and green building regulatory evolution served as scenario inputs.
Several conditions sit outside the modeled scope, including potential relaxation of MOHAP fire-resistance mandates, abrupt shipping cost dislocations affecting Italian frit imports, and accelerated polished concrete adoption in industrial segments. Forecasts reflect assumptions regarding mega-project timeline continuity and ESMA protocol implementation pace. Practitioners should monitor Dubai Municipality green building regulation amendments and master developer sustainability procurement criteria for early signals of specification pivot intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Flooring Market