
 North America Smokeless Indoor Grills Market | 2026-2036
North America Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smokeless Indoor Grills Market Insights
Specialty kitchen retail is narrowing as direct-to-consumer platforms and big-box partnerships capture larger order volumes. SharkNinja Operating LLC leverages its infomercial infrastructure to sustain impulse-driven purchases, while Hamilton Beach anchors shelf presence through mass-merchant relationships. Breville differentiates via premium stainless-steel construction and precision temperature control.
North America smokeless indoor grills are electrically powered cooking appliances that use infrared heating elements or concealed coils to generate temperatures between 350°F and 450°F while channeling grease into water-filled drip trays to suppress smoke emissions. These units serve residential kitchens and commercial foodservice operations where open-flame cooking is restricted by building codes or ventilation limitations. Electric grills lead product-type revenue due to lower price points and simpler maintenance, though infrared variants command stronger margins among performance-focused buyers. Stainless steel dominates material selection for durability perception, while non-stick coating surfaces attract replacement demand from convenience-oriented home users.
The US Consumer Product Safety Commission and Health Canada's Product Safety Program enforce electrical safety and surface temperature standards that determine market access for imported units. California's Title 24 building efficiency standards and evolving municipal fire codes in Chicago and New York City further constrain permissible wattage and housing materials for multi-unit dwellings. Stakeholders must monitor how municipal electrification mandates and evolving indoor air quality ordinances reshape product certification requirements across Canadian provinces and US states.
Market Dynamics
California's Title 24 building efficiency standards and New York City's evolving fire codes are compressing permissible wattage ranges for multi-unit residential cooking appliances, forcing manufacturers to redesign thermal management systems for dense urban housing stock.
Growth Catalysts
- EPA Indoor Air Quality Guidelines:Federal pressure on particulate emissions from residential cooking appliances accelerates adoption of water-tray grease suppression systems in apartment buildings across Chicago and Boston.
- Infrared Heating Elements:Precision temperature control technology attracts performance-focused home cooks seeking sear quality without open-flame ventilation requirements.
- Texas Extended Grilling Seasons:Subtropical climate patterns sustain replacement cycles for electric units in Houston and Dallas metro areas where outdoor grilling remains impractical during humid summer months.
Market Restraints
- Copper Coil Supply Concentration:Electrical component sourcing depends heavily on Mexican manufacturing clusters, exposing assemblers to cross-border tariff volatility and logistics bottlenecks at Laredo entry points.
- Wattage Ceiling Constraints:Chicago municipal electrical codes cap residential appliance draw at 1,500 watts for units without dedicated 20-amp circuits, limiting high-performance infrared variants in vintage housing stock.
- Outdoor Grill Substitution:Propane and natural gas patio units retain cost-per-cooking-hour advantages for single-family homeowners with yard access, constraining electric indoor penetration in suburban markets.
Strategic Opportunities
- Canadian Provincial Electrification Mandates:British Columbia and Quebec building efficiency programs incentivize electric cooking appliance retrofits in rental housing, creating subsidy-aligned distribution partnerships with provincial utilities.
- Smart Home Integration:WiFi-enabled temperature logging and recipe-guided cooking cycles converge with connected kitchen ecosystems, opening premium positioning through interoperability with Amazon Alexa and Google Home platforms.
- Commercial Foodservice Niches:Ghost kitchen operators and hotel breakfast buffets in Toronto and Vancouver seek compact, code-compliant grilling stations for menu expansion without HVAC infrastructure investment.
Industry Challenges
- UL Certification Timelines:Surface temperature testing and electrical safety validation from Underwriters Laboratories extends product launch windows by four to six months for new housing material combinations.
- Non-Stick Coating Supply Reconfiguration:PFAS-free ceramic alternatives require reformulation of supplier relationships and requalification of FDA-compliant food-contact surfaces, disrupting established procurement patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smokeless Indoor Grills Market |
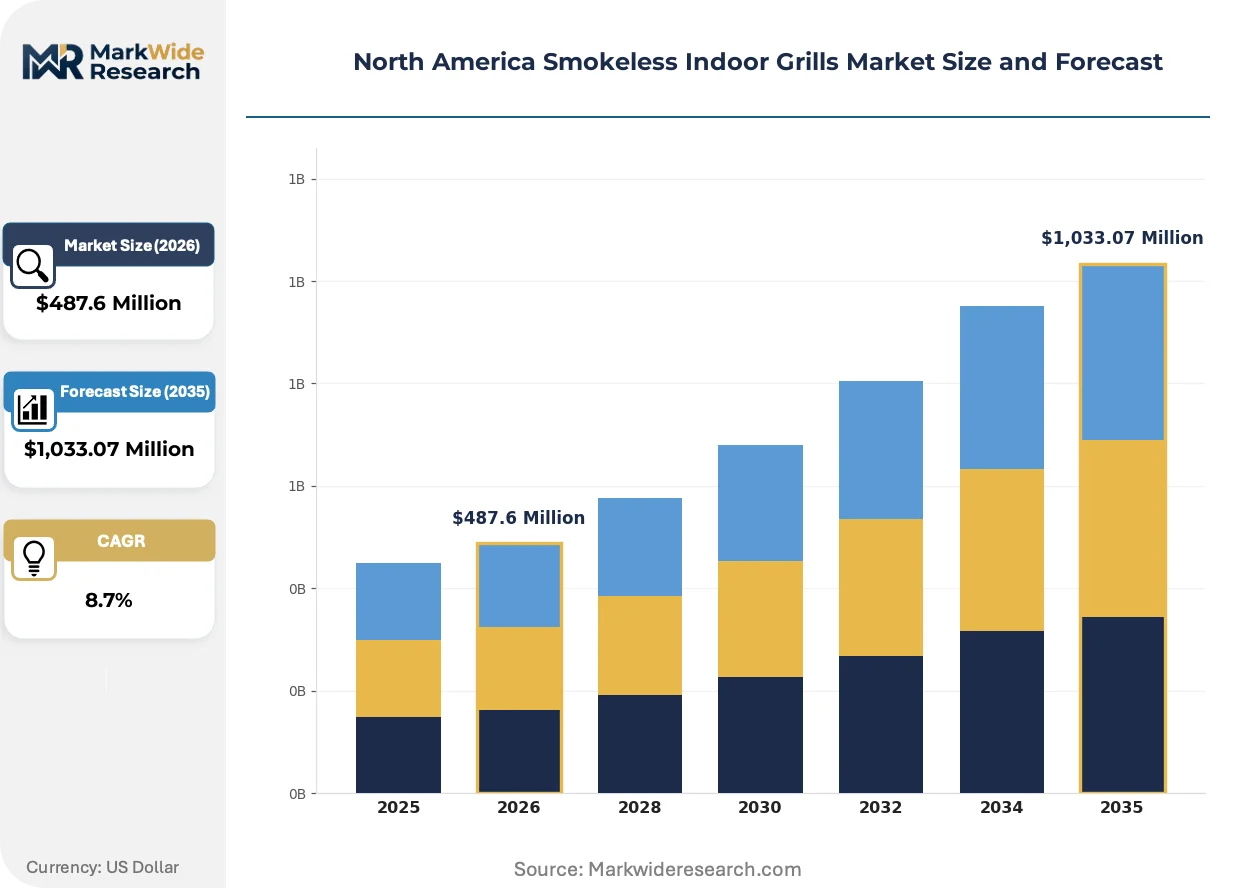
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Infrared Grills, Carbonized Grills, Hybrid Grills Material: Stainless Steel, Cast Iron, Aluminum, Non-Stick Coating Size: Compact, Medium, Large, Extra Large End User: Home Users, Restaurants, Caterers, Food Trucks |
| Companies Covered | Cuisinart, SharkNinja Operating LLC, Hamilton Beach, Spectrum Brands Holdings, Inc., Weber-Stephen Products LLC, Ninja Kitchen, Breville, DeLonghi America Inc., Philips, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smokeless Indoor Grills Market Trends and Innovations
Product architecture is bifurcating between stripped-down economy units for price-sensitive apartment renters and sensor-rich premium platforms for culinary enthusiasts, with the middle tier losing shelf space at specialty retailers.
Infrared quartz heating elements is collapsing the performance gap between electric indoor units and open-flame outdoor grills. Enthusiast home cooks in Austin and Denver metro areas are upgrading from concealed-coil entry models at twice the replacement velocity of prior cycles. The technology is compressing acceptable price ceilings upward while marginalizing basic resistive heating configurations in mass-merchant assortments.
Health Canada's Product Safety Program tightened surface temperature limits for accessible housing units in Ontario and Alberta, effective for all imports after January regulatory filing deadlines. Manufacturers must now embed redundant thermal cutoffs and insulated housing layers that add material cost without visible consumer benefit. Compact electric grill lines destined for senior living and subsidized housing developments face the steepest compliance burden and longest redesign cycles.
Appliance purchasing through builder and property management procurement channels is fragmenting traditional retail volume. Multi-family developers in Phoenix and Atlanta specify smokeless grills as standard amenity packages in new lease-up buildings, bypassing big-box and direct-to-consumer pathways entirely. This channel shift concentrates annual contract value with fewer buyers wielding steeper discount negotiating leverage.
North America Smokeless Indoor Grills Market Segmentation
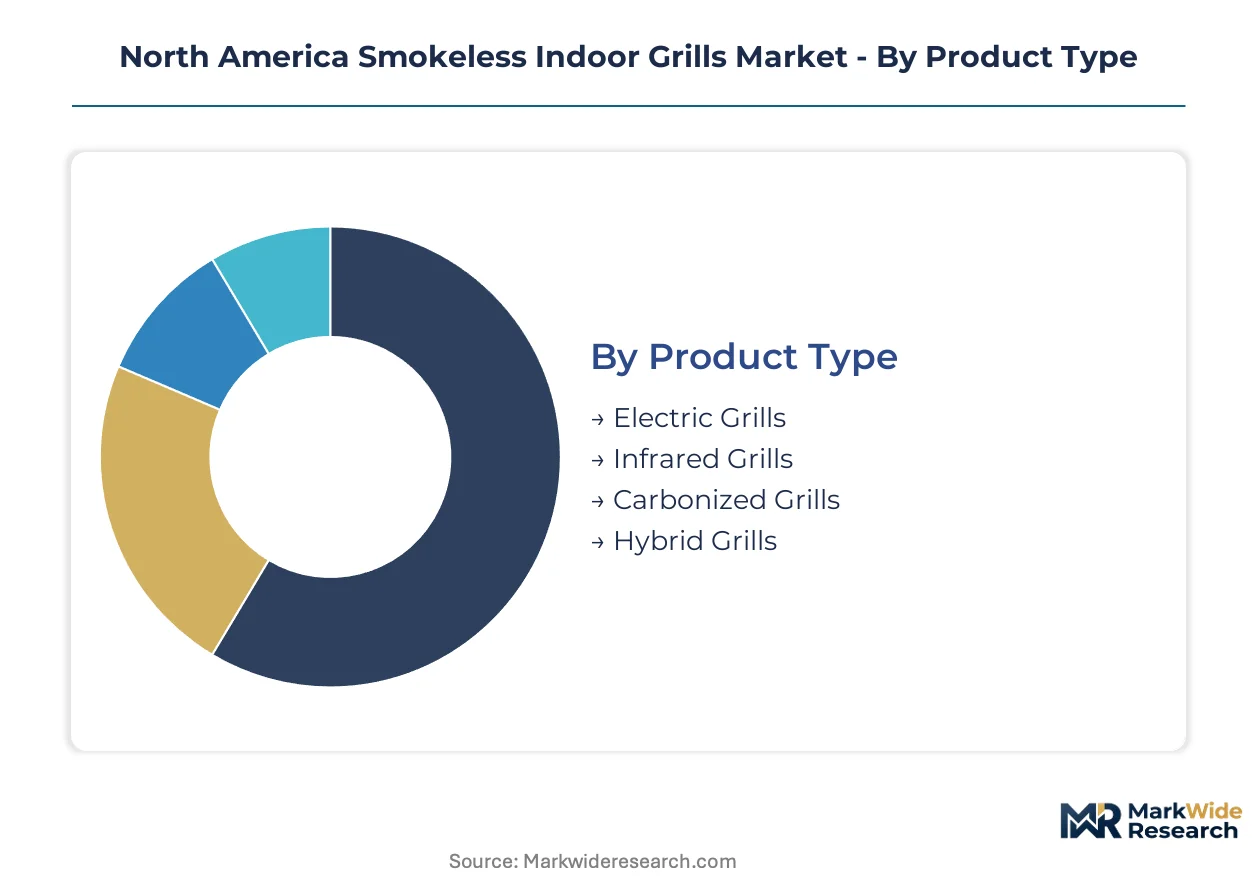
Segmentation in North America smokeless indoor grills reveals how urban housing constraints, commercial kitchen codes, and material preferences fragment purchasing behavior. Each dimension exposes distinct margin structures and certification burdens that shape manufacturer portfolio strategy.
Product Type:
Residential kitchens and commercial foodservice operations deploy fundamentally different heating architectures based on ventilation access and duty-cycle intensity.
- Electric Grills:Concealed resistive coils generate 350°F to 450°F through direct element contact with cooking surfaces. Apartment dwellers in Chicago and Boston favor these units for Title 24 compliance and simple drip-tray maintenance.
- Infrared Grills:Quartz elements deliver radiant heat with precision temperature modulation, cutting preheat intervals by half versus coil systems. Performance-focused home cooks in Austin and Denver upgrade to these units at accelerated replacement velocities.
- Carbonized Grills:Charcoal pellet systems with electric ignition satisfy smoke-ordinance exemptions in Texas jurisdictions permitting solid-fuel cooking with adequate suppression.
- Hybrid Grills:Dual-mode architectures switch between electric and carbonized operation, appealing to suburban homeowners seeking seasonal flexibility without multiple appliance purchases.
Established volume favors electric grills; emerging adoption favors infrared grills.
Material:
Surface composition determines thermal mass, cleaning protocol, and regulatory compliance burden across residential and commercial installations.
- Stainless Steel:304-grade construction dominates commercial foodservice specifications in Toronto and Vancouver for corrosion resistance and dishwasher-safe maintenance cycles.
- Cast Iron:Dense thermal mass retains sear temperatures across batch cooking sequences. Caterers in Houston and Dallas specify these grates for high-volume protein preparation.
- Aluminum:Lightweight die-cast housings reduce shipping costs for direct-to-consumer channels targeting single-person households in Manhattan studio apartments.
- Non-Stick Coating:PFAS-free ceramic formulations now replace legacy PTFE surfaces following Health Canada food-contact requalification deadlines.
Commercial procurement anchors stainless steel; residential replacement cycles are climbing fastest for non-stick coating.
Size:
Countertop footprint and cooking-surface area correlate directly with housing type and household composition across North American metros.
- Compact:Under-12-inch widths fit galley kitchens in San Francisco and Vancouver high-rises where square footage commands premium rents.
- Medium:14-to-16-inch surfaces serve two-to-four-person households in Austin and Denver townhomes with dedicated appliance garages.
- Large:18-to-20-inch configurations accommodate family meal preparation in suburban Phoenix and Atlanta single-family homes.
- Extra Large:Commercial-grade surfaces exceed 24 inches for ghost kitchen operators in Los Angeles and Toronto seeking menu expansion without hood installation.
Compact units dominate unit shipments; extra large formats are expanding most quickly in commercial channels.
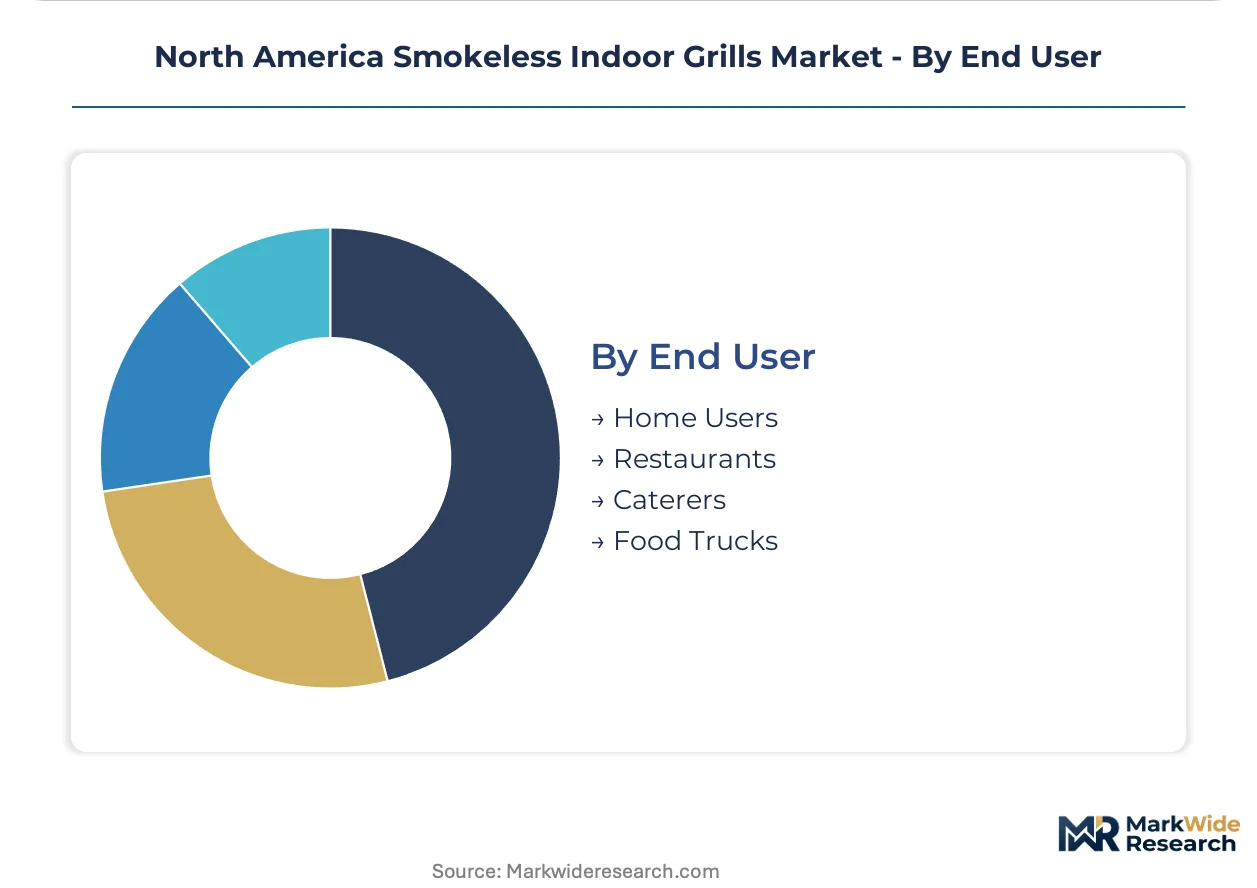
End User:
Purchasing authority and use-case intensity separate consumer replacement cycles from commercial procurement negotiations.
- Home Users:Individual households drive seasonal replacement patterns, with California and Texas accounting for disproportionate order volume due to extended grilling seasons and dense housing stock.
- Restaurants:Full-service operators in Chicago and New York City specify UL-certified units for back-of-house protein preparation where municipal fire codes prohibit open flames.
- Caterers:Mobile foodservice providers in Houston and Dallas demand rapid-heating infrared platforms for off-site event execution without permanent ventilation infrastructure.
- Food Trucks:Space-constrained operators in Los Angeles and Toronto prioritize compact electric units with generator-compatible draw below 1,500 watts.
Home users anchor aggregate volume; food trucks are gaining share fastest among commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in California and Texas outstrips Canadian Prairie provinces by approximately 15-20% due to denser urban housing stock and extended replacement cycles. This asymmetry concentrates manufacturer investment toward US coastal and Sun Belt metros while compressing margin structures in cross-border distribution channels.
United States
Apartment dwellers in Chicago and New York City drive compact electric unit demand under municipal fire codes restricting open-flame cooking. The EPA's indoor air quality guidelines pressure manufacturers toward water-tray grease suppression systems. Los Angeles ghost kitchen operators specify extra-large commercial formats for menu expansion without HVAC infrastructure investment.
Canada
British Columbia and Quebec building efficiency programs incentivize electric cooking retrofits in rental housing developments. Health Canada's Product Safety Program tightened surface temperature limits for accessible housing units in Ontario and Alberta. Toronto and Vancouver commercial foodservice operators anchor stainless steel procurement for corrosion-resistant back-of-house installations.
Mexico
Cross-border manufacturing clusters near Laredo supply copper coils and electrical components to US assemblers. Mexican manufacturing concentration exposes supply chains to tariff volatility and logistics bottlenecks at Texas entry points. Monterrey and Tijuana industrial zones specialize in die-cast aluminum housings for direct-to-consumer lightweight units.
North America Smokeless Indoor Grills Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying heating elements, control modules, and coated surfaces. The vendor base organizes around three strategic archetypes: mass-merchant shelf anchors, direct-to-consumer infomercial operators, and premium culinary equipment specialists. Competitive moves concentrate on big-box partnership expansion and smart home interoperability licensing rather than manufacturing capacity addition.
Among US-based appliance conglomerates, SharkNinja Operating LLC and Hamilton Beach occupy positions spanning mass-market penetration and impulse-driven purchase channels. Breville exemplifies the premium-tier specialist archetype through precision temperature control positioning. These three anchors represent distinct go-to-market vectors: infomercial infrastructure, retail shelf dominance, and stainless steel construction differentiation respectively.
| Leading Market Players |
|---|
| Cuisinart |
| SharkNinja Operating LLC |
| Hamilton Beach |
| Spectrum Brands Holdings, Inc. |
| Weber-Stephen Products LLC |
| Ninja Kitchen |
| Breville |
| DeLonghi America Inc. |
| Philips |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Mexican copper coil manufacturing clusters near Laredo is forcing US assemblers to accept extended payment terms and volume commitments, compressing margins for mid-tier electric grill producers while concentrating pricing power with component suppliers who control thermal element supply.
Pricing Analysis
Customization-premium spreads separate configured-to-order infrared platforms from standard electric coil units by margins reflecting precision temperature control and smart home integration. Three-tier pricing structure across premium, standard, and economy levels anchors on UL certification grade and heating element technology, with brand premium and after-sales service bundling as secondary differentiation. Price erosion runs through economy tiers as direct-to-consumer channels disintermediate specialty retail. Foodservice buyers in Toronto and Vancouver exhibit lowest price sensitivity due to code compliance requirements, while apartment renters in Chicago show highest sensitivity to upfront acquisition cost.
Supply Chain Analysis
Supplier-financing facilities from Monterrey die-cast aluminum producers are extending payment terms to 90 days for US direct-to-consumer brands, easing working capital pressure but embedding dependency. Manufacturing concentrates in Mexico, China, and Vietnam, with copper coils, quartz infrared elements, and PFAS-free ceramic coatings as critical inputs. Single-source vulnerability sits with Mexican thermal component clusters exposed to cross-border tariff volatility. Distribution runs through big-box retail partnerships, direct-to-consumer platforms, and property management procurement channels serving multi-family developer specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America smokeless indoor grills constitute a high-growth disruption as municipal electrification mandates and EPA indoor air quality guidelines eliminate open-flame alternatives in dense urban housing stock.
For Market Incumbents: Pre-empt smart home platform commoditization by securing exclusive interoperability licenses with Amazon Alexa and Google Home ecosystems before connectivity becomes table stakes. Deepen backward integration into quartz infrared element production to defend margin position against Mexican supply concentration. Accelerate UL certification pipelines for PFAS-free ceramic coating formulations ahead of Health Canada requalification deadlines.
For New Entrants and Emerging Players: Ghost kitchen operators in Los Angeles and Toronto represent the most penetrable entry point, as these facilities seek compact grilling stations without HVAC infrastructure investment. Food truck segments in Texas metro areas offer secondary white-space with generator-compatible sub-1,500-watt specifications. Pursue provincial utility partnership structures in British Columbia and Quebec to align with electrification retrofit subsidies.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across infrared platform manufacturing due to redundant thermal cutoff requirements and smart home module integration. Target mid-cap specialists with captive UL certification capabilities and established property management procurement relationships. Watch Health Canada surface temperature limit enforcement in Ontario and Alberta as signal for compliance cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | WiFi-enabled temperature logging converges with Amazon Alexa and Google Home ecosystems. |
| PFAS-Free Coating Transition | Health Canada food-contact requalification deadlines force ceramic formulation supplier reconfiguration. |
| Property Management Channel Development | Multi-family developers in Phoenix and Atlanta specify grills as standard amenity packages. |
| Provincial Utility Partnership Structuring | British Columbia and Quebec electrification programs incentivize electric cooking retrofits. |
| Infrared Element Backward Integration | Captive quartz heating production defends margins against Mexican coil supply concentration. |
Research Methodology
A spread of perspectives from product development engineers at appliance manufacturers, category buyers at mass-merchant retailers, regulatory affairs specialists at Health Canada and the EPA, and procurement directors at multi-family property management firms converged on the working assumptions. Primary interview insights combined with secondary validation from UL certification databases, municipal fire code filings in Chicago and New York City, and customs records of copper coil imports through Laredo. Bottom-up shipment data from direct-to-consumer platforms and top-down housing stock analysis triangulated market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation by heating technology, surface material, countertop footprint, and end-use intensity. CAGRs derived from replacement cycle velocity in California and Texas versus Canadian Prairie provinces, with municipal electrification mandate adoption curves and commercial foodservice code compliance timelines as industry-specific forecast inputs.
Practitioners should monitor cross-border tariff adjustments, Health Canada surface temperature enforcement actions, and smart home platform interoperability standardization for early signals. Forecasts reflect assumptions about regulatory trajectory and technology cost curves; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Dark Store Market
Food Service
Integrated Stove Market
Food Service
US Food Trucks Services Market
Food Service
Foodservice Coffee Market
Food Service
North America Cafes & Bars Market
Food Service
Air Fryer Meal Kits Market
Food Service
Europe Inflight Catering Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Nigeria Food Service Market
Food Service
Indonesia Foodservice Market
Food Service
Meal Voucher Market
Food Service
Stirrers Market
Food Service
North America Online Grocery Delivery Market
Food Service
South Africa Fast Food Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Restaurant Griddle Market