
 China Inflight Catering Market | 2026-2036
China Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
China Inflight Catering Market Outlook
Shanghai Pudong's aviation catering zone is tilting capacity toward automated cold-chain assembly for wide-body fleets. LSG Sky Chefs leverages European-origin galley engineering standards to anchor premium long-haul contracts. Guangzhou Nanland Air Catering Co. Ltd dominates Pearl River Delta routes through captive supply of halal-certified production lines. Newrest International Group SAS competes on offshore oil-platform logistics expertise translated into isolated kitchen protocols.
Inflight catering encompasses the industrial preparation, portion control, and chilled distribution of food and beverage loads meeting aircraft galley dimensional constraints and altitude-adjusted flavor profiles. Production runs through HACCP-certified commissaries where core temperature logging and 4-hour service windows govern dispatch. Full-service contracts command the deepest margin pools as tray-set complexity justifies dedicated kitchen lines, while meal kits represent the fastest-growing segment as low-cost carriers outsource assembly to cut galley labor. Breakfast items retain volume leadership on domestic morning banks, though special meals gain traction from diabetes-specific and religious-diet protocols.
China's SAMR enforces GB 14934 disinfectant standards and real-time traceability codes across aviation food premises. The country's NMPA-aligned allergen labeling rules and MEE packaging waste directives reshape procurement specifications toward compostable serviceware. Stakeholders must decide whether backward integration into cold storage or partnership with third-party logistics networks offers tighter compliance margin against escalating audit frequency.
Market Dynamics
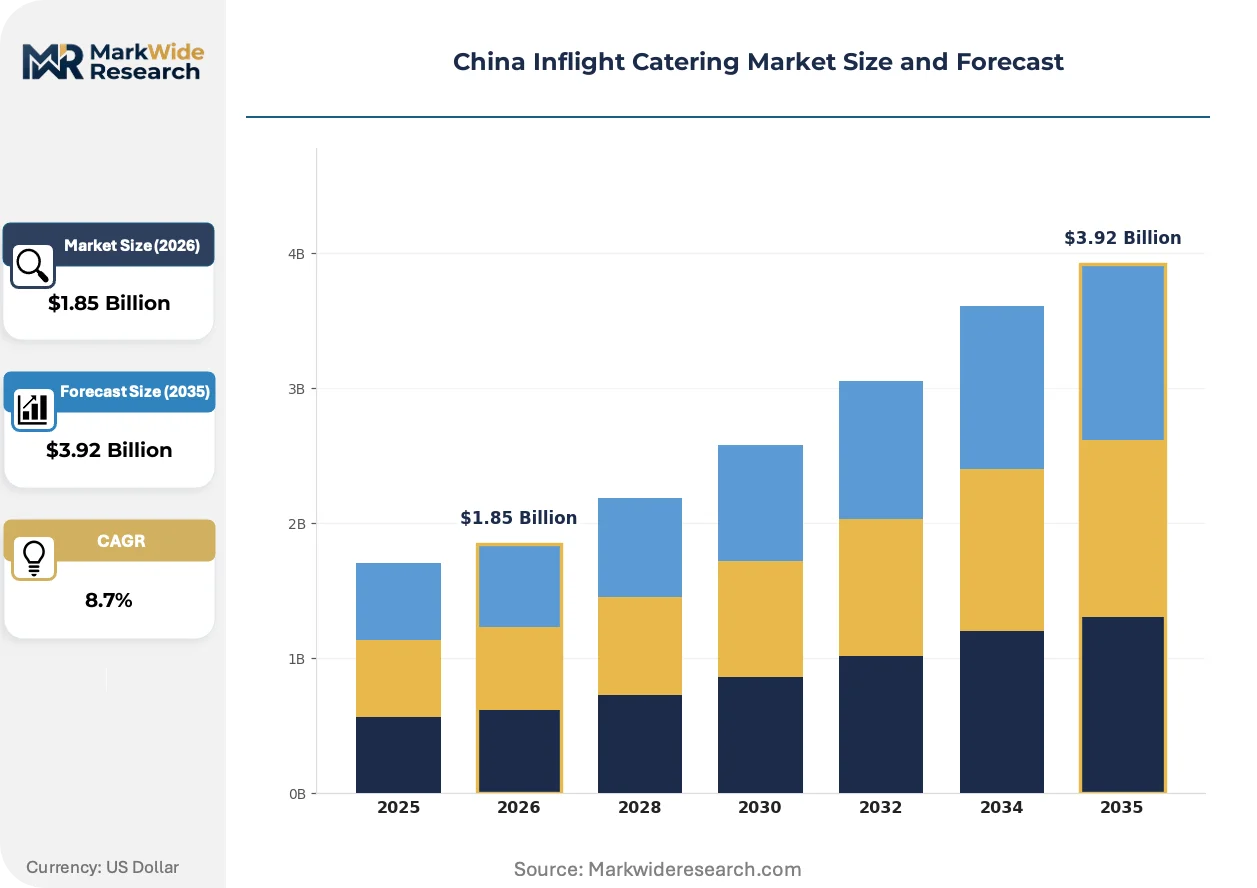
MIIT smart kitchen mandates and SAMR's real-time traceability requirements are compressing operational timelines for aviation caterers while forcing capital redeployment toward automated cold-chain infrastructure.
Growth Catalysts
- Domestic trunk route expansion:Full-service airline adoption across high-frequency corridors is generating dedicated kitchen line investments and tray-set complexity premiums.
- GB 14934 disinfectant standards:SAMR enforcement of aviation-specific hygiene protocols is professionalizing mid-tier operators and consolidating compliance-capable suppliers.
- Halal-certified production capacity:Pearl River Delta carriers are securing captive supply agreements for religious-diet protocols on Southeast Asian routes.
Market Restraints
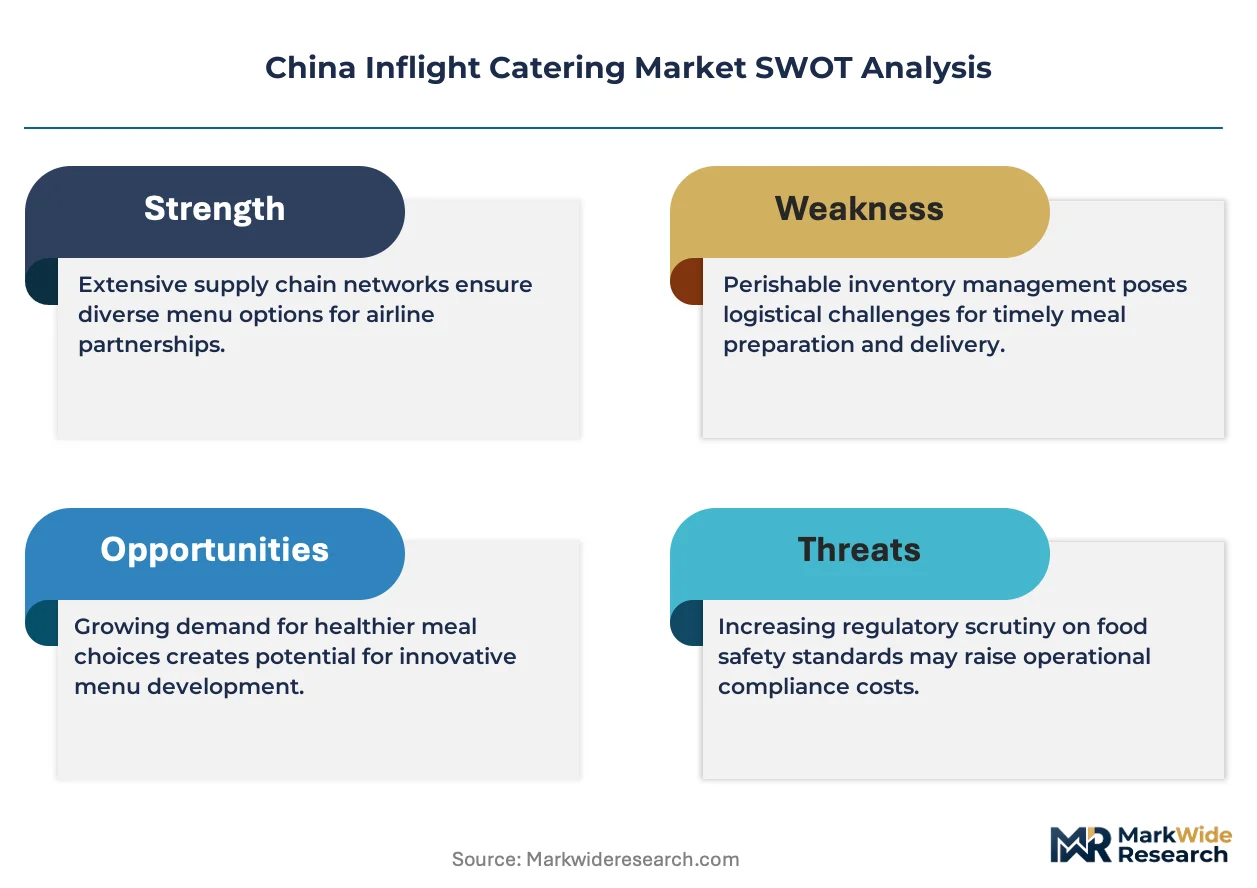
- Specialized protein input volatility:Aviation-grade poultry and seafood contracts face price pressure from cold storage capacity constraints at Shanghai Pudong's aviation cluster.
- Single-source galley engineering dependence:European-origin equipment standards limit domestic alternatives for wide-body fleet configurations.
- Four-hour service window rigidity:Core temperature logging requirements eliminate buffer capacity during peak morning bank operations.
Strategic Opportunities
- Beijing Daxin integrated zones:Northern corridor capacity expansion offers first-mover positioning for automated assembly lines serving dual-hub carriers.
- Diabetes-specific meal protocols:NMPA-aligned allergen labeling rules are creating premium tier differentiation for metabolic-condition catering.
- Compostable serviceware mandates:MEE packaging waste directives are opening procurement slots for domestic biodegradable tray manufacturers.
Industry Challenges
- HACCP auditor scarcity:Certified commissary inspectors face recruitment bottlenecks as audit frequency escalates under SAMR enforcement.
- Legacy ERP integration:Real-time traceability code systems require middleware development for kitchens running decade-old inventory platforms.
- Altitude-adjusted flavor R&D:Umami enhancement science demands specialized food chemist talent pools concentrated in coastal research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Inflight Catering Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service, Snack Service, Meal Kits, Beverages Product Type: Breakfast Items, Main Courses, Desserts, Special Meals Client Type: Airlines, Charter Services, Private Jets, Travel Agencies Delivery Mode: Pre-Packaged, On-Board Assembly, Catering Trucks, Direct Supply |
| Companies Covered | China Eastern Air Holding Company, HNA Group, Air China, Flying Food Group, Sats Ltd, LSG Sky Chefs, Guangzhou Nanland Air Catering Co. Ltd, Newrest International Group SAS, Cathay Pacific Catering Services (H.K) Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Inflight Catering Market Strategic Shifts
Automation and regulatory digitization are compressing traditional kitchen labor models while reshaping how aviation food premises demonstrate compliance to tightening audit regimes.
Robotic cold-chain assembly systems are rendering obsolete manual tray-set configurations for wide-body fleets. Full-service carriers operating domestic trunk routes are deploying these systems at pace to justify dedicated kitchen line economics. The technology is rendering obsolete the historical labor arbitrage that low-cost carriers relied upon for galley cost control.
MIIT smart kitchen mandates require real-time temperature logging and automated dispatch coordination across aviation food premises. Industrial consequence includes forced middleware investments for legacy ERP platforms and consolidated supplier qualification around IoT-capable equipment vendors. Full-service contracts face the steepest compliance timelines as tray-set complexity multiplies sensor integration points.
Meal kit outsourcing is displacing captive galley labor among low-cost carriers seeking to strip fixed costs from narrow-body operations. Third-party logistics networks are capturing assembly and last-mile distribution functions previously held in-house. This pattern concentrates in the Pearl River Delta where Guangzhou-based operators leverage halal-certified capacity across multiple airline clients.
China Inflight Catering Market Segmentation
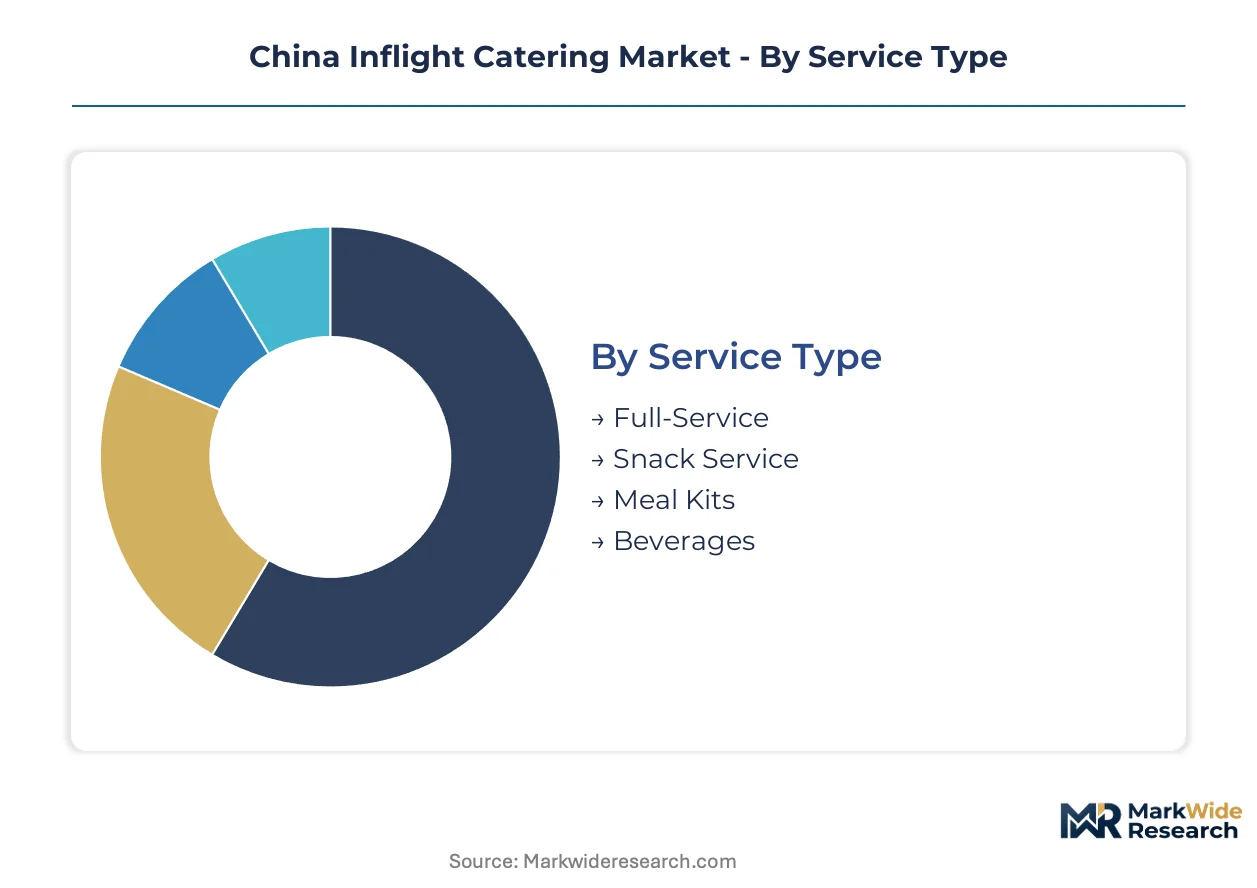
China's inflight catering market fragments across service intensity, product complexity, and client procurement patterns. Each dimension carries distinct margin profiles and compliance burdens under SAMR's GB standards.
Service Type:
Cost tier differentiation separates capital-intensive kitchen operations from outsourced assembly models.
- Full-Service:Complete tray-set preparation with dedicated kitchen lines, HACCP-certified commissaries, and altitude-adjusted flavor engineering. Shanghai Pudong's aviation cluster concentrates demand as domestic trunk carriers justify premium positioning through dedicated galley contracts.
- Meal Kits:Pre-portioned components assembled off-site for narrow-body galley loading. Pearl River Delta low-cost carriers outsource to third-party logistics networks to strip fixed labor costs from morning bank operations.
- Snack Service:Simplified cold-chain distribution of packaged items for short-haul rotations.
- Beverages:Bulk concentrate and chilled distribution governed by core temperature logging protocols.
Full-Service commands the established base. The steepest expansion runs through Meal Kits.
Product Type:
Application-specific preparation cycles align with flight scheduling patterns and passenger demographic targeting.
- Breakfast Items:Volume leadership on domestic morning banks with standardized pastry, fruit, and hot beverage configurations. Beijing Daxin's integrated catering zones process peak-load capacity for dual-hub carriers operating 6-10 AM departure windows.
- Special Meals:Religious-diet, diabetes-specific, and allergen-controlled protocols requiring segregated production lines. Guangzhou Nanland's halal-certified capacity captures Southeast Asian route demand under NMPA-aligned labeling rules.
- Main Courses:Protein-centered tray sets with umami enhancement for altitude-adjusted palates.
- Desserts:Chilled confectionery with compressed service windows for long-haul rotation cycles.
Breakfast Items anchor current throughput. Special Meals gain share fastest from premium tier differentiation.
Client Type:
Customer procurement scale determines contract structure complexity and audit frequency exposure.
- Airlines:Scheduled carriers with multi-year catering agreements, real-time traceability mandates, and automated cold-chain infrastructure requirements. Full-service contracts dominate as tray-set complexity justifies dedicated kitchen line economics.
- Private Jets:Bespoke preparation with flexible dispatch windows and premium ingredient sourcing. Beijing and Shanghai FBOs concentrate demand for customized protocols outside standard four-hour service windows.
- Charter Services:Variable-volume contracts with seasonal demand spikes and simplified compliance tiers.
- Travel Agencies:Aggregated group bookings with standardized meal allocations and bulk pricing structures.
Airlines lock in the revenue core. Private Jets climb the fastest on premium positioning.
Delivery Mode:
Supply concentration shapes logistics infrastructure investment and regulatory touchpoint density.
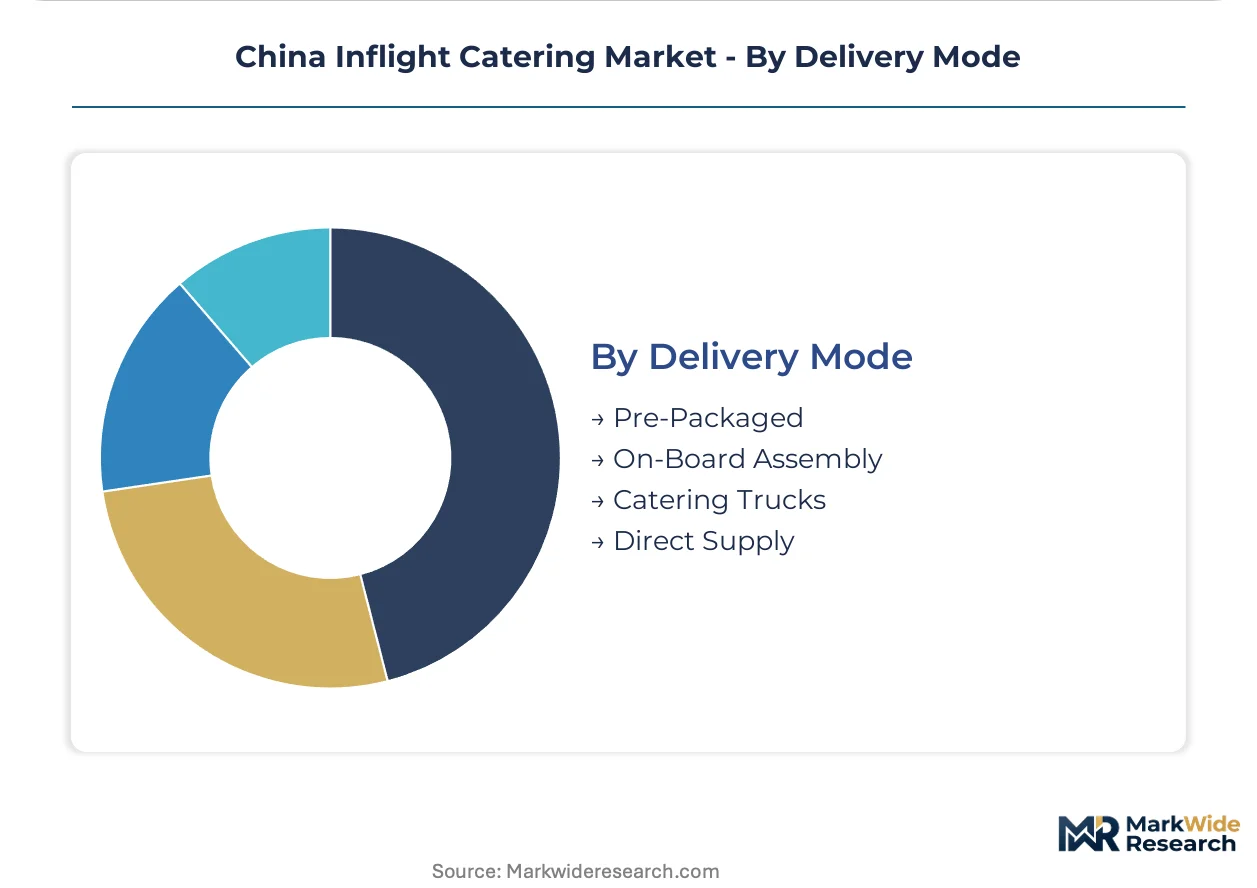
- Catering Trucks:Mobile chilled distribution from commissary to aircraft galley with GPS-tracked temperature logging. Shanghai Pudong's aviation cluster operates the densest fleet deployment under MIIT smart kitchen coordination mandates.
- Direct Supply:Producer-to-airline contracts bypassing intermediary consolidation, common for beverage concentrates and packaged snacks. MEE packaging waste directives favor domestic biodegradable serviceware manufacturers in direct procurement slots.
- Pre-Packaged:Factory-sealed items with extended shelf stability for low-frequency routes.
- On-Board Assembly:Final tray configuration performed by flight crew, limited to narrow-body cost-control models.
Catering Trucks maintain operational dominance. Direct Supply expands most quickly from sustainability procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across China's aviation corridors diverge sharply between trunk route density and regional airport fragmentation. Coastal hubs prioritize automated cold-chain throughput for wide-body fleets, while interior provinces rely on modular meal-kit distribution to serve thin-route economics.
Yangtze River Delta
Shanghai Pudong's aviation cluster processes peak-load breakfast volumes for domestic morning banks under MIIT smart kitchen coordination. SAMR's GB 14934 disinfectant standards enforce real-time traceability across HACCP-certified commissaries. LSG Sky Chefs anchors premium long-haul contracts through European-origin galley engineering standards deployed at dedicated kitchen lines.
Pearl River Delta
Guangzhou Nanland Air Catering Co. Ltd dominates halal-certified production for Southeast Asian route demand from carriers based at Baiyun International. NMPA-aligned allergen labeling rules reshape procurement specifications toward segregated religious-diet protocols. Shenzhen's integrated logistics zones concentrate third-party meal-kit assembly for low-cost carrier outsourcing.
Beijing-Tianjin-Hebei
Beijing Daxin's integrated catering zones attract dual-hub carrier investment for northern corridor capacity expansion. MEE packaging waste directives favor domestic biodegradable serviceware manufacturers in direct procurement slots. Tianjin's cold storage infrastructure supports four-hour service window rigidity for core temperature logging compliance.
Sichuan-Chongqing
Chengdu Shuangliu and Chongqing Jiangbei serve as western aviation gateways with growing full-service carrier adoption on trunk routes to coastal hubs. The region's catering operators face specialized protein input volatility from cold storage capacity constraints. Local commissaries deploy altitude-adjusted flavor R&D partnerships with coastal research clusters.
Shandong Peninsula
Qingdao and Yantai aviation zones concentrate on international route catering with Korean and Japanese carrier contracts. HACCP auditor scarcity creates recruitment bottlenecks as SAMR enforcement escalates audit frequency. Regional operators invest in legacy ERP middleware to meet real-time traceability code requirements.
China Inflight Catering Market Competitive Environment
Capability concentration sits with full-service specialists commanding dedicated kitchen line economics; scale advantage sits with diversified hospitality groups leveraging cross-sector logistics infrastructure. The vendor base stratifies across three tiers: airline-captive caterers with hub-locked contracts, independent operators serving multiple carrier clients, and meal-kit assemblers capturing low-cost carrier outsourcing. Dominant competitive moves include automated cold-chain infrastructure deployment and halal-certified production line expansion for Southeast Asian route access.
Within the airline-captive tier, China Eastern Air Holding Company and Air China exemplify hub-locked scale advantage through integrated catering subsidiaries. Guangzhou Nanland Air Catering Co. Ltd occupies a specialist position in religious-diet certification, representing the independent operator archetype with multi-client Pearl River Delta concentration. Newrest International Group SAS anchors the diversified hospitality vector, translating offshore oil-platform logistics expertise into isolated kitchen protocols for aviation applications.
| Leading Market Players |
|---|
| China Eastern Air Holding Company |
| HNA Group |
| Air China |
| Flying Food Group |
| Sats Ltd |
| LSG Sky Chefs |
| Guangzhou Nanland Air Catering Co. Ltd |
| Newrest International Group SAS |
| Cathay Pacific Catering Services (H.K) Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shanghai Pudong's aviation cluster concentrates cold storage capacity for aviation-grade poultry and seafood, translating upstream protein scarcity into margin compression across full-service tray-set contracts. SAMR's GB 14934 disinfectant standards and MIIT smart kitchen mandates force capital redeployment toward automated infrastructure, reshaping how operators defend pricing power against compliance-capable competitors.
Pricing Analysis
Price spreads between Beijing Daxin's integrated zones and Pearl River Delta meal-kit assemblers reflect divergent service intensity models. Three-tier pricing structure across premium, standard, and economy levels separates full-service carriers with dedicated kitchen lines from low-cost operators outsourcing to third-party logistics networks. Cost compression in the standard tier is intensifying because cold storage capacity constraints at Pudong limit protein input availability. Low-cost carriers operating narrow-body morning banks exhibit highest price sensitivity, while full-service domestic trunk carriers demonstrate lowest sensitivity due to tray-set complexity premiums.
Supply Chain Analysis
Aviation-grade protein inputs draw from domestic Chinese poultry farms, Australian seafood contracts, and Southeast Asian halal-certified suppliers. Specialized cold-chain equipment sources from European-origin galley engineering standards, compostable serviceware feeds from domestic biodegradable manufacturers under MEE directives, and HACCP-certified commissary infrastructure rests on regional logistics networks. Single-source vulnerability concentrates in European galley equipment standards that limit domestic alternatives for wide-body configurations. Distribution runs through GPS-tracked catering truck fleets coordinated under MIIT smart kitchen mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT smart kitchen mandates and SAMR real-time traceability requirements are compressing operational timelines and forcing capital redeployment, creating high-growth disruption for compliance-capable operators. This technological-regulatory inflection rewards automated cold-chain infrastructure while penalizing legacy ERP platforms.
For Market Incumbents: Entrench hub-locked scale advantage through backward integration into cold storage at Shanghai Pudong and Beijing Daxin. Defend against meal-kit assemblers capturing low-cost carrier outsourcing by accelerating HACCP auditor recruitment and deploying robotic tray-set systems before compliance timelines tighten further.
For New Entrants and Emerging Players: Establish a beachhead in halal-certified production capacity for Southeast Asian route access. Target Sichuan-Chongqing western gateway expansion where full-service carrier adoption on trunk routes outpaces local cold storage infrastructure. Lead with altitude-adjusted flavor R&D partnerships leveraging coastal research cluster talent pools.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because SAMR enforcement escalates audit frequency and consolidates supplier qualification around IoT-capable equipment vendors. Target acquisition archetypes include independent operators with multi-client concentration and segregated religious-diet production lines. Watch for HACCP auditor scarcity triggering margin compression at mid-tier commissaries as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cold-Chain Infrastructure Deployment | MIIT smart kitchen mandates force sensor integration across HACCP-certified commissaries for real-time traceability compliance. |
| Halal-Certified Production Line Expansion | Guangzhou Nanland's captive supply model captures Southeast Asian route demand under NMPA-aligned allergen labeling rules. |
| Backward Integration into Cold Storage | Pudong's protein input volatility rewards upstream control over aviation-grade poultry and seafood inventory buffers. |
| Legacy ERP Middleware Development | Real-time traceability code systems require interoperability investments for decade-old inventory platforms at regional operators. |
| Compostable Serviceware Procurement Shift | MEE packaging waste directives open direct supply slots for domestic biodegradable tray manufacturers against imported alternatives. |
Study Parameters
Cross-validation between primary interviews with airline procurement directors, catering operations managers, HACCP compliance officers, and cold-chain logistics specialists and secondary validation through SAMR regulatory filings, MIIT smart kitchen mandate documentation, customs trade data on aviation-grade protein imports, and airline annual procurement disclosures anchors the qualitative findings. Bottom-up segment sizing triangulates against top-down market aggregation across service type, product category, and client archetype dimensions.
Calibration against historical capacity deployment patterns at Shanghai Pudong and Beijing Daxin grounds the projection framework. Segmentation dimensions modeled include service intensity tier, product preparation cycle, customer procurement scale, and delivery logistics mode across the analysis window. CAGRs derive from slope analysis of installed automation capacity, regulatory compliance timeline acceleration, and carrier fleet expansion schedules. Altitude-adjusted flavor R&D investment flows and halal certification adoption curves inform industry-specific trajectory adjustments.
Sensitivities concentrate around MIIT mandate enforcement pace, HACCP auditor recruitment bottlenecks, and European galley equipment supply continuity. Forecasts reflect documented assumptions regarding trunk route expansion timing and low-cost carrier outsourcing propensity. Cross-checking against airline disclosed catering cost per available seat mile and commissary utilization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
New Zealand Foodservice Market
Food Service
Full-Service Restaurants Market
Food Service
Commercial Grills Market
Food Service
Europe Pizza Oven Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Cloud Kitchen Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Europe Airline Catering Services Market
Food Service
Commercial Ice Dispenser Market
Food Service
Europe Food Away from Home Market
Food Service
Bottled Water Cooler Market
Food Service
Workplace Service Market
Food Service
Virtual Kitchen Market
Food Service
Shaker Bottles Market
Food Service
Asia Pacific Airline Catering Services Market