
 Thailand Food Service Market | 2026-2036
Thailand Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Food Service Market Insights
Thai FDA's enhanced GMP-HACCP certification mandate is expanding the cost-of-entry calculus for new food service entrants. Minor International leverages its integrated supply chain across hotel and restaurant formats to sustain margin control. CP All PCL anchors the convenience-store food service segment through its 7-Eleven network dominance. LINE MAN Wongnai competes aggressively on delivery logistics technology, capturing urban consumer frequency.
Thailand Food Service encompasses the preparation, sale, and delivery of ready-to-consume meals through commercial establishments ranging from street vendors to full-service restaurants, operating under strict thermal control and cold-chain protocols to prevent tropical-climate spoilage. Fast food and café formats lead volume throughput due to standardized menus and rapid table turnover, while fine dining captures disproportionate margin pools through experience-based pricing. Online delivery and dine-in channels now split urban demand, with food trucks emerging as a flexible entry vehicle for new operators testing neighborhood viability.
Thai FDA, Ministry of Public Health sanitation codes, and municipal operating licenses collectively shape market access, product safety standards, and facility inspection frequencies across provinces. The Consumer Protection Board monitors advertising claims and delivery platform fee transparency, tightening operational compliance for aggregator models. Stakeholders must monitor regulatory harmonization between Bangkok's municipal health department and emerging provincial enforcement regimes as expansion targets shift inland.
Market Dynamics
Thai FDA's GMP-HACCP certification mandate is compressing independent operator margins while accelerating chain-format consolidation across Bangkok and secondary cities. The regulatory cost burden is restructuring competitive viability thresholds.
Growth Catalysts
- Quick-service penetration:Chain formats are capturing secondary-city demand through standardized supply chains and thermal-control protocols suited to tropical climates.
- Thai FDA certification harmonization:Unified sanitation standards across provinces are reducing multi-jurisdictional compliance friction for multi-unit operators.
- Delivery platform density:Urban logistics networks anchored by LINE MAN Wongnai are compressing delivery times and expanding addressable meal occasions.
Market Restraints
- Input cost volatility:Palm oil and protein feedstock fluctuations are squeezing kitchen-level margins for independent full-service establishments.
- Supply concentration risk:CP All PCL's captive distribution network limits third-party access to cold-chain infrastructure in provincial markets.
- Regulatory friction:Municipal operating license variations between Bangkok and emerging provincial enforcement regimes create expansion complexity.
Strategic Opportunities
- Chiang Mai premium-format expansion:Underserved fine-dining density in northern Thailand offers experience-based pricing capture for curated concepts.
- Food truck mobility:Flexible format testing is lowering neighborhood viability assessment costs before permanent site commitment.
- Consumer Protection Board transparency mandates:Delivery platform fee disclosure rules are creating competitive differentiation for aggregator-light direct-order channels.
Industry Challenges
- HACCP auditor scarcity:Certified food safety assessor availability is constraining certification timelines for new market entrants.
- Cold-chain capex intensity:Tropical-climate spoilage prevention requires continuous refrigeration investment that strains working capital.
- Legacy POS integration:Dine-in reservation systems resist seamless connection with delivery platform order management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Food Service Market |
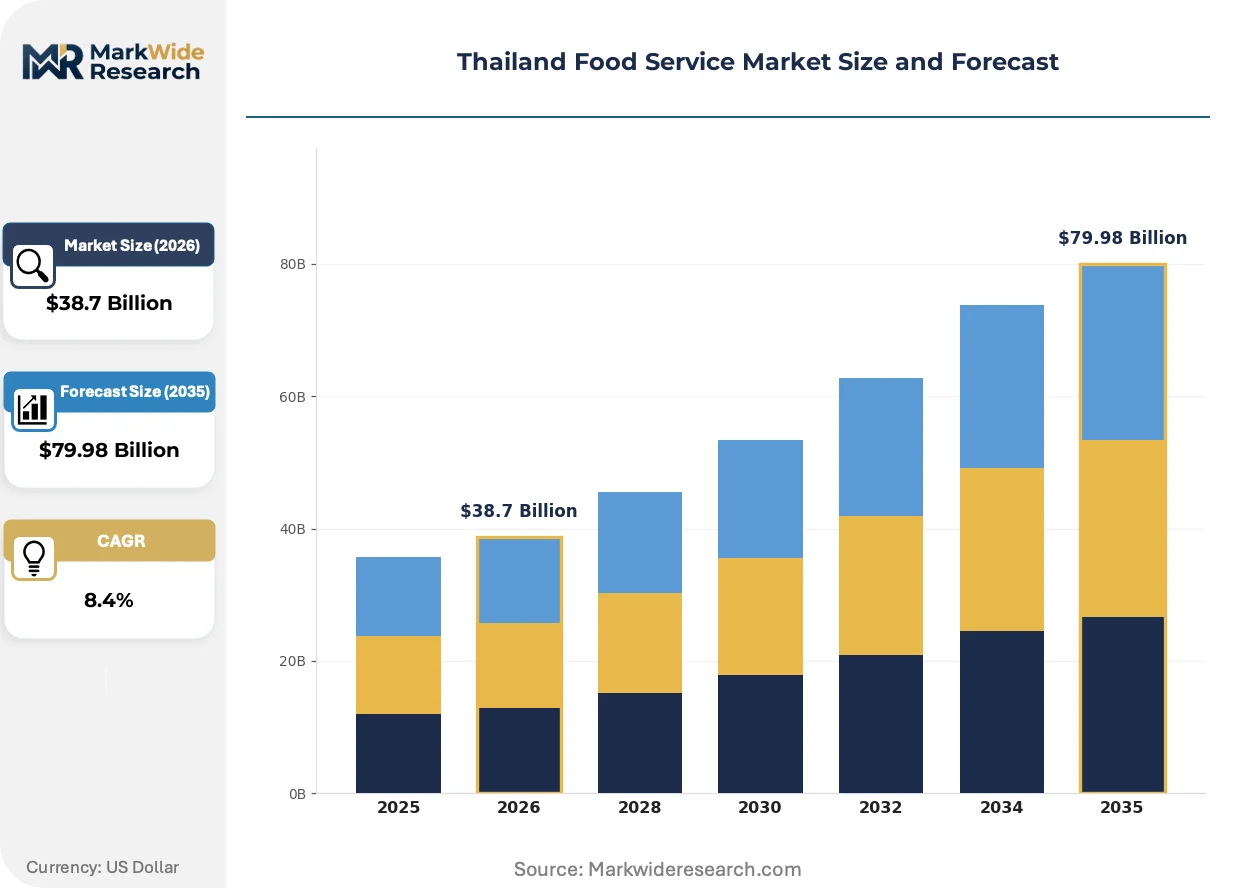
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Fine Dining, Cafés, Catering End User: Consumers, Businesses, Institutions, Travelers Pricing Model: Value Menu, Premium Pricing, Subscription, Pay-Per-Use Distribution Channel: Online Delivery, Dine-In, Takeaway, Food Trucks |
| Companies Covered | Yum! Brands Inc., LINE MAN Wongnai, CP All PCL, McThai Co. Ltd., Maxim's Caterers Ltd., Minor International, Central Plaza Hotel PCL, AQUA Corporation, Thai Beverage, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Food Service Market Trends and Innovations
Kitchen automation and predictive demand forecasting are compressing labor dependency and waste ratios across Thai food service formats. These shifts are redrawing operational economics between chain and independent models.
AI-powered demand forecasting is rewriting inventory and staffing optimization across quick-service chains. Central kitchen operators in Bangkok are deploying machine learning to predict hourly demand patterns and reduce protein spoilage. The technology is compressing the margin gap between chain-format efficiency and independent operational flexibility.
Thai FDA's enhanced GMP-HACCP certification mandate is elevating facility inspection frequencies and documentation requirements nationwide. Independent operators face capital expenditure pressure to upgrade ventilation and refrigeration systems. Full-service restaurants in Phuket and secondary cities are consolidating through franchise conversion to distribute compliance costs.
Urban consumer frequency is rotating toward aggregator-mediated discovery and away from direct restaurant relationships. Young professionals in Bangkok are selecting meals through LINE MAN Wongnai interface rather than brand loyalty. This behavior is compressing customer lifetime value for establishments without platform-independent direct-order infrastructure.
Thailand Food Service Market Segmentation
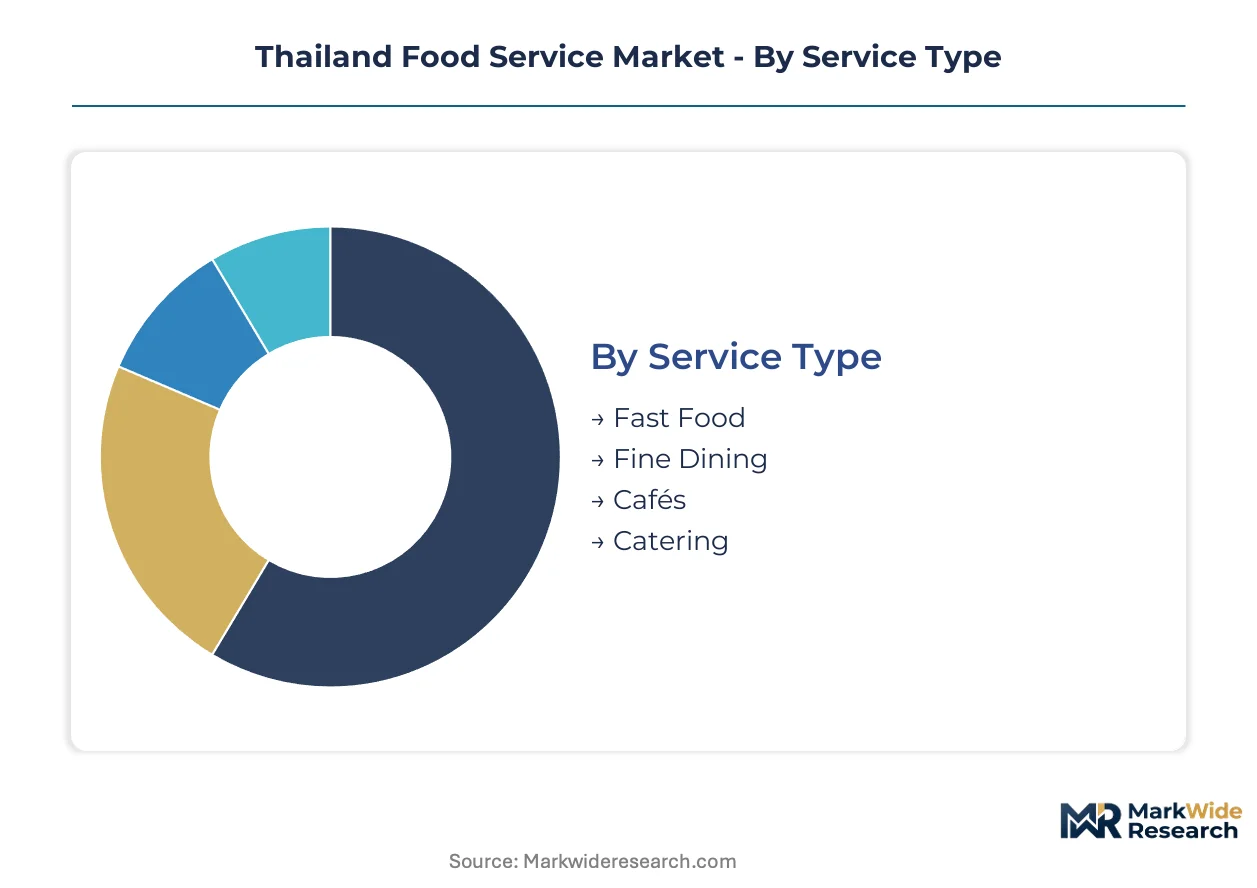
Thai FDA's tiered certification requirements create divergent compliance burdens across service formats, with full-service establishments facing steeper facility-upgrade costs than limited-menu operators. Segmentation reveals where regulatory friction concentrates and which structural pockets offer viable entry paths for new capital.
Service Type:
Thai FDA's GMP-HACCP certification mandate applies differentially across formats, with fine-dining kitchens requiring enhanced ventilation documentation and fast-food operators qualifying for streamlined audit protocols.
- Fast Food:Standardized menus and rapid throughput enable centralized procurement that absorbs palm oil price volatility. Bangkok and secondary-city chains leverage thermal-control protocols suited to tropical climates, compressing spoilage rates below independent benchmarks.
- Fine Dining:Experience-based pricing captures disproportionate margin pools through curated concepts. Chiang Mai's undersupplied premium density and Phuket's tourism-driven demand concentrate expansion opportunity, though HACCP auditor scarcity extends certification timelines.
- Cafés:Beverage-forward formats face lower protein-handling compliance thresholds than full kitchens. LINE MAN Wongnai's platform density drives urban frequency for grab-and-go morning occasions.
- Catering:Institutional contracts require batch-cold-chain integrity across event logistics. Municipal license variations between Bangkok and provincial regimes complicate multi-jurisdiction operations.
Fast Food sits at the top of the volume ranking, with Fine Dining climbing the fastest.
End User:
Customer-type concentration determines order-frequency profiles and platform-dependency exposure, with direct-order infrastructure becoming a defensive priority as aggregator mediation rises.
- Consumers:Young professionals in Bangkok rotate meal discovery through delivery interfaces rather than brand loyalty, compressing customer lifetime value for establishments lacking platform-independent channels.
- Businesses:Corporate catering contracts demand predictable portion scaling and invoice-grade documentation. Central kitchen operators deploy predictive demand forecasting to optimize protein procurement for recurring B2B volumes.
- Institutions:Schools and hospitals require Thai FDA's enhanced sanitation documentation at contract-renewal points. Compliance cost consolidation favors franchise conversion over independent bidding.
- Travelers:Tourism-dependent demand in Phuket and secondary destinations exhibits seasonal amplitude. Experience-based pricing tolerance runs higher than resident benchmarks.
Consumers generate the highest order frequency, while Businesses deliver the steadiest contract-backed revenue streams.
Pricing Model:
Revenue-structure selection shapes working-capital intensity and customer-lock-in mechanics, with subscription formats requiring upfront technology investment against predictable recurrence.
- Value Menu:Price-point discipline depends on captive supply-chain access. CP All PCL's distribution network limits third-party cold-chain reach in provincial markets.
- Premium Pricing:Curated concepts in northern Thailand and resort destinations capture margin through experience differentiation rather than throughput scale.
- Subscription:Meal-plan economics require accurate churn prediction to balance prep waste against commitment discounts. AI-powered demand forecasting is compressing the margin gap for chains with central kitchen infrastructure.
- Pay-Per-Use:Flexible occasion-matching suits food truck mobility and event-catering formats testing neighborhood viability before permanent site commitment.
Value Menu commands the widest addressable base, with Subscription formats expanding most quickly among urban professionals.
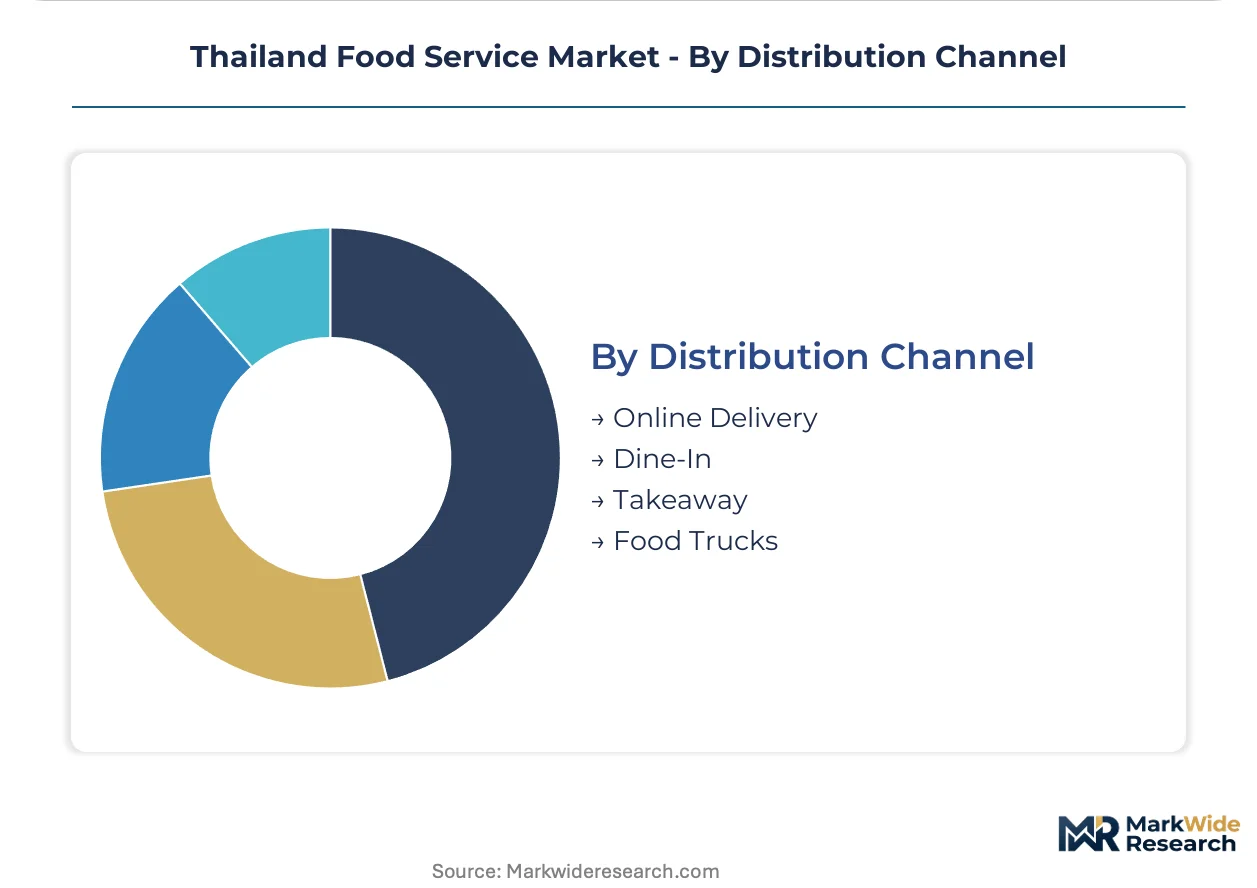
Distribution Channel:
Channel-mix decisions determine capex allocation between dine-in facility investment and delivery-logistics technology, with platform-fee transparency mandates reshaping aggregator economics.
- Online Delivery:LINE MAN Wongnai's urban logistics density compresses delivery times and expands addressable meal occasions. Consumer Protection Board fee-disclosure rules create differentiation openings for direct-order channels.
- Dine-In:Full-service formats face legacy POS integration resistance when connecting reservation systems to delivery order management. Facility-upgrade costs for Thai FDA compliance strain independent working capital.
- Takeaway:Packaging and thermal-retention standards fall under municipal health department inspection regimes. Bangkok's enforcement density exceeds emerging provincial consistency.
- Food Trucks:Mobile permits enable low-cost neighborhood viability testing before permanent lease commitment. Cold-chain capex intensity for tropical spoilage prevention applies regardless of format scale.
Online Delivery leads urban transaction volume, with Food Trucks gaining share fastest as flexible entry vehicles for new operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok's dense hospitality workforce anchors Thailand's food service concentration, with skilled kitchen labor and front-of-house talent clustering in the capital before diffusing to secondary markets.
Bangkok Metropolitan Region
Corporate dining contracts and premium tourism demand drive volume concentration. The Bangkok Metropolitan Administration enforces municipal health codes that exceed national baselines. Sukhumvit and Silom districts host the densest fine-dining clusters, where international hotel chains capture business-traveler meal occasions.
Chiang Mai
Digital nomad influx and domestic tourism are expanding café and co-working food service density. Thailand's Ministry of Public Health coordinates with provincial authorities on GMP-HACCP inspector deployment. Nimmanhaemin Road has emerged as a curated concept testing ground for northern expansion.
Phuket
Seasonal tourism amplitude creates demand volatility that favors flexible labor models. The provincial public health office applies Thai FDA sanitation standards with resort-sector inspection frequency. Patong and Laguna precincts concentrate beachfront dining investment from Bangkok-based operators.
Eastern Economic Corridor
Industrial zone workforce expansion is driving quick-service penetration in Rayong and Chonburi provinces. Board of Investment incentives for food processing are spilling over into service-sector cold-chain infrastructure. Amata and Map Ta Phut industrial estates anchor captive catering contracts for manufacturing tenants.
Isan Region
Urbanization in Khon Kaen and Udon Thani is creating secondary-city demand for chain-format standardization. Provincial health departments are harmonizing operating license protocols with Bangkok benchmarks. Central Plaza and Robinson retail complexes in Khon Kaen serve as food court anchors for regional brand entry.
Thailand Food Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Thailand's food service tiers. The market exhibits moderate consolidation, with hospitality conglomerates controlling premium real estate while delivery platforms and convenience networks capture high-frequency occasions. Two strategic archetypes dominate: integrated hospitality groups leveraging cross-format supply chains, and platform-native operators optimizing urban logistics density. Competitive moves center on franchise conversion to distribute compliance costs and direct-order infrastructure to reduce aggregator dependency.
Within the integrated hospitality tier, Minor International and Central Plaza Hotel PCL represent archetypes of cross-format supply chain leverage, while CP All PCL anchors convenience-store food service density through captive distribution networks.
| Leading Market Players |
|---|
| Yum! Brands Inc. |
| LINE MAN Wongnai |
| CP All PCL |
| McThai Co. Ltd. |
| Maxim's Caterers Ltd. |
| Minor International |
| Central Plaza Hotel PCL |
| AQUA Corporation |
| Thai Beverage |
| Others |
Pricing and Supply Chain Analysis
Captive supply chain integration across hotel and restaurant formats anchors both procurement leverage and pricing power for Thailand's largest food service conglomerates. Minor International's backward control over protein sourcing and cold-chain logistics enables margin insulation that independent operators cannot replicate under Thai FDA's escalating compliance costs.
Pricing Analysis
Bundled service packaging dominates fine-dining and catering formats while unbundled transactional pricing prevails in quick-service and café channels. Three-tier pricing structure across premium, standard, and economy levels separates experience-based concepts in Chiang Mai and Phuket from value-menu penetration in secondary cities. Pricing pressure stems from palm oil and protein feedstock volatility squeezing kitchen-level margins. Corporate catering clients exhibit lowest price sensitivity due to invoice-grade documentation requirements, while young professionals in Bangkok show highest sensitivity through platform-mediated discovery behavior.
Supply Chain Analysis
Freight cost intensity for tropical cold-chain compliance elevates the strategic value of proximate sourcing from Thailand's domestic agricultural base, with secondary reliance on Australian beef and New Zealand dairy imports. Protein feedstocks, palm oil derivatives, and packaging materials constitute the core input dependencies. Single-source vulnerability concentrates around CP All PCL's captive distribution network limiting third-party cold-chain access in provincial markets. Distribution runs through central kitchen hubs in Bangkok radiating to franchise-format endpoints, with LINE MAN Wongnai's logistics layer superimposed for urban delivery density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's food service market reads as a late-cycle quality story where Thai FDA certification harmonization is filtering demand toward premium-format operators with documented sanitation infrastructure.
For Market Incumbents: Acquire certified cold-chain assets in secondary cities to preempt franchise-format consolidation. Defensive priority centers on central kitchen capacity expansion in Rayong and Chonburi to capture Eastern Economic Corridor industrial catering contracts. Threat substitution from AI-powered demand forecasting at chain competitors necessitates parallel technology investment to maintain procurement efficiency parity.
For New Entrants and Emerging Players: Delivery platform partnerships offer the lowest-friction channel for urban frequency capture without dine-in facility capex. White-space targets concentrate in Chiang Mai's undersupplied fine-dining density and Khon Kaen's emerging retail-complex food courts. Go-to-market angle should leverage food truck mobility for neighborhood viability testing before permanent site commitment.
For Investors and Strategic Acquirers: Consolidation pressure builds where HACCP auditor scarcity extends certification timelines and strains independent working capital. Long-term viability favors franchise-format operators with distributed compliance cost structures and direct-order infrastructure reducing aggregator dependency. Acquisition target archetype: mid-scale full-service restaurants in Phuket and secondary cities facing conversion pressure. Signal to watch: municipal license harmonization progress between Bangkok and provincial enforcement regimes as inflection indicator for multi-unit expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Franchise Format Conversion | Distributes Thai FDA compliance costs across multi-unit operator networks in secondary cities. |
| Direct-Order Channel Investment | Reduces LINE MAN Wongnai dependency and preserves customer lifetime value for urban establishments. |
| Central Kitchen Expansion | Captures B2B catering volume in Eastern Economic Corridor industrial zones with predictive procurement. |
| AI-Powered Demand Forecasting | Compresses protein spoilage rates and labor dependency for quick-service chain competitiveness. |
| Provincial Cold-Chain Acquisition | Preempts CP All PCL network limitations and enables franchise penetration in Isan Region growth corridors. |
Research Methodology
Bottom-up outlet-level modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with central kitchen operators, franchise development executives, municipal health department inspectors, and delivery platform logistics managers combined with secondary validation from Thai FDA certification databases, Ministry of Public Health sanitation code filings, and Board of Investment incentive disclosures. Triangulation across these sources anchored volume and value estimates.
Input-output matrix framing connects protein procurement flows through processing and distribution to end-use consumption by service format and customer type. Segmentation dimensions modeled include service type, end-user category, pricing model, and distribution channel across the projection horizon. CAGRs derived from trend extrapolation of outlet expansion rates, transaction frequency shifts, and average ticket evolution calibrated against macroeconomic consumption indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement intensity variations between Bangkok and emerging provincial regimes, palm oil price volatility, and delivery platform fee structure evolution. Forecasts reflect documented assumptions about certification timeline normalization and cold-chain infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Away from Home Market
Food Service
Gas Floor Fryers Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Vacuum Flask Market
Food Service
Smokeless Grill Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Restaurant Griddle Market
Food Service
Qatar Food Service Market
Food Service
Beverage Vending Machine Market
Food Service
Europe Cloud Kitchen Market
Food Service
Commercial Burger Grill Market
Food Service
Ice Cream Carts Market
Food Service
Italy Foodservice Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Food Trucks Market