
 Workplace Service Market | 2026-2036
Workplace Service Market Size, Share, and Industry Trends Forecast 2026-2036
Workplace Service Market Outlook
ISO 41001 facility management certification is redrawing competitive boundaries in workplace services. Sodexo leverages its food services heritage to anchor integrated contracts across healthcare and corporate campuses. ISS A/S sustains geographic density in Northern Europe through bundled cleaning, security, and maintenance operations. CBRE Group dominates commercial real estate-adjacent service lines, extending property management into full workplace experience delivery.
Workplace services encompass the outsourced operation, maintenance, and optimization of commercial and institutional physical environments, spanning HVAC systems maintaining 68-72°F setpoints, security access control protocols, and janitorial sanitization cycles measured in ATP bioluminescence scores. Their primary purpose is to ensure occupant productivity, regulatory compliance, and asset longevity at lower cost than in-house execution. Cleaning services occupy the largest revenue pool given universal need and frequency, while smart building solutions represent the fastest-expanding margin segment as IoT sensor networks enable predictive maintenance and energy optimization. Corporate offices drive the highest contract value per site, though healthcare facilities command premium pricing due to infection control specifications and Joint Commission audit requirements.
OSHA workplace safety standards, EPA chemical handling regulations, and ISO 41001 facility management frameworks collectively shape service provider qualification, insurance bonding requirements, and contract tenability across the United States. The EPA's Safer Choice program for cleaning product formulations increasingly gates procurement decisions for federal and Fortune 500 accounts. Stakeholders must monitor how AI-driven workspace analytics platforms reshape the trade-off between outsourced efficiency and in-house data control before committing to long-term engagement structures.
Market Dynamics
Smart building sensor networks are compressing maintenance cycles from reactive to predictive modes, forcing facility management providers to restructure service delivery around real-time data streams rather than scheduled interventions.
Growth Catalysts
- OSHA workplace safety mandates:Federal enforcement of hazard communication standards and injury reporting protocols compels mid-market employers to outsource compliance-heavy functions to certified specialists.
- IoT-enabled predictive maintenance:Vibration analysis and thermal imaging sensors embedded in HVAC systems reduce unplanned downtime, creating measurable ROI that accelerates contract renewals.
- Germany's building energy efficiency regulations:The F-Gas Regulation and national climate targets drive demand for integrated facility retrofits combining heating, cooling, and lighting optimization.
Market Restraints
- Skilled technician scarcity:EPA Section 608 certification requirements for refrigerant handling constrain the available labor pool for HVAC service expansion.
- Input cost volatility:Specialty cleaning chemicals and semiconductor-dependent sensor hardware face price instability from concentrated Asian manufacturing.
- Data sovereignty friction:GDPR's cross-border transfer restrictions complicate centralized analytics platforms serving multinational corporate accounts.
Strategic Opportunities
- Japan's aging building stock:Over 35% of commercial structures exceed 30 years, creating retrofit demand for integrated workplace service bundles.
- AI-driven space utilization analytics:Convergence of computer vision and occupancy sensors enables dynamic cleaning schedules and energy allocation.
- India's Smart Cities Mission:Municipal infrastructure modernization opens municipal and institutional facility management contracts previously executed in-house.
Industry Challenges
- ISO 41001 certification timelines:The 12-18 month accreditation process delays market entry for regional specialists seeking Fortune 500 eligibility.
- Legacy building management system integration:Proprietary protocols from 1990s-era HVAC controls resist interoperability with cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workplace Service Market |
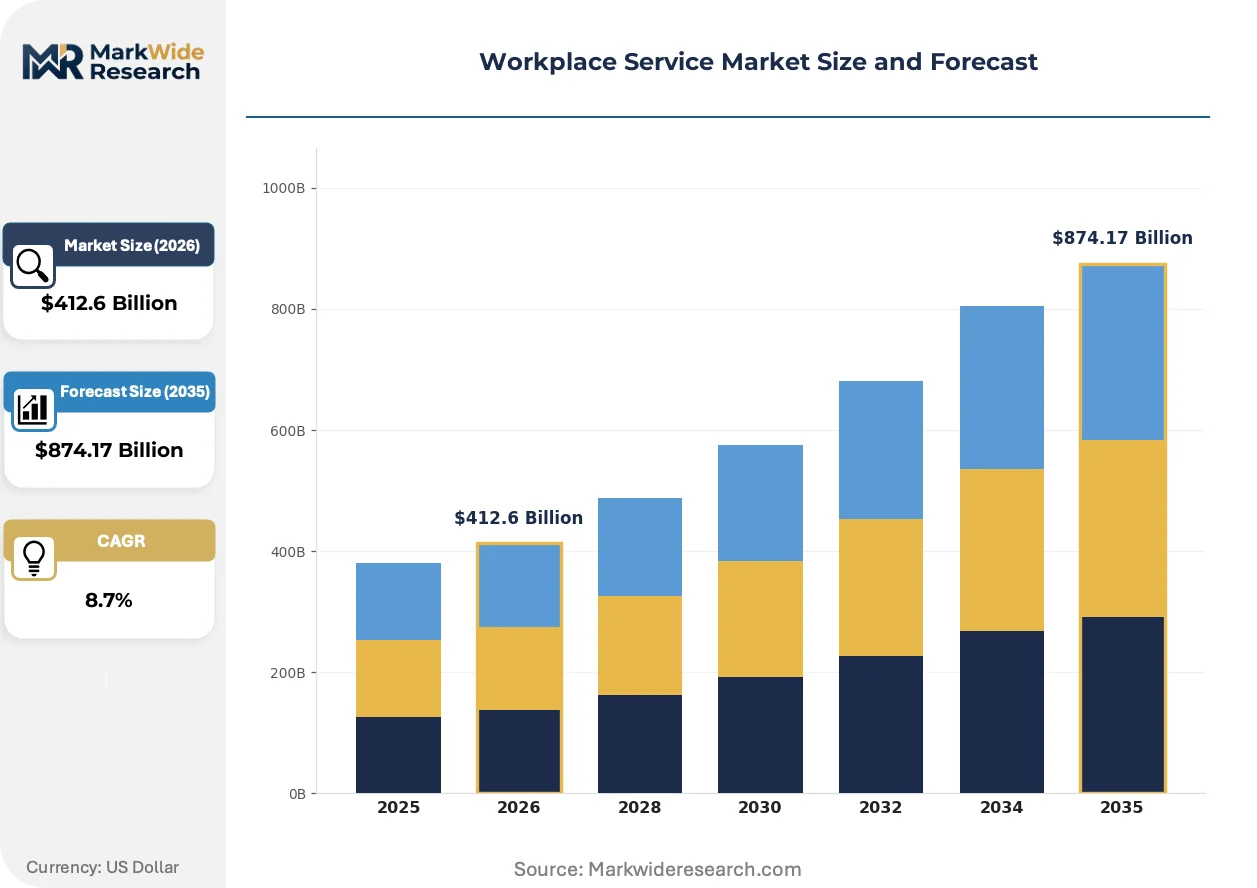
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $874.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, IT Support Client Type: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Chains Technology: Smart Building Solutions, Facility Management Software, Security Systems, Communication Tools Engagement Model: Outsourced Services, In-House Teams, Freelancers, Hybrid Models |
| Companies Covered | ISS A/S, Sodexo, CBRE Group, JLL, Cushman & Wakefield, ABM Industries, Accenture, Atos SE, HCL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workplace Service Market Strategic Shifts
Workplace service delivery is pivoting from labor-intensive task execution to technology-augmented outcome guarantees, with data streams becoming the primary contract performance metric.
Digital twin modeling is supplanting traditional facility audits for asset condition assessment. Large corporate campuses in the United States now deploy virtual building replicas fed by live sensor feeds to simulate maintenance scenarios before physical intervention. This compression of planning cycles reduces contractor mobilization costs and tightens SLA performance windows.
REACH chemical authorization protocols are restricting legacy cleaning formulations across European Union member states. The substitution of high-VOC solvents with bio-based alternatives forces reformulation of standard janitorial supply chains. German automotive manufacturing facilities face the steepest compliance deadlines, accelerating supplier consolidation toward certified green chemistry portfolios.
Corporate real estate teams are consolidating vendor relationships into single-source integrated contracts spanning cleaning, security, and maintenance. This preference compression displaces fragmented point-solution providers in favor of multi-service operators with certified management systems. The United States healthcare vertical exhibits the most aggressive consolidation, with hospital systems reducing supplier counts by 60% to streamline Joint Commission audit preparation.
Workplace Service Market Segmentation
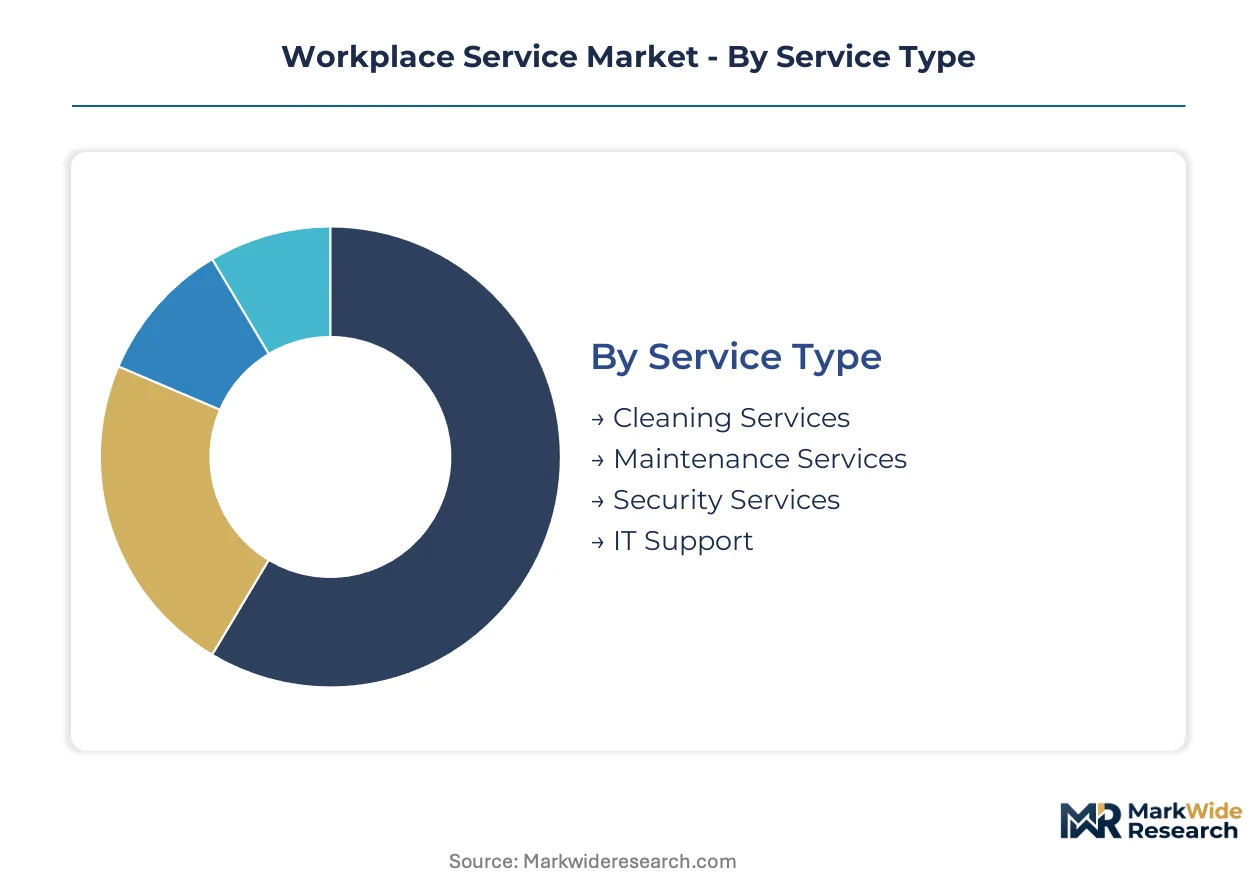
Workplace service procurement fractures across four distinct dimensions, each commanding separate vendor qualification protocols and margin structures. Understanding substitution pressures across service types and engagement models determines contract tenability and renewal economics.
Service Type:
Cleaning services face the most acute substitution threat from autonomous robotics and electrostatic disinfection systems, compressing labor-dependent pricing power fastest among all service categories.
- Cleaning Services:ATP bioluminescence scoring protocols and EPA Safer Choice chemical specifications define contract compliance. Demand concentrates in United States healthcare facilities where Joint Commission audit requirements mandate documented sanitization cycles exceeding 10,000 square feet per hour throughput benchmarks.
- Maintenance Services:HVAC setpoint management, vibration analysis, and thermal imaging diagnostics form the technical core. Germany's F-Gas Regulation and building energy efficiency mandates drive integrated retrofit contracts combining heating, cooling, and lighting optimization in automotive manufacturing campuses.
- Security Services:Access control protocols and manned guarding rotations measured in incident response time SLAs.
- IT Support:Helpdesk ticketing systems and network infrastructure monitoring with MTTR guarantees.
Cleaning services anchor the volume base while smart building-augmented maintenance gains share at the steepest rate.
Client Type:
Cost tier stratification separates premium compliance-heavy contracts from standardized facility management, with healthcare and corporate offices occupying opposite ends of the pricing spectrum.
- Corporate Offices:Integrated experience delivery spanning food services, concierge, and wellness programming. United States technology campuses in Seattle and Austin command per-square-foot premiums for LEED-certified and WELL Building Standard compliance.
- Healthcare Facilities:Infection control specifications, Joint Commission readiness, and biohazard waste handling protocols. Operating room terminal cleaning and isolation room decontamination cycles carry 40-60% pricing premiums over standard janitorial rates.
- Educational Institutions:Seasonal demand fluctuations tied to academic calendars and dormitory turnover schedules.
- Retail Chains:High-frequency, low-margin contracts with standardized scope across distributed footprints.
Healthcare facilities command the highest contract premiums while corporate offices deliver the most predictable renewal rates.
Technology:
Application maturity divides proven infrastructure from experimental deployments, with facility management software approaching commoditization as sensor networks remain vendor-concentrated.
- Smart Building Solutions:IoT sensor networks enabling predictive maintenance and real-time energy optimization. Japan's aging commercial building stock exceeding 30 years creates retrofit demand for integrated sensor deployments in Tokyo and Osaka financial districts.
- Facility Management Software:Work order automation, asset registry management, and vendor performance dashboards. Cloud-native platforms face GDPR cross-border transfer friction when serving multinational corporate accounts with centralized analytics.
- Security Systems:Biometric access control and video analytics with privacy-compliant data retention.
- Communication Tools:Tenant experience applications and service request portals with mobile-first interfaces.
Facility management software saturates mid-market adoption while smart building solutions climb the fastest among enterprise accounts.
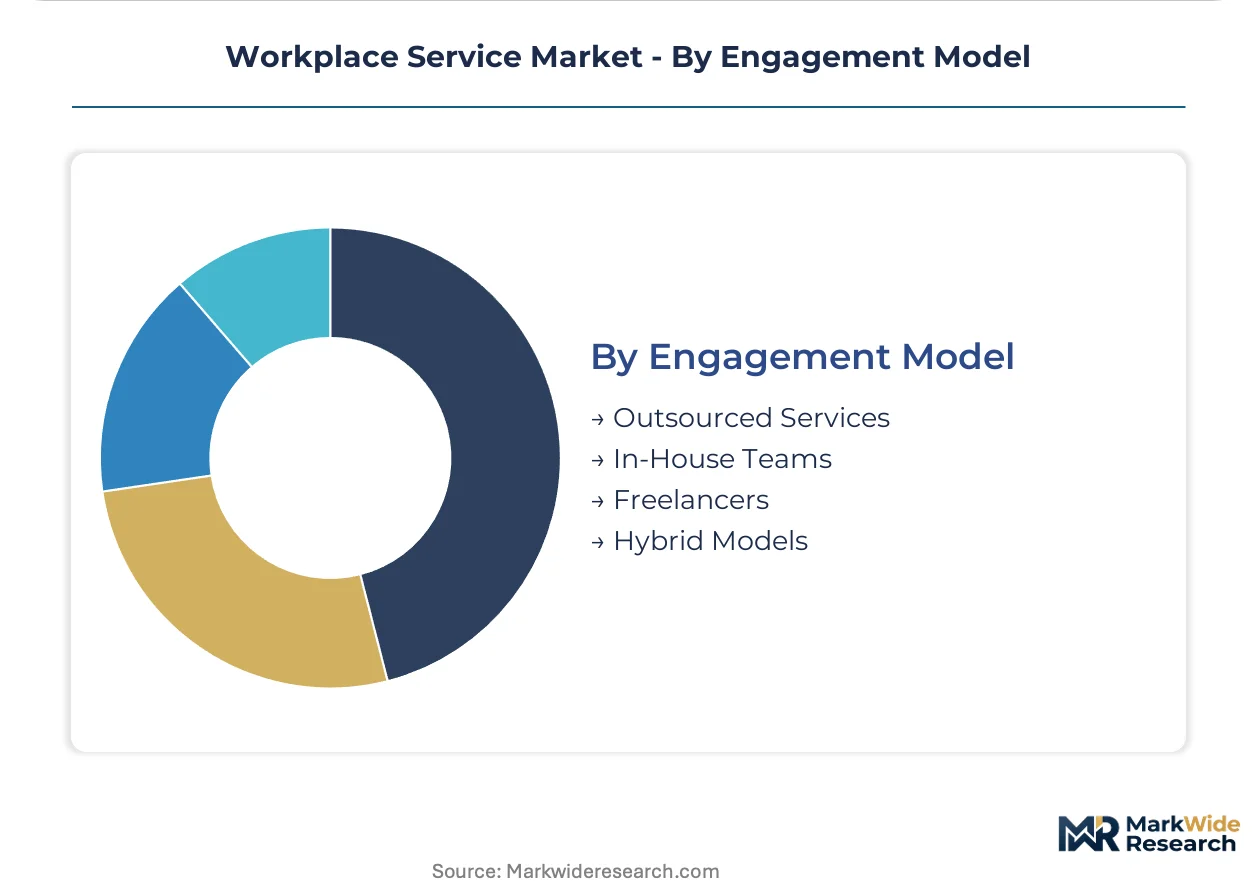
Engagement Model:
Customer type concentration reflects organizational scale and risk tolerance, with outsourcing preference correlating directly to regulatory exposure and capital intensity.
- Outsourced Services:Multi-year integrated contracts with ISO 41001 certification requirements and performance-based SLAs. OSHA workplace safety mandate enforcement in the United States compels mid-market employers toward certified specialists with documented compliance histories.
- In-House Teams:Direct employment of maintenance technicians and facility managers retaining operational control over sensitive data streams.
- Freelancers:Project-based specialist engagement for peak demand periods and technical overflow.
- Hybrid Models:Core competency retention with variable demand outsourcing for cleaning and security staffing.
Outsourced services dominate contract value while hybrid models expand most quickly among cost-conscious mid-market accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal OSHA enforcement expansion and Germany's F-Gas Regulation are redirecting facility management procurement toward certified multi-service providers with documented compliance frameworks.
United States
OSHA workplace safety mandate enforcement compels mid-market employers toward outsourced specialists with hazard communication protocols. The EPA's Safer Choice program gates federal and Fortune 500 cleaning product procurement. Corporate campuses in Seattle and Austin command per-square-foot premiums for LEED-certified integrated service contracts.
Germany
The F-Gas Regulation and national climate targets drive demand for integrated facility retrofits combining heating, cooling, and lighting optimization. REACH chemical authorization protocols restrict legacy cleaning formulations across automotive manufacturing facilities. Industrial clusters in Bavaria and Baden-Württemberg accelerate supplier consolidation toward certified green chemistry portfolios.
Japan
Over 35 percent of commercial structures exceeding 30 years create retrofit demand for integrated workplace service bundles. METI building energy efficiency standards mandate sensor-enabled predictive maintenance in financial district properties. Tokyo and Osaka commercial towers deploy IoT networks for real-time HVAC optimization and space utilization analytics.
India
The Smart Cities Mission opens municipal and institutional facility management contracts previously executed in-house. BIS certification requirements for building management systems shape vendor qualification protocols. Maharashtra and Karnataka technology corridors attract integrated service providers targeting campus-style corporate developments.
United Kingdom
GDPR cross-border transfer restrictions complicate centralized analytics platforms serving multinational corporate accounts with UK headquarters. The country's national building safety regulator enforces stricter fire safety and maintenance documentation standards for high-rise commercial properties. London's financial district drives premium pricing for ISO 41001-certified integrated contracts spanning security, cleaning, and technical maintenance.
Workplace Service Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with publicly traded facility management groups holding scale advantages in integrated contract bidding while private operators retain flexibility in niche compliance segments. Market structure tilts toward consolidation as corporate real estate teams reduce vendor counts by half to streamline audit preparation. Three archetypes dominate: multi-service integrated operators, property-adjacent real estate service extenders, and technology-augmented maintenance specialists. Competitive intensity concentrates on ISO 41001 certification acquisition and AI-driven workspace analytics platform deployment.
Within the integrated services tier, Sodexo leverages food services heritage to anchor healthcare and corporate campus contracts, while ISS A/S sustains geographic density in Northern Europe through bundled operations. CBRE Group exemplifies the property-adjacent archetype, extending commercial real estate management into full workplace experience delivery. These three represent distinct competitive positioning vectors—hospitality-anchored integration, regional density optimization, and real estate-adjacent service extension—each commanding different client risk profiles and contract tenability patterns.
| Leading Market Players |
|---|
| ISS A/S |
| Sodexo |
| CBRE Group |
| JLL |
| Cushman & Wakefield |
| ABM Industries |
| Accenture |
| Atos SE |
| HCL Technologies |
| Others |
Value Chain & Pricing Dynamics
Multi-year integrated service contracts with performance-based SLAs lock in supply access for facility management providers while anchoring price visibility against input cost volatility. These structures tie vendor compensation to ATP bioluminescence scores and thermal imaging diagnostics, transferring operational risk from corporate real estate teams to certified specialists.
Pricing Analysis
Certification level creates the primary spread between premium ISO 41001-accredited operators and uncertified regional competitors. Contract pricing stratifies across integrated experience bundles, standalone maintenance tiers, and commodity cleaning rates, with healthcare infection control specifications commanding 40-60% premiums over standard janitorial scopes. Cost compression in labor-dependent cleaning segments intensifies as autonomous robotics and electrostatic disinfection systems displace hourly staffing models. Retail chains exhibit the highest price sensitivity, while United States hospital systems prioritize Joint Commission compliance over rate negotiation.
Supply Chain Analysis
Just-in-time chemical procurement dominates janitorial supply chains, though EPA Safer Choice formulation shortages are pushing larger operators toward strategic stockpiles of bio-based cleaning agents. Specialty chemical manufacturing concentrates in Germany, China, and the United States, while semiconductor-dependent IoT sensor hardware feeds from South Korean and Taiwanese fabrication facilities. Single-source vulnerability runs through concentrated Asian electronics manufacturing, with distribution running through national distributor networks and direct procurement channels serving Fortune 500 accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from autonomous cleaning robotics and AI-driven workspace analytics platforms that compress labor-dependent margins. Defense requires locking in certification advantages and technology integration ahead of compliance mandate acceleration.
For Market Incumbents: Secure ISO 41001 certification density across operating geographies before enforcement windows tighten, and accelerate backward integration into smart building sensor deployment to capture predictive maintenance revenue streams. Autonomous robotics vendors threaten standard cleaning contract renewal economics; counter by bundling technology-augmented outcome guarantees that commodity competitors cannot replicate.
For New Entrants and Emerging Players: Lead with AI-driven space utilization analytics as the wedge capability, targeting Japan's aging commercial building stock exceeding 30 years where retrofit demand outpaces incumbent service bandwidth. India's Smart Cities Mission offers the most penetrable municipal entry point, with BIS certification requirements still stabilizing. Position around dynamic cleaning schedules and energy allocation algorithms that legacy operators lack.
For Investors and Strategic Acquirers: Capital is best deployed toward multi-service integrated operators with ISO 41001 certification and established healthcare vertical penetration, as contract consolidation trends favor scale over specialization. The five-to-ten year viability window favors providers with proprietary workspace analytics platforms. Watch for inflection when OSHA enforcement expansion accelerates mid-market outsourcing conversion rates.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Acquisition | Fortune 500 eligibility gates open only to accredited operators with documented compliance frameworks. |
| AI-Driven Workspace Analytics Platform | Predictive maintenance algorithms differentiate service delivery from labor-dependent competitors. |
| Healthcare Vertical Specialization | Joint Commission audit preparation commands 40-60% pricing premiums over standard janitorial rates. |
| Smart Building Sensor Integration | IoT networks enable real-time HVAC optimization and space utilization analytics for corporate campuses. |
| Green Chemistry Portfolio Transition | EPA Safer Choice and REACH authorization protocols increasingly gate federal and automotive procurement decisions. |
Study Parameters
Initial hypotheses were tested against primary input from facility management executives, corporate real estate directors, healthcare compliance officers, and janitorial supply procurement leads and refined through secondary validation across SEC filings, EPA Safer Choice product registries, OSHA enforcement databases, and ISO certification records. Bottom-up contract value estimates triangulated with top-down market sizing across service type, client vertical, and engagement model dimensions.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics, with segmentation modeling spanning cleaning, maintenance, security, and IT support service types alongside corporate office, healthcare, educational, and retail client verticals. CAGRs were derived from historical contract renewal rates and technology adoption curves, with forecast inputs incorporating F-Gas Regulation compliance timelines and METI building energy efficiency standards.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement expansion or accelerated smart building retrofit cycles would require recalibration. Forecasts reflect assumptions around certification adoption rates and sensor hardware cost curves. Revision becomes warranted when autonomous robotics penetration crosses threshold displacement levels in standard cleaning segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Online Food Delivery Market
Food Service
Egypt Food Service Market
Food Service
Haute Cuisine Market
Food Service
Food Service Dairy Products Market
Food Service
Food Trucks Market
Food Service
Sandwich Toasters Market
Food Service
Europe Inflight Catering Market
Food Service
Meal Kit Delivery Services Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Contract Catering Market
Food Service
Gourmet Street Food Market
Food Service
Lunch Takeout Market
Food Service
Commercial Tandoor Oven Market
Food Service
Plates Market
Food Service
Cambodia Foodservice Market
Food Service
One-Off Chopsticks Market