
 Saudi Arabia Inflight Catering Market | 2026-2036
Saudi Arabia Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Inflight Catering Market Insights
The transition from single-source to multi-source procurement is shifting how Saudi carriers structure their catering contracts. Gategroup leverages its international network to compete for premium airline accounts across the Kingdom. Saudi Airlines Catering Company anchors domestic capacity with centralized kitchen infrastructure at King Abdulaziz International Airport. Newrest Group Services specializes in remote-site and charter aviation catering, extending its footprint into secondary Saudi airports.
Inflight catering encompasses the preparation, assembly, and delivery of ready-to-serve meals, snacks, and beverages under strict time-temperature controls for consumption aboard aircraft, with meals typically produced in HACCP-certified commissaries within four to six hours of departure. The commercial airlines segment dominates volume demand as Saudi Arabia's flag carrier and international operators expand fleet sizes and route networks. Meal services command the largest revenue pool within service type segmentation, while special meal services—including halal, diabetic, and allergen-free options—represent the fastest-growing category as carriers differentiate on passenger inclusivity.
The Saudi Food and Drug Authority enforces aviation-specific food safety protocols that mandate continuous cold-chain documentation and supplier traceability, while the General Authority of Civil Aviation coordinates operational certifications for on-airport catering facilities. These dual regulatory layers elevate capital requirements for new entrants and reinforce incumbent advantages. Stakeholders must monitor how evolving SFDA digital traceability mandates reshape procurement specifications and third-party audit frequencies.
Market Dynamics
SFDA's digital traceability mandates are compressing supplier qualification timelines while forcing commissaries to rebuild documentation infrastructure around real-time cold-chain monitoring.
Growth Catalysts
- Route network expansion:King Abdulaziz International Airport's terminal upgrades and new international connections are multiplying daily flight rotations requiring catering provisioning.
- SFDA HACCP digitization:The Saudi Food and Drug Authority's electronic documentation requirements are accelerating automation investments that reduce per-meal handling costs.
- Premium cabin differentiation:Full-service carriers are outsourcing specialized halal and allergen-free meal production to certified commissaries with dedicated production lines.
Market Restraints
- Perishable input volatility:Fresh protein and produce prices fluctuate with Red Sea shipping disruptions, compressing commissary margins on standard meal contracts.
- Equipment supply concentration:Galley insert and refrigeration unit manufacturing concentrates in European and East Asian suppliers, extending replacement part lead times.
- Substitution by pre-packaged retail:Low-cost carriers are replacing hot meal services with buy-on-board snack selections that bypass commissary production entirely.
Strategic Opportunities
- Secondary airport penetration:Taif, Yanbu, and Al-Ula airports lack dedicated catering infrastructure, creating first-mover positions for commissary operators.
- Religious tourism meal services:Umrah and Hajj charter operators require high-volume halal certification that exceeds standard airline kitchen capacity.
- Blockchain-IoT convergence:Temperature logging sensors linked to distributed ledger systems are enabling premium pricing for carriers seeking audit-ready documentation.
Industry Challenges
- HACCP auditor scarcity:SFDA-certified food safety assessors are concentrated in Riyadh and Jeddah, delaying facility certifications in emerging airport locations.
- Legacy ERP integration:Commissary management systems must interface with airline reservation platforms and SFDA traceability portals simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Inflight Catering Market |
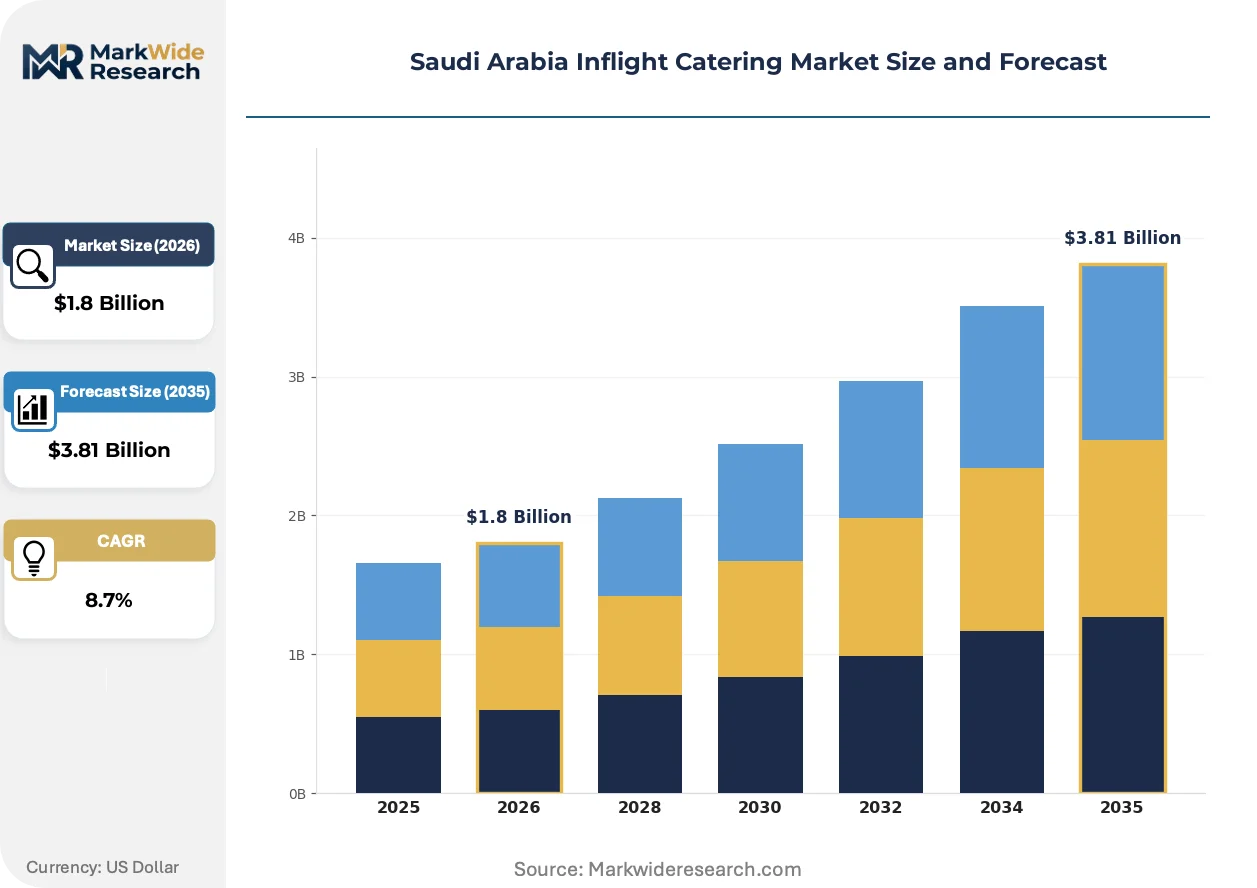
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Services, Snack Services, Beverage Services, Special Meal Services End User: Commercial Airlines, Charter Airlines, Cargo Airlines, Private Jets Menu Type: First Class, Business Class, Economy Class, Kids Menu Supply Chain Model: Centralized, Decentralized, Hybrid, Third-Party Providers |
| Companies Covered | Catrion Catering Holding Company, Gategroup, Newrest Group Services, SATS Ltd., LSG Sky Chefs, Saudi Airlines Catering Company, Emirates Flight Catering, Gulf Catering Company, Sodexo FZE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Inflight Catering Market Trends and Innovations
Automation and regulatory digitization are converging to reshape how Saudi commissaries manage production workflows, supplier relationships, and compliance documentation.
Automated meal assembly lines equipped with robotic portioning and tray-sealing systems are unifying previously fragmented production stations into continuous-flow operations. Saudi Airlines Catering Company and international operators are deploying these systems at King Abdulaziz International Airport to compress four-hour production windows. This unifying architecture reduces cross-contamination risks while enabling real-time throughput adjustments based on final passenger counts.
SFDA's phased implementation of blockchain-based supplier traceability is mandating that all aviation food vendors submit immutable batch records by 2027. Commissaries must retrofit procurement systems to capture farm-to-fork documentation for every protein and produce item. Premium carriers operating Riyadh-Europe routes are responding fastest, using compliance as a competitive differentiator in corporate travel procurement.
Airlines are consolidating catering contracts around performance-based metrics rather than per-meal unit pricing. Full-service carriers in Jeddah now penalize commissaries for temperature excursions and reward on-time delivery precision with volume guarantees. This restructuring is most visible among flag carriers expanding long-haul networks, where catering reliability directly affects on-time performance rankings.
Saudi Arabia Inflight Catering Market Segmentation

Segmentation in Saudi Arabia's inflight catering market reveals how procurement priorities diverge across carrier types and cabin tiers. Understanding these splits exposes where margin pools concentrate and which operational models face pressure from regulatory digitization.
Service Type:
Cost tier separates segments here, with labor intensity and ingredient complexity driving diverging margin structures.
- Meal Services:Full hot and cold meal production requiring HACCP-certified commissaries with dedicated protein handling, vegetable prep, and tray assembly lines. Riyadh-based full-service carriers dominate procurement volumes, though SFDA cold-chain documentation mandates are compressing supplier margins on standard economy meal contracts.
- Special Meal Services:Religious, medical, and allergen-specific preparations demanding segregated production environments and ingredient traceability. Jeddah's Umrah and Hajj charter operators generate concentrated demand for halal-certified special meals that exceed standard kitchen capacity during peak pilgrimage windows.
- Snack Services:Pre-packaged and freshly prepared light offerings with shorter production cycles and lower regulatory touchpoints.
- Beverage Services:Alcoholic and non-alcoholic drink provisioning, bar cart assembly, and specialized coffee/tea programs.
Meal Services leads volumes today; Special Meal Services is gaining share fastest.
End User:
Volume scale and contract stability create distinct procurement behaviors across buyer types.
- Commercial Airlines:Scheduled carriers operating fixed routes with predictable load factors and multi-year catering agreements. King Abdulaziz International Airport's expanding international connections multiply daily flight rotations requiring commissary provisioning at scale.
- Private Jets:Ultra-high-net-worth individuals and corporate flight departments demanding bespoke menu customization with 24-hour turnaround flexibility.
- Charter Airlines:Seasonal and pilgrimage operators with surge capacity requirements during Hajj and Umrah periods.
- Cargo Airlines:Flight crew provisioning for freighter operations with minimal passenger meal requirements.
Commercial Airlines anchors procurement volumes; Private Jets commands the steepest expansion trajectory.
Menu Type:
Cabin tier directly maps to ingredient specification, presentation complexity, and per-passenger spend.
- First Class:Multi-course dining with premium proteins, vintage wine pairings, and chef-designed presentations requiring specialized galley equipment and extended preparation timelines.
- Business Class:Elevated meal services with greater customization than economy, driving outsourced production to certified commissaries with dedicated premium lines.
- Economy Class:Standardized meal programs with tight cost controls and high-volume production efficiency.
- Kids Menu:Age-appropriate portions and allergen-conscious formulations targeting family travel segments.
Economy Class dominates production volumes; Business Class is expanding most quickly as Saudi carriers upgrade regional fleet configurations.
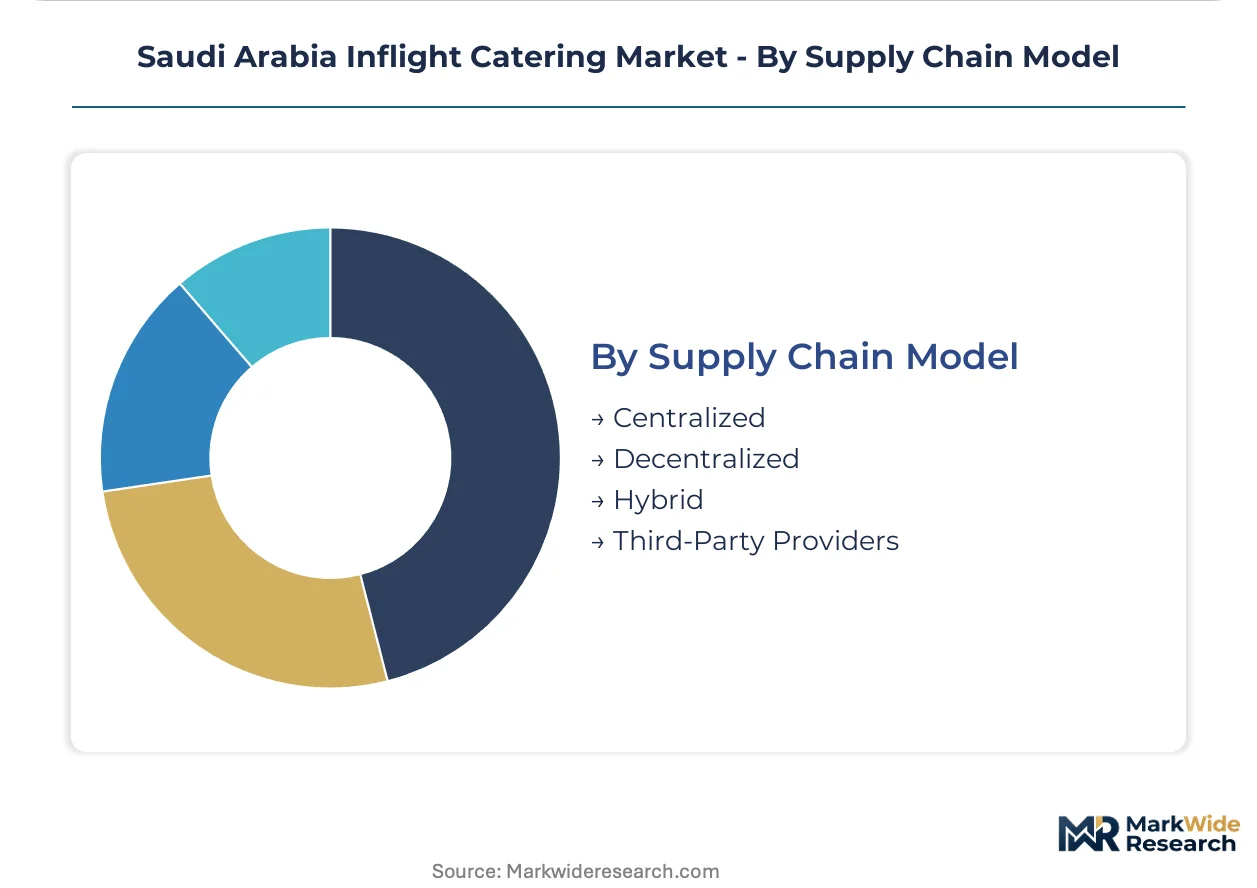
Supply Chain Model:
Capital deployment and operational control separate how commissary capacity reaches aircraft.
- Centralized:Single large-scale kitchen facility serving multiple airports through refrigerated transport networks. Saudi Airlines Catering Company's King Abdulaziz International Airport complex exemplifies this model, capturing economies of scale across the Western Province.
- Third-Party Providers:Independent catering companies competing for airline contracts through specialized certifications and performance-based service level agreements.
- Decentralized:Multiple smaller kitchens positioned at individual airports to minimize transport time and temperature excursion risks.
- Hybrid:Combined approach with central production for standard items and local finishing for time-sensitive or customized components.
Centralized infrastructure commands current capacity; Third-Party Providers is climbing the fastest as flag carriers diversify sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdulaziz International Airport anchors Saudi Arabia's inflight catering infrastructure, with commissary capacity concentrated in Riyadh and Jeddah metropolitan zones. The SFDA's aviation food safety mandates and GACA operational certifications create dual regulatory layers that elevate capital requirements for facility expansion. Regional demand patterns track pilgrimage seasons, international route additions, and secondary airport development timelines.
Riyadh
King Khalid International Airport's terminal expansion is multiplying daily flight rotations requiring hot meal provisioning. The SFDA maintains its primary aviation food safety certification center here, concentrating HACCP auditor resources. Riyadh-based full-service carriers are outsourcing premium cabin production to certified commissaries with dedicated halal and allergen-free lines.
Western Region
Jeddah's Umrah and Hajj charter operators generate surge demand for high-volume halal meal services exceeding standard kitchen capacity during pilgrimage peaks. The Saudi Food and Drug Authority enforces continuous cold-chain documentation mandates through its Western Province inspection protocols. King Abdulaziz International Airport hosts the kingdom's largest centralized catering complex, capturing economies of scale across multiple airline accounts.
Eastern Province
King Fahd International Airport's growing international connections are expanding commissary provisioning requirements for full-service carriers. GACA coordinates operational certifications for on-airport catering facilities under regional aviation safety frameworks. Dammam-based operators face longer supplier lead times for fresh protein inputs due to Red Sea shipping disruptions affecting port access.
NEOM Northwest
The emerging tourism and aviation hub is creating greenfield demand for catering infrastructure without legacy commissary presence. SFDA digital traceability mandates are being implemented as foundational requirements rather than retrofit obligations. Oxagon's planned airport development is attracting third-party catering operators seeking first-mover positioning in an uncrowded regulatory environment.
Taif and Secondary Hubs
Taif Regional Airport and Al-Ula's new international gateway lack dedicated HACCP-certified catering facilities, forcing refrigerated transport from Jeddah. Charter operators serving religious tourism routes require flexible surge capacity that centralized Riyadh and Jeddah kitchens struggle to provision efficiently. Newrest Group Services has extended operations into these locations, specializing in remote-site aviation catering with mobile kitchen units.
Saudi Arabia Inflight Catering Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue premium certification and digital traceability differentiation. The market exhibits moderate concentration around flag carrier-affiliated commissaries and international network operators. Three archetypes dominate: centralized national champions with airport-anchored infrastructure, global network specialists leveraging cross-border procurement scale, and niche operators targeting pilgrimage charter and private aviation segments. Competitive moves center on multi-source contract diversification and automation investments that compress SFDA compliance costs.
Within the national champion tier, Saudi Airlines Catering Company anchors domestic capacity through its King Abdulaziz International Airport complex. Gategroup and Newrest Group Services represent the global network and niche specialization archetypes respectively, with the latter extending into secondary Saudi airports where infrastructure gaps persist. These three entities exemplify how regulatory digitization and route network expansion are reshaping procurement relationships across the kingdom's aviation ecosystem.
| Leading Market Players |
|---|
| Catrion Catering Holding Company |
| Gategroup |
| Newrest Group Services |
| SATS Ltd. |
| LSG Sky Chefs |
| Saudi Airlines Catering Company |
| Emirates Flight Catering |
| Gulf Catering Company |
| Sodexo FZE |
| Others |
Pricing and Supply Chain Analysis
Fresh protein and produce inputs from European and East Asian suppliers flow through Red Sea shipping corridors into three-tier pricing structures across premium, standard, and economy meal tiers, with per-unit costs escalating at each handling stage from farm to final tray assembly at King Abdulaziz International Airport.
Pricing Analysis
Input-cost pass-through from Red Sea shipping disruptions compresses commissary margins on standard economy meal contracts while premium cabin tiers absorb volatility through fixed multi-year agreements. Price differentiation hinges on halal certification grade and volume scale, with Hajj charter operators commanding bulk discounts unavailable to ad-hoc private aviation clients. Cost compression in economy tier is intensifying because low-cost carriers are substituting buy-on-board retail for hot meal services. Flag carriers demonstrate the lowest price sensitivity; regional charter operators exhibit the highest.
Supply Chain Analysis
Direct-to-airline contracts handle hyperscale demand from Saudi flag carriers, while third-party logistics channels serve fragmented private jet and charter segments. Geographic supply concentration centers on Spain, the Netherlands, and Thailand for premium proteins and specialized galley inserts. Raw material dependencies include halal-certified poultry, temperature-stable packaging films, and European-manufactured refrigeration units. Single-source vulnerability in galley equipment manufacturing extends replacement part lead times. Distribution runs through cold-chain logistics networks anchored at King Abdulaziz and King Khalid International Airports.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's inflight catering market functions as a stable compounder, with pilgrimage-driven demand for high-volume halal meal services creating predictable revenue basins across seasonal cycles.
For Market Incumbents: Deepen backward integration into halal protein supply chains to offset Red Sea shipping volatility and secure margin control. Expand dedicated allergen-free production lines at King Abdulaziz International Airport to capture premium cabin outsourcing from full-service carriers upgrading regional fleets. SFDA digital traceability mandates threaten laggards with audit failure costs. For New Entrants and Emerging Players: Blockchain-enabled temperature logging platforms offer the lowest-friction entry path into premium carrier accounts seeking audit-ready documentation. White-space targets include Taif and Al-Ula secondary airports lacking HACCP-certified infrastructure, plus Umrah charter surge capacity during peak pilgrimage windows. Position through performance-based service level agreements rather than per-meal unit pricing. For Investors and Strategic Acquirers: Consolidation pressure builds where SFDA-certified commissary capacity concentrates in Riyadh and Jeddah while secondary airport demand grows unmet. The market supports 5-10 year holding periods anchored by infrastructure scarcity and regulatory moats. Target acquisition archetype: mid-scale operators with existing GACA certifications and mobile kitchen capabilities. Monitor SFDA blockchain mandate compliance rates as inflection indicator for operational readiness premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Upgrade | SFDA mandates drive capital allocation toward segregated production lines at King Abdulaziz International Airport. |
| Blockchain-IoT Integration | Immutable temperature logging enables premium pricing from carriers seeking audit-ready documentation. |
| Secondary Airport Expansion | Taif and Al-Ula infrastructure gaps create first-mover positions for mobile commissary operators. |
| Backward Integration | Captive halal protein supply reduces exposure to Red Sea shipping disruptions affecting port access. |
| Performance-Based Contracting | Volume guarantees tied to on-time delivery precision reshape procurement relationships with flag carriers. |
Research Methodology
Bottom-up airline procurement modeling reconciled against top-down commissary capacity tracking forms the analytical core of this study. Primary interviews with catering operations directors, SFDA compliance officers, airline procurement managers, and GACA certification specialists were cross-validated against secondary sources including SFDA regulatory filings, GACA operational bulletins, customs trade data, and airline fleet expansion disclosures. Triangulation between demand-side contract flows and supply-side kitchen infrastructure investments ensures dimensional accuracy.
Historical trendline analysis of meal production volumes and carrier fleet deployments established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include service type, cabin tier, supply chain configuration, and airport hub classification. CAGRs were derived from slope analysis of normalized production indices rather than single-point extrapolation. Forecast inputs incorporate SFDA digitization timelines, pilgrimage seasonality coefficients, and international route addition schedules.
The model assumes a particular technology adoption path; alternative pathways for blockchain-IoT cold-chain monitoring would alter the outlook if carrier compliance incentives shift. Forecasts reflect documented assumptions about regulatory implementation pace and infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Mobile Food Services Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Takeout Dinner Market
Food Service
Gas Floor Fryers Market
Food Service
Restaurant Griddle Market
Food Service
Pasteurized Eggs Market
Food Service
Commercial Rice Cooker Market
Food Service
Europe Food Service Market
Food Service
Air Fryer Market
Food Service
Europe Vending Machine Market
Food Service
Food Contract Manufacturing Market
Food Service
Commercial Grills Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Restaurant Takeout Market
Food Service
Food Truck Services Market
Food Service
Bottled Water Cooler Market