
 United States Full Service Restaurants Market | 2026-2036
United States Full Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Full Service Restaurants Market Insights
Line cook availability is collapsing across back-of-house operations, forcing operators to restructure kitchen workflows and compress menu complexity. Darden Restaurants sustains margin stability through centralized supply chain control over seafood and protein procurement. Texas Roadhouse anchors its growth in hand-cut steak preparation as a labor-intensive differentiator that resists automation. Shake Shack navigates premium burger positioning by leveraging limited menu breadth to reduce skilled labor dependency.
United States Full Service Restaurants are sit-down establishments where patrons receive table service from waitstaff, with kitchens executing made-to-order dishes across proteins, starches, and vegetables requiring temperature-controlled storage and fire-based cooking equipment; the segment serves social dining occasions, business entertainment, and celebratory gatherings through experiential hospitality rather than transactional speed. Dine-in service occupies the largest revenue pool though delivery integration now captures incremental occasion-based spending. Mid-Range pricing dominates transaction volume while Premium tier concentrates profit per cover through wine markups and protein upgrades. Italian cuisine leads cuisine-type penetration in suburban markets where family occasion frequency runs highest.
FDA food safety protocols, OSHA kitchen safety standards, and state-level alcohol beverage control frameworks collectively elevate compliance costs while restricting market access for undercapitalized entrants. The Department of Labor's tipped minimum wage regulations reshape front-of-house staffing economics across state jurisdictions with divergent base wage floors. Stakeholders must monitor labor law fragmentation between states and automation ROI thresholds as workforce scarcity forces permanent operating model recalibration.
Market Dynamics
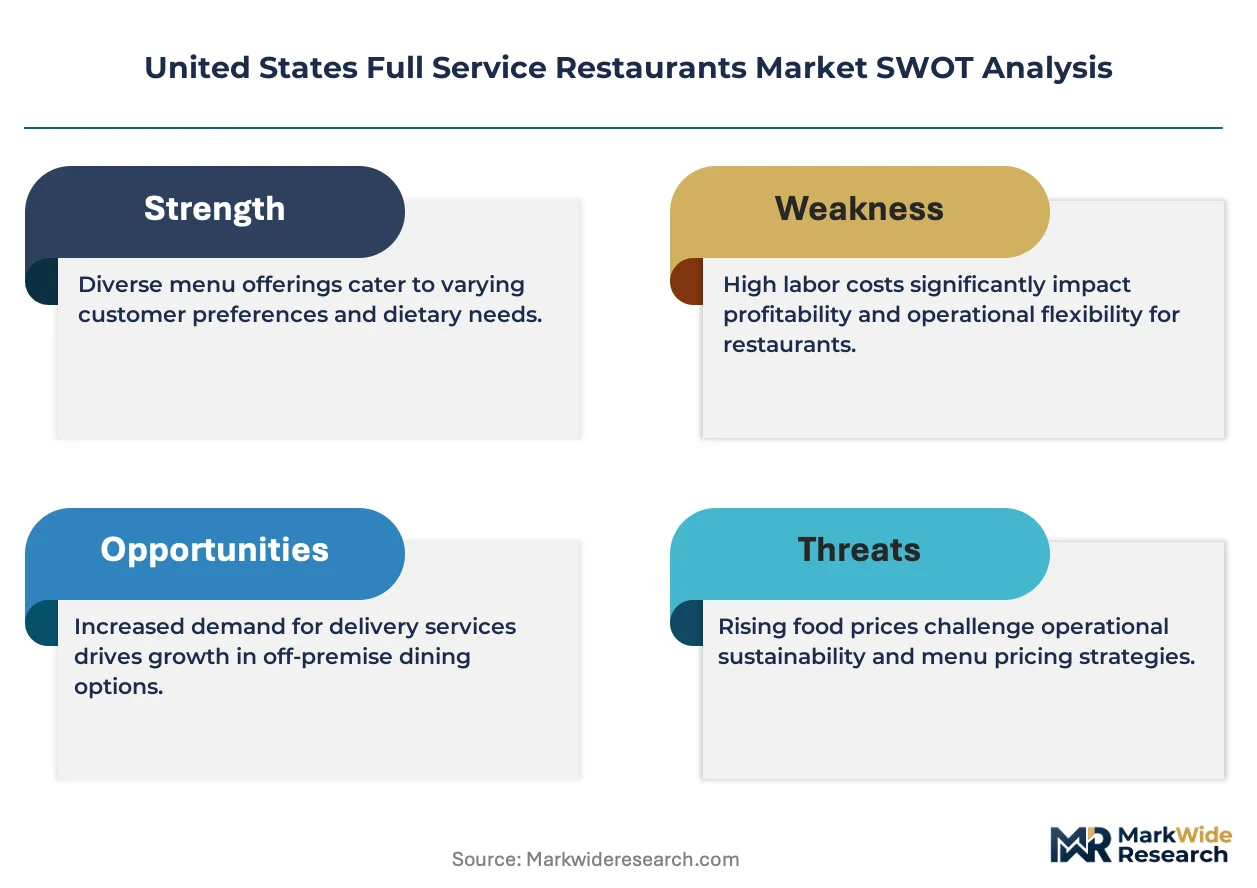
Labor scarcity across back-of-house operations is forcing permanent workflow restructuring as kitchen automation ROI thresholds compress against wage inflation and line cook availability collapses. The FDA's Food Safety Modernization Act simultaneously elevates compliance capital requirements while creating operational friction for smaller operators unable to absorb centralized supply chain investments.
Growth Catalysts
- Population Inflow Concentration:Texas, Florida, and California metropolitan corridors are expanding prime dining location demand as business groups drive rising table service requirements across urban entertainment districts.
- FSMA Compliance Investment:The FDA's Food Safety Modernization Act is reshaping kitchen equipment and HACCP protocol spending, favoring scaled operators with capital to absorb temperature-controlled storage upgrades.
- Delivery Integration:Third-party platform partnerships are capturing incremental occasion-based spending beyond traditional dine-in revenue pools, extending full-service restaurant reach into home consumption occasions.
Market Restraints
- Protein Input Volatility:Seafood and beef procurement costs fluctuate with commodity markets and climate-driven supply disruptions, compressing margin stability for mid-range operators lacking centralized purchasing power.
- OSHA Kitchen Safety Standards:Compliance with federal workplace safety protocols elevates insurance premiums and equipment retrofit costs, particularly for independent operators in older real estate footprints.
- Substitution Threat from Fast-Casual:Premium burger and steak concepts face displacement pressure from fast-casual competitors offering comparable protein quality at compressed price points with reduced service labor.
Strategic Opportunities
- Suburban Italian Cuisine Penetration:Family occasion frequency in suburban markets remains underdeveloped relative to urban cores, creating white space for experiential dining formats targeting multi-generational gatherings.
- Wine Markup Optimization:Premium tier profit per cover expansion through beverage program sophistication offers margin protection independent of protein cost cycles.
- Limited Menu Automation:Kitchen workflow compression through reduced SKU complexity enables labor model recalibration, with burger and sandwich formats demonstrating viable paths to reduced skilled cook dependency.
Industry Challenges
- Line Cook Skill Collapse:Back-of-house talent pipelines have deteriorated as culinary training program enrollment drops and wage competition from warehousing and logistics sectors intensifies.
- State Wage Law Fragmentation:The Department of Labor's tipped minimum wage regulations create front-of-house staffing economics complexity across divergent state base wage floors, complicating multi-state operator workforce planning.
- Legacy POS Integration Friction:Delivery platform API connectivity demands conflict with established point-of-sale infrastructure, requiring capital expenditure for middleware solutions that preserve kitchen display system workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Full Service Restaurants Market |
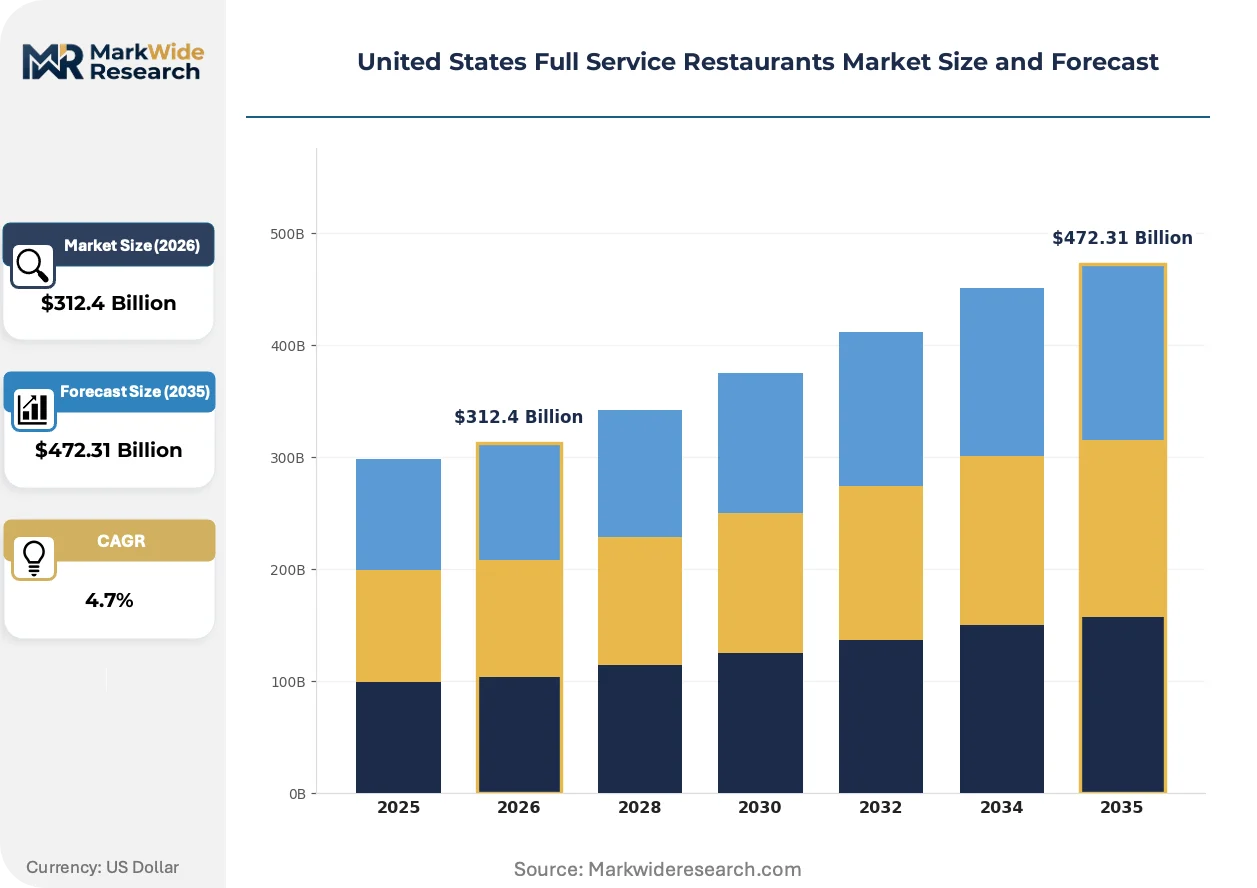
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Takeout, Delivery, Banquet Cuisine Type: Italian, Mexican, Asian, American Customer Type: Families, Couples, Business Groups, Tourists Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Darden Restaurants Inc., Texas Roadhouse Inc., Bloomin' Brands Inc., Brinker International Inc., The Cheesecake Factory Inc., Applebee's Grill + Bar, Shake Shack Inc., Red Lobster, Outback Steakhouse, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Full Service Restaurants Market Trends and Innovations
Kitchen technology deployment is accelerating as labor scarcity forces automation adoption beyond traditional quick-service boundaries. Full-service operators are reconfiguring equipment mixes and menu architecture simultaneously to capture productivity gains.
Combi-oven technology is decomposing traditional fire-based cooking station requirements by consolidating roasting, steaming, and baking functions into programmable units. Mid-range chains are deploying these systems fastest, replacing multiple single-purpose pieces with equipment that reduces skilled labor dependency while maintaining output consistency. The structural consequence is compression of back-of-house square footage requirements and reduced ventilation infrastructure capital.
The FDA's Food Safety Modernization Act is mandating enhanced traceability systems from farm to table, requiring investments in supplier documentation and temperature logging technology. Seafood and protein procurement now demands blockchain-enabled tracking platforms that smaller independents struggle to implement. Premium steakhouse segments are responding fastest, leveraging existing supplier relationships to absorb compliance costs while marketing provenance transparency as a differentiation lever.
Third-party delivery platform dependence has shifted customer acquisition economics toward commission-heavy channel structures that erode dine-in margin profiles. Full-service operators are responding with ghost kitchen formats and menu rationalization to isolate delivery-specific production from core dining room operations. Texas and Florida markets show this bifurcation most visibly, with operators maintaining separate kitchen lines for platform orders versus experiential table service.
United States Full Service Restaurants Market Segmentation
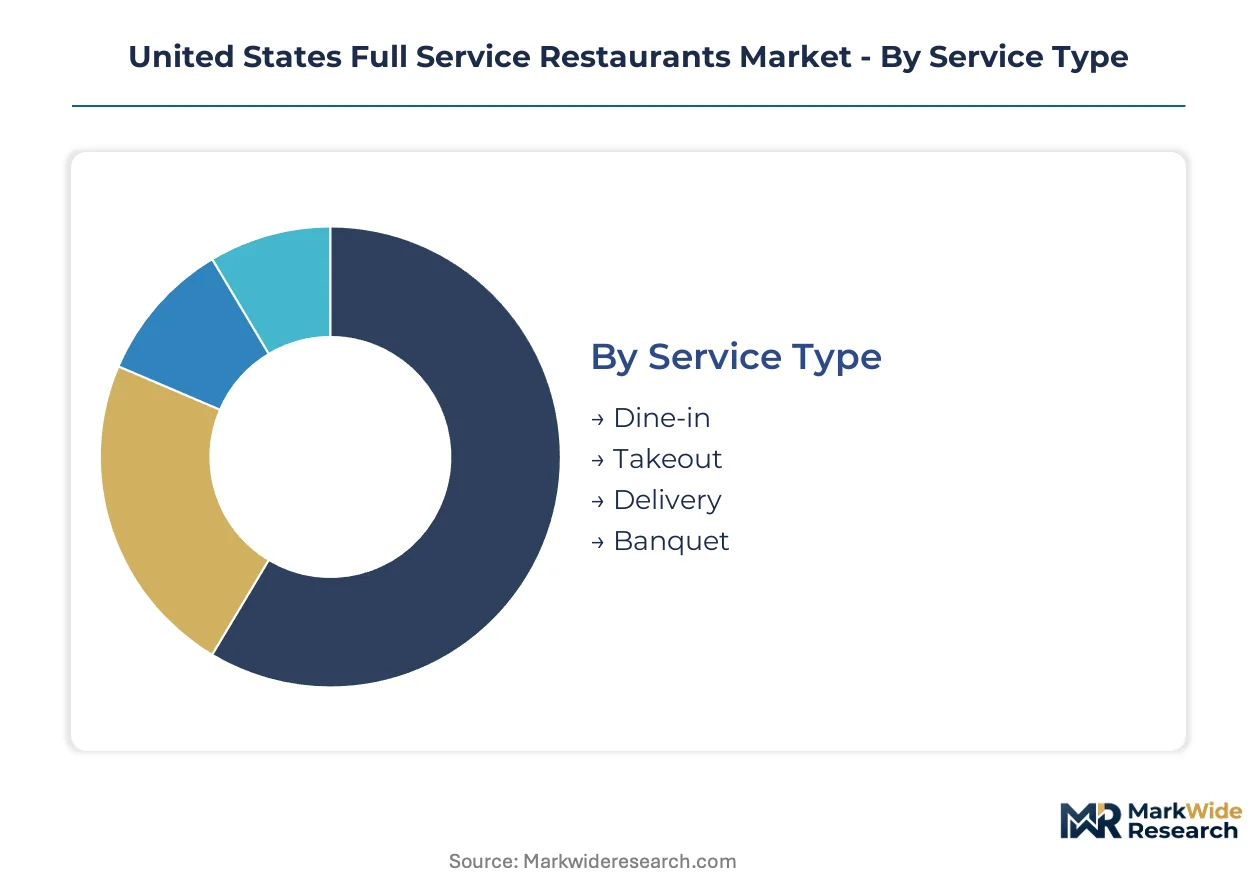
Segmentation in United States full service restaurants determines capital allocation across kitchen equipment, real estate footprints, and labor models. Each dimension carries distinct margin profiles and regulatory exposure that reshape operator strategy across metropolitan and suburban corridors.
Service Type:
Dine-in dominates domestic revenue concentration across Texas, Florida, and California metropolitan districts where business groups and celebratory occasions sustain table demand. Delivery and takeout formats expand through third-party platform integration that captures incremental home consumption spending.
- Dine-in:Traditional table service requiring full front-of-house staffing and experiential hospitality design. Demand concentrates in urban entertainment districts and suburban family corridors where occasion-based spending supports premium positioning.
- Takeout:Counter-based order fulfillment with compressed service labor requirements. Growth accelerates in office-dense submarkets where lunch occasions favor speed over atmosphere, though margin erosion from packaging costs persists.
- Delivery:Platform-mediated fulfillment isolating production from dining room operations. Commission structures from DoorDash and Uber Eats compress profitability, driving ghost kitchen proliferation in Texas and Florida markets.
- Banquet:Private event catering with advance-scheduled production cycles. Volume concentration in wedding and corporate entertainment segments stabilizes labor scheduling against walk-in volatility.
Dine-in holds the largest share; momentum sits with Delivery as platform penetration extends into tertiary markets.
Cuisine Type:
Menu architecture determines supply chain complexity, equipment specialization, and skilled labor dependency. Italian formats demonstrate lowest barrier to entry; Asian cuisines face highest back-of-house skill compression.
- Italian:Pasta and pizza production scales efficiently with reduced line cook specialization. Family occasion frequency in suburban markets sustains penetration leadership, though wine program sophistication separates premium from commodity positioning.
- Mexican:Fresh ingredient handling and fire-based cooking equipment requirements elevate kitchen capital intensity. Texas and Florida population inflows expand addressable demand for authentic regional formats.
- Asian:Wok-based cooking stations demand specialized ventilation and thermal equipment. Labor scarcity in wok technique intensifies as culinary program enrollment drops.
- American:Steak and burger formats anchor protein-forward positioning. Hand-cut preparation resists automation while supporting premium tier pricing through experiential differentiation.
Italian cuisine holds the largest share; Asian formats are expanding most quickly as metropolitan diversity intensifies.
Customer Type:
Occasion segmentation drives daypart mix, average check engineering, and beverage attachment rates. Business groups sustain weekday lunch and dinner volume; families concentrate weekend revenue.
- Families:Multi-generational dining occasions favor shareable formats and value-engineered menus. Suburban location strategy prioritizes parking accessibility and high-chair capacity over urban density.
- Couples:Date-night and celebratory occasions support premium tier pricing and wine markup optimization. Intimate seating configurations differentiate from family-oriented competitors.
- Business Groups:Corporate entertainment and team dining sustains weekday dinner volume. Private dining room requirements elevate real estate capital per cover.
- Tourists:Destination dining concentrates in Florida and California gateway markets. Seasonal volatility demands flexible staffing models distinct from resident-dependent operators.
Families hold the largest share; Business Groups are gaining share fastest as return-to-office patterns stabilize.
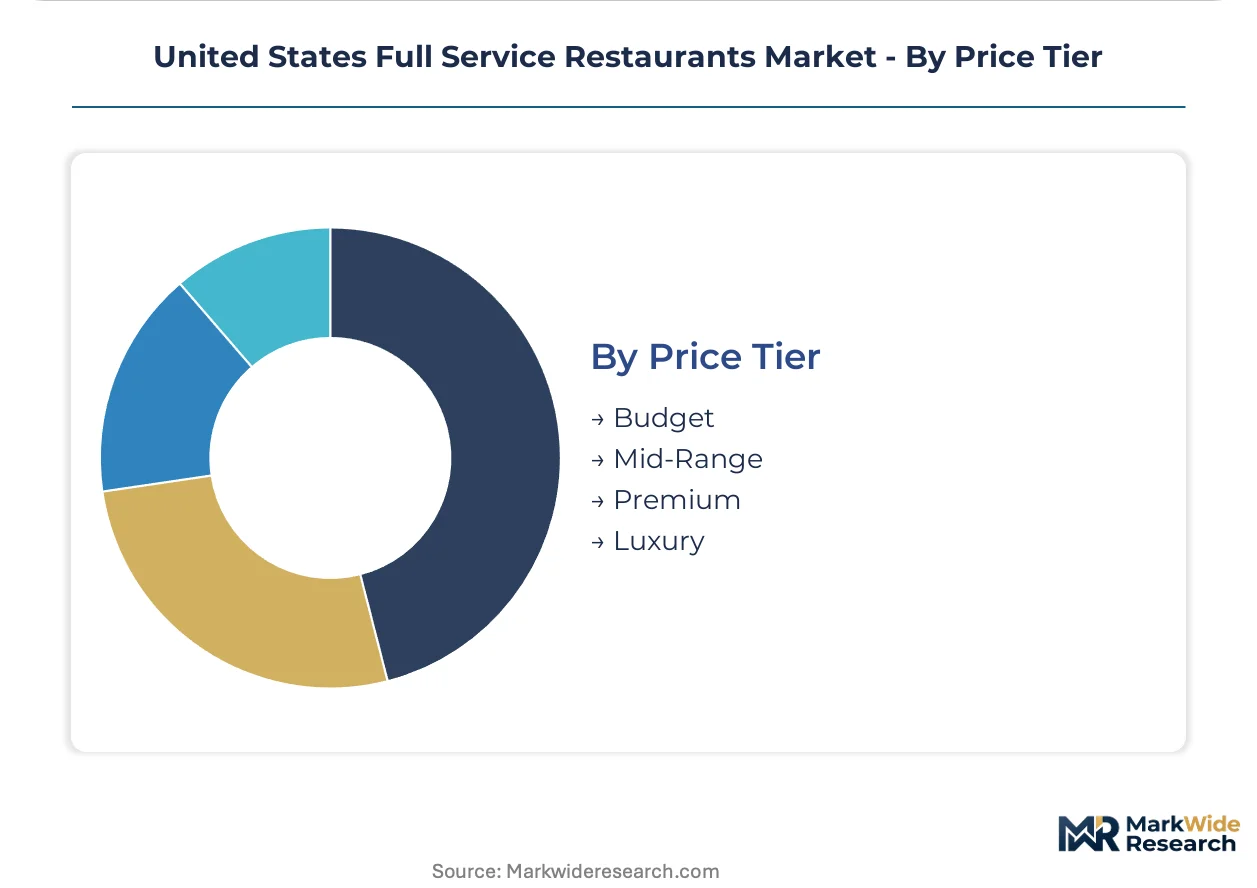
Price Tier:
Price positioning determines protein quality thresholds, beverage program investment, and front-of-house service intensity. Mid-Range volume funds scaled supply chain control; Premium tier protects margin through wine markups.
- Budget:Limited service intensity and compressed menu breadth reduce skilled labor dependency. Value positioning faces displacement pressure from fast-casual competitors with comparable price points.
- Mid-Range:Balanced experiential hospitality with standardized kitchen workflows. Darden Restaurants and similar scaled operators concentrate procurement power for margin stability.
- Premium:Protein upgrades and beverage sophistication drive profit per cover expansion. Texas Roadhouse anchors positioning through labor-intensive hand-cut differentiation.
- Luxury:Chef-driven concepts with highest skilled labor dependency and lowest automation viability. FDA Food Safety Modernization Act compliance costs favor capitalized entrants with supplier relationship depth.
Mid-Range holds the largest share; Premium tier shows the steepest expansion trajectory as occasion-based spending shifts toward experiential quality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida command premium pricing power through population inflows and business group density, while California operators absorb elevated real estate and labor costs that compress margin profiles relative to Sun Belt counterparts.
Texas
Metropolitan Dallas-Fort Worth and Houston corridors absorb corporate relocation flows that expand business group dining occasions. The Texas Alcoholic Beverage Commission maintains strict licensing frameworks that favor established operators with compliance infrastructure. Austin's entertainment district concentration anchors experiential dining formats targeting technology sector clientele.
Florida
Tourism gateway markets in Orlando and Miami sustain seasonal demand volatility requiring flexible staffing architectures. The Florida Department of Business and Professional Regulation enforces food safety protocols that elevate kitchen capital requirements for independent entrants. Tampa Bay's suburban corridor expansion creates white space for family occasion formats with parking-optimized real estate.
California
Los Angeles and San Francisco metropolitan areas concentrate premium-tier pricing through experiential hospitality differentiation. The California Department of Public Health implements CalCode standards that exceed federal baselines for temperature-controlled storage and HACCP documentation. San Diego's coastal corridor demonstrates fastest delivery platform integration with ghost kitchen proliferation isolating production from dine-in operations.
New York Metro
Manhattan's corporate entertainment density sustains weekday lunch and private dining room utilization against residential outflow pressures. The New York State Department of Health enforces strict food safety inspection cycles that elevate compliance labor allocation. Brooklyn's emerging dining corridors attract chef-driven concepts targeting celebratory occasions with intimate seating configurations.
Illinois
Chicago's central business district stabilizes weekday revenue pools through return-to-office patterns and convention traffic recovery. The Illinois Department of Public Health mandates food handler certification requirements that reshape front-of-house training economics. The West Loop's restaurant row concentration exemplifies adaptive reuse of industrial real estate for experiential dining formats.
United States Full Service Restaurants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States Full Service Restaurants Market. Scaled multi-brand operators concentrate procurement power and supply chain control, while single-concept specialists anchor differentiation through experiential hospitality design. The competitive structure fragments across three strategic archetypes: centralized supply chain operators, labor-intensive experiential differentiators, and limited-menu automation adopters. Dominant competitive moves include ghost kitchen format expansion for delivery isolation and wine program sophistication for margin protection independent of protein cost cycles.
Within the scaled multi-brand tier, Darden Restaurants Inc. and Bloomin' Brands Inc. exemplify centralized procurement architectures that stabilize margin profiles against commodity volatility. Texas Roadhouse Inc. occupies a distinct position as a labor-intensive experiential differentiator, while Shake Shack Inc. represents the limited-menu automation path that reduces skilled cook dependency. These three company structures illustrate the strategic archetype segmentation reshaping competitive positioning across metropolitan and suburban corridors.
| Leading Market Players |
|---|
| Darden Restaurants Inc. |
| Texas Roadhouse Inc. |
| Bloomin' Brands Inc. |
| Brinker International Inc. |
| The Cheesecake Factory Inc. |
| Applebee's Grill + Bar |
| Shake Shack Inc. |
| Red Lobster |
| Outback Steakhouse |
| Others |
Pricing and Supply Chain Analysis
Long-term protein procurement contracts lock in supply access and price visibility for scaled operators while exposing independents to spot market volatility. Darden Restaurants and Bloomin' Brands leverage centralized purchasing power to compress beef and seafood input costs against commodity swings.
Pricing Analysis
The customization-premium spread separates hand-cut steak preparation from standardized protein formats across the Mid-Range and Premium tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein grade and wine program sophistication. Cost compression in the Budget tier intensifies because fast-casual competitors deliver comparable quality at reduced service labor. Families exhibit highest price sensitivity; Business Groups demonstrate lowest sensitivity due to corporate entertainment budgets.
Supply Chain Analysis
Domestic beef processing concentration in Nebraska, Kansas, and Texas underwrites margin stability for steakhouse chains with direct packer relationships. Protein procurement draws from commodity livestock markets and climate-affected seafood landing zones. Single-source vulnerability in premium beef grading creates exposure when drought conditions contract fed cattle supply. Distribution runs through broadline foodservice distributors with regional cold chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Full Service Restaurants Market tracks a cyclical recovery as return-to-office patterns stabilize business group dining frequency and suburban family occasion spending rebounds from pandemic-era compression.
For Market Incumbents: Fortify margin stability through backward integration into protein processing and centralized supply chain control over seafood procurement. Darden Restaurants exemplifies this architecture. Channel control through owned delivery infrastructure counters third-party platform commission erosion. Certification investment in FDA Food Safety Modernization Act compliance creates regulatory moats against undercapitalized competitors.
For New Entrants and Emerging Players: Anchor in suburban Italian cuisine penetration where family occasion frequency runs highest and parking-optimized real estate remains available. The most penetrable geography clusters in Tampa Bay and Austin corridor expansion zones. Ghost kitchen formats targeting delivery-specific production offer capital-light entry with reduced front-of-house staffing requirements.
For Investors and Strategic Acquirers: Scaled multi-brand operators with supply chain control technology represent the primary acquisition target archetype for portfolio margin stabilization. Long-term viability over the coming decade hinges on automation ROI thresholds compressing against persistent line cook scarcity. The signal to watch is kitchen equipment deployment velocity as labor cost inflation accelerates workflow restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Format Expansion | Isolates delivery production from dine-in operations, preserving experiential hospitality margin profiles. |
| Wine Program Sophistication | Expands profit per cover independent of protein cost cycles through markup optimization. |
| Combi-Oven Technology Deployment | Consolidates roasting, steaming, and baking functions to reduce skilled cook dependency. |
| Blockchain Traceability Investment | Meets FDA Food Safety Modernization Act documentation requirements for seafood and protein sourcing. |
| Limited Menu Rationalization | Compresses SKU complexity to enable labor model recalibration in burger and sandwich formats. |
Research Methodology
Desk research of SEC 10-K filings, foodservice distributor trade data, and FDA enforcement records preceded structured interviews with multi-unit restaurant operators, supply chain procurement directors, and kitchen equipment manufacturers. Primary fieldwork with back-of-house managers and front-of-house staffing consultants validated labor scarcity patterns and automation adoption timelines. Secondary sources included National Restaurant Association operational surveys, Bureau of Labor Statistics wage data, and state health department inspection protocols. Bottom-up location-level revenue modeling and top-down national market sizing underwent cross-validation.
Variance decomposition across service type, cuisine format, price tier, and metropolitan corridor density shaped the analytical framework. Segmentation dimensions modeled included dine-in versus delivery channel mix, protein-forward versus pasta-based menu architecture, and suburban versus urban real estate footprint. CAGRs derived from historical location expansion rates, per-cover spending trajectories, and platform commission structure evolution. Forecast inputs incorporated tipped minimum wage regulatory shifts and third-party delivery penetration saturation curves.
Decision-makers should treat outputs as directional under assumptions of stable population inflow patterns and continued business group dining normalization; material deviation in remote work permanence or protein commodity spikes would warrant model refresh. Practitioners should keep alternative scenarios live as labor law fragmentation between states and automation technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Philippines Foodservice Market
Food Service
Clear Ice Maker Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Commercial Rice Cooker Market
Food Service
Qatar Food Service Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Air Fryer Meal Kits Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Onboard Rail Catering Market
Food Service
Snack Subscription Box Service Market
Food Service
Online Grocery Market
Food Service
Catering Food Warmers Market
Food Service
France Foodservice Market