
 Germany Household Side by Side Refrigerator Market | 2026-2036
Germany Household Side by Side Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Household Side by Side Refrigerator Market Insights
Apartment dwellers is rotating toward share leadership as Germany's urban housing stock densifies and kitchen footprints contract. Bosch Group leverages its embedded position in German builder channels to sustain volume through new-construction specifications. Liebherr-Hausgeräte Ochsenhausen GmbH anchors the premium tier with commercial-grade cooling heritage repurposed for residential estates. Samsung competes through connected-kitchen ecosystems that extend software touchpoints beyond the appliance itself.
A household side by side refrigerator consists of two vertically split compartments with independent temperature zones, typically employing inverter compressors and polyurethane foam insulation to maintain 0-4°C refrigeration and -18°C freezing capacities across 500-700 liter volumes. The primary purpose centers on segregated fresh and frozen food storage for multi-person households requiring high-throughput kitchen operations. Energy Efficient models capture the fastest replacement demand as EU energy labeling revisions push A+++ thresholds higher and consumers recalculate lifetime electricity costs. Smart connectivity segments occupy emerging margin pools through subscription-enabled features and predictive maintenance interfaces, though penetration remains nascent relative to standard configurations. Families continue dominating absolute unit demand, while Singles and Seniors represent underdeveloped addressable bases with diverging feature requirements.
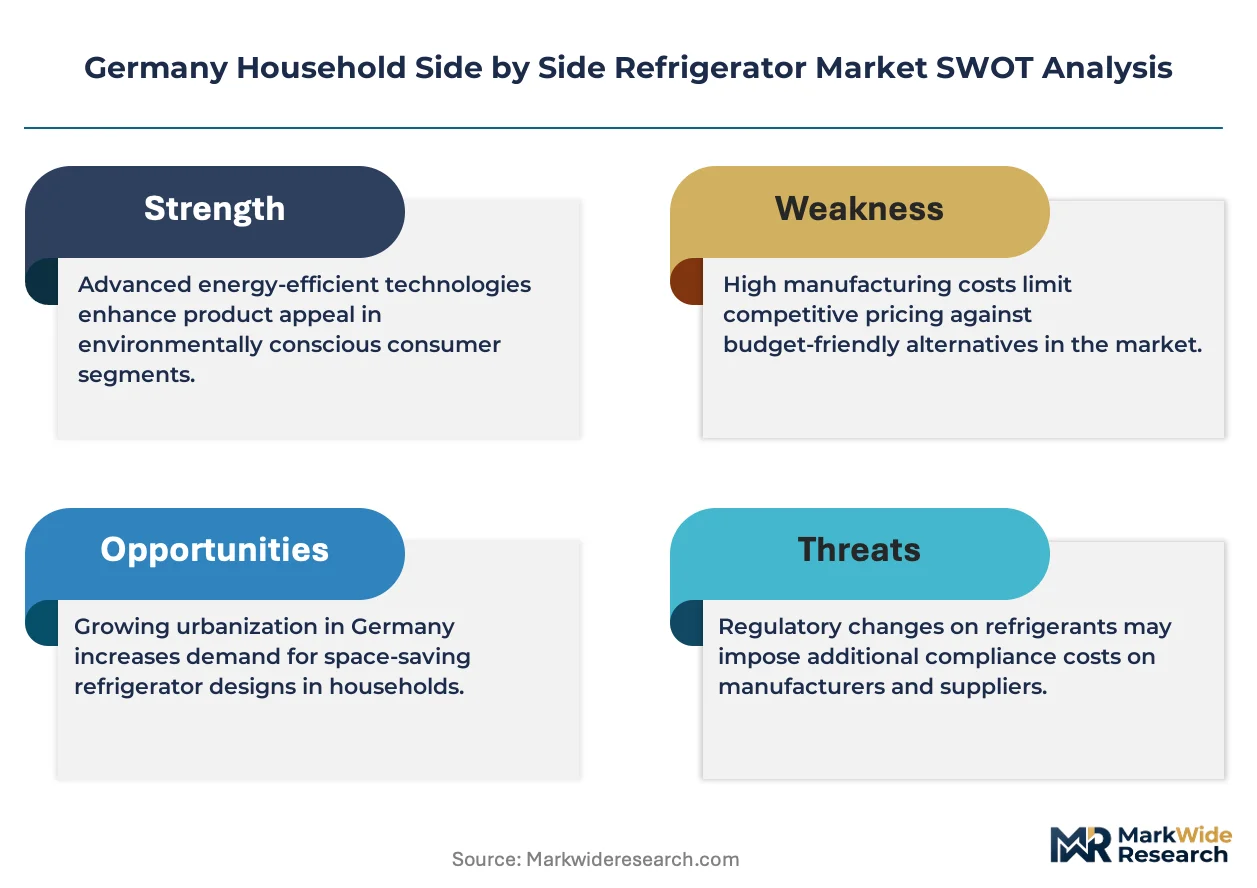
The EU F-Gas Regulation and Germany's national Energielabel system constrain refrigerant choices and minimum efficiency performance, effectively raising compliance costs for import-dependent suppliers. KBA-adjacent supply chain standards for transport refrigeration create technology spillover effects that domestic manufacturers exploit for household product differentiation. Stakeholders must monitor how the EU AI Act and pending cybersecurity certification frameworks reshape smart appliance data governance obligations and liability allocation across OEMs and platform providers.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets and forcing wholesale platform redesigns across German manufacturing footprints. Appliance OEMs must retool compressor architectures and insulation systems simultaneously as A+++ energy labeling thresholds ratchet higher.
Growth Catalysts
- Apartment densification:Urban household formation in Berlin and Munich is tilting toward sub-60-square-meter units. Compact side-by-side formats with 500-550 liter capacities capture this structural demand shift.
- Energieeffizienzlabel upgrades:Germany's national efficiency labeling system now penalizes C-grade and below appliances at point-of-sale. Retailers accelerate A+++ and A++++ inventory turns to avoid stranded stock.
- Inverter compressor diffusion:Variable-speed drive technology cuts energy consumption by 30-40% versus fixed-speed alternatives. Bavarian and North Rhine-Westphalian households prioritize lifetime electricity cost calculations over upfront purchase price.
Market Restraints
- Polyurethane foam input volatility:Isocyanate and polyol feedstock prices swing with crude oil and natural gas benchmarks. German insulation suppliers pass through 60-70% of commodity spikes within one quarter.
- Compressor supply concentration:Two Asian manufacturing clusters control 80% of global inverter compressor output. German OEMs face extended lead times and allocation risk during peak construction seasons.
- Substitution by bottom-freezer formats:French-door and bottom-freezer configurations occupy identical price bands with smaller footprints. Single-person households in Hamburg and Frankfurt increasingly select these alternatives.
Strategic Opportunities
- Smart appliance data monetization:Connected refrigeration platforms generate usage telemetry for predictive maintenance and food inventory management. Subscription-enabled feature unlocks create recurring revenue streams beyond hardware margins.
- Senior household retrofit demand:Germans aged 65+ represent 22% of the population with above-average homeownership rates. Large-format side-by-side units with ergonomic drawer configurations and voice interfaces address accessibility gaps in this underserved segment.
- Heat pump refrigeration convergence:Integration with residential heat pump systems enables waste heat recovery for water pre-heating. Building energy management system compatibility positions premium units as whole-home efficiency assets.
Industry Challenges
- Cybersecurity certification complexity:The EU AI Act and pending EN 303 645 standards impose data governance obligations on smart appliance OEMs. German manufacturers must reallocate engineering resources from feature development to compliance documentation.
- Refrigerant transition capex intensity:R600a and R290 hydrocarbon systems require production line reconfiguration and technician retraining. Domestic facilities face 18-24 month payback periods on platform conversion investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Household Side by Side Refrigerator Market |
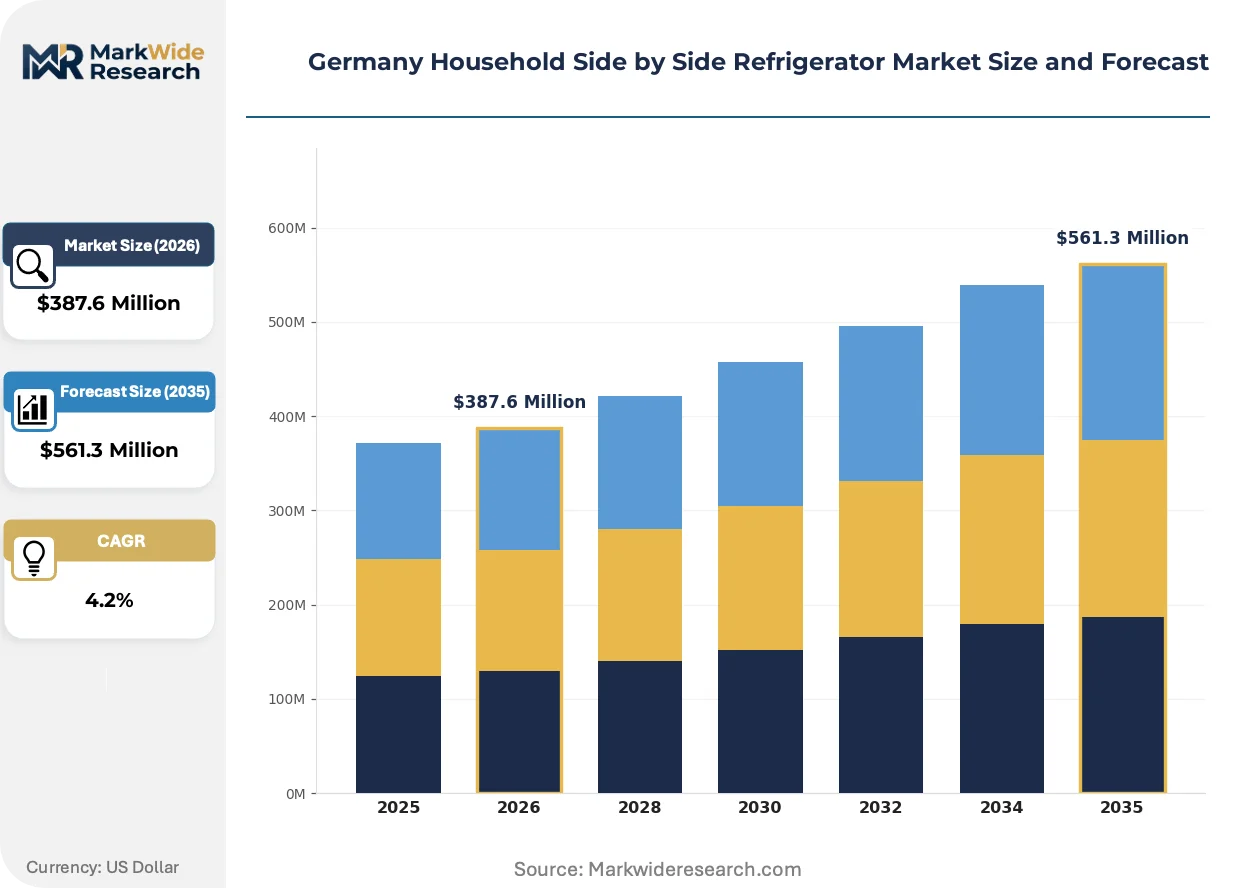
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $561.3 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Smart, Energy Efficient, Compact End User: Families, Singles, Apartment Dwellers, Seniors Feature: Water Dispenser, Ice Maker, Adjustable Shelves, LED Lighting Distribution Channel: Online Stores, Retail Shops, Appliance Showrooms, Wholesale |
| Companies Covered | Siemens AG, Bosch Group, Samsung, Bauknecht Hausgeräte GmbH, Liebherr-Hausgeräte Ochsenhausen GmbH, AB Electrolux, LG Electronics, Whirlpool Corporation, Haier Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Household Side by Side Refrigerator Market Trends and Innovations
Refrigeration technology is splitting along efficiency-versus-connectivity axes as German buyers polarize between electricity cost minimizers and kitchen ecosystem integrators. This divergence is reshaping R&D allocation and channel positioning simultaneously.
Variable-capacity inverter compressors is bifurcating the efficiency-performance frontier. Energy-conscious buyers in Stuttgart and Düsseldorf specify these systems for 15-year total cost of ownership optimization. Standard fixed-speed configurations are compressing into entry price tiers as inverter penetration crosses 60% of premium segment volume.
The EU F-Gas Regulation mandates 95% phase-down of hydrofluorocarbon refrigerants by 2030. German manufacturers accelerate hydrocarbon and CO2 transcritical system development for residential scale. North American and Asian import brands face compliance cost disadvantages against domestic producers with KBA-adjacent transport refrigeration expertise.
Apartment dwellers are consolidating food purchasing into weekly bulk formats. This consumption pattern elevates throughput capacity and organizational shelf design in purchase criteria. Urban retail channels in Berlin and Munich now feature 600+ liter compact-depth side-by-side units as standard showroom configurations.
Germany Household Side by Side Refrigerator Market Segmentation
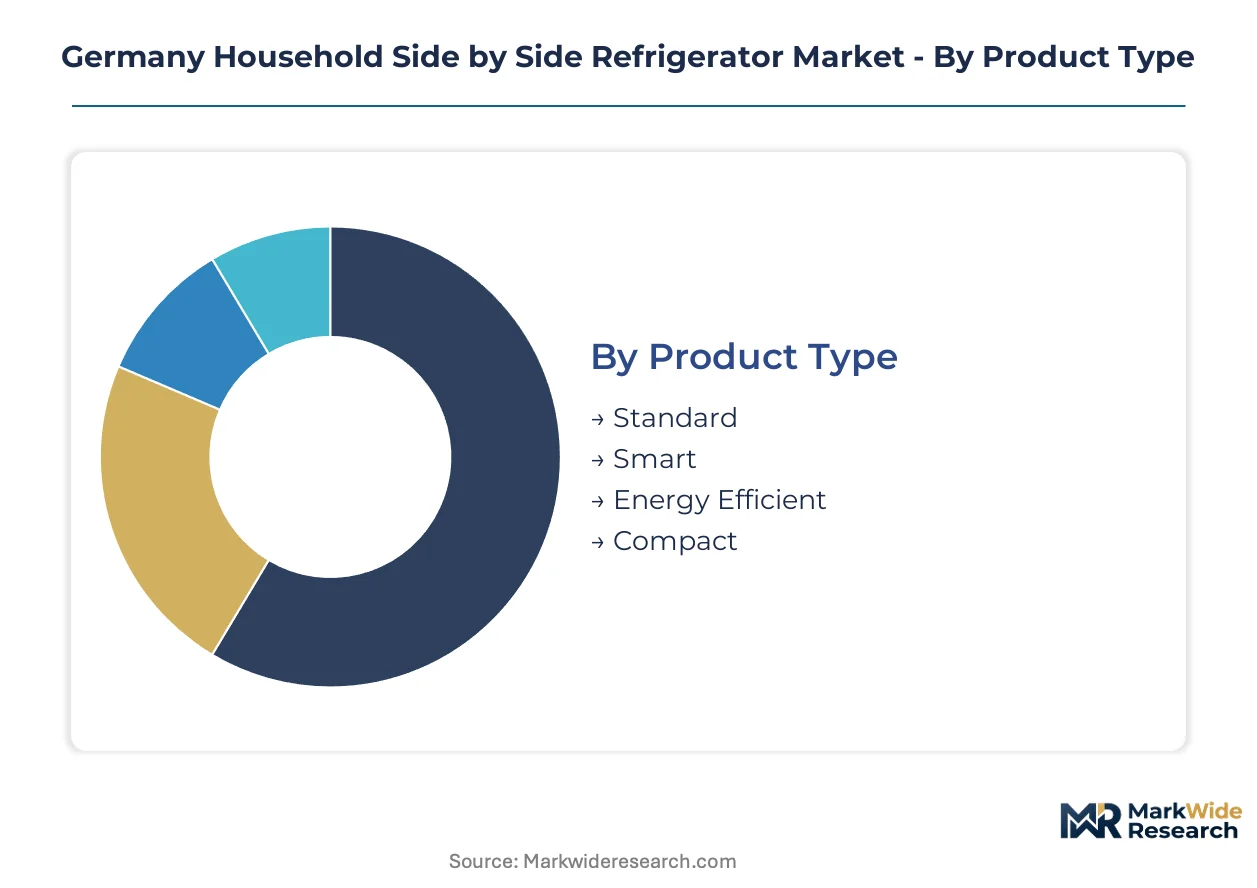
German households exhibit divergent refrigeration requirements based on housing stock characteristics, household composition, and energy cost sensitivity. The EU F-Gas Regulation and Energielabel thresholds create compliance-driven stratification that reshapes segment trajectories differently across product configurations and buyer archetypes.
Product Type:
The EU F-Gas Regulation mandates refrigerant phase-downs that disproportionately burden specific platform architectures, forcing manufacturers to prioritize certain efficiency tiers over others.
- Standard:Fixed-speed compressor systems with conventional polyurethane foam insulation dominate replacement cycles in rural and suburban households. North Rhine-Westphalian municipalities with older housing stock sustain volume through retrofit demand.
- Energy Efficient:Inverter compressor platforms with vacuum-insulated panels achieve A+++ and A++++ ratings under Germany's Energielabel system. Bavarian households prioritize 15-year total electricity cost calculations over upfront purchase price.
- Smart:WiFi-enabled units with predictive maintenance interfaces and food inventory management.
- Compact:500-550 liter capacity formats engineered for sub-60-square-meter urban apartments.
Energy Efficient handles the majority of throughput; Compact is climbing the fastest on share.
End User:
Household formation patterns in Berlin and Munich are tilting toward smaller living units that reshape capacity and feature requirements across buyer archetypes.
- Families:Multi-person households requiring 600+ liter throughput capacity for bulk food storage and high-frequency kitchen operations. Demand concentrates in Bavaria and Baden-Württemberg where larger average household sizes sustain premium uptake.
- Apartment Dwellers:Urban renters and owners in dense housing stock prioritizing compact footprints and organizational shelf design. Weekly bulk purchasing patterns elevate 600+ liter compact-depth configurations in Berlin and Munich showrooms.
- Singles:One-person households in Hamburg and Frankfurt increasingly selecting French-door alternatives.
- Seniors:Germans aged 65+ with above-average homeownership rates and accessibility requirements.
Families anchor absolute unit demand; Apartment Dwellers is expanding most quickly as urban densification accelerates.
Feature:
Margin pools concentrate in features that reduce food waste or integrate with connected-kitchen ecosystems, though penetration varies sharply by household technology adoption profiles.
- Water Dispenser:Integrated filtration systems with external access doors. Premium segment positioning in Stuttgart and Düsseldorf where convenience features justify price premiums.
- Ice Maker:Automatic production with storage bins and crush functions.
- Adjustable Shelves:Modular interior configurations accommodating varying container dimensions and bulk items.
- LED Lighting:Low-heat illumination reducing energy consumption versus incandescent alternatives.
Water Dispenser commands the highest feature attach rate; Adjustable Shelves is gaining share fastest through universal applicability across household types.
Distribution Channel:
Channel economics in Germany reflect the country's dual retail structure combining concentrated specialist chains with fragmented independent operators.
- Retail Shops:Electronics and home improvement chains with national footprint and Energielabel-compliant inventory management. Retailers accelerate A+++ and A++++ turns to avoid stranded stock from efficiency regulation tightening.
- Appliance Showrooms:Specialist dealers with consultation-heavy purchase journeys and builder channel relationships. Bavarian and North Rhine-Westphalian locations sustain premium positioning through specification influence in new construction.
- Online Stores:E-commerce platforms with price transparency and delivery logistics.
- Wholesale:Volume contracts with property developers and housing associations.
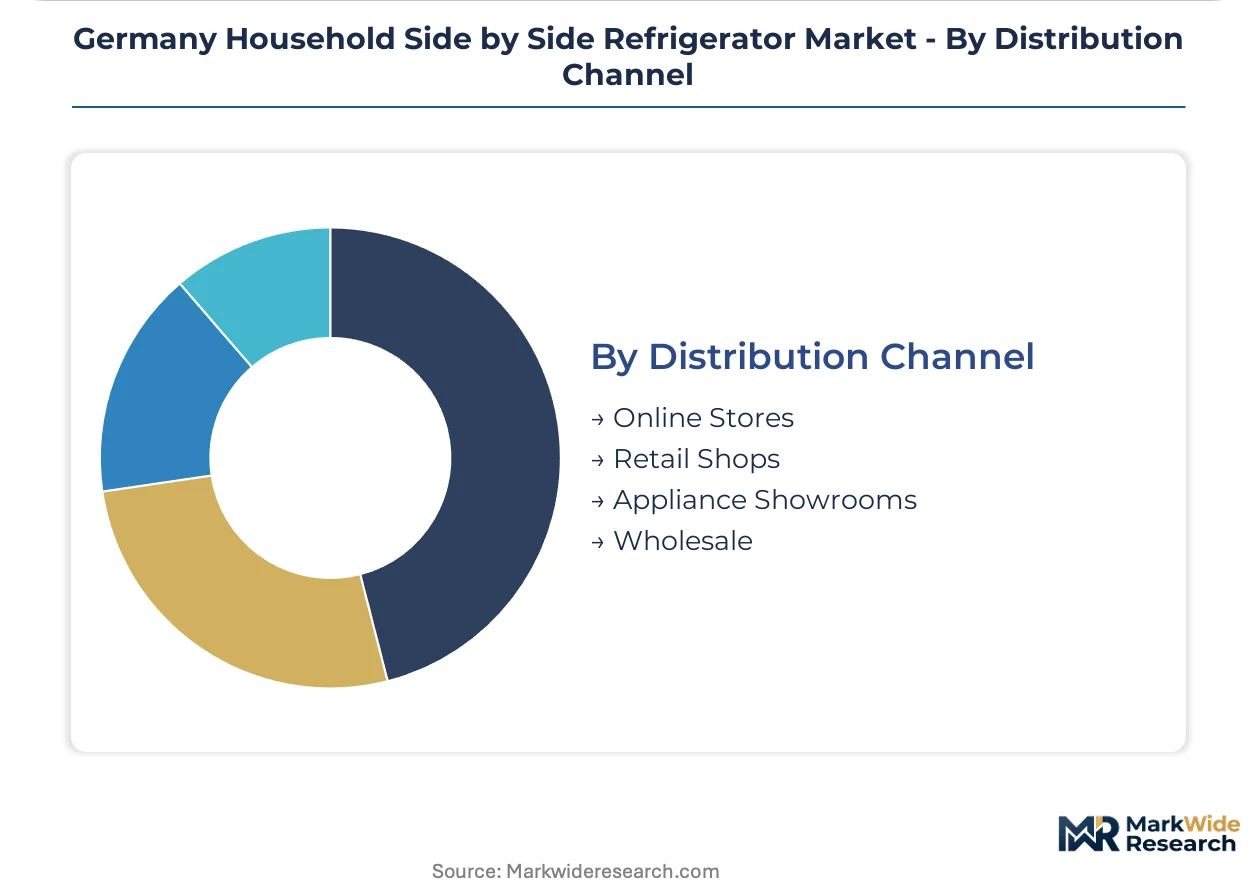
Retail Shops handles the majority of throughput; Online Stores is expanding most quickly on share as delivery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway and Germany's dense autobahn network enable efficient appliance distribution from manufacturing clusters to population centers. Bavaria and North Rhine-Westphalia concentrate production capacity alongside consumer demand. Federal efficiency mandates reshape regional replacement cycles unevenly across state housing stocks.
Bavaria
Munich's premium housing market sustains demand for A+++ rated units with advanced insulation. The state's Energieberatung programs subsidize efficiency upgrades in older buildings. Ingolstadt and Nuremberg manufacturing corridors anchor domestic production of inverter compressor platforms.
North Rhine-Westphalia
Cologne and Düsseldorf metropolitan areas exhibit the highest per-capita side-by-side penetration in Germany. The KBA's transport refrigeration standards create technology spillover advantages for local OEMs. Ruhr Valley industrial heritage supports specialized polyurethane foam supply chains.
Baden-Württemberg
Stuttgart's affluent suburbs prioritize 15-year total cost of ownership calculations over purchase price. The state's Ministry of Environment enforces stricter refrigerant handling protocols than federal minimums. Karlsruhe and Mannheim form a corridor of smart appliance software development.
Berlin-Brandenburg
Apartment densification in Berlin proper drives compact-format demand above national averages. The city's Senatsverwaltung für Umwelt mandates building energy certificates that accelerate appliance replacement. Potsdam and surrounding commuter zones exhibit growing family household formation.
Hamburg
Port logistics infrastructure enables rapid import clearance for Asian appliance brands. The city's high single-person household density favors French-door alternatives over traditional side-by-side configurations. HafenCity redevelopment incorporates smart building specifications for premium kitchen installations.
Germany Household Side by Side Refrigerator Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized domestic manufacturers. The vendor base splits between integrated appliance groups with builder channel access and premium specialists with commercial cooling heritage. Two strategic archetypes dominate: scale-driven platforms leveraging procurement volume, and differentiation-focused players emphasizing craftsmanship credentials. Competitive moves center on smart ecosystem integration and refrigerant platform transitions ahead of EU F-Gas deadlines.
Within the domestic specialist tier, Liebherr-Hausgeräte Ochsenhausen GmbH and Bauknecht Hausgeräte GmbH exemplify engineering-centric positioning rooted in German manufacturing tradition. Bosch Group anchors the diversified conglomerate archetype with embedded distribution through national retail and construction channels. Samsung represents the connected-ecosystem challenger, competing through software touchpoints that extend beyond hardware specifications.
| Leading Market Players |
|---|
| Siemens AG |
| Bosch Group |
| Samsung |
| Bauknecht Hausgeräte GmbH |
| Liebherr-Hausgeräte Ochsenhausen GmbH |
| AB Electrolux |
| LG Electronics |
| Whirlpool Corporation |
| Haier Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German OEMs and polyurethane foam suppliers lock in insulation material access while capping price volatility exposure for premium tier production. These arrangements bind Bavarian and North Rhine-Westphalian manufacturers to indexed pricing clauses that track isocyanate and polyol feedstock movements.
Pricing Analysis
Volume-discount tiering structures separate A+++ rated inverter compressor platforms from fixed-speed C-grade alternatives, with efficiency certification grade and regional delivery cost as primary differentiation drivers. Pricing pressure stems from Asian import brands compressing mid-market margins through aggressive channel pricing. Apartment dwellers exhibit highest price sensitivity due to constrained kitchen footprints, while family households in Stuttgart prioritize 15-year electricity cost calculations over upfront purchase price.
Supply Chain Analysis
Inventory lead times for inverter compressors now stretch across two Asian manufacturing clusters controlling most global variable-speed drive output. German assembly draws from Chinese and South Korean compressor sources, with polyurethane foam feedstocks anchored in domestic Ruhr Valley chemical corridors. Single-source vulnerability concentrates in semiconductor-based inverter control modules. Distribution runs through national electronics chains and specialist appliance showrooms with builder channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against French-door and bottom-freezer configurations that capture single-person household demand in Hamburg and Frankfurt. Incumbents must differentiate side-by-side throughput capacity and organizational shelf design to retain family segment loyalty.
For Market Incumbents: Consolidate inverter compressor supply relationships through capacity reservation agreements with Asian manufacturing clusters to secure allocation during peak construction seasons. Deepen builder channel specification influence in Bavarian and North Rhine-Westphalian new construction to preempt substitution by alternative formats. Prioritize A+++ and A++++ certification investment as Energielabel thresholds tighten. For New Entrants and Emerging Players: Anchor in senior household retrofit demand across Germans aged 65+ with above-average homeownership rates, where accessibility-focused large-format units remain underserved. Target Berlin-Brandenburg apartment densification with compact-depth 600+ liter configurations that accommodate weekly bulk purchasing patterns. Pursue wholesale contracts with housing associations for standardized premium installations. For Investors and Strategic Acquirers: Domestic specialists with commercial cooling heritage and KBA-adjacent transport refrigeration expertise represent attractive acquisition targets as EU F-Gas Regulation compliance costs rise. Long-term viability hinges on hydrocarbon refrigerant platform conversion completion and smart appliance data monetization infrastructure. Monitor EN 303 645 cybersecurity certification progress as inflection indicator for connected-feature margin realization.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Conversion | R600a and R290 hydrocarbon system deployment satisfies EU F-Gas Regulation phase-down mandates ahead of deadlines. |
| Inverter Compressor Supply Agreement | Long-term contracts with Asian manufacturing clusters mitigate allocation risk during German construction peaks. |
| Smart Connectivity Infrastructure | Predictive maintenance interfaces and food inventory management unlock subscription revenue beyond hardware margins. |
| Builder Channel Specification | New-construction relationships in Bavaria and North Rhine-Westphalia secure premium tier volume through embedded positioning. |
| Senior Accessibility Retrofit | Ergonomic drawer configurations and voice interfaces address unmet demand among Germans aged 65+ with homeownership. |
Research Methodology
The analysis maps product type configurations, end user archetypes, feature attachments, and distribution channels, each validated through appliance manufacturer product managers, retail category buyers, and polyurethane foam procurement leads. Primary interview findings triangulate against customs records, KBA transport refrigeration standards documentation, and Energielabel registry databases. Bottom-up unit shipment estimates reconcile with top-down household penetration models across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including regional housing formation data and electricity tariff trajectories. The analytical framework models segmentation across efficiency tiers, household composition, capacity formats, and smart feature penetration throughout the forecast period. CAGRs derive from replacement cycle acceleration under EU F-Gas Regulation and urban densification patterns in Berlin and Munich.
Decision-makers should treat outputs as directional under assumptions of continued Energielabel threshold tightening and apartment dweller share expansion; material deviation in refrigerant transition timelines or construction activity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Washing Machine Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Residential Washing Machine Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
US Household Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Small Home Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Merchandizing Refrigerators Market