
 Colombia Home Appliances Market | 2026-2036
Colombia Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Home Appliances Market Outlook
Urban middle-class households is reorganizing demand patterns across the Colombia Home Appliances Market, displacing traditional rural-first purchasing sequences. Samsung Electronics leverages its integrated semiconductor and display supply chain to dominate premium refrigerator and air conditioner segments. Whirlpool Corporation anchors its position through extensive service networks and localized assembly operations near Barranquilla. LG Electronics differentiates via inverter compressor technology leadership and aggressive financing partnerships with Colombian retail chains.
Colombia Home Appliances encompass electrically powered mechanical devices designed for domestic tasks, typically operating at 110V/60Hz with energy consumption ratings certified under local technical regulations. These products incorporate refrigerant circuits, induction heating elements, or brushless motor systems to perform food preservation, garment cleaning, thermal comfort, or meal preparation functions. Refrigerators command the largest value share due to universal household penetration and replacement-driven demand, while air conditioners represent the fastest-expanding category as cooling degree days rise across Andean and Caribbean zones. The distribution channel structure tilts toward specialty stores and supermarket chains, though online platforms capture accelerating traffic from price-tier comparison shoppers seeking mid-range and economy positioning.
Colombia's Ministerio de Minas y Energía enforces appliance energy labeling through the Unidad de Planeación Minero Energética, compressing demand toward inverter and A-rated equipment. The Superintendencia de Industria y Comercio monitors consumer protection compliance and warranty enforcement, elevating service infrastructure as a competitive barrier. Local technical standards aligned with ICONTEC certification requirements shape import eligibility and manufacturing specifications for both domestic assembly and direct shipment models. Stakeholders must monitor regulatory tightening on refrigerant transitions and e-waste recovery obligations as these frameworks mature.
Market Dynamics
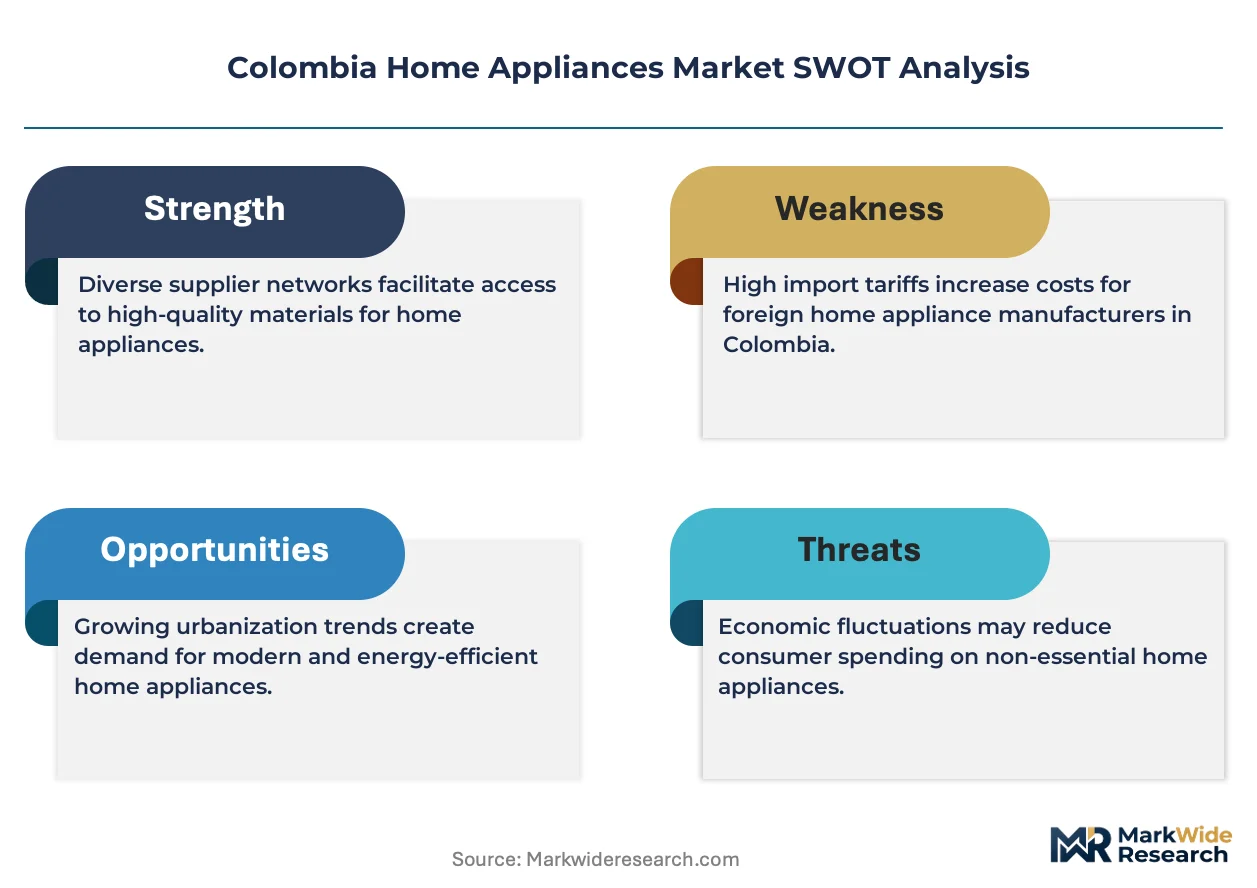
Colombia's Unidad de Planeación Minero Energética labeling mandates are compressing demand toward inverter-equipped and A-rated equipment, forcing manufacturers to accelerate refrigerant transitions and service infrastructure investments across Andean and Caribbean zones.
Growth Catalysts
- Energy Efficiency Mandates:The Unidad de Planeación Minero Energética certification program creates replacement pull toward inverter compressors and variable-speed motor systems in refrigeration and climate control categories.
- Urban Middle-Class Expansion:Household formation in Bogotá, Medellín, and Cali generates first-time ownership and upgrade cycles for multi-door refrigerators and split-system air conditioners.
- Retail Credit Penetration:Colombian retail chains now embed appliance financing into point-of-sale systems, collapsing payment friction for mid-range equipment purchases.
Market Restraints
- Copper and Steel Input Volatility:Compressor housings and cabinet frames face raw material cost swings that manufacturers cannot fully pass through in price-sensitive segments.
- Import Concentration Risk:Finished goods and component supply routes through Cartagena and Buenaventura create exposure to Pacific and Caribbean shipping disruptions.
- Refrigerant Transition Friction:The phasedown of hydrofluorocarbons under evolving national regulations forces simultaneous R&D and inventory obsolescence costs.
Strategic Opportunities
- Secondary City Penetration:Barranquilla, Bucaramanga, and Pereira exhibit underpenetrated air conditioner ownership relative to cooling degree-day exposure.
- E-Waste Recovery Mandates:Anticipated extended producer responsibility frameworks will reward early movers with certified recycling networks and refurbishment capabilities.
- Smart Appliance Integration:Convergence of inverter hardware with Wi-Fi connectivity modules enables remote diagnostics and predictive maintenance service models.
Industry Challenges
- Certification Timeline Compression:ICONTEC testing protocols for new refrigerant chemistries and inverter control systems extend product launch windows.
- Service Technician Scarcity:Refrigerant handling certification and inverter electronics repair skills lag installed base growth, particularly outside major metropolitan zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Home Appliances Market |
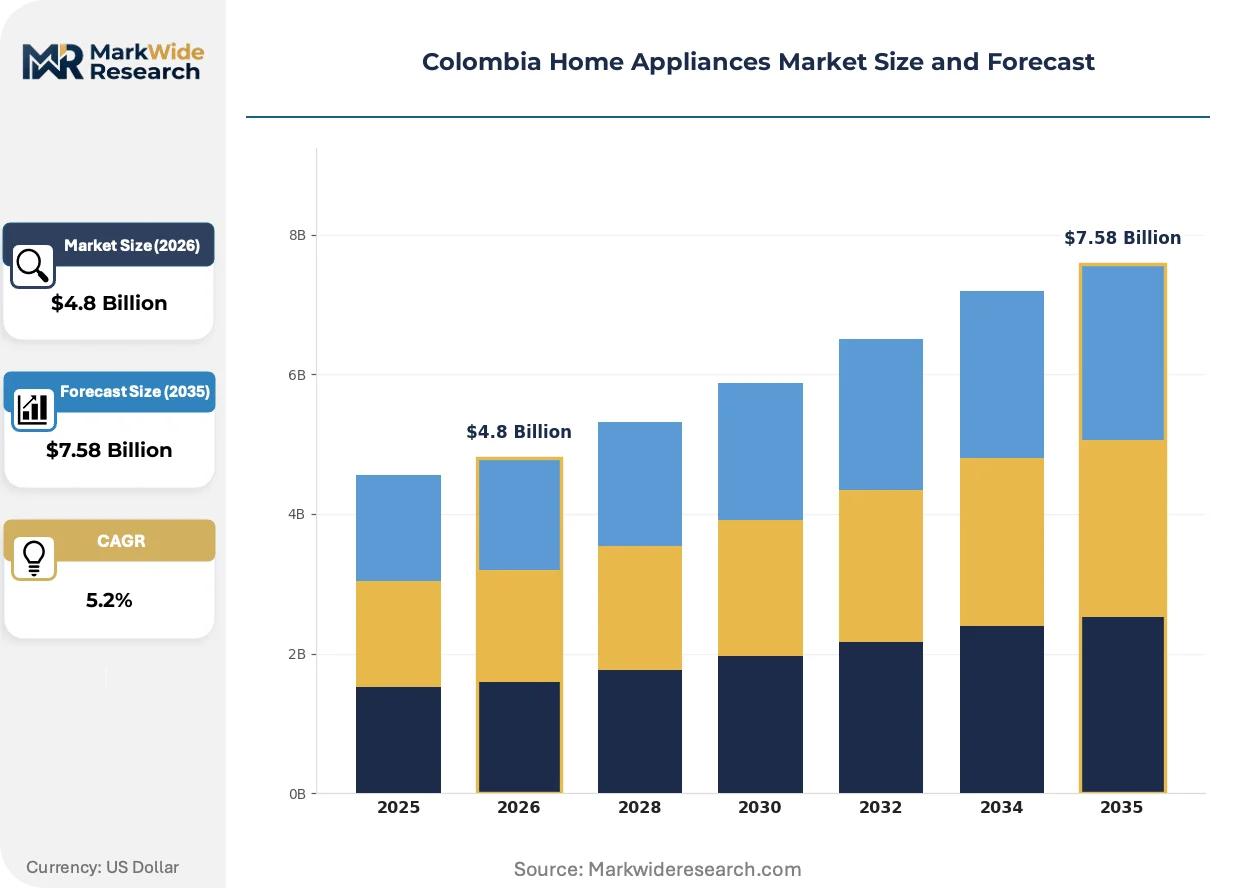
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwave Ovens, Air Conditioners End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Samsung Electronics, Arcelik AS, Whirlpool Corporation, Panasonic Corporation, BSH Hausgeräte GmbH, Electrolux AB, Haier Electronics Group Co. Ltd, Mitsubishi Electric Corporation, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Home Appliances Market Strategic Shifts
Inverter compressor platforms and connected diagnostics are redrawing competitive boundaries, compressing margins on conventional fixed-speed equipment while opening service-revenue streams for integrated manufacturers.
Inverter-driven variable-speed compression is bifurcating the refrigeration and climate-control segments. Urban middle-class households in Bogotá and Medellín now treat inverter labeling as a baseline filter, collapsing demand for fixed-speed alternatives. This technology compression is eliminating second-tier assemblers lacking semiconductor partnerships or captive compressor sourcing.
The Unidad de Planeación Minero Energética tightens energy labeling thresholds every three years, forcing manufacturers to redesign control systems and insulation packages. Industrial consequence falls heaviest on import-dependent distributors without localized engineering capabilities. Air conditioner categories face the steepest compliance gradients, driving accelerated R&D partnerships between Korean manufacturers and Colombian assembly operations.
Colombian retail chains now unbundle after-sales service from product pricing, shifting warranty fulfillment to manufacturer-certified technicians rather than store-employed repair staff. This channel restructuring compresses distributor margins while elevating service infrastructure as a purchase determinant. The pattern is most visible in Medellín and Cali, where specialty retailers compete on installation speed and refrigerant leak coverage rather than upfront discounts.
Colombia Home Appliances Market Segmentation
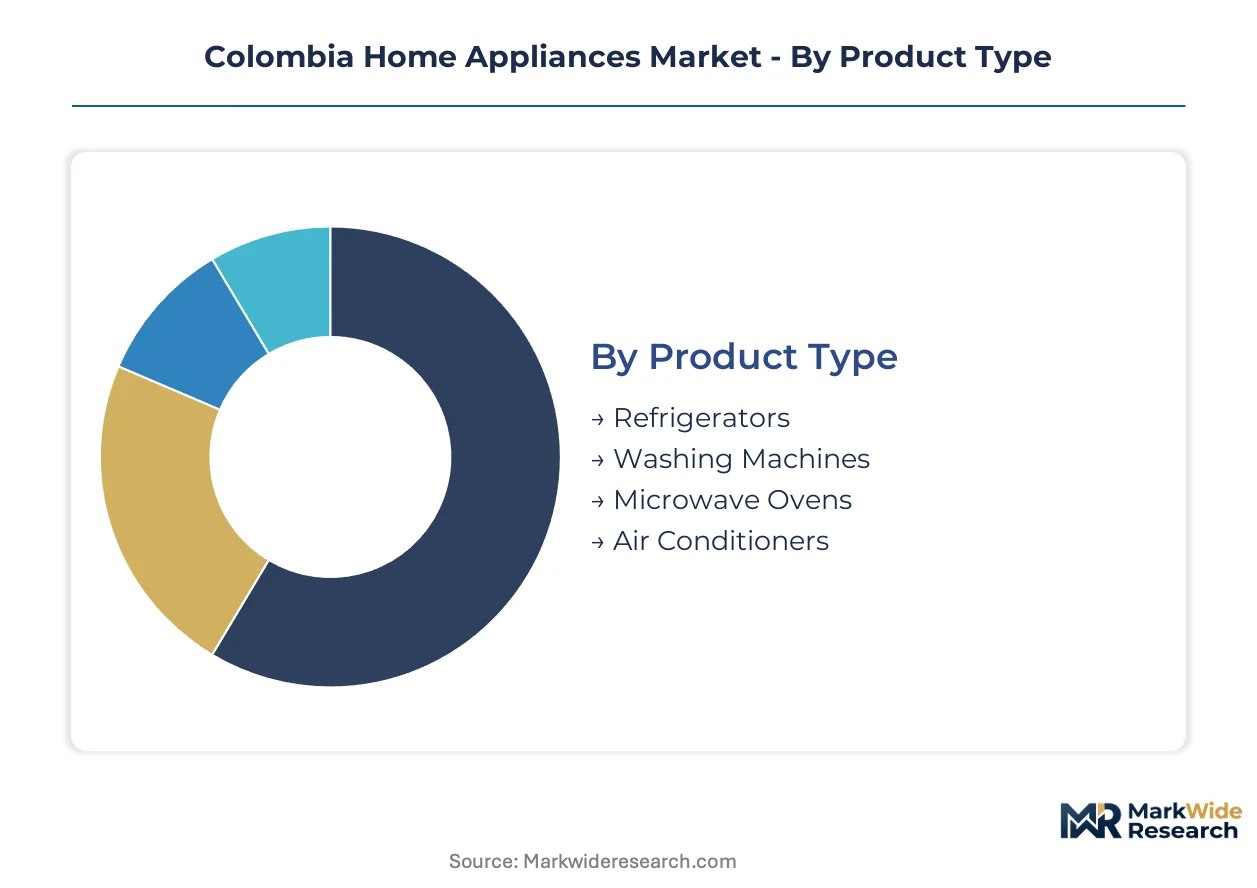
Segmentation reveals how Unidad de Planeación Minero Energética labeling mandates and urban credit penetration differentially shape demand across product categories and buyer profiles. Understanding these splits enables targeted positioning toward replacement cycles versus first-time ownership opportunities.
Product Type:
Domestic assembly concentrates on refrigeration and climate control, while washing machines and microwave ovens rely more heavily on direct import routes through Cartagena and Buenaventura.
- Refrigerators:Multi-door and inverter-compressor configurations dominate urban middle-class replacement demand in Bogotá and Medellín, where energy efficiency ratings function as baseline purchase filters. The category absorbs the bulk of localized assembly investment near Barranquilla due to volume scale and refrigerant handling requirements.
- Air Conditioners:Split-system inverter units are expanding most quickly across Andean and Caribbean zones as cooling degree days rise and UPME thresholds tighten. Bucaramanga and Pereira exhibit significant underpenetration relative to thermal exposure, creating white-space opportunity for penetration-focused entrants.
- Washing Machines:Front-loading drum designs with variable-speed motor systems are displacing top-loading alternatives in credit-enabled urban households.
- Microwave Ovens:Inverter-based flatbed models compete against conventional turntable designs on countertop space efficiency and energy labeling scores.
Refrigerators command the established base. The steepest expansion runs through Air Conditioners.
End User:
Residential demand concentrates in owner-occupied urban housing, while commercial and hospitality segments drive volume through project-based procurement with extended payment terms.
- Residential:Household formation in Bogotá, Medellín, and Cali generates replacement cycles for multi-door refrigeration and first-time air conditioner installations, with financing embedded at point-of-sale collapsing payment friction for mid-range equipment tiers.
- Commercial:Office and food-service operators in Cartagena and Barranquilla prioritize inverter climate control for operating cost containment under escalating electricity tariffs.
- Hospitality:Hotel development along Caribbean coastlines drives project-scale procurement of mini-bar refrigeration and ducted air conditioning systems.
- Retail:Appliance retail chains themselves constitute a distinct end-use segment for climate control and food preservation equipment in display and storage applications.
Residential segment anchors volume concentration. Hospitality is gaining share fastest on coastal development activity.
Distribution Channel:
Channel structure tilts toward physical retail in climate-control categories requiring installation coordination, while online platforms capture accelerating traffic in replacement-driven segments with standardized specifications.
- Specialty Stores:Installation speed and refrigerant leak coverage differentiate competitors in Medellín and Cali, where warranty fulfillment has shifted to manufacturer-certified technicians rather than store-employed repair staff.
- Supermarkets:Hypermarket chains in Bogotá embed financing partnerships and promotional bundling to drive traffic in compact refrigeration and microwave categories.
- Online:Price-tier comparison shoppers seeking mid-range and economy positioning increasingly validate specifications through digital platforms before fulfillment.
- Direct Sales:Project-scale hospitality and commercial procurement bypass retail markup through manufacturer-direct negotiation on volume commitments.
Specialty stores retain the installed base relationship. Online channels are climbing the fastest on price transparency and comparison functionality.
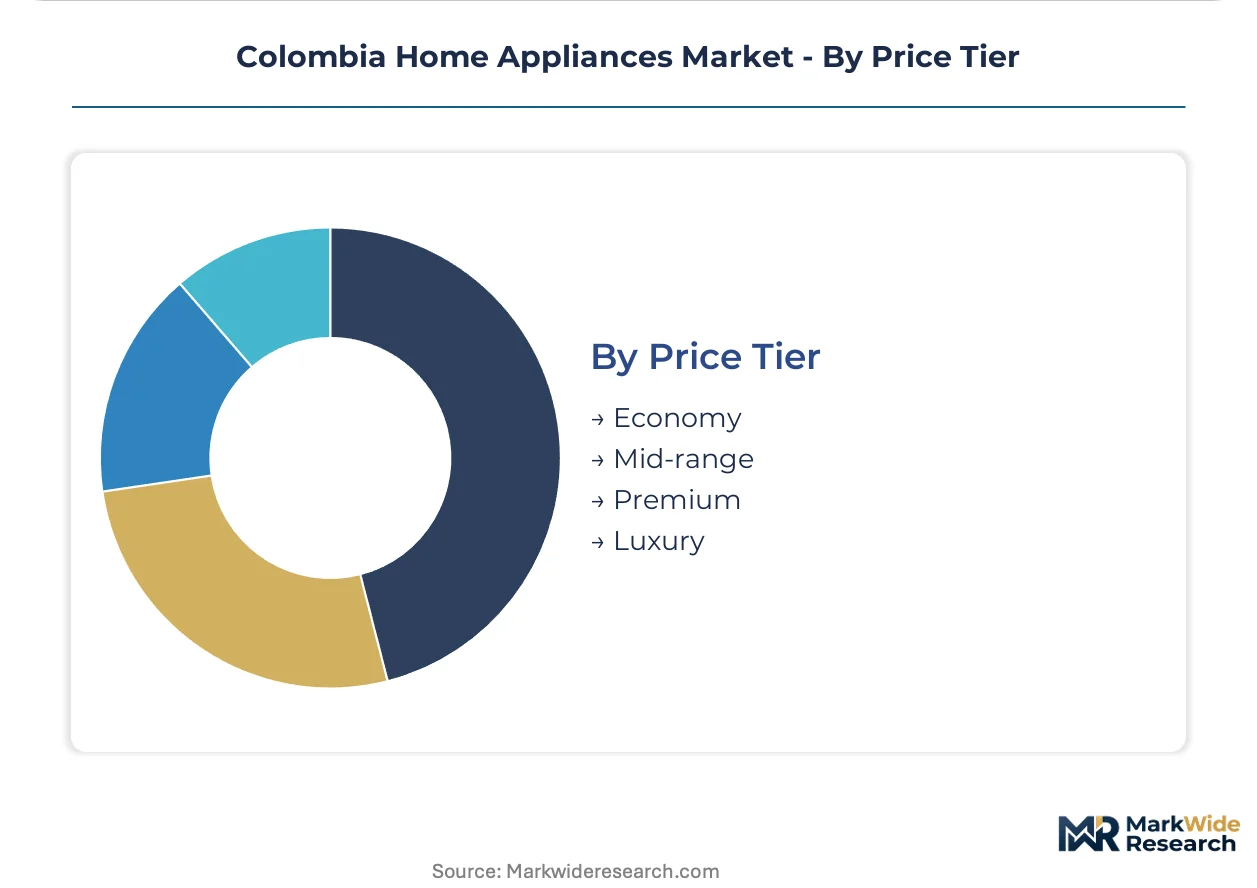
Price Tier:
Pricing stratification reflects energy labeling grade, inverter technology inclusion, and service infrastructure attachment rather than purely cosmetic differentiation.
- Premium:Inverter-equipped multi-door refrigeration and connected climate control systems target urban middle-class households treating A-rated UPME labels as non-negotiable baseline filters.
- Mid-range:Single-compressor inverter refrigerators and basic split-system air conditioners balance efficiency compliance with credit-accessible payment structures.
- Economy:Fixed-speed alternatives face demand compression as labeling mandates tighten, concentrating residual volume in rural electrification zones and rental housing replacement cycles.
- Luxury:Built-in refrigeration columns and multi-zone climate control systems address high-end residential construction in Bogotá's northern districts.
Mid-range tier captures the broadest household access. Premium positioning is expanding most quickly on efficiency mandate compliance and replacement cycle upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Caribbean port of Cartagena anchors Colombia's appliance import infrastructure, handling finished goods and compressor components bound for assembly operations near Barranquilla and distribution networks spanning the Andean interior.
Bogotá Capital District
Household formation in Usaquén and Chapinero drives replacement cycles for multi-door inverter refrigerators and first-time split-system air conditioner installations. The Unidad de Planeación Minero Energética enforces A-rated labeling thresholds that filter purchase decisions toward variable-speed compression platforms. Specialty retailers in the northern districts compete on manufacturer-certified installation speed rather than upfront discounts.
Medellín Metropolitan Area
Credit-enabled middle-class expansion in Envigado and El Poblado generates upgrade demand for front-loading washing machines with variable-speed motor systems. The Superintendencia de Industria y Comercio monitors warranty enforcement, elevating service infrastructure as a competitive barrier. Assembly operations in the Aburrá Valley concentrate on refrigeration cabinet fabrication for regional distribution.
Cali and Valle del Cauca
Rising cooling degree days across the Cauca River valley accelerate split-system air conditioner penetration in owner-occupied housing. The Ministerio de Minas y Energía refrigerant transition mandates force simultaneous R&D and inventory management adjustments. Yumbo hosts compressor testing facilities serving Andean climate-control equipment certification.
Barranquilla and Atlántico
Localized refrigerator assembly leverages port proximity to reduce finished goods logistics costs for Caribbean zone distribution. Electrification rate disparities between urban and peri-urban zones create tiered demand for economy versus inverter-equipped product lines. The municipality's industrial corridor hosts cabinet stamping and insulation injection operations.
Bucaramanga and Santander
Underpenetrated air conditioner ownership relative to thermal exposure creates white-space opportunity for penetration-focused entrants in Floridablanca and Piedecuesta. Retail credit penetration lags Bogotá and Medellín, compressing mid-range equipment accessibility. The region's mining-linked household income volatility shapes replacement cycle timing.
Colombia Home Appliances Market Competitive Environment
Concentration sits with diversified electronics conglomerates possessing captive semiconductor and compressor supply chains. Korean and Japanese manufacturers anchor premium positioning through inverter technology leadership and integrated component sourcing. European majors compete via localized assembly scale and extended service networks. Strategic moves center on refrigerant transition R&D partnerships and point-of-sale financing integration with Colombian retail chains.
Among Korean-based diversified electronics groups, Samsung Electronics and LG Electronics exemplify the integrated conglomerate archetype through captive display and semiconductor supply chain control. Whirlpool Corporation represents the Western multinational assembly model with localized operations near Caribbean port infrastructure. BSH Hausgeräte GmbH occupies a position within the European precision-engineering tier, while Haier Electronics Group Co. Ltd anchors Chinese manufacturing scale in the mid-range equipment segment. Arcelik AS exemplifies regional specialist positioning with Turkey-to-Latin America manufacturing transfer capabilities.
| Leading Market Players |
|---|
| Samsung Electronics |
| Arcelik AS |
| Whirlpool Corporation |
| Panasonic Corporation |
| BSH Hausgeräte GmbH |
| Electrolux AB |
| Haier Electronics Group Co. Ltd |
| Mitsubishi Electric Corporation |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
Inverter compressor substitution for fixed-speed motors simultaneously redraws supply geography toward East Asian semiconductor corridors and compresses pricing economics across Colombian distribution tiers. This component transition forces manufacturers to absorb semiconductor sourcing premiums while UPME labeling mandates prevent full cost pass-through to price-sensitive economy segments.
Pricing Analysis
Volume-discount tiering structures stratify across premium inverter-equipped, standard single-compressor, and economy fixed-speed equipment levels. Price differentiation hinges on UPME certification grade and manufacturer-certified service bundling. Pricing pressure intensifies in mid-range tiers as Korean conglomerates leverage captive compressor production to undercut import-dependent distributors. Rural electrification zones exhibit highest price sensitivity, while Bogotá's northern districts show lowest elasticity for A-rated labeling compliance.
Supply Chain Analysis
China and South Korea anchor inverter compressor and control module fabrication for Colombian-bound climate-control equipment. Raw material dependencies center on copper for compressor housings, steel for cabinet frames, and refrigerant chemistries subject to phasedown timelines. Supply chain risk concentrates in Pacific and Caribbean shipping chokepoints through Cartagena and Buenaventura. Distribution runs through manufacturer-certified technician networks that unbundle installation from retail pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Colombia Home Appliances Market sits in a replacement-cycle recovery phase, with UPME labeling mandates accelerating equipment turnover beyond natural obsolescence timelines.
For Market Incumbents: Secure refrigerant transition R&D partnerships with Colombian assembly operations before ICONTEC certification windows compress. Lock in point-of-sale financing integration with retail chains to defend against Korean manufacturers' captive semiconductor cost advantages. Prioritize service technician certification pipelines in Bucaramanga and Pereira where scarcity threatens installed base support.
For New Entrants and Emerging Players: Anchor in secondary city air conditioner penetration where cooling degree-day exposure exceeds ownership rates. Target hospitality project procurement along Caribbean coastlines with ducted system offerings bypassing retail markup structures. Pursue manufacturer-direct negotiation models with volume commitment pricing to displace established distribution relationships.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors assembly-scale specialists with localized engineering capabilities. Long-term viability across the projection horizon rests on e-waste recovery network certification and refurbishment infrastructure. Monitor refrigerant inventory obsolescence announcements as inflection indicators for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Platform Localization | UPME certification compliance accelerates demand capture in Bogotá and Medellín replacement cycles. |
| Refrigerant Transition Partnership | ICONTEC testing protocol alignment compresses product launch windows for climate-control categories. |
| Retail Financing Integration | Point-of-sale credit embedding collapses payment friction for mid-range equipment tiers. |
| Secondary City Service Expansion | Technician certification pipelines in Bucaramanga address scarcity threatening penetration growth. |
| E-Waste Recovery Certification | Extended producer responsibility frameworks reward early movers with refurbishment capabilities. |
Study Parameters
Desk research of customs trade records, UPME certification databases, and retail audit data preceded structured interviews with appliance category buyers, manufacturer regional directors, compressor procurement leads, and service network operators. Primary fieldwork across Bogotá, Medellín, and Barranquilla validated secondary estimates through bottom-up shipment analysis and top-down household penetration modeling.
Variance decomposition across product type, price tier, distribution channel, and regional electrification rate shaped the analytical framework throughout the forecast period. CAGRs derived from replacement cycle timing, credit penetration curves, and regulatory compliance phase-in schedules. Forecast inputs incorporated cooling degree-day projections and refrigerant transition cost assumptions without year-specific anchoring.
Material uncertainties — copper and steel input volatility, Pacific shipping disruptions, and refrigerant chemistry approval delays — sit outside the modeled envelope. Forecasts reflect assumptions documented in segmentation splits and stakeholder interview triangulation. Recalibration cycles align with material shifts in UPME labeling threshold announcements and port infrastructure capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
US Household Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
North America Electric Fireplace Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Australia Washing Machine Market
Home Appliances
North America Built-In Home Appliances Market