
 Residential Washing Machine Market | 2026-2036
Residential Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Washing Machine Market Intelligence
Apartment-complex developers and property-management firms is restructuring procurement patterns across the residential washing machine value chain. LG Electronics Inc. leverages its inverter-direct-drive technology to anchor premium positioning in urban multi-unit housing. Samsung Electronics Co. Ltd. competes through smart-ecosystem integration that extends appliance control into home-automation platforms. Haier Smart Home Co. Ltd. dominates compact and combo washer-dryer formats through manufacturing scale that sustains cost leadership in space-constrained Asian cities.
A residential washing machine is an electromechanical appliance designed for automated textile cleaning through programmed cycles of agitation, rinsing, and spin-drying, typically operating at drum speeds between 800 and 1600 revolutions per minute and rated for energy and water consumption per kilogram of load. Front-load configurations command the highest margin pools due to superior water efficiency and gentler fabric handling, while compact washers capture the fastest-growing structural segment as micro-living trends proliferate in dense metropolitan cores. Smart technology integration, encompassing Wi-Fi connectivity and AI-driven load sensing, is shifting from premium novelty toward baseline expectation across mid-tier distribution channels.
The US Department of Energy enforces minimum efficiency standards that disqualify conventional top-load agitator models from federal rebate programs, while the EU Ecodesign Directive and Energy Labeling Framework progressively tighten maximum allowable water and electricity consumption thresholds. China's MIIT implements dual-carbon-aligned efficiency grades that restrict market access for non-inverter motor designs. Stakeholders must monitor how fragmented national efficiency regimes reshape component sourcing and whether regulatory divergence between North American and European test protocols fragments product-platform strategies.
Market Dynamics
Inverter-motor technology is compressing the mid-tier product range as efficiency mandates from India's BIS and China's MIIT disqualify conventional agitator designs from incentive programs and rebate eligibility.
Growth Catalysts
- India's BIS energy-labeling mandates:Procurement officers in Mumbai and Delhi apartment complexes now specify inverter-motor units exclusively, eliminating semi-automatic inventory from developer specifications.
- Water-scarcity regulations:Municipal conservation ordinances in São Paulo and Cape Town are forcing household upgrades from top-load agitators to front-load platforms that cut consumption per cycle.
- Micro-living proliferation:Compact washer-dryer combos are capturing new-build installations in Tokyo, Seoul, and Singapore where floor space per unit has fallen below 35 square meters.
Market Restraints
- Copper and rare-earth magnet costs:Inverter-motor production depends on neodymium supply concentrated in Chinese processing facilities, exposing OEMs to input price volatility.
- EU Ecodesign Directive test-protocol divergence:Washing performance metrics differ from US Department of Energy procedures, forcing platform fragmentation and redundant certification costs.
- Extended replacement cycles:Direct-drive motor durability has lengthened average ownership to 12-14 years, compressing replacement demand in saturated ownership markets like Germany and Japan.
Strategic Opportunities
- Indonesia's underpenetrated secondary cities:Surabaya and Bandung exhibit sub-40% automatic washer penetration, creating first-mover positioning for compact-format distributors.
- Apartment-complex bulk procurement:Property-management platforms in Vietnam and Philippines are consolidating unit purchases through B2B channels that bypass traditional retail markup.
- AI-driven predictive maintenance:Sensor-enabled load-sensing technology is opening subscription-based service revenue streams separate from hardware margins.
Industry Challenges
- Embedded software certification:Cybersecurity validation for Wi-Fi-connected units is extending product launch timelines by 8-12 months in markets requiring IEC 62443 compliance.
- Cross-border service network gaps:Warranty fulfillment in fragmented Southeast Asian distribution requires partnerships with local repair cooperatives that lack standardized technician training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Washing Machine Market |
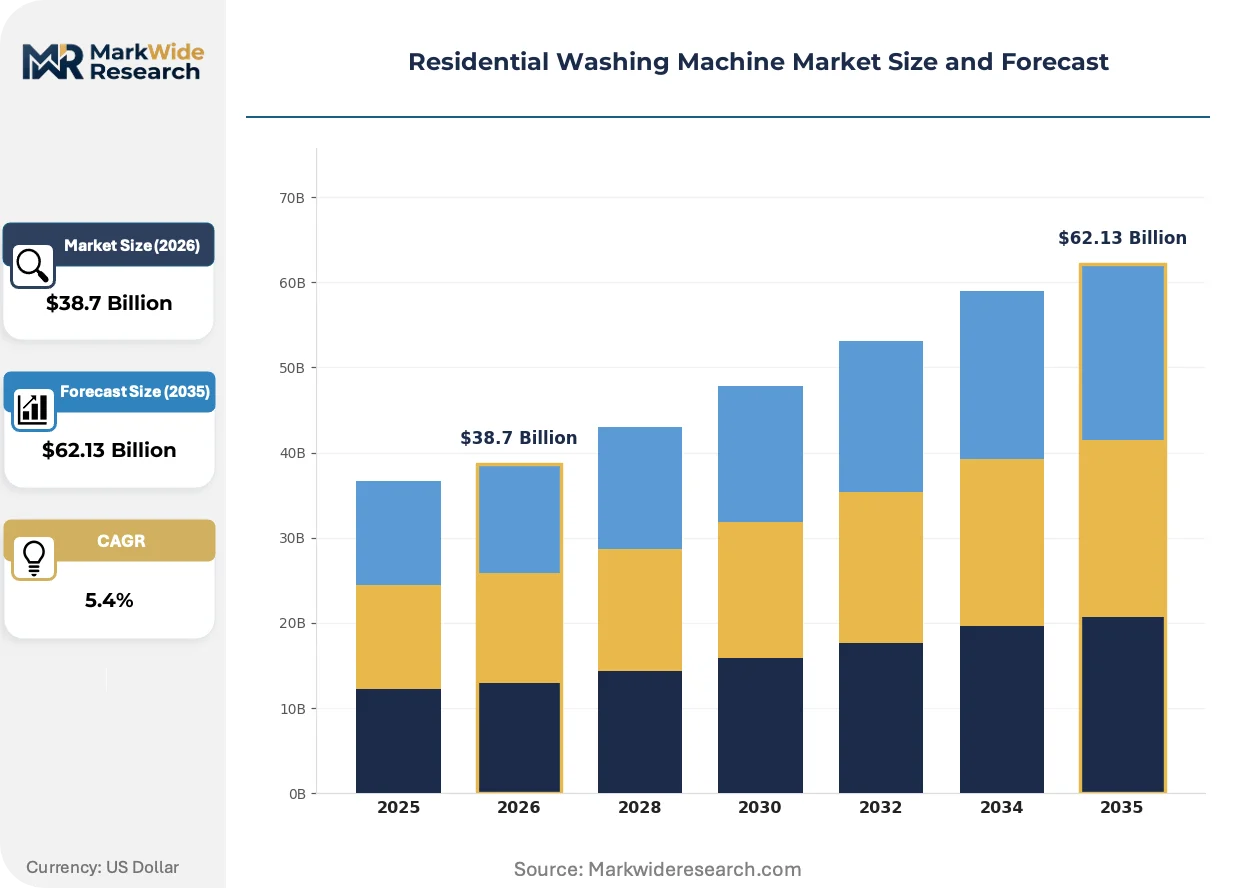
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Load, Top Load, Combo Washer-Dryer, Compact Washer Capacity: 6-8 kg, 8-10 kg, 10-12 kg, Above 12 kg Technology: Smart Technology, Energy Efficient, Conventional, Steam Cleaning Distribution Channel: Online Retail, Direct Sales, Appliance Stores, Hypermarkets |
| Companies Covered | Whirlpool Corporation, LG Electronics Inc., Samsung Electronics Co. Ltd., AB Electrolux, GE Appliances, BSH Hausgeräte GmbH, Panasonic Corporation, Haier Smart Home Co. Ltd., Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Washing Machine Market Strategic Shifts & Innovations
Hardware-software integration is redefining baseline product expectations as connectivity features migrate from premium SKUs to mid-tier price bands. Three developments are compressing competitive differentiation windows.
Heat-pump drying technology is consolidating its position in European markets where the EU Ecodesign Directive's 2025 efficiency thresholds will disqualify conventional vented and condenser designs from A-rated labeling. German and Dutch retailers are already delisting non-heat-pump combo units from their standard assortments. This compression is forcing Asian OEMs to license European compressor technology or absorb 18-month development cycles to achieve thermal efficiency parity.
China's MIIT dual-carbon efficiency grades are tightening market access requirements for motor designs that fail to meet Grade 1 or 2 thresholds. Domestic manufacturers in Qingdao and Hefei are redirecting R&D budgets from capacity expansion to inverter-control algorithm refinement. Export-oriented production lines now require separate component sourcing to satisfy divergent North American and European test protocols.
Urban developer procurement is consolidating around lifecycle cost metrics rather than upfront unit pricing. Build-to-rent operators in London, Berlin, and Sydney are specifying 15-year total cost of ownership models that include water, energy, and maintenance projections. This shift is compressing distributor margins and favoring manufacturers with captive service networks or third-party maintenance partnerships.
Residential Washing Machine Market Segmentation
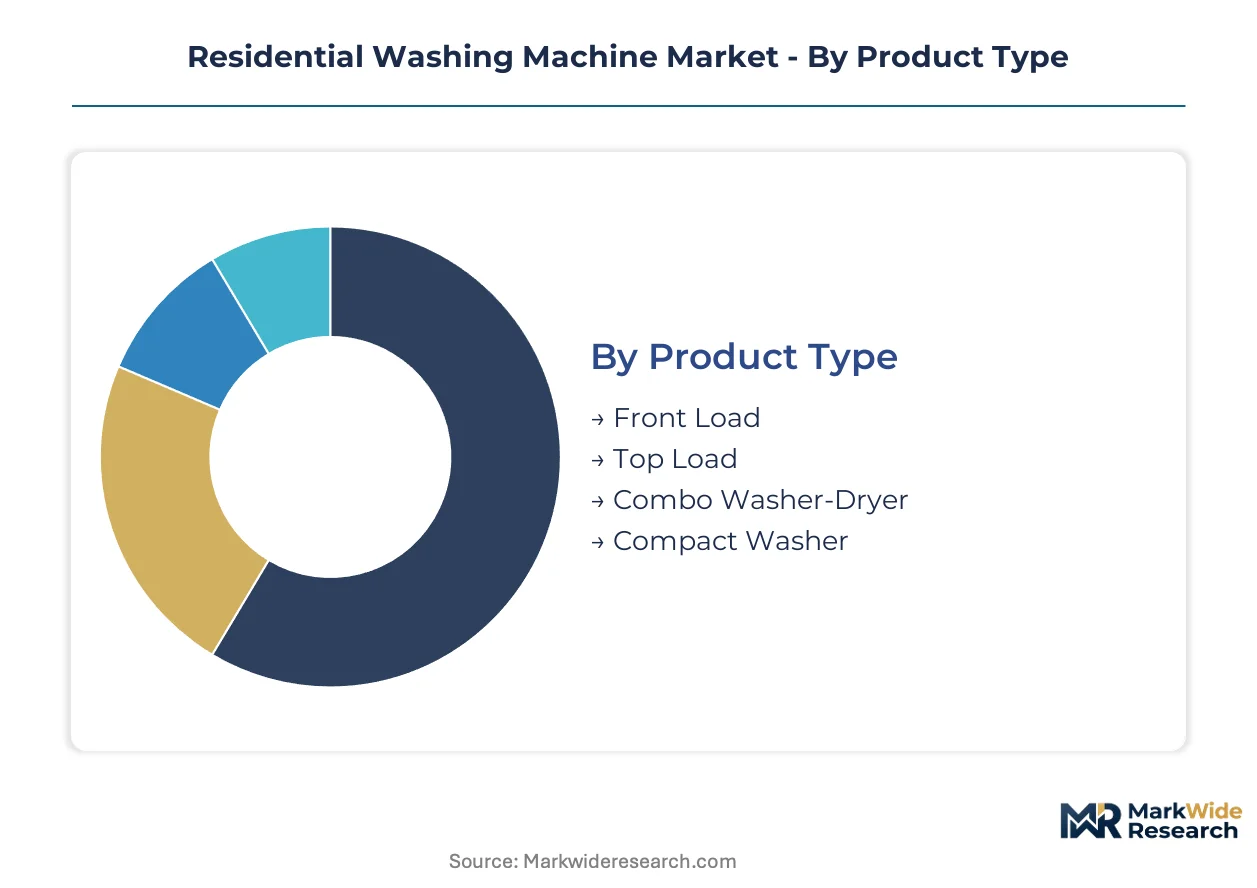
Segmentation in residential washing machines reveals how procurement criteria diverge between property developers and individual households. Understanding these splits exposes where margin pools concentrate and which technology investments align with buyer decision hierarchies.
Product Type:
Customization versus standardization tension peaks in load-configuration design, where water-efficiency mandates and space constraints pull specifications in opposing directions.
- Front Load:Horizontal-axis tumbling action reduces water consumption by 40-50% versus agitator designs. Mumbai and São Paulo apartment complexes now mandate front-load specifications under municipal conservation ordinances, locking out conventional alternatives from bulk procurement.
- Top Load:Vertical-axis agitator mechanism maintains faster cycle times and ergonomic loading height. Demand concentrates in US suburban single-family housing where water costs remain low and replacement cycles favor familiar mechanical formats.
- Combo Washer-Dryer:Integrated drying condenser suits Tokyo and Singapore micro-units below 35 square meters.
- Compact Washer:Sub-60cm width formats target European galley kitchens and Asian studio apartments.
Leading the category by volume: Top Load. Growing fastest: Compact Washer.
Capacity:
Volume concentration in mid-range drums reflects the dominance of 2-4 person households across urbanizing economies.
- 6-8 kg:Standard drum volume for European and Southeast Asian nuclear families. German and Dutch retailers stock this as the default replacement specification, with EU Ecodesign labeling favoring water-efficient smaller loads over oversized drums.
- 8-10 kg:Expanded capacity captures Indian and Brazilian multi-generational households where weekly washing consolidates into fewer cycles. India's BIS energy-labeling mandates push inverter-motor adoption in this bracket as developers specify Grade 1 efficiency for new-build installations.
- 10-12 kg:Large-family format with limited penetration outside Middle Eastern and North American markets.
- Above 12 kg:Commercial-scale drums occasionally specified for high-end residential compounds.
Dominant by installed base: 6-8 kg. Climbing the fastest: 8-10 kg.
Technology:
Margin stratification follows the regulatory compliance burden each technology tier carries across fragmented national efficiency regimes.
- Smart Technology:Wi-Fi connectivity and AI-driven load sensing enable predictive maintenance subscriptions. China's MIIT dual-carbon standards accelerate adoption as domestic OEMs integrate connectivity to differentiate inverter-motor platforms in Qingdao and Hefei production lines.
- Energy Efficient:Inverter-motor and heat-pump configurations qualify for federal rebate programs under US Department of Energy standards and EU A-rated labeling. Procurement officers in Berlin and Sydney build-to-rent operators specify 15-year total cost of ownership models favoring these designs.
- Conventional:Fixed-speed motor designs face disqualification from incentive programs in India and China.
- Steam Cleaning:High-temperature sanitization cycles target allergy-sensitive households in Japan and South Korea.
Highest-margin tier: Smart Technology. Steepest expansion trajectory: Energy Efficient.
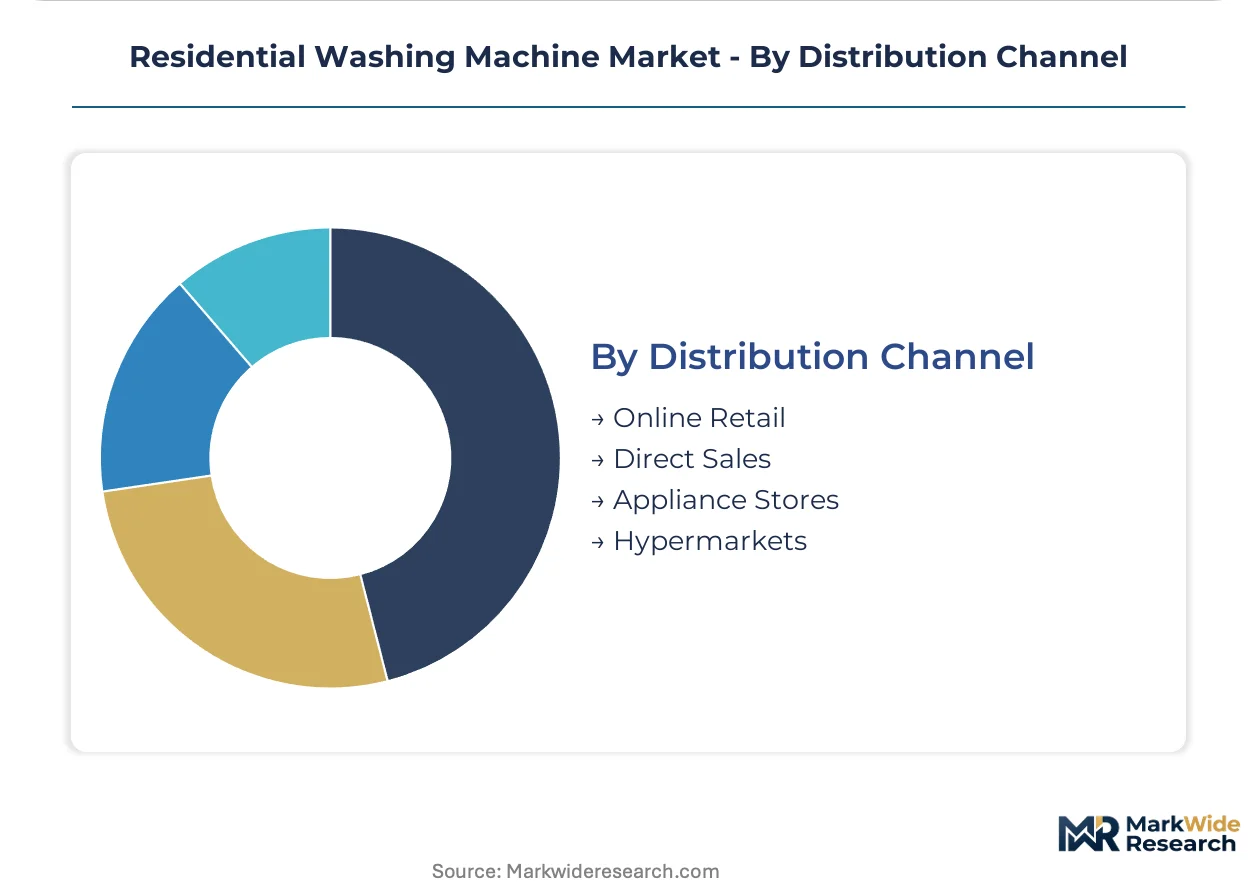
Distribution Channel:
Channel selection determines whether manufacturers capture property-management bulk procurement or individual replacement demand.
- Online Retail:Platform-driven comparison shopping concentrates in India's tier-2 cities and Southeast Asian metropolitan clusters where smartphone penetration outstrips appliance-store footprint. Vietnam and Philippines property-management platforms increasingly route bulk purchases through B2B digital channels.
- Direct Sales:Manufacturer-controlled fulfillment supports developer specifications requiring customized service contracts. LG and Samsung leverage this channel for London and Berlin build-to-rent operators demanding 15-year lifecycle cost projections.
- Appliance Stores:Physical demonstration remains critical for tactile purchase decisions in Japan and Germany.
- Hypermarkets:Mass-merchandise volume concentrates in US and Latin American suburban retail.
Largest volume channel: Appliance Stores. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban apartment complexes in Mumbai, São Paulo, and Jakarta are driving replacement demand as municipal water-scarcity ordinances disqualify conventional agitator designs from new-build specifications. Procurement officers in these metropolitan clusters now mandate inverter-motor front-load configurations exclusively.
United States
Suburban single-family housing sustains top-load agitator demand where water costs remain low and ergonomic loading height matters. The US Department of Energy enforces minimum efficiency standards that disqualify conventional models from federal rebate programs. Retail concentration in the Southeast and Midwest favors familiar mechanical formats with faster replacement cycles.
Germany
Build-to-rent operators in Berlin and Hamburg specify 15-year total cost of ownership models favoring heat-pump dryer integration. The EU Ecodesign Directive progressively tightens maximum allowable water and electricity consumption thresholds. German retailers are delisting non-heat-pump combo units from standard assortments ahead of 2025 efficiency deadlines.
China
MIIT dual-carbon efficiency grades restrict market access for non-inverter motor designs across Qingdao and Hefei production clusters. Domestic manufacturers redirect R&D budgets from capacity expansion to inverter-control algorithm refinement. Export-oriented production lines require separate component sourcing to satisfy divergent North American and European test protocols.
India
Mumbai and Delhi apartment complexes now specify BIS Grade 1 inverter-motor units exclusively, eliminating semi-automatic inventory from developer specifications. Multi-generational households in Bangalore and Hyderabad drive 8-10 kg capacity demand where weekly washing consolidates into fewer cycles. Tier-2 cities including Surabaya and Bandung exhibit sub-40% automatic washer penetration.
Brazil
São Paulo municipal conservation ordinances force household upgrades from top-load agitators to front-load platforms. Water-scarcity regulations tighten across southeastern metropolitan clusters where housing stock modernizes rapidly. Latin American suburban retail concentrates volume in mass-merchandise channels favoring familiar mechanical formats.
Residential Washing Machine Market Key Industry Players
South Korean and Chinese producers anchor the premium efficiency tier; European specialists hold position in heat-pump integration and lifecycle service contracting. The vendor base organizes around three strategic archetypes: scale-driven platform manufacturers, connectivity-focused ecosystem integrators, and compact-format regional specialists. Competitive moves concentrate on technology licensing partnerships and captive service network expansion to capture build-to-rent procurement.
Among the named fabricators, LG Electronics Inc. and Samsung Electronics Co. Ltd. occupy positions within the premium-tier vector, while Haier Smart Home Co. Ltd. anchors the scale-driven compact-format segment. These three exemplify how geographic origin and corporate structure map onto divergent strategic postures: the South Korean entities represent ecosystem integration archetypes, whereas the Qingdao-based limited company sits within manufacturing-scale specialization. Whirlpool Corporation and AB Electrolux serve as reference points for North American and European market presence respectively.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| LG Electronics Inc. |
| Samsung Electronics Co. Ltd. |
| AB Electrolux |
| GE Appliances |
| BSH Hausgeräte GmbH |
| Panasonic Corporation |
| Haier Smart Home Co. Ltd. |
| Hitachi Ltd. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap component suppliers in China's Shandong and Jiangsu provinces anchor inverter-motor production, concentrating neodymium magnet sourcing within a tight supplier network that disciplines pricing power across OEM tiers. This ownership pattern ties raw material access directly to volume commitment structures, compressing margin flexibility for manufacturers outside the core supply cluster.
Pricing Analysis
Volume concentrates in standard-tier inverter-motor front-load units while margin pools accrue to smart-connected heat-pump combos. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled predictive maintenance bundles from basic efficiency-compliant models. Pricing pressure stems from copper and rare-earth magnet cost volatility feeding into motor production. Property-management bulk buyers in Southeast Asian markets exhibit highest price sensitivity, while build-to-rent operators in European cities prioritize lifecycle cost metrics over upfront unit pricing.
Supply Chain Analysis
Reverse-logistics flows for inverter-motor refurbishment are gaining traction as extended replacement cycles in Germany and Japan create aftermarket service opportunities. Manufacturing concentrates in China, South Korea, and Vietnam, with neodymium processing anchored in Chinese facilities. Component sourcing draws from rare-earth magnet suppliers, copper winding producers, and semiconductor control module fabricators. Single-source vulnerability in neodymium supply exposes OEMs to input price shocks. Distribution runs through appliance retail chains, direct sales to property developers, and platform-driven online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around efficiency compliance capabilities, with India's BIS and China's MIIT mandates forcing conventional motor specialists toward exit or acquisition. Regulatory disqualification of non-inverter designs from incentive programs accelerates this pressure.
For Market Incumbents: Cement defensive positioning through captive service network expansion in build-to-rent corridors and backward integration into neodymium magnet sourcing. LG Electronics and Samsung Electronics leverage direct-sales channels to lock in 15-year lifecycle contracts with Berlin and Sydney operators. Threat of Asian OEM cost leadership in compact formats demands R&D acceleration in heat-pump dryer integration.
For New Entrants and Emerging Players: Launch via B2B digital platforms targeting Vietnam and Philippines property-management consolidation, bypassing traditional retail markup structures. Indonesia's Surabaya and Bandung present white-space opportunity with sub-40% automatic washer penetration. Compact washer-dryer combos for sub-35 square meter micro-units offer the most penetrable product entry point.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional compact-format specialists with established local repair cooperatives in Southeast Asian markets. Five-to-ten year viability hinges on heat-pump technology licensing capabilities or inverter-control algorithm IP. Signal to monitor: EU Ecodesign Directive 2025 delisting velocity for non-heat-pump units.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | European OEMs license compressor technology to Asian manufacturers seeking A-rated EU Ecodesign compliance. |
| Direct-to-Developer Sales Channel | Manufacturer-controlled fulfillment captures build-to-rent procurement specifying 15-year lifecycle cost models. |
| AI Predictive Maintenance Subscription | Sensor-enabled load sensing opens recurring revenue streams separate from hardware margins in connected units. |
| Neodymium Supply Partnership | Captive sourcing agreements with Chinese processing facilities hedge rare-earth magnet price volatility exposure. |
| Compact Format Manufacturing Scale-Up | Production expansion in Qingdao and Hefei clusters targets space-constrained Asian metropolitan housing stock. |
Research Approach
Document review covered customs trade records, MIIT efficiency grade filings, and EU Ecodesign regulatory databases, complemented by interviews with appliance OEM procurement directors, property-management platform operators, and inverter-motor component suppliers. Primary fieldwork engaged plant managers at Qingdao manufacturing clusters, category buyers at German retail chains, and technical R&D directors at South Korean ecosystem integrators. Secondary validation drew from BIS certification registries, Bureau of Indian Standards labeling data, and Southeast Asian housing development permits. Bottom-up unit shipment modeling triangulated against top-down efficiency mandate compliance projections.
Segmented outputs across product type, capacity tier, technology integration level, and distribution channel structure populated the analytical framework over the projection horizon. CAGRs derived from regression against regulatory deadline pacing and replacement cycle elasticity in saturated ownership markets. Forecast inputs incorporated municipal water-scarcity ordinance adoption curves and apartment-complex bulk procurement consolidation rates.
Neodymium supply disruption, regulatory test-protocol divergence between North American and European procedures, and extended replacement cycles from direct-drive motor durability are the dominant revision risks. Practitioners should monitor rare-earth export policy shifts, IEC 62443 cybersecurity certification timeline extensions, and build-to-rent operator procurement standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Brazil Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
UAE Home Appliances Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
North America Home Appliances Market
Home Appliances
India Laundry Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Household Appliance Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Household Induction Cooktops Market