
 Sweden Laundry Appliances Market | 2026-2036
Sweden Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Laundry Appliances Market Analytics
Aftermarket service revenue is fragmenting across independent repair networks and manufacturer-certified programs. Electrolux leverages its Nordic service infrastructure to control post-warranty maintenance contracts. Bosch competes through extended warranty bundling with premium washing machine sales. Miele anchors high-margin service pools in commercial laundry segments through predictive maintenance subscriptions.
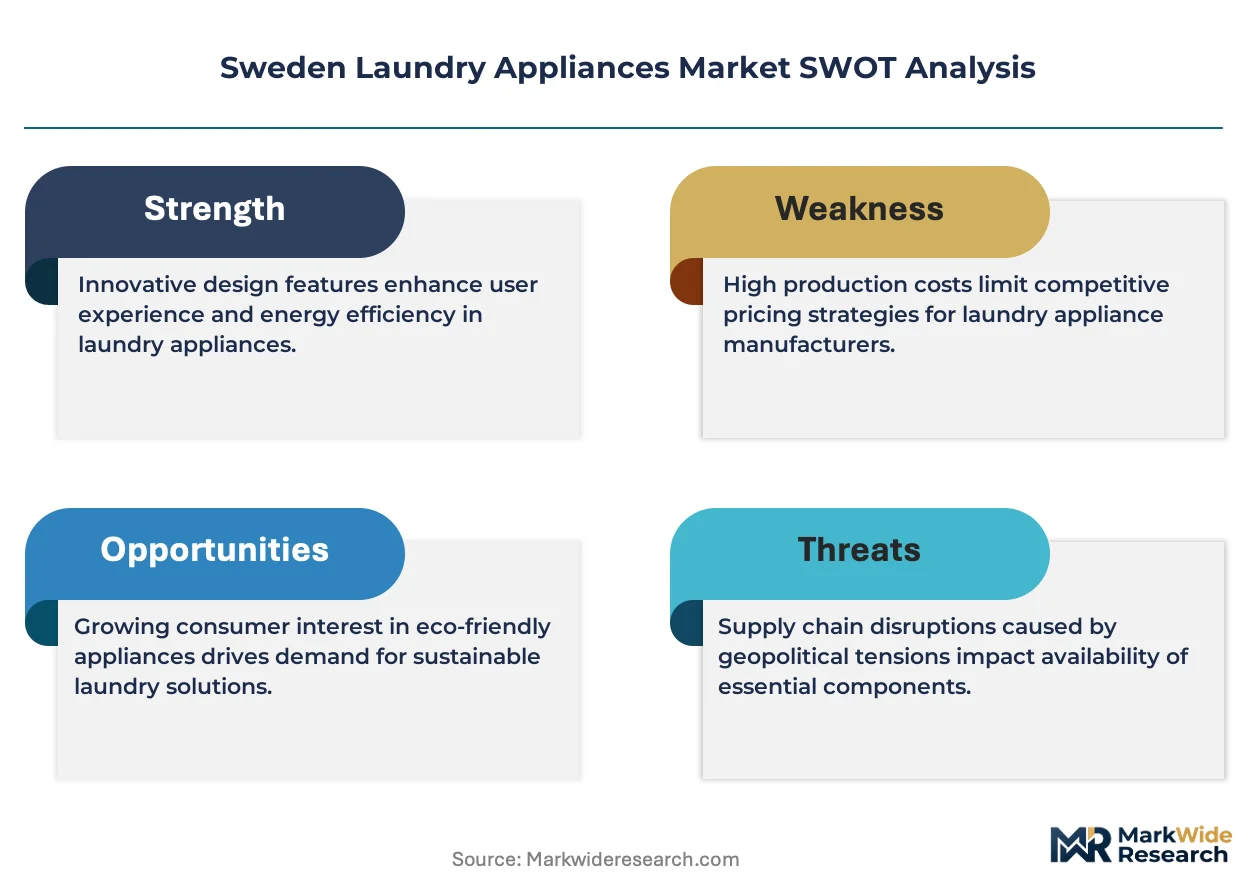
Sweden laundry appliances encompass electrically powered machines designed for textile cleaning and drying, typically operating at 220-240V with drum capacities ranging from 6 kg in compact residential units to 20 kg in industrial configurations, utilizing either vented condensation or heat-pump drying technology to remove moisture from fabrics. These appliances serve household, commercial hospitality, and industrial textile processing applications where automated laundering replaces manual washing to improve hygiene standards and labor efficiency. Washing machines lead product type value contribution due to higher replacement frequency and premiumization toward A+++ energy-rated front-load designs. Smart appliances represent the fastest-expanding technology segment as WiFi-enabled cycle optimization and load-sensing features penetrate mid-tier price bands. Energy-efficient models command durable margin pools driven by Sweden's progressive electricity tariffs and consumer preference for lifecycle cost reduction.
Swedish market access requires compliance with EU Ecodesign regulations governing water and energy consumption limits, alongside CE marking certification administered by the Swedish Energy Agency. The EU F-Gas Regulation restricts refrigerant types in heat-pump dryers, compelling manufacturers to redesign drying circuits with lower global warming potential alternatives. Boverket national building codes influence installation specifications for multi-unit residential developments, particularly mandating space-efficient washer-dryer combos in compact apartments. Stakeholders must monitor evolving EU right-to-repair legislation and its impact on spare parts availability requirements across the Nordic distribution network.
Market Dynamics
Sweden's progressive electricity tariffs and Boverket building codes are compressing replacement cycles while forcing manufacturers to redesign around heat-pump drying circuits and space-constrained washer-dryer combos for urban apartments.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-global-warming-potential refrigerants are accelerating heat-pump dryer redesigns, creating upgrade demand across Stockholm's rental housing stock.
- Urban housing renewal:Compact apartment construction in Gothenburg and Malmö mandates washer-dryer combo installations under Boverket space-efficiency codes.
- Lifecycle cost optimization:A+++ energy-rated front-load machines reduce operating expenditures for households facing Sweden's tiered electricity pricing structure.
Market Restraints
- Copper and rare-earth input volatility:Heat-pump compressor manufacturing depends on concentrated Chinese rare-earth processing, exposing margin structures to supply disruptions.
- Technical limitation in condensation efficiency:Heat-pump dryers require longer cycle times than vented alternatives, creating consumer resistance in time-sensitive segments.
- Regulatory friction from right-to-repair legislation:Pending EU spare parts availability mandates complicate inventory planning across Nordic distribution networks.
Strategic Opportunities
- Predictive maintenance subscriptions:WiFi-enabled load-sensing technology enables remote diagnostics, opening recurring revenue pools in commercial hospitality segments.
- Underpenetrated northern corridors:Norrland and Västerbotten counties show slower housing stock renewal, creating first-mover potential for energy-efficient retrofit programs.
- Channel innovation through independent repair networks:Post-warranty service fragmentation allows certified technician programs to capture aftermarket revenue from manufacturer-controlled pools.
Industry Challenges
- Heat-pump engineering talent scarcity:Refrigeration system design expertise concentrates among legacy appliance manufacturers, constraining new entrant R&D velocity.
- CE marking timeline compression:Evolving EU Ecodesign water consumption limits require accelerated certification cycles for product refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Laundry Appliances Market |
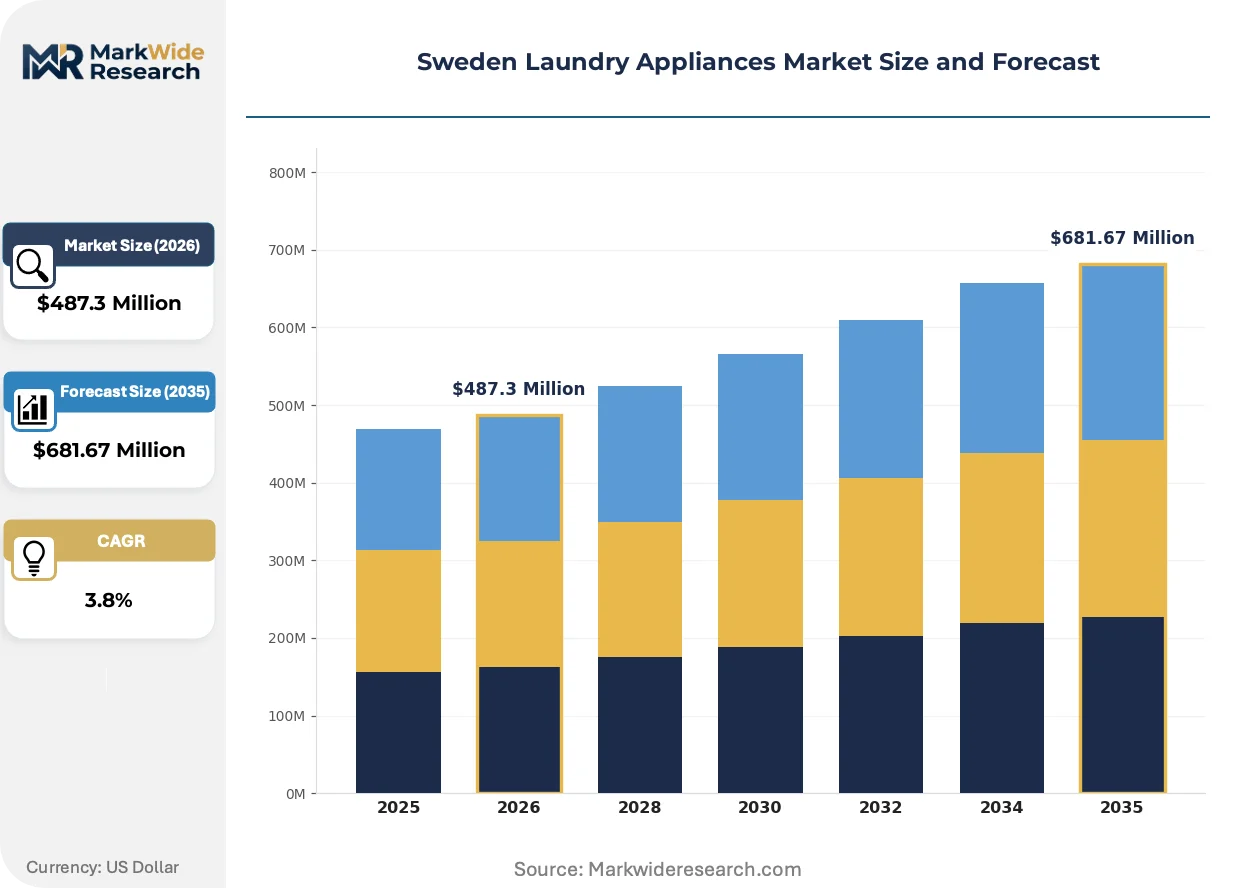
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Portable Washers End User: Residential, Commercial, Industrial, Hospitality Technology: Smart Appliances, Energy-Efficient, Conventional, Top-Load Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Siemens, Whirlpool, Electrolux, LG, Samsung, Bosch, Miele, AEG, Cylinda, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Laundry Appliances Market Evolving Landscape
Digitalization of cycle control and remote monitoring capabilities is redefining value capture models, shifting competition from hardware specifications to software-enabled service ecosystems.
Heat-pump drying technology is virtualizing moisture extraction processes through closed-loop refrigerant circuits that recycle thermal energy rather than venting heated air. Mid-tier Swedish households in dense urban districts are adopting these systems at accelerated rates due to Boverket restrictions on external venting in multi-unit buildings. This thermal virtualization is compressing the performance gap between standalone dryers and integrated washer-dryer units, enabling single-appliance solutions for space-constrained apartments.
Sweden's implementation of EU Ecodesign regulations through the Swedish Energy Agency certification framework is tightening water consumption limits for residential washing machines. Manufacturers must redesign drum and spray patterns to maintain cleaning performance under reduced fill volumes. Front-load A+++ rated machines face the steepest compliance requirements, driving R&D investment toward load-sensing algorithms that optimize water deployment per kilogram of textiles.
After-sales service unbundling is fragmenting traditional warranty bundling as independent repair networks gain technical competence in heat-pump diagnostics. Stockholm's metropolitan service market sees manufacturer-certified programs competing with regional technician cooperatives for post-warranty maintenance contracts. This disintermediation is most pronounced in commercial laundry segments where predictive maintenance subscriptions are displacing reactive break-fix arrangements.
Sweden Laundry Appliances Market Segmentation
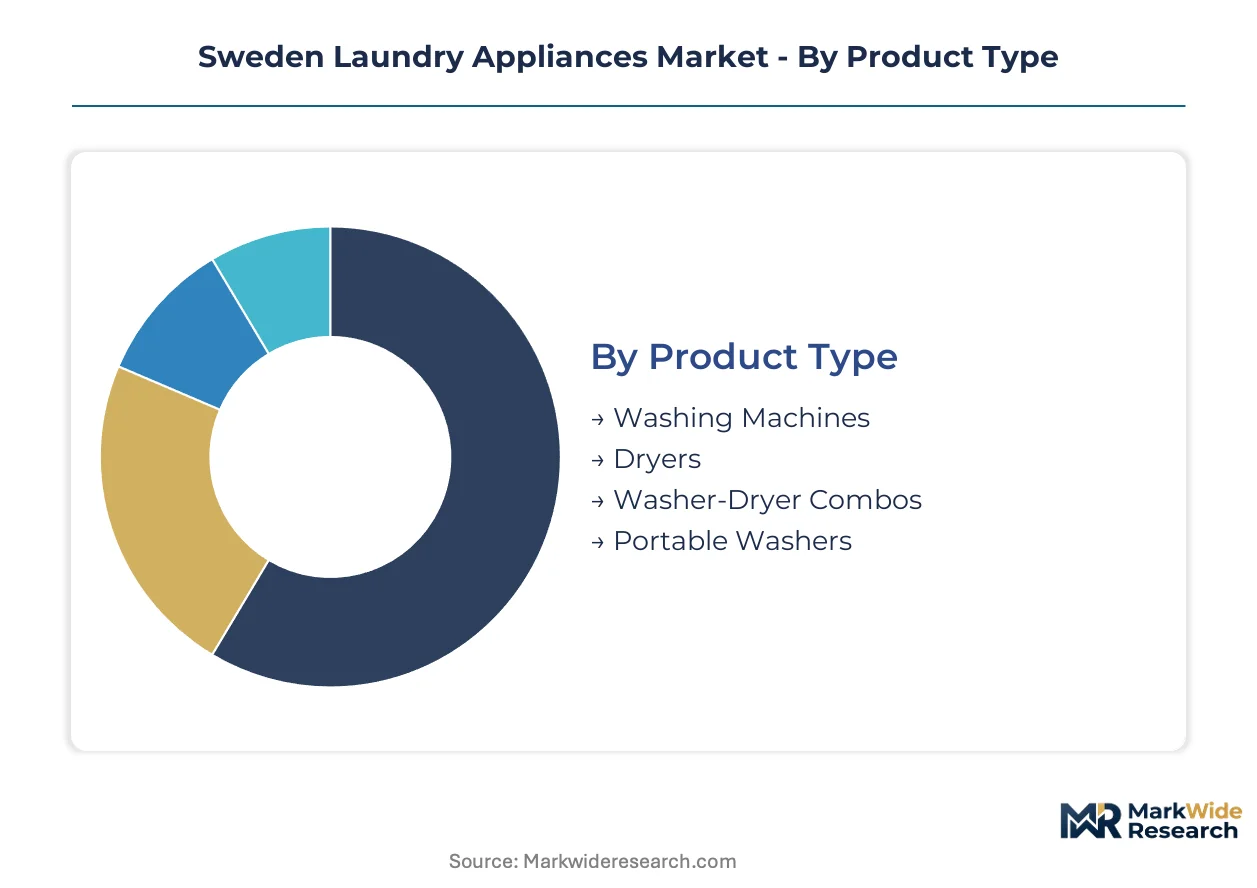
Segmentation in Sweden's laundry appliances market reflects divergent purchasing logics across housing types, energy cost exposures, and channel preferences. Manufacturers must configure product portfolios to capture replacement cycles in Stockholm's compact apartments while serving industrial-scale demand in textile processing clusters.
Product Type:
Cost tier differentiation separates premium heat-pump systems from entry-level vented alternatives, with mid-tier front-load washers commanding the volume base.
- Washing Machines:Front-load drum designs operating at 220-240V with capacities from 6 kg to 12 kg dominate residential replacement demand. A+++ energy-rated units concentrate in Stockholm and Gothenburg urban corridors where progressive electricity tariffs accelerate payback calculations for efficiency investments.
- Dryers:Heat-pump condensation systems recycle thermal energy through closed-loop refrigerant circuits, eliminating external venting requirements. Boverket building codes in multi-unit residential developments across Malmö and Uppsala mandate these installations where ductwork is impractical.
- Washer-Dryer Combos:Single-appliance solutions integrate washing and drying functions for space-constrained apartments under 50 square meters.
- Portable Washers:Compact 3-5 kg capacity units serve secondary residences and student housing in university towns.
Washing machines command the established base. The steepest expansion runs through washer-dryer combos.
End User:
Application context determines performance specifications, with commercial operators prioritizing cycle throughput over residential consumers focused on lifecycle operating costs.
- Residential:Household installations drive volume demand through replacement cycles averaging 10-12 years for washing machines. Stockholm County households lead penetration of WiFi-enabled smart appliances with load-sensing optimization features.
- Commercial:Laundromat and multi-family housing facilities require 15-20 kg capacity units with coin-operated or card-payment interfaces. Gothenburg's rental housing stock generates concentrated demand for durable mid-tier equipment.
- Industrial:Textile processing facilities utilize 50-200 kg batch washers with programmable chemical injection systems.
- Hospitospitality:Hotels and restaurants demand 20-30 kg capacity units with rapid cycle times and linen-tracking integration.
Residential installations anchor volume. Commercial hospitality applications are climbing the fastest.
Technology:
Customer type stratification separates early smart-home adopters from price-sensitive replacement buyers, with regulatory pressure compressing conventional technology's addressable market.
- Smart Appliances:WiFi-enabled machines with remote cycle control and predictive maintenance diagnostics penetrate mid-tier price bands. Stockholm metropolitan households adopt these systems at rates exceeding national averages due to dense urban housing and technology affinity.
- Energy-Efficient:A+++ rated front-load washers and heat-pump dryers reduce water and electricity consumption below EU Ecodesign thresholds. Swedish Energy Agency certification requirements tighten annually, forcing continuous redesign of drum spray patterns and thermal recovery systems.
- Conventional:Vented dryers and top-load washers without connectivity features serve price-sensitive segments and rural markets.
- Top-Load:Vertical-axis drum designs persist in compact installations where front-load door swing is impractical.
Energy-efficient models anchor the installed base. Smart appliances are gaining share fastest.
Distribution Channel:
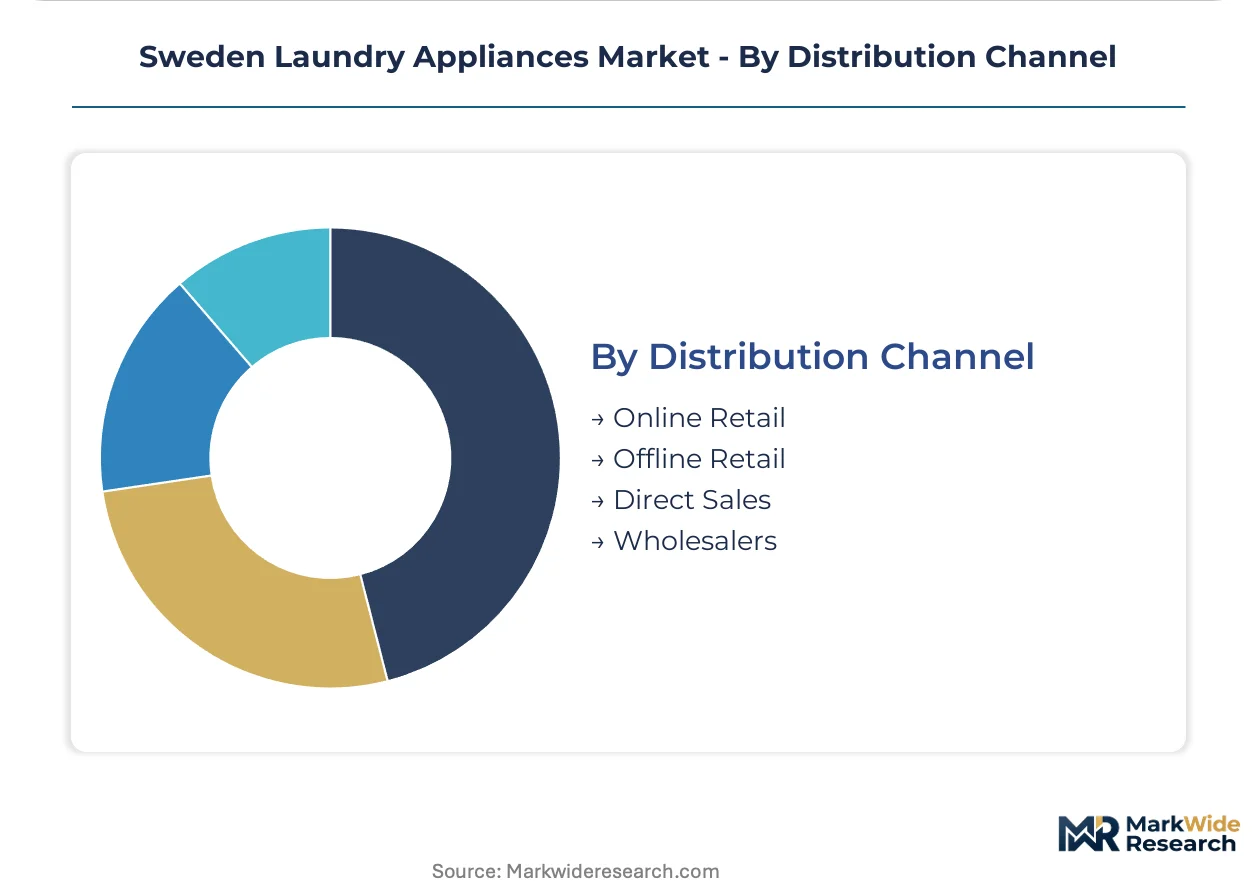
Geography and margin structure fragment procurement patterns, with urban consumers shifting toward digital channels while commercial buyers retain direct relationships.
- Online Retail:E-commerce platforms capture consumer research and comparison shopping for replacement purchases. Stockholm and Malmö metropolitan areas show highest online penetration for standard-capacity residential machines.
- Offline Retail:Physical appliance stores provide installation coordination and immediate availability for urgent replacements. Gothenburg's retail corridor maintains concentration of Electrolux and Bosch brand stores.
- Direct Sales:Manufacturer field teams serve commercial hospitality and industrial accounts with customized fleet proposals.
- Wholesalers:Regional distributors stock inventory for contractor channel serving new residential construction and renovation projects.
Offline retail commands the established base. Online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in Sweden's laundry appliances market varies sharply by geography. Urban households in Stockholm and Gothenburg absorb premium pricing for A+++ rated machines, while northern counties prioritize lifecycle cost reduction over upfront investment.
Stockholm County
Replacement demand concentrates in dense urban districts where Boverket building codes mandate space-efficient installations. The Swedish Energy Agency enforces stringent EU Ecodesign water consumption limits on all new machine registrations. Södermalm and Kungsholmen districts drive heat-pump dryer penetration in multi-unit housing.
Västra Götaland
Gothenburg's rental housing stock generates durable mid-tier equipment demand through property management procurement cycles. CE marking certification administered by the Swedish Energy Agency filters non-compliant imports from Nordic distribution channels. Mölndal and Partille industrial zones anchor commercial laundry service provider clusters.
Skåne
Malmö's compact apartment construction accelerates washer-dryer combo installations under Boverket space-efficiency mandates. EU F-Gas Regulation restrictions on high-global-warming-potential refrigerants compel heat-pump circuit redesigns. Lund university town sustains portable washer demand for student housing subsegments.
Norrland
Norrbotten and Västerbotten counties exhibit slower housing stock renewal, creating retrofit program opportunities for energy-efficient upgrades. The Swedish Energy Agency's progressive electricity tariff structures incentivize A+++ rated front-load replacements. Luleå and Umeå metropolitan areas concentrate limited commercial hospitality demand.
Sweden Laundry Appliances Market Competitive Landscape
European heritage manufacturers and Asian electronics conglomerates split the Swedish laundry appliances market through divergent channel strategies. Consolidation around established Nordic service infrastructures favors incumbents with post-warranty maintenance networks. Two strategic archetypes dominate: integrated appliance manufacturers with captive distribution, and scale-driven electronics specialists leveraging component cost advantages. Competitive moves center on extended warranty bundling and predictive maintenance subscription rollouts.
Among European integrated manufacturers, Electrolux and Bosch exemplify the heritage archetype with deep Nordic market presence. Miele occupies a premium-tier position within the same grouping. Samsung and LG represent the Asian electronics specialist archetype, competing through smart appliance connectivity features and aggressive mid-tier pricing. These five companies anchor the competitive structure, with regional specialists like Cylinda and AEG filling niche segments.
| Leading Market Players |
|---|
| Siemens |
| Whirlpool |
| Electrolux |
| LG |
| Samsung |
| Bosch |
| Miele |
| AEG |
| Cylinda |
| Others |
Value Network & Pricing Analysis
Copper and rare-earth input volatility originating from concentrated Chinese processing facilities compresses margin structures while simultaneously widening spreads between premium heat-pump systems and entry-level vented alternatives. This commodity exposure forces manufacturers to absorb cost spikes in mid-tier segments or pass through to price-sensitive rural buyers, reshaping procurement strategies toward long-term offtake contracts for compressor components.
Pricing Analysis
Aftermarket service revenue pools including predictive maintenance subscriptions and extended warranty contracts now drive lifetime value capture for manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates Miele's commercial hospitality bundles from Bosch's mid-tier extended warranties and entry-level vented dryer alternatives. Pricing pressure stems from Asian electronics specialists compressing mid-tier smart appliance margins through aggressive connectivity-feature bundling. Commercial laundromat operators exhibit highest price sensitivity due to fleet procurement volumes, while Stockholm residential buyers prioritize lifecycle operating cost reduction over upfront expenditure.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates strategic planning for heat-pump compressor sourcing. Manufacturing concentration in China, South Korea, and Germany supplies rare-earth magnets, refrigeration circuits, and precision-machined drums respectively. Component dependencies span copper windings, neodymium magnets, and electronic control modules. Single-source vulnerability in Chinese rare-earth processing constrains alternative sourcing for heat-pump dryer redesigns mandated by EU F-Gas Regulation. Distribution runs through manufacturer-certified service networks competing with independent technician cooperatives for post-warranty maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shared laundry services and on-demand garment cleaning apps threaten replacement demand frequency, forcing incumbents to embed their hardware into subscription ecosystems that capture consumer spend regardless of ownership models.
For Market Incumbents: Build captive service infrastructure moats through predictive maintenance platform rollouts and certified technician network exclusivity. Electrolux's Nordic service density provides a template for controlling post-warranty revenue pools against independent repair network fragmentation. Secure backward integration into heat-pump compressor supply through long-term offtake agreements with German and South Korean component specialists, insulating margin structures from Chinese rare-earth volatility. Prioritize R&D investment in load-sensing algorithms that reduce water consumption below tightening Swedish Energy Agency thresholds. For New Entrants and Emerging Players: Build out white-space positions in Norrland and Västerbotten counties where housing stock renewal lags southern metropolitan corridors. Target commercial hospitality segments in Luleå and Umeå with rapid-cycle industrial equipment featuring linen-tracking integration, displacing reactive break-fix arrangements with subscription diagnostics. Establish go-to-market partnerships with regional contractor networks serving Boverket-mandated new construction projects, bypassing incumbent-controlled retail channels. For Investors and Strategic Acquirers: Independent repair network consolidators with heat-pump diagnostic capabilities represent the most defensible acquisition archetype as manufacturer warranty bundling fragments. Long-term viability hinges on positioning for EU right-to-repair legislation implementation and spare parts availability mandates across Nordic distribution. Monitor Swedish Energy Agency certification timeline compression as the critical inflection signal—accelerated Ecodesign water consumption limits will strand inventory and favor agile redesign capabilities over scale economies.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | WiFi-enabled diagnostics transform Electrolux and Bosch from hardware vendors into recurring revenue service providers. |
| Heat-Pump Supply Agreement | Long-term compressor offtake contracts with German refrigeration specialists reduce exposure to Chinese rare-earth processing concentration. |
| Certified Technician Network Expansion | Post-warranty service fragmentation allows regional cooperatives to capture aftermarket revenue from manufacturer-controlled pools. |
| Washer-Dryer Combo Portfolio Refresh | Boverket space-efficiency mandates in Malmö and Stockholm compact apartments accelerate single-appliance solution adoption. |
| Commercial Hospitality Fleet Partnership | Hotels in Gothenburg and Lund demand 20-30 kg capacity units with rapid cycle times and predictive maintenance integration. |
Research Methodology
Cross-validation between appliance manufacturer product planning executives and Swedish Energy Agency certification specialists anchors the qualitative findings on regulatory trajectory and redesign cycle timing. Primary interviews with commercial laundry facility operators, property management procurement directors, and independent service technician cooperatives were synthesized with secondary validation from EU Ecodesign directive filings, Swedish customs import records, and Boverket building code amendments. Bottom-up unit shipment estimates by county were reconciled with top-down market value assessments across the projection horizon.
Calibration against historical replacement cycle data and housing stock renewal rates informed the analytical framework. Segmentation dimensions modeled include product type, end-user application, technology tier, and distribution channel, with additional stratification by metropolitan density and electricity tariff exposure. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and technology substitution elasticities. Heat-pump adoption curves and smart appliance connectivity penetration served as industry-specific forecast inputs.
Stress conditions across rare-earth price volatility, CE marking timeline compression, and right-to-repair legislative implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on Boverket code enforcement consistency and EU F-Gas Regulation refrigerant phase-out schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Italy Home Appliances Market
Home Appliances
UAE Major Home Appliances Market